Key insights
6 slides
Market Leadership
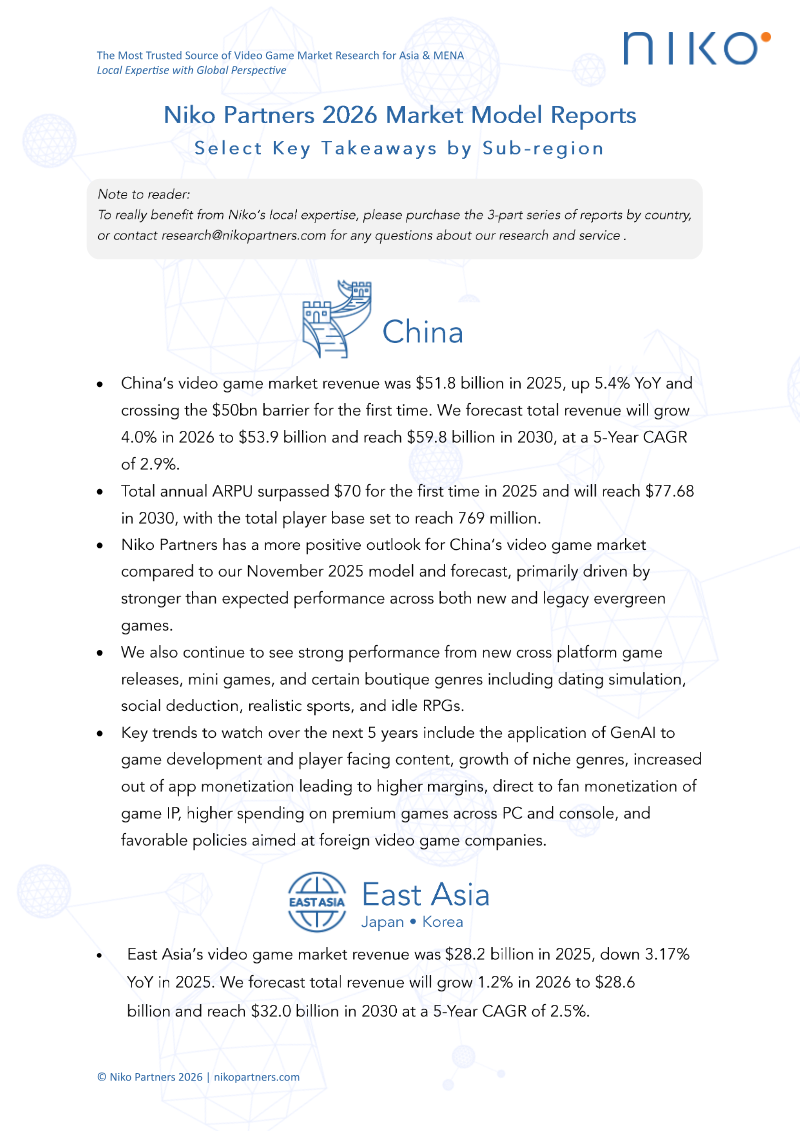
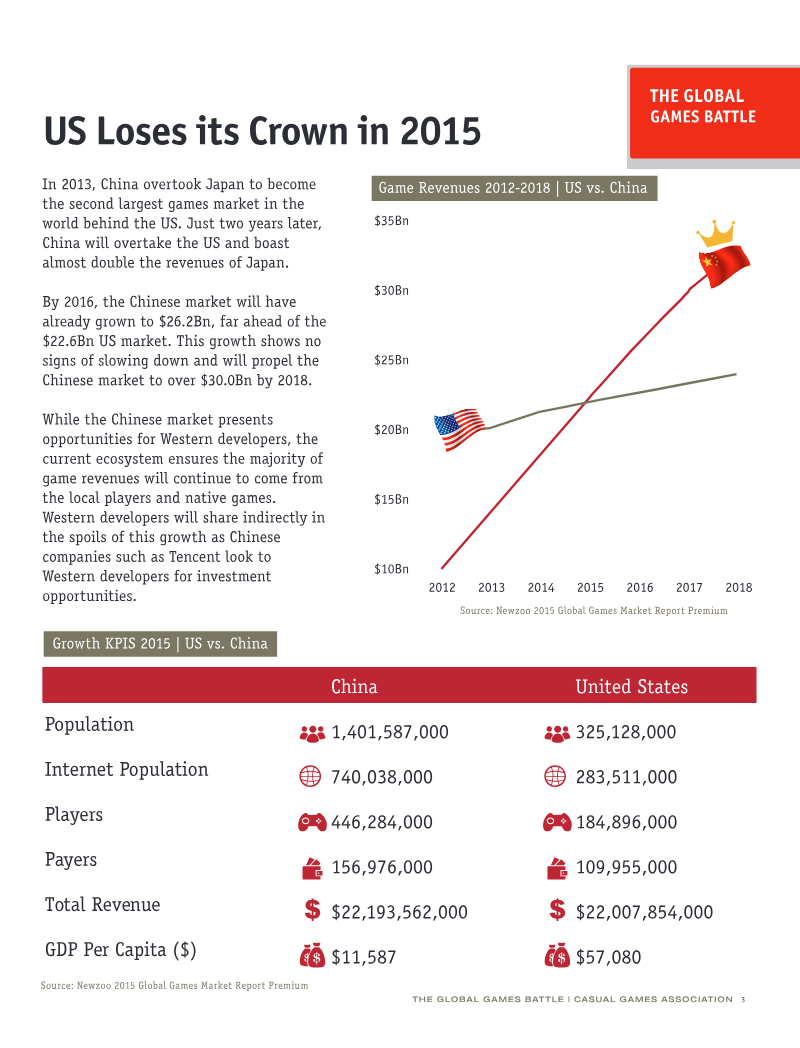
China became the world's largest games market in 2015.
China surpassed the United States in 2015 to become the world's largest games market. Both nations are projected to account for 50% of global revenue by 2018.
China's Growth
China's games market reached $22.2 billion in 2015.
Growth was driven by a 50% growth rate in the smartphone gaming segment.
Page 5 of the report$22.2 billion
China's games market revenue in 2015.
- year-on-year increase
- 23%
- smartphone gaming growth
- 50%
US Market Overview
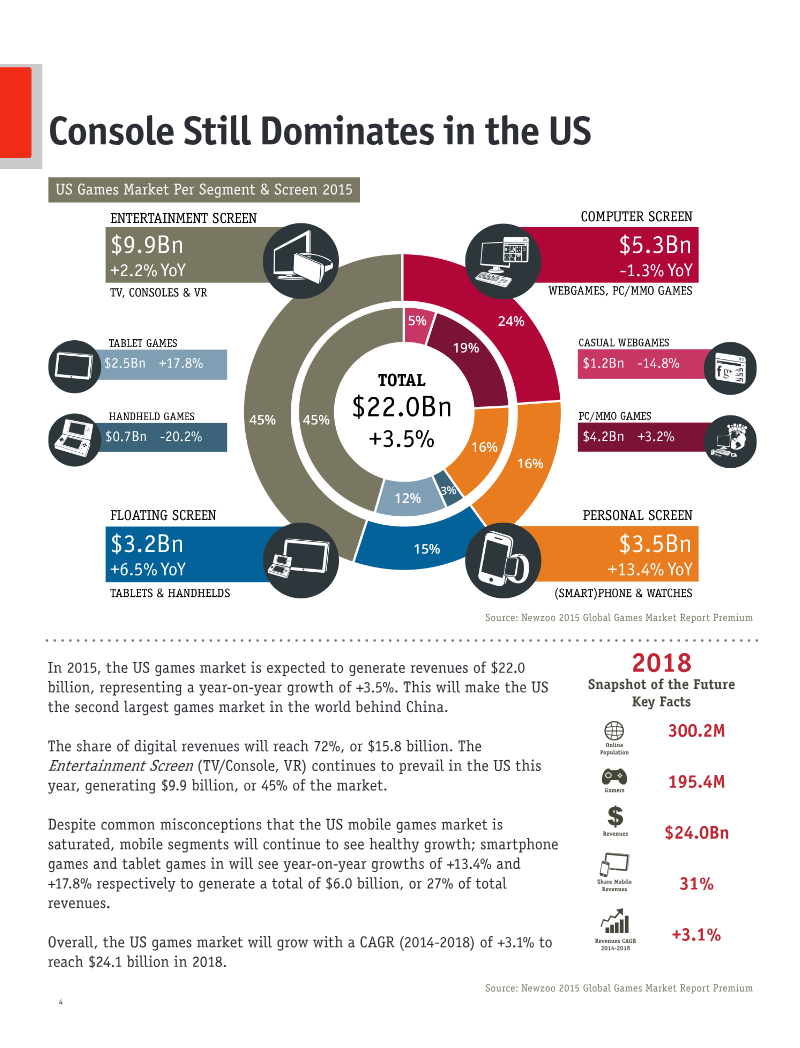
The US market generated $22.0 billion in 2015.
45% of the total revenue in the US market was derived from TV, console, and VR platforms. The US market maintains a strong console presence.
Spending Habits
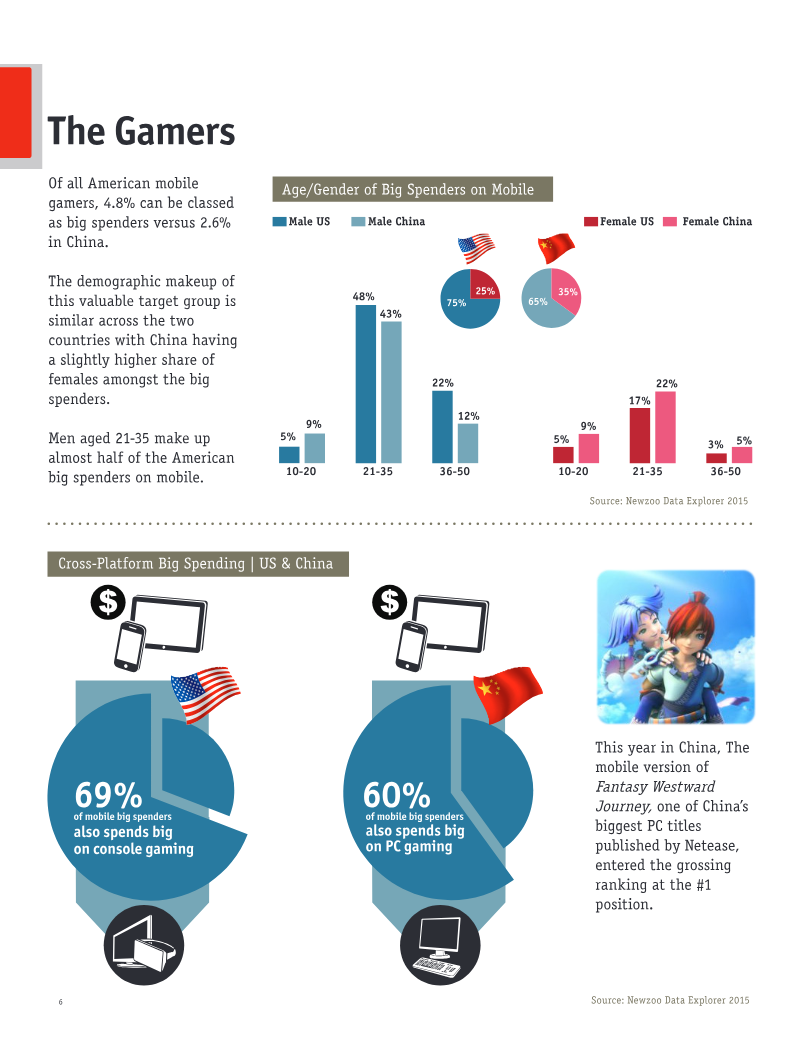
US mobile gamers show a higher propensity for high-value spending.
The rate for US mobile gamers is 4.8%. This is nearly double the 2.6% rate observed among Chinese mobile gamers.
Genre Popularity
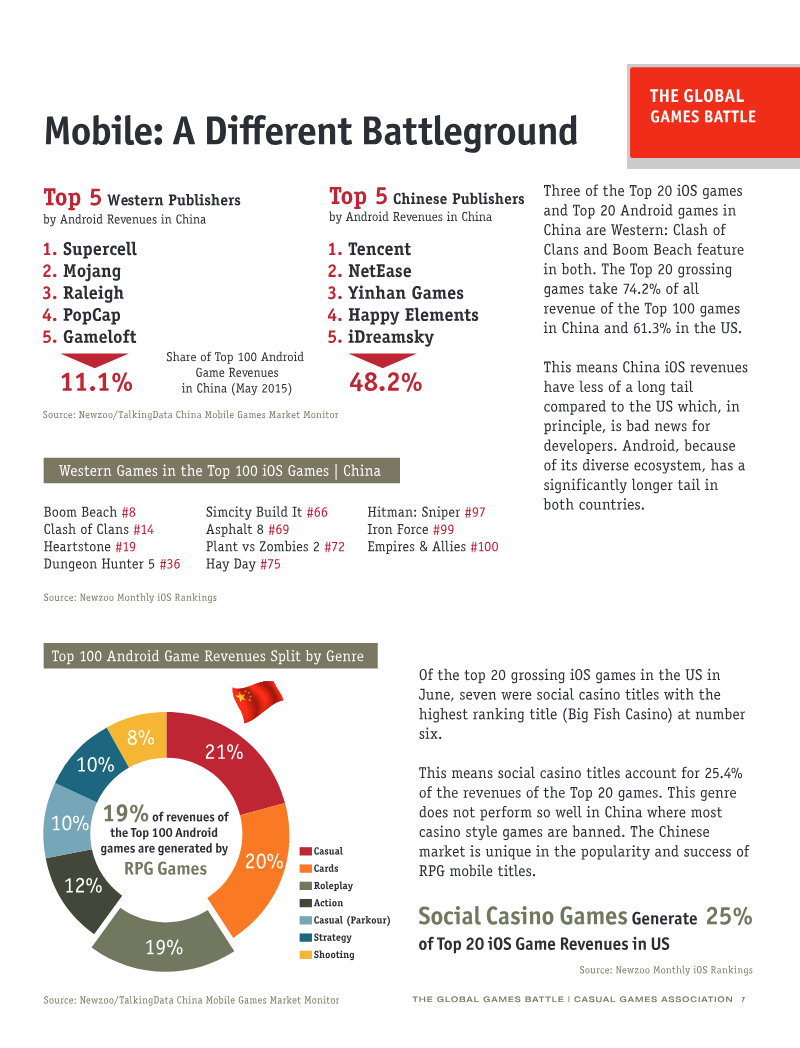
Genre preferences are sharply divided between the US and China.
Social casino games account for 25.4% of top-grossing iOS revenue in the US. RPGs dominate the Chinese market.
Market Access
Western developers face significant barriers to entering the Chinese market.
These barriers are due to local publisher dominance. Strategic partnerships or cross-platform adaptations are necessary for success.
Entering the Chinese market is like navigating a maze with many established players already inside.
1 / 6
Ask AI about this report