Koei Tecmo
Game Co.173 documents
Japanese developer/publisher. Dynasty Warriors, Nioh, Dead or Alive, Atelier, Romance of the Three Kingdoms.
Documents
Report1 pages
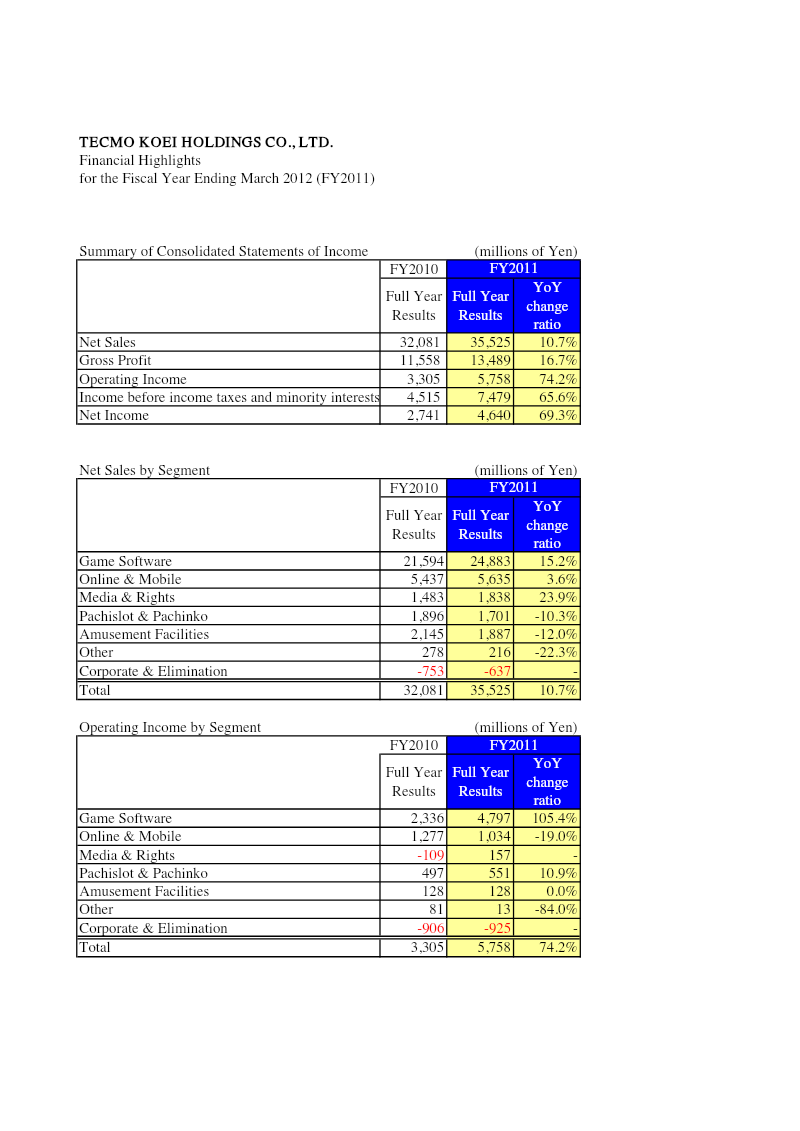
Financial Highlights: FY2011
Financial highlights for the fiscal year ending March 2012 demonstrate robust growth across Tecmo Koei Holdings’ core segments. Net sales increased 10.7 % from ¥32,081 million in FY2010 to ¥35,525 million in FY2011, driven primarily by a 15.2 % rise in Game Software sales to ¥24,883 million and a 23.9 % increase in Media & Rights revenue to ¥1,838 million. Online & Mobile sales grew modestly by 3.6 %, while Pachislot & Pachinko, Amusement Facilities and Other segments experienced declines of 10.3 %, 12.0 % and 22.3 % respectively, partially offset by a slight improvement in Media & Rights.
Operating income surged 74.2 % to ¥5,758 million, largely due to a 105.4 % jump in Game Software operating profit (¥4,797 million) and a 10.9 % rise in Pachislot & Pachinko operating profit (¥551 million). Online & Mobile operating income fell 19.0 % to ¥1,034 million, and Other segment profit contracted sharply by 84.0 % to ¥13 million. Gross profit rose 16.7 % to ¥13,489 million, and net income climbed 69.3 % to ¥4,640 million, reflecting improved profitability across the business.
The data cover all domestic and international operations of Tecmo Koei Holdings, covering the period from FY2010 to FY2011. Figures are presented in millions of Japanese yen and reflect consolidated financial statements, with corporate eliminations accounted for in the totals. The analysis indicates that strategic focus on Game Software and Media & Rights has yielded significant revenue and profit gains, while traditional gaming and amusement segments face contraction.
- Tecmo Koei Holdings achieved a 74.2% surge in operating income to ¥5,758 million and a 69.3% increase in net income to ¥4,640 million for the fiscal year ending March 2012.
- Net sales grew 10.7% to ¥35,525 million, driven primarily by a 15.2% increase in Game Software sales to ¥24,883 million.
- Game Software operating profit more than doubled, jumping 105.4% to ¥4,797 million, which served as the primary catalyst for the company's overall profit growth.
- Media & Rights revenue saw a significant 23.9% increase to ¥1,838 million, while Online & Mobile sales experienced more modest growth of 3.6%.
- Operating income for the Online & Mobile segment declined by 19.0% to ¥1,034 million.
Koei Tecmo
Report27 pages
Management Policy & Strategy: Fiscal Year Ended March 2013
The document outlines Tecmo Koei Holdings’ fiscal strategy and performance for the year ending March 2013, emphasizing a record‑high profit trajectory. Sales reached ¥34.6 billion in FY2012, up 2.5 % from the previous year, while operating profit climbed ¥6.21 billion (17.9 % of sales) and ordinary profit rose to ¥8.84 billion (25.5 % of sales). Net income improved from 13.1 % to 16.3 %, reflecting a 21.9 % increase in profit margin. The company attributes gains to strong game software sales, particularly titles such as “One Piece: Dynasty Warriors 8” and “Fist of the North Star,” and to a 900‑million‑user social game base. Segment analysis shows Game software as the largest contributor, with Online & Mobile and Media & Rights businesses identified for future rebuilding.
Geographically, Japan remains the dominant market (≈84 % of sales), followed by overseas segments: North America, Europe, and Asia contribute 7.5 %, 4.8 %, and 4.2 % respectively, with overseas sales growing modestly at 1.6 %. The company projects FY2013 sales of ¥37 billion, operating profit of ¥7.0 billion (18.9 % margin), and ordinary profit of ¥9.0 billion (24.3 %). Planned capital expenditures are ¥1.5 billion, with depreciation expenses expected to improve by 0.4 points.
Strategically, the firm focuses on IP creation and multi‑platform expansion, targeting new titles, collaborative projects, and ancillary media such as animation, comics, and merchandise. Online & Mobile initiatives aim to strengthen social games, expand browser titles in Asia, and pursue women‑oriented IPs. Overall, the plan seeks to sustain growth while enhancing profitability through diversified revenue streams and cost efficiencies.
- Tecmo Koei achieved record-high profitability in FY2012, with operating profit reaching ¥6.21 billion (17.9% of sales) and net income margin increasing to 16.3%.
- Total sales grew 2.5% year-over-year to ¥34.6 billion, driven primarily by strong performance in game software titles like 'One Piece: Dynasty Warriors 8' and 'Fist of the North Star.'
- The company maintains a heavy reliance on the domestic market, with Japan accounting for approximately 84% of total sales, while overseas segments (North America, Europe, and Asia) grew by only 1.6%.
- Management projects continued growth for FY2013, targeting ¥37 billion in sales and an operating profit of ¥7.0 billion.
- The firm is prioritizing a strategy of IP diversification, leveraging ancillary media such as animation and comics alongside a social game user base of 900 million.
Koei Tecmo
Report1 pages
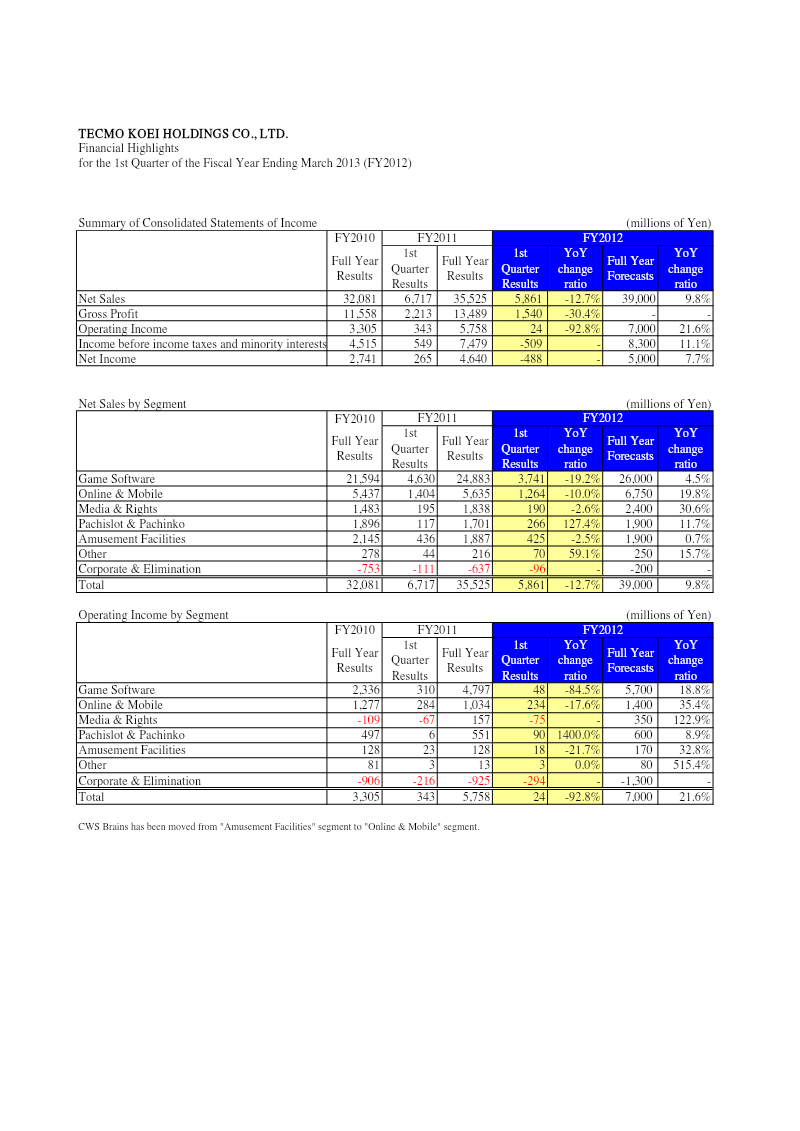
Financial Highlights: 1st Quarter of Fiscal Year Ending March 2013
Financial highlights for the first quarter of fiscal year ending March 2013 reveal a mixed performance across Tecmo Koei Holdings’ operating segments. Net sales fell 12.7 % year‑over‑year to ¥35,525 million, driven primarily by declines in Game Software (−19.2 %) and Online & Mobile (−10.0 %). Media & Rights sales were essentially flat, while Pachislot & Pachinko and Other segments posted modest gains of 127.4 % and 59.1 %, respectively. The company’s operating income contracted sharply, dropping 92.8 % to ¥5,758 million; this was largely due to a steep decline in Game Software operating income (−84.5 %) and a 17.6 % drop in Online & Mobile operating income. Conversely, Pachislot & Pachinko operating income surged 1,400 % to ¥551 million, and Media & Rights turned a loss into a profit of ¥157 million. Net income decreased 48.8 % to ¥4,640 million, reflecting the overall revenue and operating income downturns. Forecasts for the full year project net sales of ¥39,000 million (up 9.8 %) and operating income of ¥7,000 million (up 21.6 %). The report covers Japan‑based operations for the first quarter of FY2012, with data presented in millions of yen. Methodological details are not disclosed beyond segment classification changes, notably the transfer of CWS Brains from Amusement Facilities to Online & Mobile.
- Tecmo Koei Holdings experienced a significant financial downturn in Q1 FY2013, with net sales falling 12.7% year-over-year to ¥35,525 million and operating income plummeting 92.8% to ¥5,758 million.
- The core Game Software segment, the company's primary revenue driver, saw a 19.2% decline in sales and an 84.5% collapse in operating income.
- Online & Mobile operations underperformed, recording a 10.0% drop in sales and a 17.6% decrease in operating income.
- Pachislot & Pachinko operations provided a major bright spot, with sales increasing 127.4% and operating income surging 1,400% to ¥551 million.
- Net income for the quarter fell 48.8% to ¥4,640 million, reflecting the broader contraction across the company's primary business segments.
+1
Koei Tecmo
Report2 pages
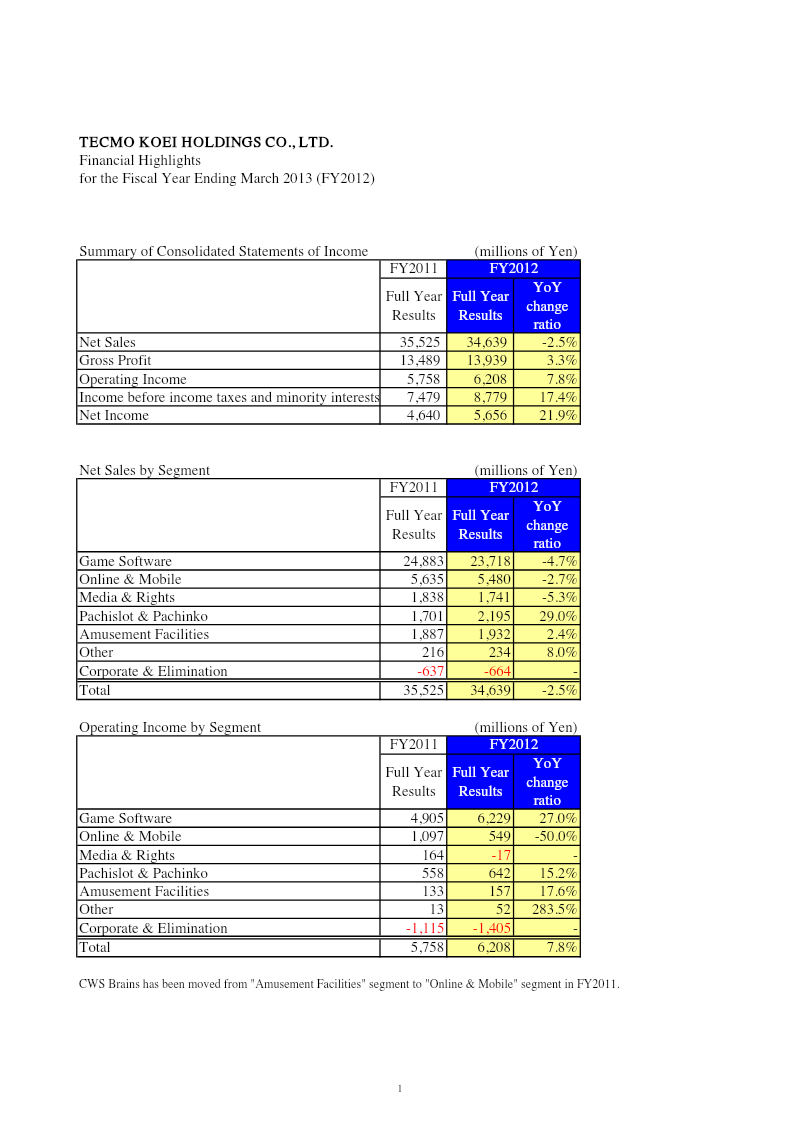
Financial Highlights: FY2012
Financial highlights for the fiscal year ending March 2013 (FY2012) show a modest decline in net sales of 2.5 % to ¥34,639 million, driven mainly by a 4.7 % drop in Game Software sales and a 2.7 % fall in Online & Mobile revenue. Gross profit, however, increased by 3.3 % to ¥13,939 million, reflecting higher operating income of 7.8 % (¥6,208 million) and a 17.4 % rise in income before taxes to ¥8,779 million. Net income grew 21.9 % to ¥5,656 million, supported by a 27 % jump in Game Software operating income and a 15.2 % increase from Pachislot & Pachinko, offset by a 50 % decline in Online & Mobile operating income.
Segment performance varied: Pachislot & Pachinko sales rose 29 % to ¥2,195 million; Amusement Facilities grew 2.4 %; Other segments saw an 8 % rise, while Media & Rights fell 5.3 %. The company’s balance sheet expanded, with total assets rising from ¥54,909 million to ¥63,594 million, largely due to a jump in cash and time deposits (¥6,742 → 13,851 million) and investment securities (¥33,752 → 45,339 million). Current liabilities increased from ¥9,220 million to ¥12,303 million, driven by higher trade payables and income taxes payable. Shareholders’ equity grew from ¥77,934 million to ¥82,392 million, supported by retained earnings and capital surplus gains.
The report covers Japan‑based operations for FY2012, with data presented in millions of yen. It relies on consolidated financial statements prepared under Japanese GAAP, reflecting a full year’s performance and balance sheet as of March 31, 2013.
- Net income grew by 21.9% to ¥5,656 million in FY2012, despite a 2.5% decline in total net sales to ¥34,639 million.
- Operating income rose 7.8% to ¥6,208 million, bolstered by a 27% increase in Game Software operating income and a 15.2% rise from Pachislot & Pachinko, which offset a 50% collapse in Online & Mobile operating income.
- Revenue performance was mixed across segments, with Pachislot & Pachinko sales jumping 29% to ¥2,195 million, while Game Software sales fell 4.7% and Online & Mobile revenue dropped 2.7%.
- The company’s balance sheet strengthened significantly, with total assets increasing from ¥54,909 million to ¥63,594 million, driven by substantial growth in cash, time deposits, and investment securities.
- Income before taxes saw a notable 17.4% increase to ¥8,779 million, contributing to an overall rise in shareholders' equity from ¥77,934 million to ¥82,392 million.
Koei Tecmo
Report2 pages
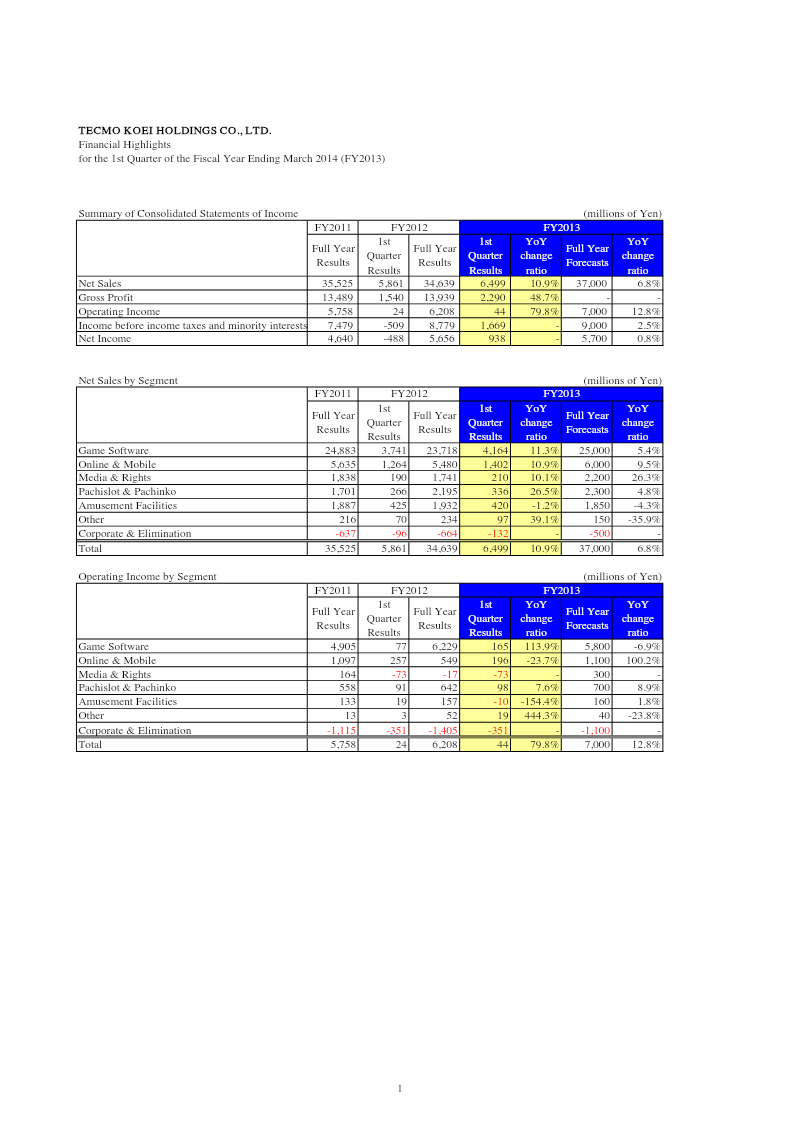
Financial Highlights: 1st Quarter of Fiscal Year Ending March 2014
The first‑quarter results for the fiscal year ending March 2014 show a 10.9 % rise in consolidated net sales to ¥35,525 million, driven mainly by a 10.9 % increase in game‑software revenue and a 26.5 % jump in pachislot & pachinko sales. Operating income climbed 79.8 % to ¥6,208 million, largely from a 113.9 % surge in game‑software operating profit and a 444.3 % rise in the “Other” segment, offset by declines in online & mobile and amusement‑facility operating income. Net income increased 938 million yen (18.0 % YoY) to ¥5,656 million, although the year‑to‑date net income for FY2013 remained slightly below forecast at ¥5,700 million.
Segment‑level analysis indicates that game software remains the core driver of profitability, while online & mobile revenue grew modestly (10.9 %) but with a 23.7 % decline in operating income, reflecting higher costs or lower margins. Media & rights and pachislot & pachinko segments showed modest operating gains, whereas amusement facilities experienced a 10.4 % drop in operating income.
Balance‑sheet activity shows current assets falling from ¥31,416 million to ¥19,267 million as cash and receivables declined sharply, while fixed assets remained stable. Total assets increased to ¥65,782 million, supported by a rise in investment securities. Current liabilities dropped from ¥12,303 million to ¥4,708 million, largely due to reduced trade payables and accrued bonuses. Shareholders’ equity decreased slightly from ¥82,392 million to ¥80,478 million, reflecting a modest decline in retained earnings and treasury stock adjustments. Overall, the company maintained solid revenue growth and profitability in Q1 FY2014, with notable strength in its core game‑software segment.
- Consolidated net sales rose 10.9% to ¥35,525 million in Q1 FY2014, driven by a 10.9% increase in game-software revenue and a 26.5% surge in pachislot & pachinko sales.
- Operating income grew 79.8% to ¥6,208 million, bolstered by a 113.9% increase in game-software operating profit and a 444.3% rise in the 'Other' segment.
- Net income increased 18.0% year-over-year to ¥5,656 million, though this figure fell slightly short of the ¥5,700 million forecast for the period.
- While online & mobile revenue grew by 10.9%, the segment's operating income declined by 23.7%, indicating reduced margins or increased operational costs.
- Amusement facility operations underperformed, recording a 10.4% drop in operating income during the quarter.
+1
Koei Tecmo
Financial32 pages
1st Half Financial Results: FY2015
The first‑half financial results for FY2014 demonstrate a continued upward trajectory, with sales reaching ¥16.11 billion and operating profit rising to ¥3.29 billion, a 4.2 % increase year‑on‑year and a 0.7 % rise versus forecast. Net income climbed to ¥4.21 billion, up 26.1 % YoY and 0.7 % above expectations, reflecting a 76.5 % increase from the prior year’s first half. Operating profit margins improved to 20.4 %, up 1.3 percentage points from the previous period, while ordinary profit margins reached 38.2 %, a 60.4 % YoY gain.
Geographically, Japan contributed ¥12.78 billion (82.7 % of total sales) with a 1.4 % YoY rise, while overseas markets grew by ¥3.51 billion (17.3 % of total), driven largely by North America and Europe, which saw sales increases of 31.0 % and 64.1 %, respectively. Unit volumes mirrored this trend, with overseas units up 30.4 % and North America up 60.3 %.
Segment analysis shows the Game division as the largest contributor, generating ¥9.87 billion in sales and ¥2.36 billion in operating profit, followed by Online & Media at ¥3.24 billion sales and ¥0.60 billion profit. The company’s strategy focuses on multi‑platform development, IP expansion into media and merchandise, and aggressive download business growth. Cost efficiencies are evident: COGS fell to 57 % of sales, SG&A to 55.6 %, and capital expenditures were maintained at ¥4 billion.
The company maintains a dividend policy targeting 50 % payout or ¥50 per share, with plans to increase the dividend to ¥50 in FY2014. Overall, the first‑half performance confirms a robust growth trajectory and sets a strong foundation for full‑year targets.
- The company achieved ¥16.11 billion in sales and ¥3.29 billion in operating profit for the first half of FY2014, representing a 4.2% year-on-year increase in operating profit.
- Net income rose significantly to ¥4.21 billion, marking a 26.1% year-on-year increase and exceeding forecasts by 0.7%.
- Overseas market performance was a key growth driver, with sales in North America and Europe increasing by 31.0% and 64.1% respectively, while total overseas unit volumes grew by 30.4%.
- The Game division remains the primary revenue driver, contributing ¥9.87 billion in sales and ¥2.36 billion in operating profit, followed by the Online & Media segment.
- Profitability improved as operating margins reached 20.4% and ordinary profit margins climbed to 38.2%, a 60.4% year-on-year gain.
Koei Tecmo

Financial38 pages
Financial Results: Fiscal Year Ending March 2015
Sales increased for the second consecutive year (Units: Dividend in Yen) and profit for the fifth! 80 (Unit: Net income in Million Yen) 70 Dividend (Units: Millions of Yen) FY2013 FY2014 YoY Change Amount Ratio Amount Ratio Amount Rate of change 50 37,576 55Yen 55Yen 8,000 Sales ...
- Sales increased for the second consecutive year, growing by 0.6% to 37,799 Million Yen in FY2014, while net income grew for the fifth consecutive year, increasing by 36.0% to 9,434 Million Yen in FY2014.
- Operating Profit increased by 35.2% to 9,652 Million Yen in FY2014, with the operating profit ratio improving by 4.3 points to 25.5%.
- Game Software was the largest contributor to sales (24,863 Million Yen) and operating profit (7,795 Million Yen) in FY2014.
- The company plans for continued growth in FY2015, with projected sales of 40,000 Million Yen (up 5.8%) and net income of 9,500 Million Yen (up 0.7%).
- Japan accounted for 53.8% of total unit sales (3,790 thousand units) in FY2014, while North America was the largest overseas market at 23.8% (1,680 thousand units).
Koei Tecmo
Report2 pages
Financial Highlights: Q1 FY2014
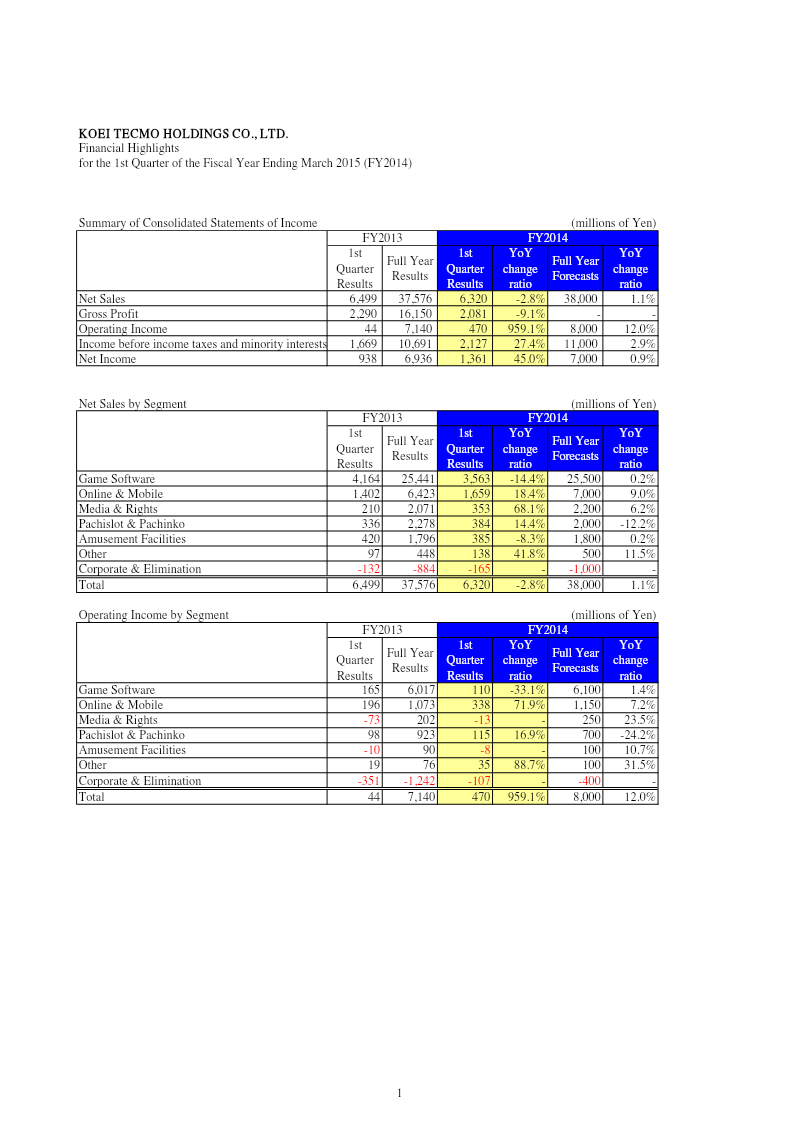
Financial highlights for the first quarter of fiscal year 2014 demonstrate a robust performance across KOEI TECMO HOLDINGS’ diversified portfolio. Net sales reached ¥37,576 million, a 2.8% decline from the prior year’s full‑year figure but aligned with the forecasted ¥38,000 million. Gross profit fell 9.1% to ¥16,150 million, while operating income surged 959.1% to ¥7,140 million, reflecting a sharp rise in profitability from the core gaming segment. Income before taxes climbed 27.4% to ¥10,691 million, and net income increased 45.0% to ¥6,936 million, approaching the forecasted ¥7,000 million.
Segment analysis shows Game Software sales of ¥25,441 million, down 14.4% YoY but near forecasted levels; Online & Mobile sales rose 18.4% to ¥6,423 million, surpassing the projected ¥7,000 million by 9.0%. Media & Rights and Pachislot & Pachinko segments posted significant gains of 68.1% and 18.4%, respectively, while Amusement Facilities declined 8.3%. Operating income mirrored these trends: Game Software contributed ¥6,017 million (−33.1% YoY), Online & Mobile added ¥1,073 million (+71.9%), and Media & Rights turned a profit of ¥202 million after a prior loss.
Balance‑sheet data as of June 30, 2014 show total assets at ¥93,826 million, down from ¥100,622 million the previous year, largely due to a reduction in current assets and a modest decline in fixed assets. Current liabilities fell sharply from ¥10,122 million to ¥4,421 million, improving liquidity. Shareholders’ equity remained strong at ¥84,433 million, with retained earnings slightly lower than the prior year. Overall, the quarter reflects a strategic shift toward higher‑margin online and mobile offerings while maintaining solid financial health.
- KOEI TECMO HOLDINGS reported a massive 959.1% surge in operating income to ¥7,140 million for Q1 FY2014, driven by increased profitability in its core gaming segment.
- Net income rose 45.0% to ¥6,936 million, nearly meeting the company's ¥7,000 million forecast despite a 2.8% decline in net sales to ¥37,576 million.
- The Online & Mobile segment outperformed expectations with an 18.4% sales increase to ¥6,423 million and a 71.9% rise in operating income to ¥1,073 million.
- Game Software sales fell 14.4% year-over-year to ¥25,441 million, resulting in a 33.1% decline in segment operating income to ¥6,017 million.
- Media & Rights and Pachislot & Pachinko segments saw significant growth, with sales increasing by 68.1% and 18.4% respectively.
+1
Koei Tecmo
Report2 pages
Financial Highlights: 1st Half of the Fiscal Year Ending March 2015
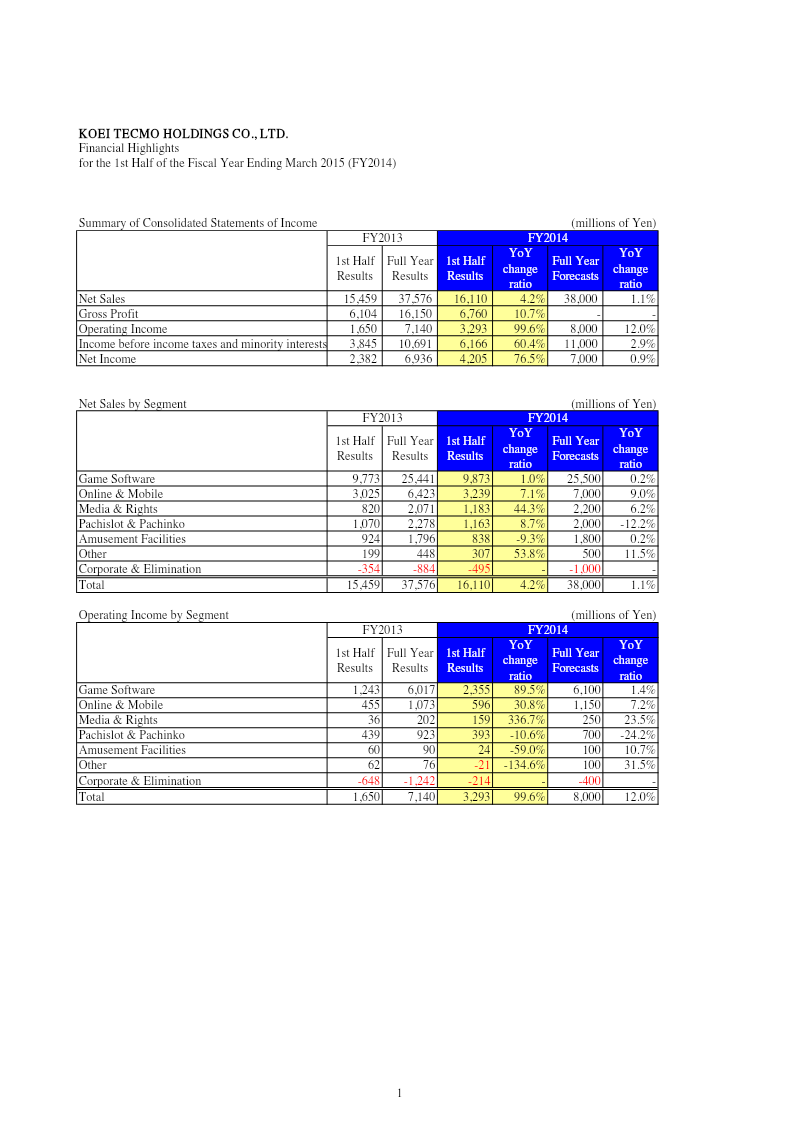
Financial highlights for the first half of fiscal year 2014, ending March 31 2014, show robust growth across KOEI TECMO HOLDINGS’ core segments. Net sales rose 4.2 % year‑on‑year to ¥37,576 million, driven primarily by game software sales that increased 1.0 % to ¥25,441 million and online & mobile revenue that grew 7.1 % to ¥6,423 million. Media & rights sales surged 44.3 %, while pachislot & pachinko and amusement facilities experienced moderate gains of 8.7 % and 9.3 %, respectively. Operating income expanded dramatically by 99.6 % to ¥7,140 million, largely due to a 89.5 % jump in game software operating profit and a 30.8 % rise in online & mobile profits. Net income climbed 76.5 % to ¥6,936 million, reflecting improved profitability across most segments.
Segment‑level operating income highlights include a 336.7 % increase in media & rights and a 23.5 % rise in online & mobile, while pachislot & pachinko and amusement facilities saw declines of 10.6 % and 59.0 %. Corporate & elimination costs increased, offsetting some gains.
Balance‑sheet data as of September 30 2014 show total assets at ¥99,132 million, slightly down from the prior year’s ¥100,622 million. Current assets fell to ¥18,855 million from ¥25,274 million, largely due to reduced cash and time deposits. Current liabilities dropped to ¥5,093 million from ¥10,122 million, improving liquidity. Shareholders’ equity increased to ¥91,269 million from ¥88,788 million, supported by retained earnings growth and a modest rise in accumulated other comprehensive income.
Overall, the first half of FY2014 delivered strong revenue and earnings growth, particularly in digital and media segments, while maintaining a solid balance‑sheet position with improved liquidity and equity.
- KOEI TECMO HOLDINGS achieved a 99.6% increase in operating income to ¥7,140 million and a 76.5% rise in net income to ¥6,936 million for the first half of the fiscal year ending March 2015.
- Net sales grew 4.2% year-on-year to ¥37,576 million, fueled by a 1.0% increase in game software sales and a 7.1% rise in online and mobile revenue.
- Profitability in the game software segment surged with an 89.5% increase in operating profit, while the online and mobile segment saw a 30.8% profit gain.
- The media and rights segment experienced significant growth, with sales rising 44.3% and operating income jumping 336.7% year-on-year.
- Liquidity improved as of September 30, 2014, with current liabilities decreasing to ¥5,093 million from ¥10,122 million in the prior year.
Koei Tecmo
Report2 pages
Financial Highlights: FY2013
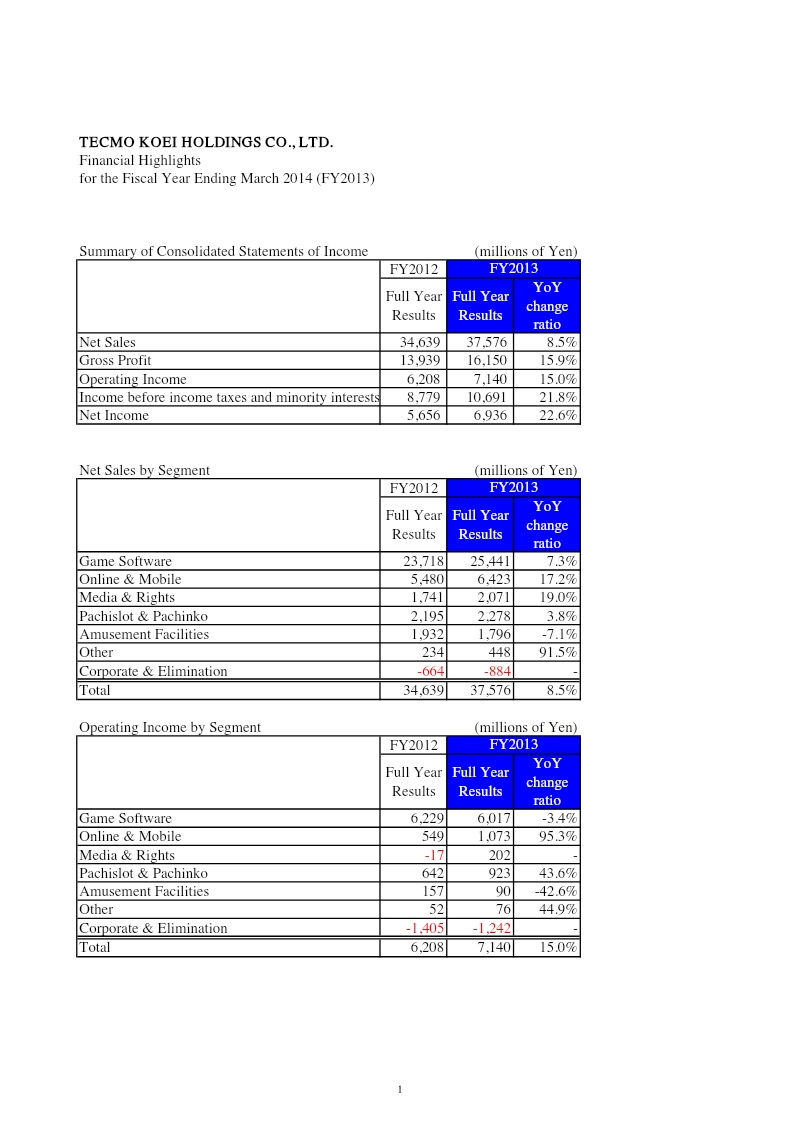
Financial highlights for the fiscal year ending March 2014 demonstrate a solid growth trajectory for Tecmo Koei Holdings. Net sales increased by 8.5 % to ¥37,576 million, driven primarily by a 7.3 % rise in Game Software sales and a notable 17.2 % jump in Online & Mobile revenue, while Media & Rights grew 19 %. Operating income expanded 15.0 % to ¥7,140 million; the Online & Mobile segment alone contributed a 95.3 % surge in operating profit, offsetting modest declines in Game Software and Amusement Facilities.
Profitability metrics improved markedly: income before taxes rose 21.8 % to ¥10,691 million and net income climbed 22.6 % to ¥6,936 million. Gross profit margin widened from 40.2 % in FY2012 to 43.0 % in FY2013, reflecting efficient cost management across segments.
Balance‑sheet strength is evident. Total assets grew 5.9 % to ¥100,622 million, largely due to a jump in investment securities and property & equipment. Current assets fell 19 % as cash and marketable securities were reduced, yet liquidity remained robust with current assets still exceeding current liabilities. Shareholders’ equity increased 5.4 % to ¥86,535 million, supported by retained earnings growth and a modest reduction in treasury stock.
The data cover the Japanese market for FY2013, with segmental performance broken down by product lines. Figures are presented in millions of yen and reflect consolidated financial statements, providing a comprehensive view of the company’s operational and financial health during the period.
- Tecmo Koei Holdings achieved a 22.6% increase in net income to ¥6,936 million for FY2013, supported by a 15.0% rise in operating income to ¥7,140 million.
- The Online & Mobile segment was a primary growth driver, recording a 17.2% revenue increase and a 95.3% surge in operating profit.
- Consolidated net sales grew 8.5% to ¥37,576 million, bolstered by a 7.3% increase in Game Software sales and 19% growth in Media & Rights.
- Operational efficiency improved as the gross profit margin expanded from 40.2% in FY2012 to 43.0% in FY2013.
- Income before taxes rose 21.8% to ¥10,691 million, reflecting strong overall profitability across the company's segments.
Koei Tecmo
Report2 pages
Financial Highlights: 3rd Quarter of the Fiscal Year Ending March 2015
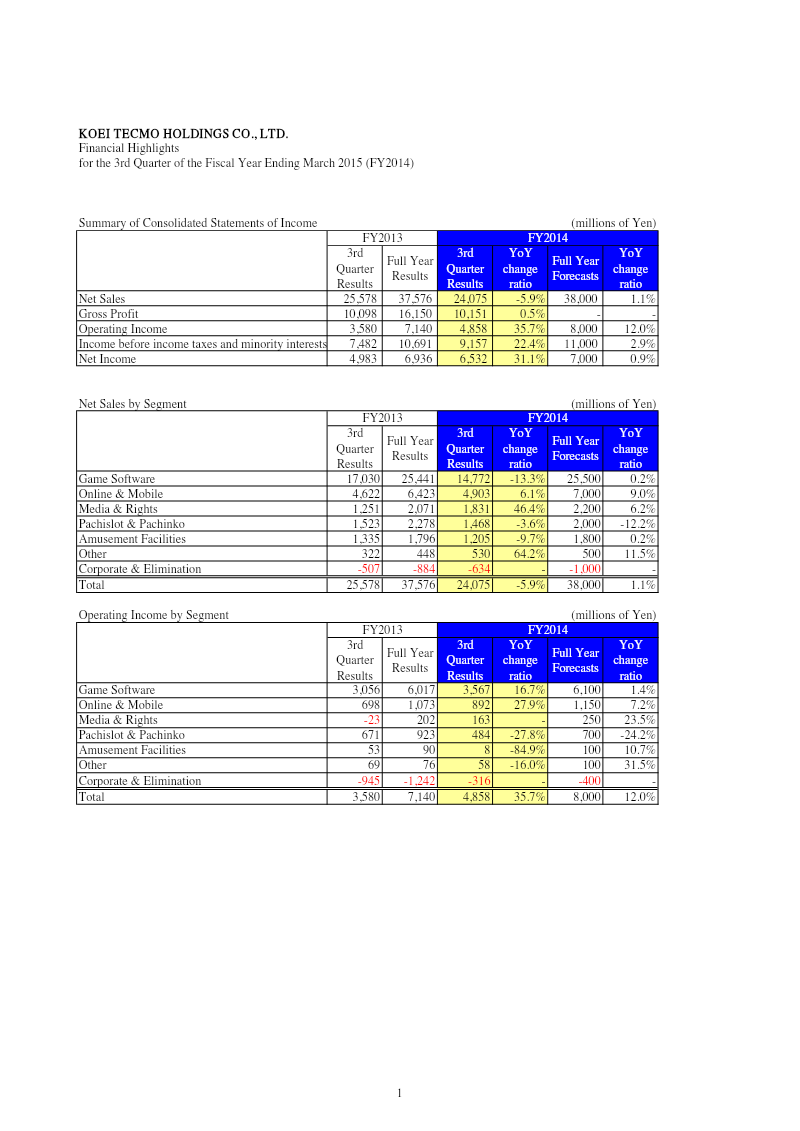
Financial highlights for the third quarter of fiscal year 2014, ending March 31 2015, show a robust performance across KOEI TECMO HOLDINGS’ core segments. Net sales rose to ¥37,576 million from ¥25,578 million in the same quarter of FY2013, a 5.9% decline versus the prior year but an increase of 1.1 % against the company’s forecast. Gross profit climbed to ¥16,150 million, up 0.5 % from the previous year’s figure, while operating income surged to ¥7,140 million, a 35.7 % jump from the prior year’s ¥3,580 million and 12.0 % above forecasted levels. Net income reached ¥6,936 million, up 31.1 % from FY2013’s ¥4,983 million and slightly above the projected ¥7,000 million.
Segment analysis reveals that Game Software sales increased to ¥25,441 million, a 13.3 % year‑over‑year decline but only 0.2 % below forecast, whereas Online & Mobile sales grew by 6.1 % to ¥6,423 million, outperforming the 9.0 % forecasted rise. Media & Rights sales expanded sharply by 46.4 % to ¥2,071 million, surpassing the 6.2 % forecasted growth. Pachislot & Pachinko and Amusement Facilities sales fell 3.6 % and 9.7 %, respectively, yet both remained close to or above their forecasted changes.
Operating income by segment mirrored these trends: Game Software and Online & Mobile segments delivered the largest gains, while Media & Rights shifted from a loss to a profit of ¥202 million. The company’s balance sheet strengthened, with total assets increasing from ¥100,622 million to ¥106,432 million and shareholders’ equity rising to ¥89,845 million. Current liabilities fell markedly, improving liquidity ratios. Overall, the quarter demonstrated solid profitability growth driven by strong performance in core software and online segments, offsetting declines in traditional gaming and amusement operations.
- KOEI TECMO HOLDINGS achieved a 35.7% surge in operating income to ¥7,140 million, significantly outperforming the company's forecast by 12.0%.
- Net income for the third quarter ending March 31, 2015, rose 31.1% year-over-year to ¥6,936 million, despite a 5.9% decline in net sales to ¥37,576 million compared to the prior year.
- The Media & Rights segment experienced a sharp 46.4% revenue expansion to ¥2,071 million, successfully shifting from a loss to a profit of ¥202 million.
- Online & Mobile sales grew by 6.1% to ¥6,423 million, contributing to the company's overall profitability alongside the core Game Software segment.
- Game Software sales totaled ¥25,441 million, representing a 13.3% year-over-year decline that remained nearly in line with forecasts at 0.2% below projections.
+1
Koei Tecmo
Report2 pages
Financial Highlights: 1st Quarter of the Fiscal Year Ending March 2016
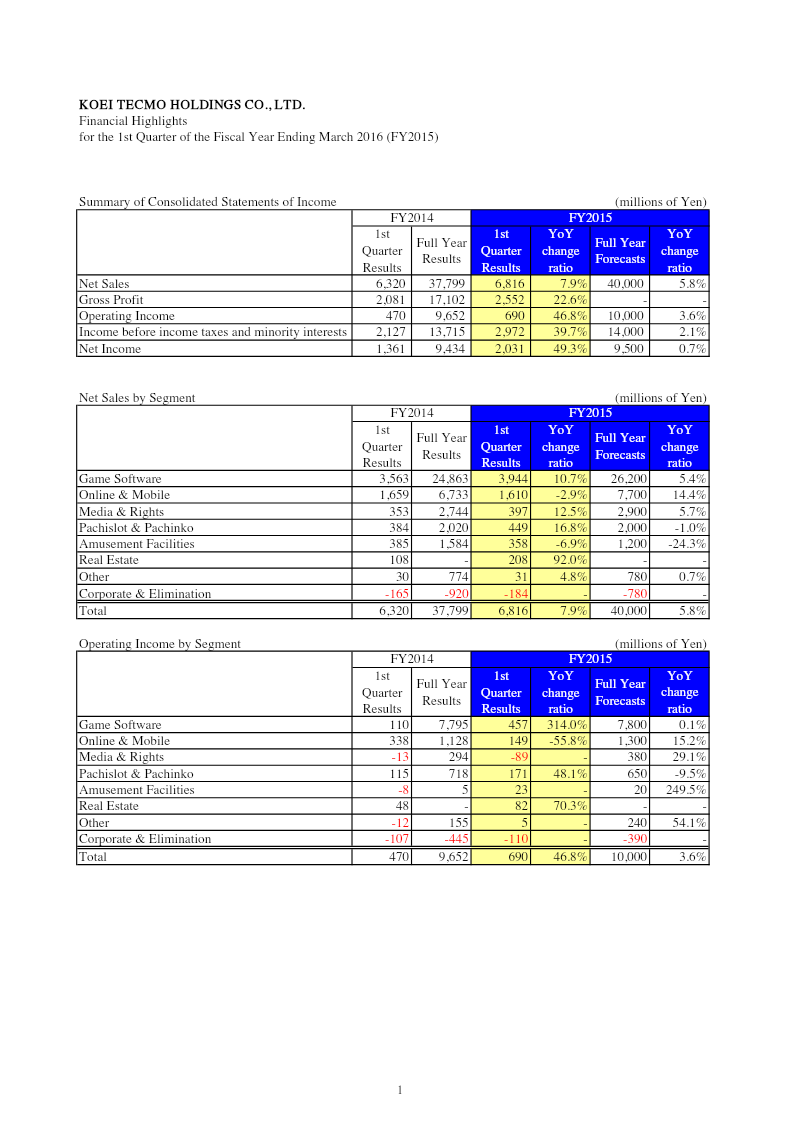
Koei Tecmo Holdings reported a strong first‑quarter performance for the fiscal year ending March 2016, with net sales rising 7.9% to ¥37.8 billion from ¥35.2 billion the prior year, and net income increasing 49.3% to ¥9.4 billion. Gross profit grew 22.6%, while operating income surged 46.8% to ¥9.7 billion, reflecting higher profitability across most segments. Game software sales led the increase at 10.7%, followed by online & mobile (−2.9%) and media & rights (+12.5%). Pachislot & pachinko sales rose 16.8%, whereas amusement facilities declined 6.9%. Real‑estate revenue jumped 92% but was offset by a corporate & elimination loss of ¥920 million. Operating income per segment showed dramatic gains in game software (314%) and pachislot & pachinko (48%), but a sharp decline in online & mobile (-55.8%) and media & rights (-89). Forecasts for the full year target net sales of ¥40 billion (up 5.8%) and operating income of ¥10 billion (up 3.6%).
On the balance‑sheet side, total assets fell from ¥115.2 billion to ¥107.1 billion, largely due to reductions in current assets and investment securities. Current liabilities dropped by 49% to ¥5.6 billion, driven by lower trade payables and accrued bonuses. Shareholders’ equity decreased modestly to ¥90.2 billion, with retained earnings at ¥51.2 billion and a slight decline in treasury stock. Net assets stood at ¥98.1 billion, reflecting modest changes in other comprehensive income items such as unrealized gains on securities and foreign‑currency adjustments. The company’s liquidity position remained solid, with cash and time deposits at ¥10.9 billion and a current‑asset to liability ratio improving from 2.47 to 3.94. Overall, the quarter demonstrated robust revenue growth and improved profitability despite segment‑specific variances, positioning Koei Tecmo for a moderately optimistic full‑year outlook.
- Koei Tecmo reported a strong Q1 fiscal 2016, with net income surging 49.3% to ¥9.4 billion and net sales rising 7.9% to ¥37.8 billion.
- Operating income grew 46.8% to ¥9.7 billion, driven by a 314% increase in game software segment profitability and a 48% gain in pachislot & pachinko.
- The online & mobile segment experienced a 2.9% decline in sales and a significant 55.8% drop in operating income, while media & rights saw an 89% decline in operating income despite a 12.5% revenue increase.
- The company maintains a solid liquidity position, with the current-asset to liability ratio improving from 2.47 to 3.94 and cash and time deposits totaling ¥10.9 billion.
- Total assets decreased from ¥115.2 billion to ¥107.1 billion, while current liabilities were reduced by 49% to ¥5.6 billion due to lower trade payables and accrued bonuses.
+1
Koei Tecmo