Investment reports and market data
Documents
Insurance in the Video Game Sector: Spain
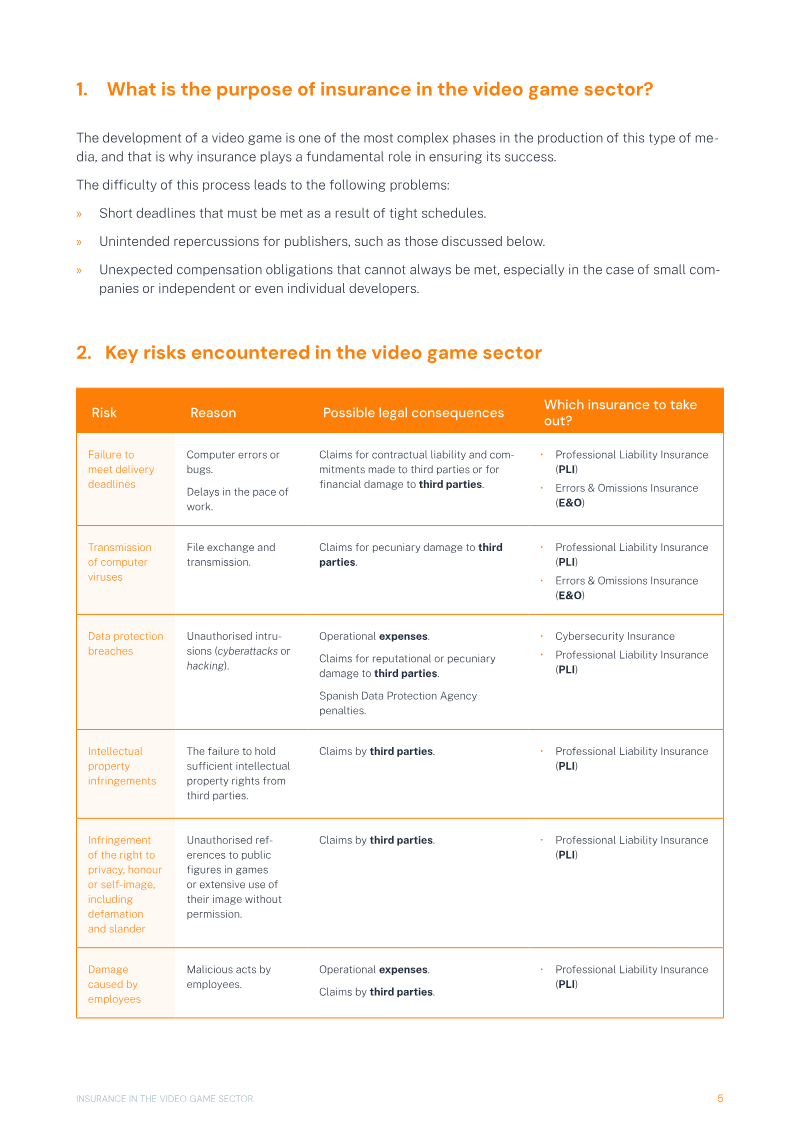
The guide explains that insurance is a critical safeguard for video-game development in Spain, where tight schedules, complex technical workflows and the involvement of multiple parties create a range of legal and financial exposures.
- Spanish video game developers face critical financial and legal exposures from project delays, software bugs, cyber-attacks, and intellectual property infringements.
- Professional Liability Insurance (PLI) and Errors & Omissions (E&O) policies are essential to mitigate risks related to contractual failures and professional errors.
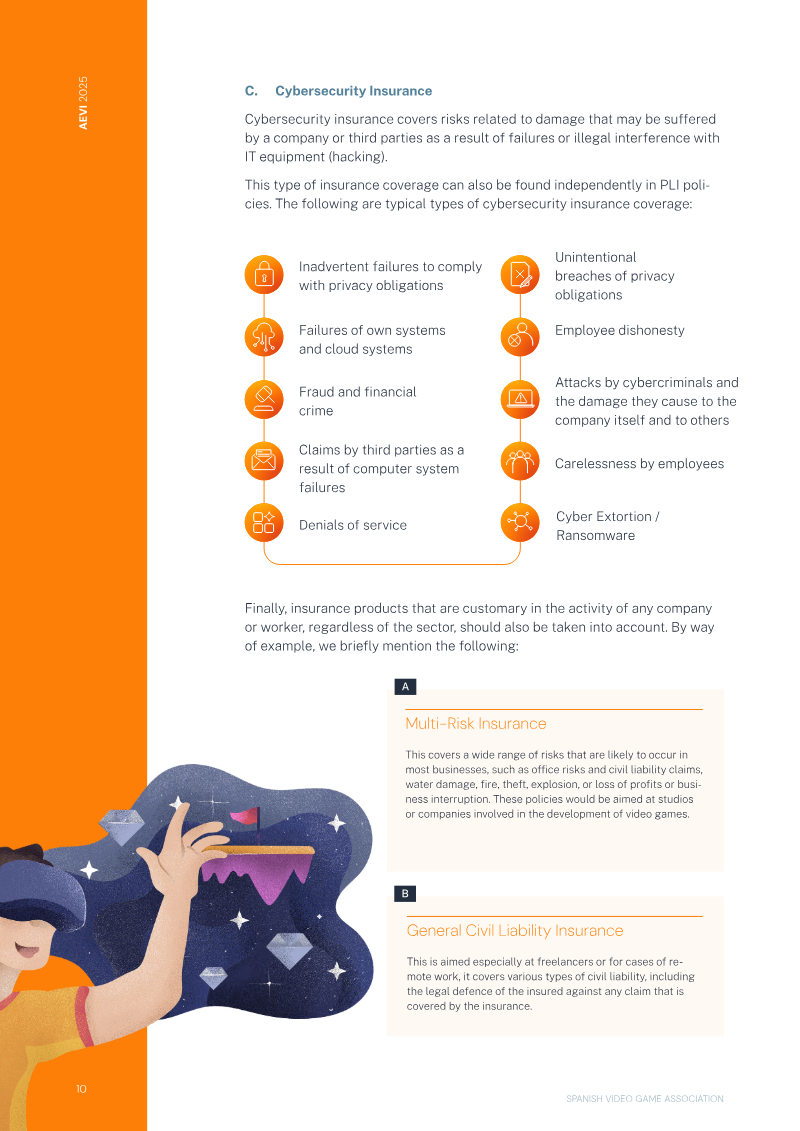
- Cybersecurity insurance is required to address specific threats including ransomware, data-protection breaches, and the transmission of computer viruses.
Taxation in the Video Game Sector: Spain
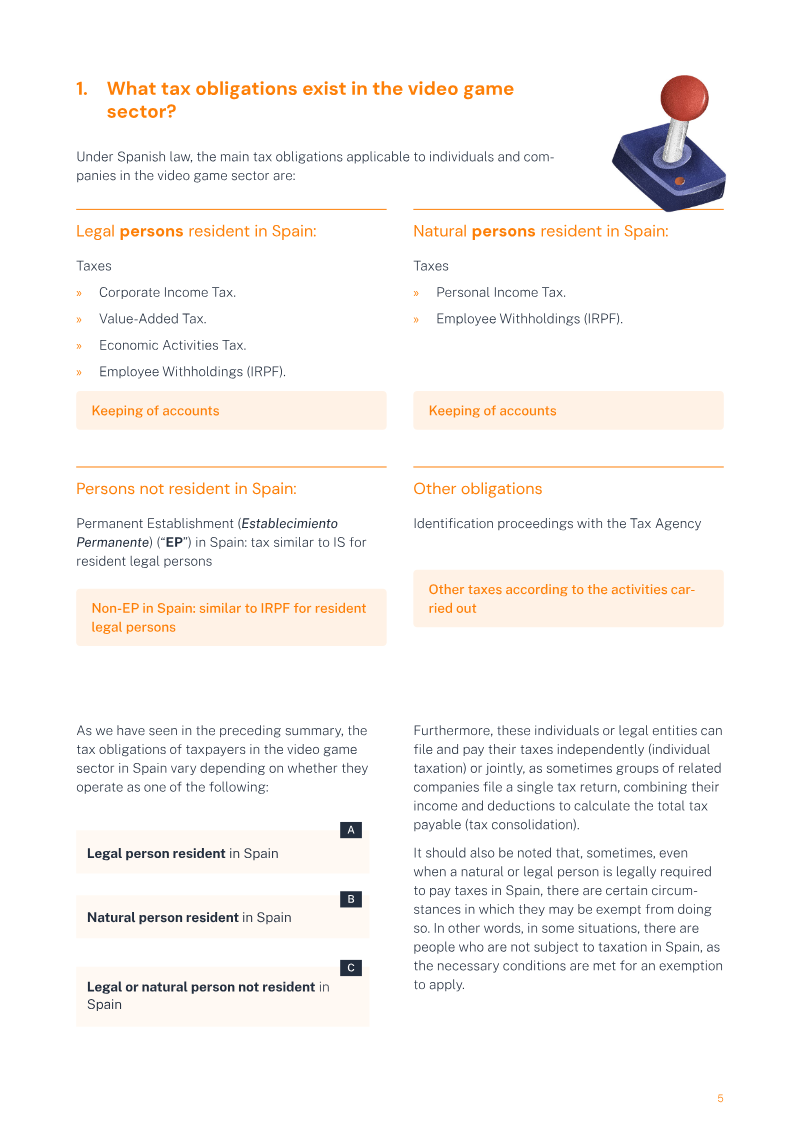
The guide explains the tax framework that applies to video-game companies operating in Spain, outlining both mandatory obligations and the range of incentives available to reduce fiscal burdens.
- Resident video game companies in Spain are subject to a 25% corporate income tax rate, while qualifying start-ups can access a reduced 15% rate for four tax periods.
- The Canary Islands offer a highly competitive 4% corporate tax rate and exemptions on property-transfer and IGIC taxes for companies meeting specific investment and employment criteria.
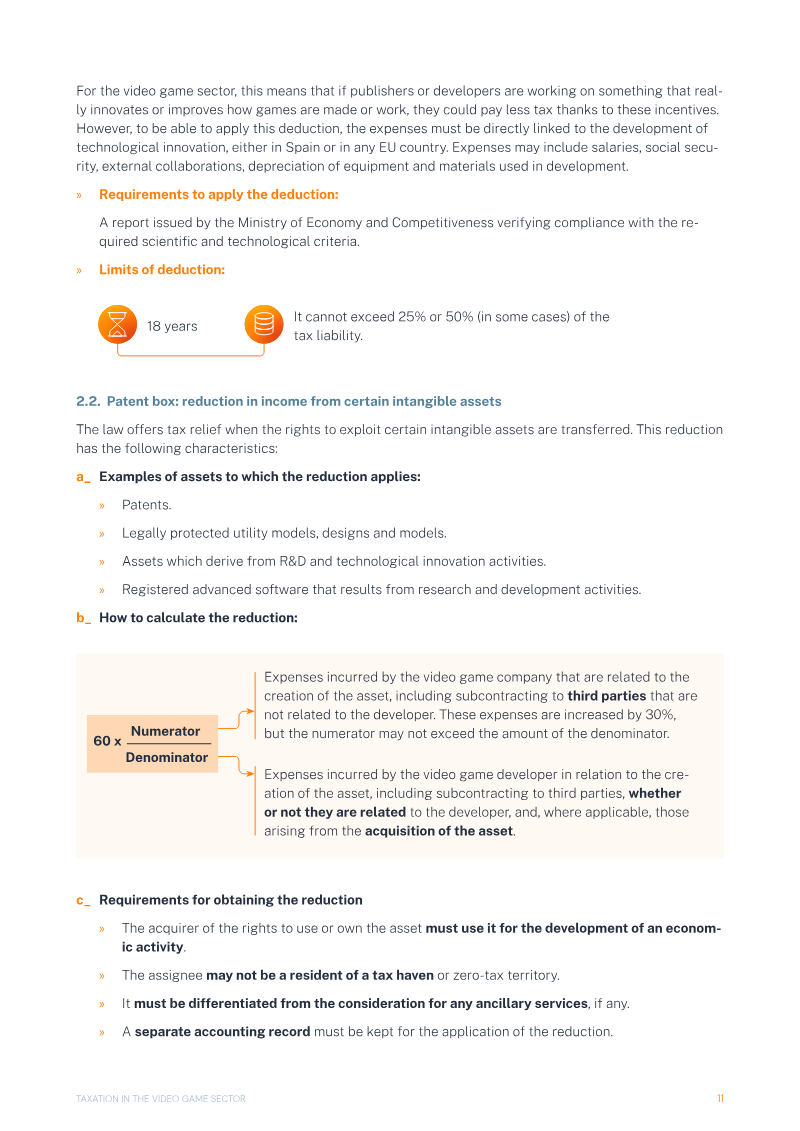
- R&D and technological innovation expenses qualify for a 12% tax credit, capped at 25–50% of total tax liability, alongside a patent-box regime that reduces the taxable base for advanced software.
La Fiscalidad en el Sector de los Videojuegos: España
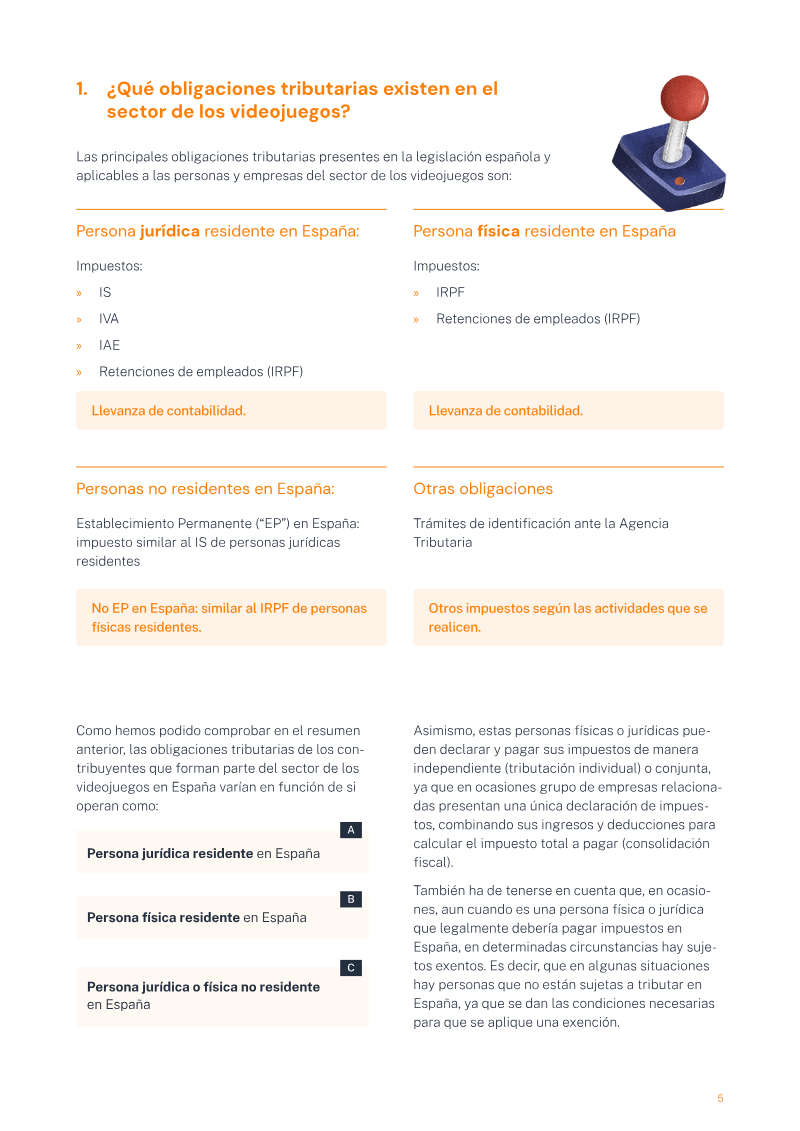
The guide aims to clarify the tax framework that applies to video-game developers, publishers and related service providers operating in Spain, outlining both mandatory obligations and available fiscal incentives.
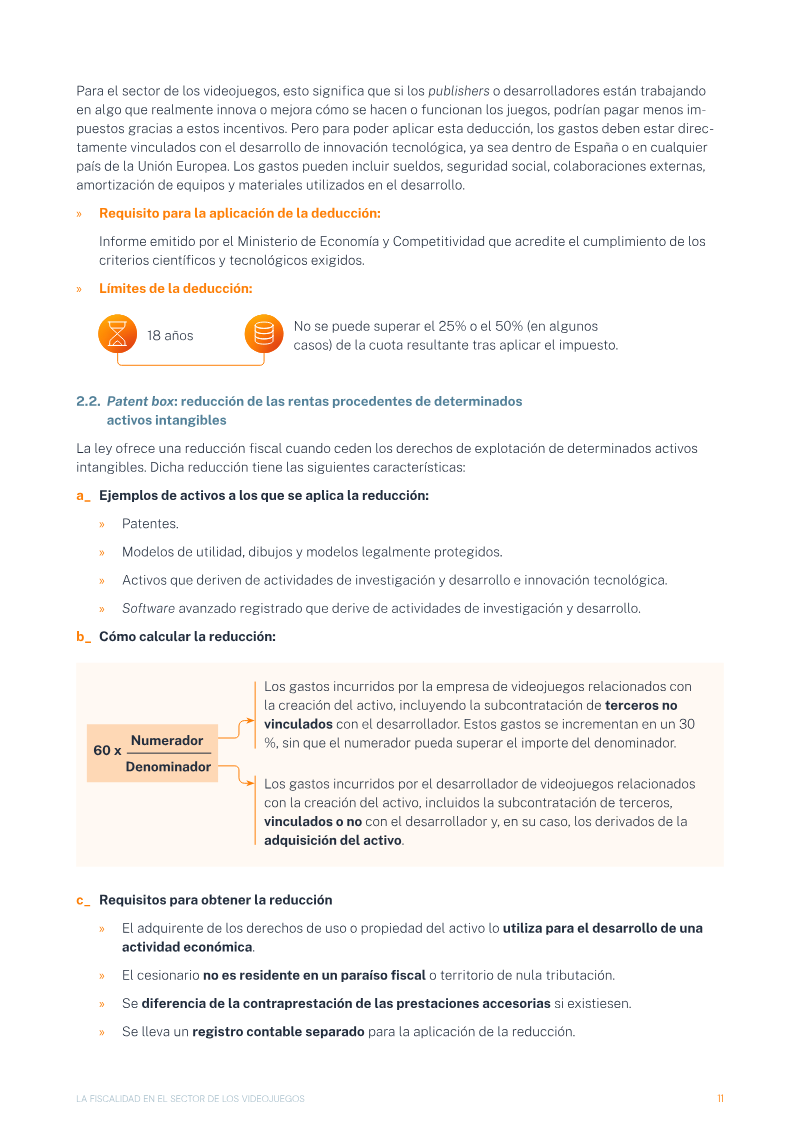
- Video game companies in Spain can access a 12% tax deduction for qualifying R&D+i expenses, which increases to 45% for projects developed in the Canary Islands.
- Start-ups meeting ENISA criteria qualify for a reduced 15% corporate tax rate for four years, along with exemptions from advance payments and deferred tax liabilities.
- The standard corporate income tax (IS) rate in Spain is 25%, while personal income tax (IRPF) for self-employed professionals ranges from 19% to 47%.
Interview with Frank Kang, Associate Partner at Antler: Malaysia
Korean content and entertainment startups are being urged to treat Southeast Asia as a primary growth engine rather than a peripheral market.
- Korean entertainment and content startups must treat Southeast Asia as a primary growth engine rather than a peripheral market to achieve sustainable expansion.
- Success requires deep localisation through local 'co-pilots' to navigate fragmented linguistic, regulatory, and payment landscapes in key hubs like Jakarta, Manila, and Bangkok.
- Revenue models should shift toward mobile-wallet-driven micro-transactions, live-commerce, and hybrid free-plus-premium structures to align with local consumption habits.
Global Sports Tech Market Report H1 2025
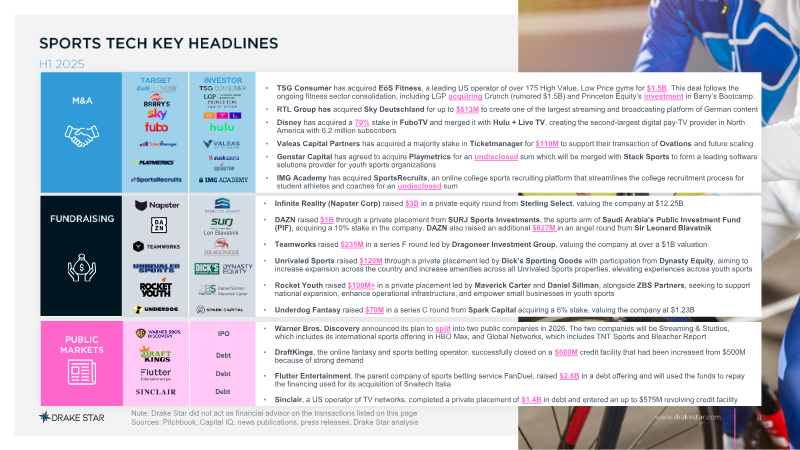
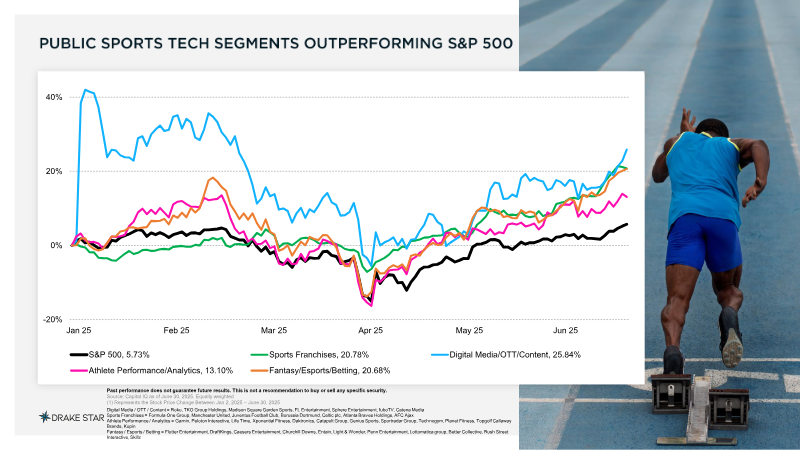
In the first half of 2025 the global sports-technology sector recorded approximately $52 billion in announced or closed transactions, underscoring a rapid acceleration of both merger-and-acquisition activity and capital raising.
- The global sports tech market reached a total deal value of $51.9 billion in H1 2025 across 503 announced or closed transactions.
- M&A activity dominated the sector with $32.2 billion in disclosed deal value across 233 deals, led by TSG Consumer’s $1.5 billion acquisition of EōS Fitness.
- Private placements hit a record $6.6 billion across 239 deals, highlighted by Infinite Reality raising $3 billion and DAZN securing $1.8 billion.
Global Gaming Report 2025
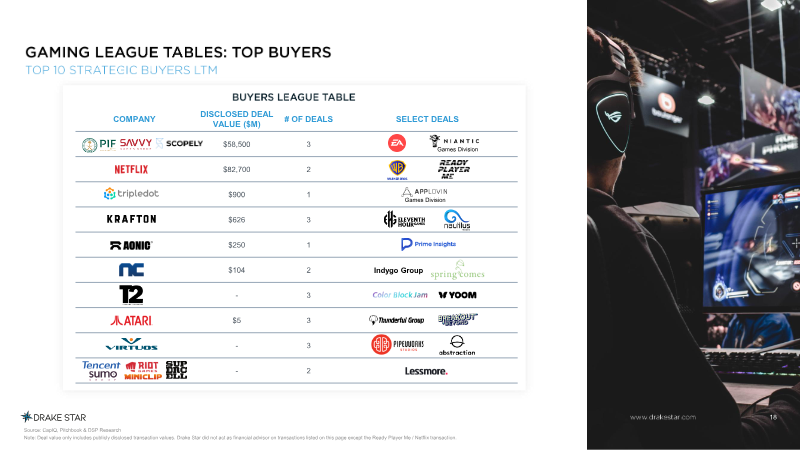
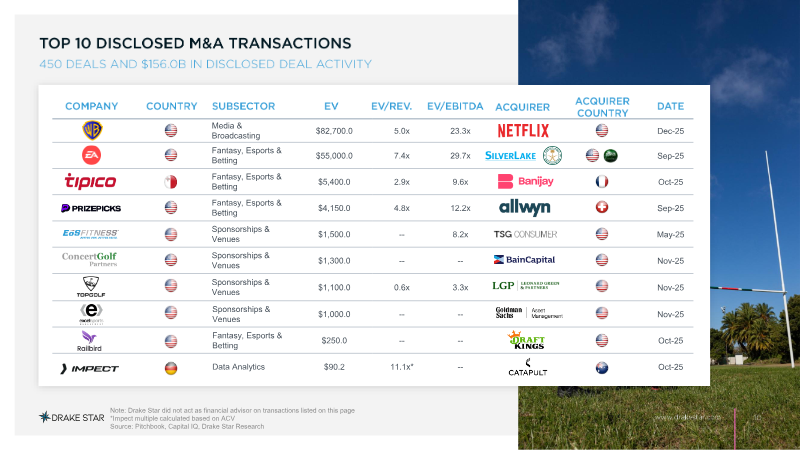
The analysis focuses on the accelerating consolidation of the worldwide gaming ecosystem, emphasizing the unprecedented scale of mergers and acquisitions (M&A) and private-placement financing observed in the final quarter of 2025 and projecting a further surge into 2026.
- The gaming M&A market reached a landmark $161 billion in total disclosed value across 759 announced deals in 2025.
- Netflix announced a major $82.7 billion acquisition of Warner Bros. and its gaming division, which triggered a hostile $108.4 billion bid for Warner Bros. Discovery by Paramount–Skydance.
- A consortium led by PIF completed a $55 billion leveraged buyout of Electronic Arts (EA) in September 2025.
Sports Tech Market 2025
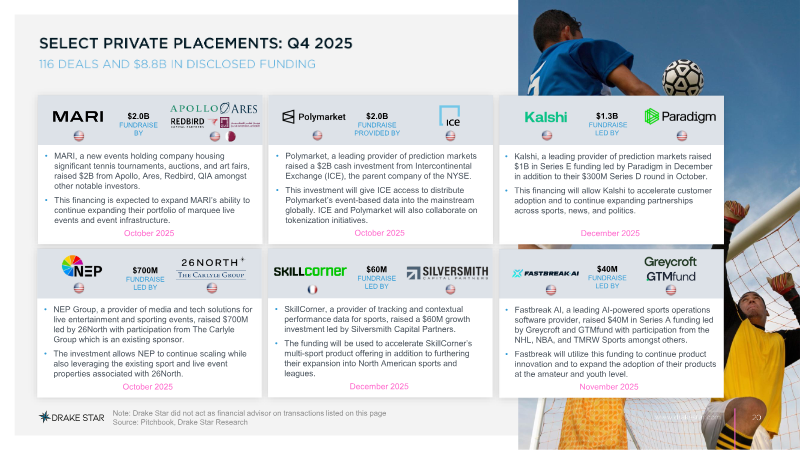
The 2025 sports-technology market experienced an unprecedented surge of private capital, with roughly 500 announced transactions totaling $14.3 billion.
- The sports tech market reached a record $200 billion in total deal value across 1,026 announced transactions in 2025.
- M&A activity was dominated by two mega-deals: Netflix's $82.7 billion proposed acquisition of Warner Bros Discovery and Saudi PIF/Silver Lake's $55 billion acquisition of EA.
- Private placements hit a record $14.3 billion in 2025, a 1.5x growth in value since 2023, despite the total number of financing deals declining to 500.
Investor Trends Set to Dominate Gaming M&A in 2025 ft. Drake Star’s Michael Metzger
The global gaming mergers and acquisitions market is undergoing a robust recovery, evidenced by a 70% year-over-year increase in deal volume during the third quarter of 2024.
- Gaming M&A activity surged in 2024 with a 70% year-over-year increase in sales, driven by a shift toward profitability-focused deals and strategic consolidation.
- Private equity firms have become major players in the gaming sector, evidenced by the year's two largest acquisitions: CVC’s purchase of Checkex and EQT’s acquisition of Keywords.
- Standard deal structures for private and venture-backed companies currently consist of a cash payment at closing followed by an earnout based on future performance metrics.
Remedy Capital Markets Day 2024: Creative Ambitions
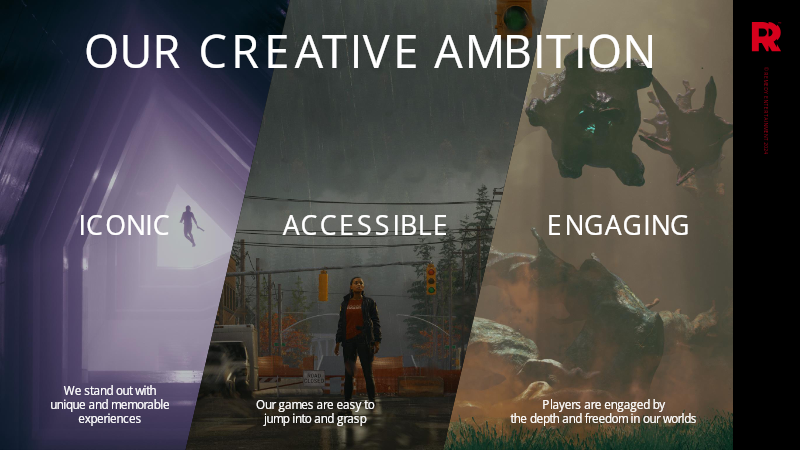
Remedy Entertainment focuses on establishing a distinct market position by prioritizing iconic, accessible, and engaging gaming experiences.
- Remedy Entertainment is positioning itself as a leader in the premium action-adventure segment by focusing on mature, narrative-driven titles that blend familiar settings with supernatural elements.
- The studio’s core creative strategy centers on high-quality storytelling, character development, and emotional depth to ensure its games resonate with a broad, global audience.
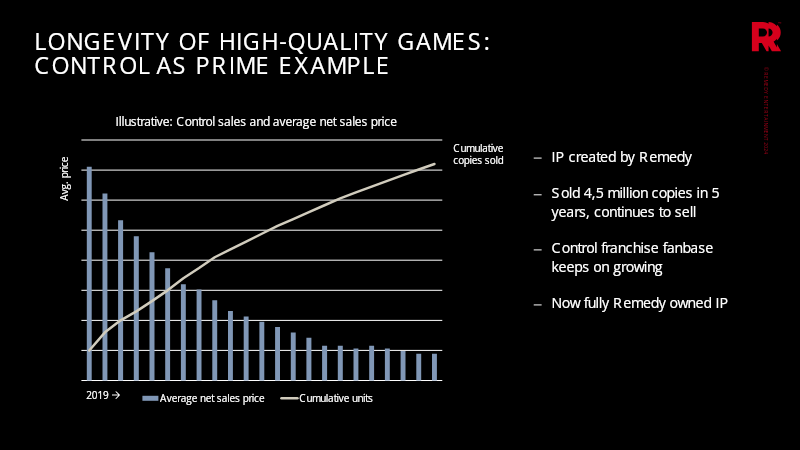
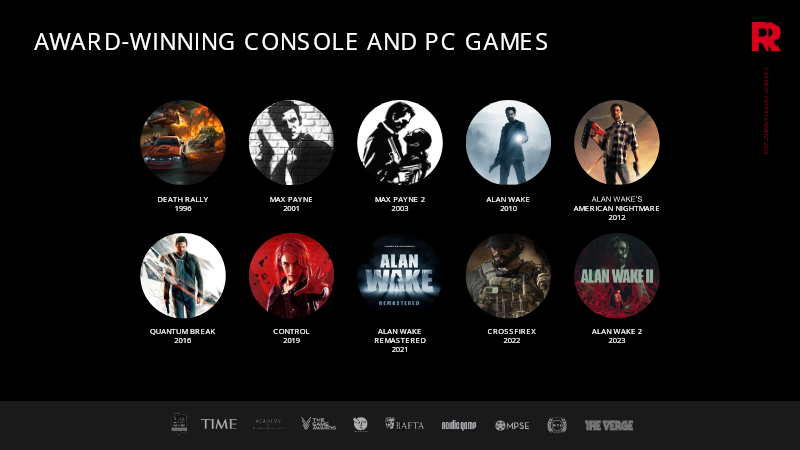
- The Alan Wake and Control franchises serve as the primary pillars of the studio's current output, consistently achieving high critical acclaim and major industry awards.
Remedy Capital Markets Day 2024: Business Logic and Value Creation
The Remedy Capital Markets Day 2024 presentation outlines a strategic pivot toward self-publishing as the primary engine for long-term value creation and profitability.
- Remedy is shifting to a self-publishing model to capture higher margins, targeting a 30% EBITDA margin by 2027.
- The company aims to double its 2024 revenue by 2027 through a portfolio of self-published titles and partner-funded projects.
- Financial modeling indicates that self-publishing creates non-linear returns, with potential ROI increasing from 75% to 250% if game sales double from 100 million to 200 million euros.
Remedy Capital Markets Day 2024
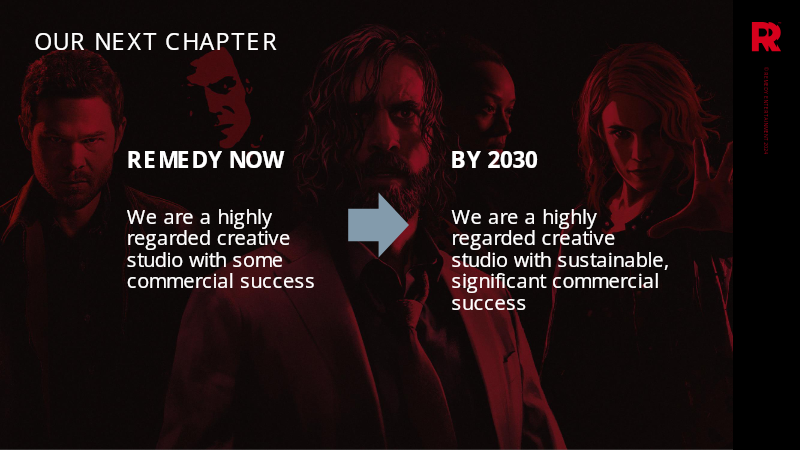
Remedy Entertainment’s 2024 Capital Markets Day outlines a strategic pivot toward sustainable, profitable growth by transitioning into a self-publishing entity while leveraging its established portfolio of high-quality, narrative-driven action games.
- Remedy is transitioning to a self-publishing model for its core intellectual properties to capture a larger share of sales and long-term financial upside.
- The company aims to transform the Control and Alan Wake franchises into multi-medium, world-class entertainment brands by 2030.
- The current development pipeline features three major projects: the multiplayer title FBC: Firebreak, the sequel Control 2, and the Max Payne 1 & 2 remake.
Week in Mobile Games E36 - Games industry M&A hits overdrive with Plarium and Easybrain deals
The mobile gaming industry is currently undergoing a period of intense structural realignment, characterized by high-profile mergers and acquisitions and a strategic pivot toward more sustainable monetization models.
- Major mobile gaming M&A activity is accelerating, highlighted by Miniclip’s $1.2 billion acquisition of Easybrain and MTG’s $620 million purchase of Plarium.
- Publishers are shifting from hyper-casual advertising models to hybrid-casual strategies to improve long-term revenue sustainability.
- The Indian mobile gaming market is forecast to reach a valuation of $7.5 billion by 2028, signaling significant regional growth.