ReportSensor Tower
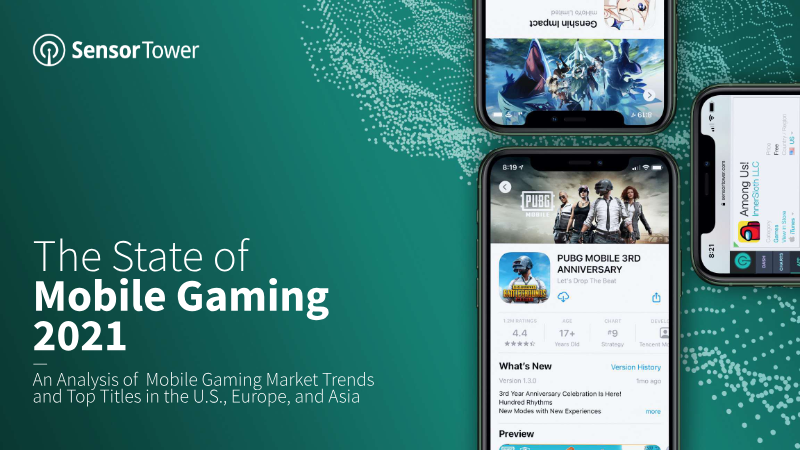
The State of Mobile Gaming 2021: U.S., Europe, and Asia
202178 pages~67 min full read
Key insights
6 slides
The surge
Quarterly consumer spending reached $22 billion by early 2021.
Global mobile gaming spending rose 25% year-over-year. Pandemic-related shifts accelerated both spending and engagement.

Who leads
The United States leads revenue, while Asia dominates downloads.
Asia's download volume is driven by high adoption rates in India and Indonesia. Europe has demonstrated significant growth, particularly in Germany.

Concentration
Top five markets account for 77% of total spending.
The freemium model generates 99% of App Store revenue. Premium titles face a continued decline.

Subscriptions
Subscription models are utilized by 29% of top-grossing titles.
Advertising remains a primary revenue stream for hypercasual and puzzle genres. Developers are navigating evolving user privacy and advertising attribution.
Page 60 of the report20179
201817
201927
202029
2023 projection
The industry is projected to reach $117 billion in spending by 2023.
Annual downloads are projected to reach 67.2 billion by 2023. Role-playing games remain the highest-grossing genre.
Page 44 of the report201963
202080
2021F95
2022F106
2023F117
Future growth
Growth is expected to be strongest in Southeast Asia and Europe.
These regions are anticipated to outpace global revenue growth rates. Major players like Zynga and Playrix are navigating privacy challenges.

1 / 6
Ask AI about this report