Key insights
6 slides
Valuation Shift
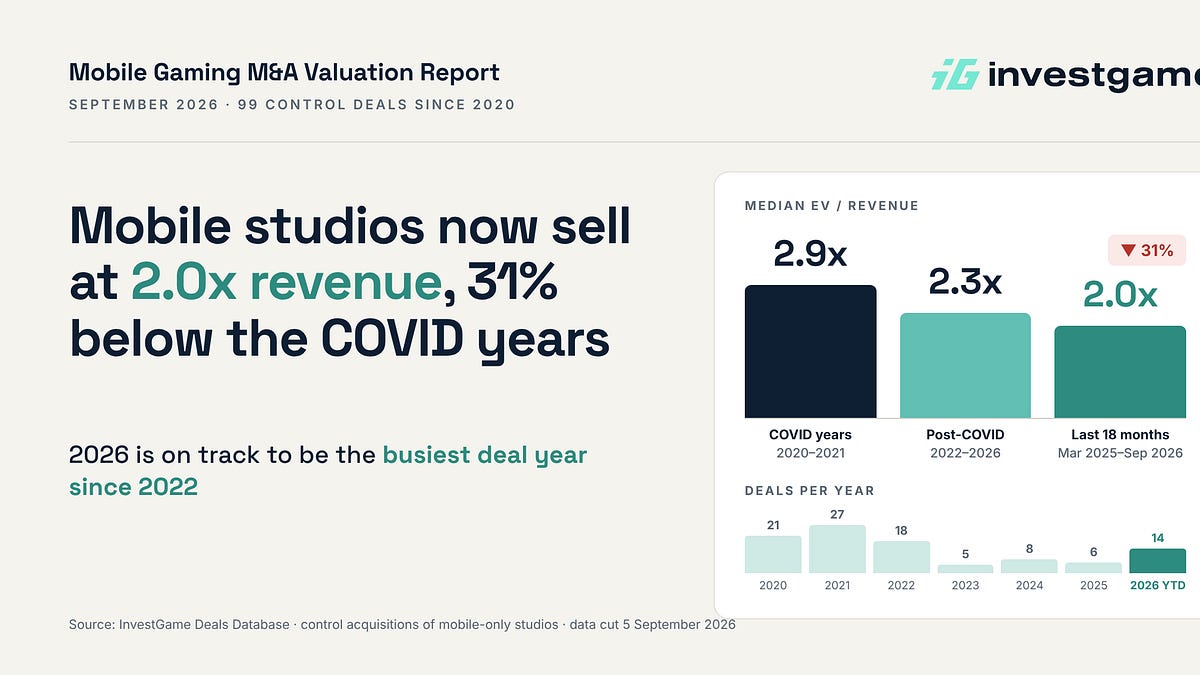
Mobile gaming studio acquisitions are valued at a median of 2.0x revenue and 8.6x EBITDA.
The market is experiencing a cooling in acquisition multiples.
Market Trend
Revenue multiples decreased by 31% and EBITDA multiples dropped by 14% from 2020–2021 peaks.
Valuations have retreated from pandemic-era highs.
Declining Multiples. Mobile gaming studio acquisitions are currently valued at a median of 2.0x revenue and 8.6x EBITDA, representing a 31% and 14% decline respectively compared to the 2020–2021 COVID-era peaks.
Accelerating Activity
Deal activity is accelerating in 2026, with 14 recorded transactions by September 5.
This makes 2026 the busiest year for mobile studio M&A since 2022. Market activity is picking up despite the contraction in pricing.
Historical Volume
Annual deal volume for mobile-only studios dropped from a peak of approximately 24 deals per year.
The volume then averaged 11 deals per year between 2022 and 2025.
Premium for Large Deals
Large-cap acquisitions valued at $1bn+ command a significant premium.
These deals trade at a median of 3.9x revenue and 19.7x EBITDA.
Size Premium. Large-cap acquisitions valued at $1bn+ command a significant premium, trading at a median of 3.9x revenue and 19.7x EBITDA, compared to 2.1x and 9.1x for mid-cap deals between $100m and…
Value Per Employee
The median enterprise value per employee across all mobile studio deals is $1.8m.
Large-cap deals average $3.3m per employee. Hit-title studios can significantly exceed this average.
1 / 6
Ask AI about this report