1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReport European Games Developer Federation
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReportEuropean Games Developer Federation
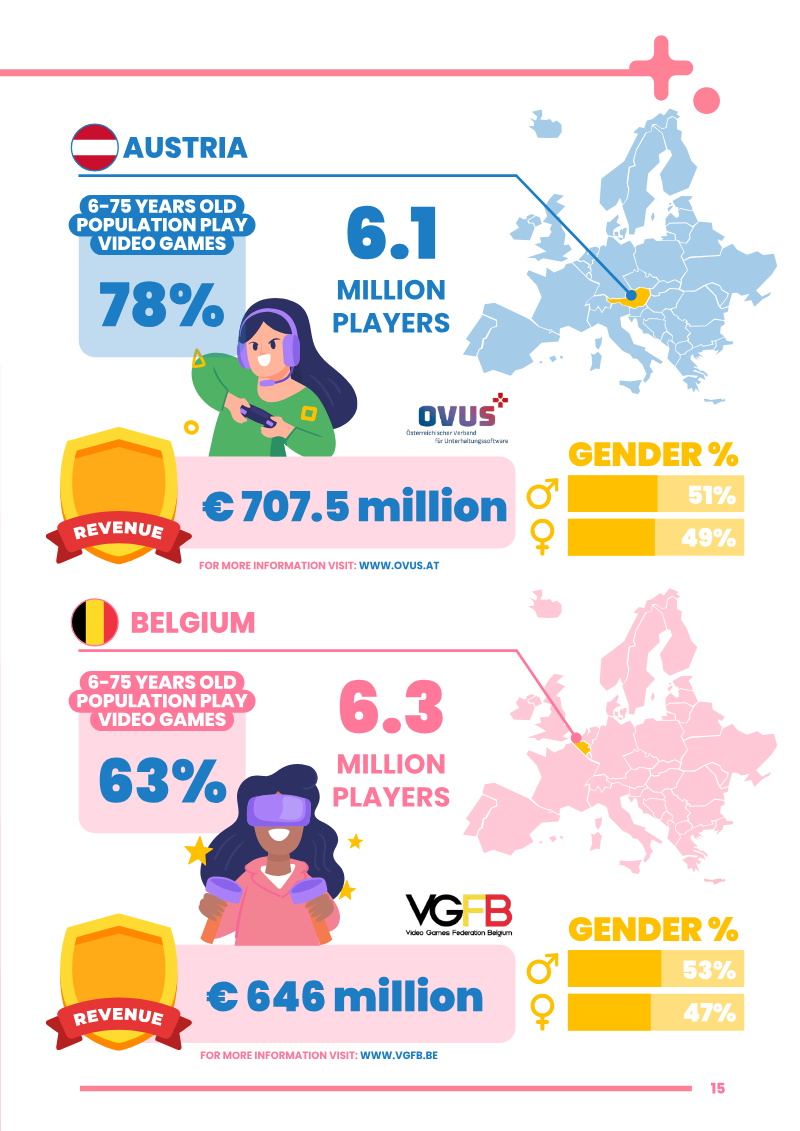
The Belgian games industry experienced significant expansion throughout 2021, characterized by robust growth in both infrastructure and economic output. The sector saw the number of active entities—comprising game studios, publishers, service providers, and incubators—climb to 110, representing a notable increase from the 84 organizations recorded in 2020. This organizational growth was mirrored by a rise in human capital, with full-time equivalent employment reaching 935 positions, up from 825 the previous year. Consequently, the industry generated a total turnover of €88 million, marking an 8% year-over-year increase.
Geographically, the industry maintains a diverse footprint across the nation. East Flanders continues to serve as the primary hub for game companies, while the Brussels region demonstrated exceptional momentum with a 70% growth rate in its local sector. The distribution of companies remains spread across various provinces, including Antwerp, West Flanders, and Walloon Brabant, reflecting a decentralized but active ecosystem. Maturity within the market is also evident, as more than half of the identified companies have been in operation for over five years, suggesting a stable foundation for long-term development.
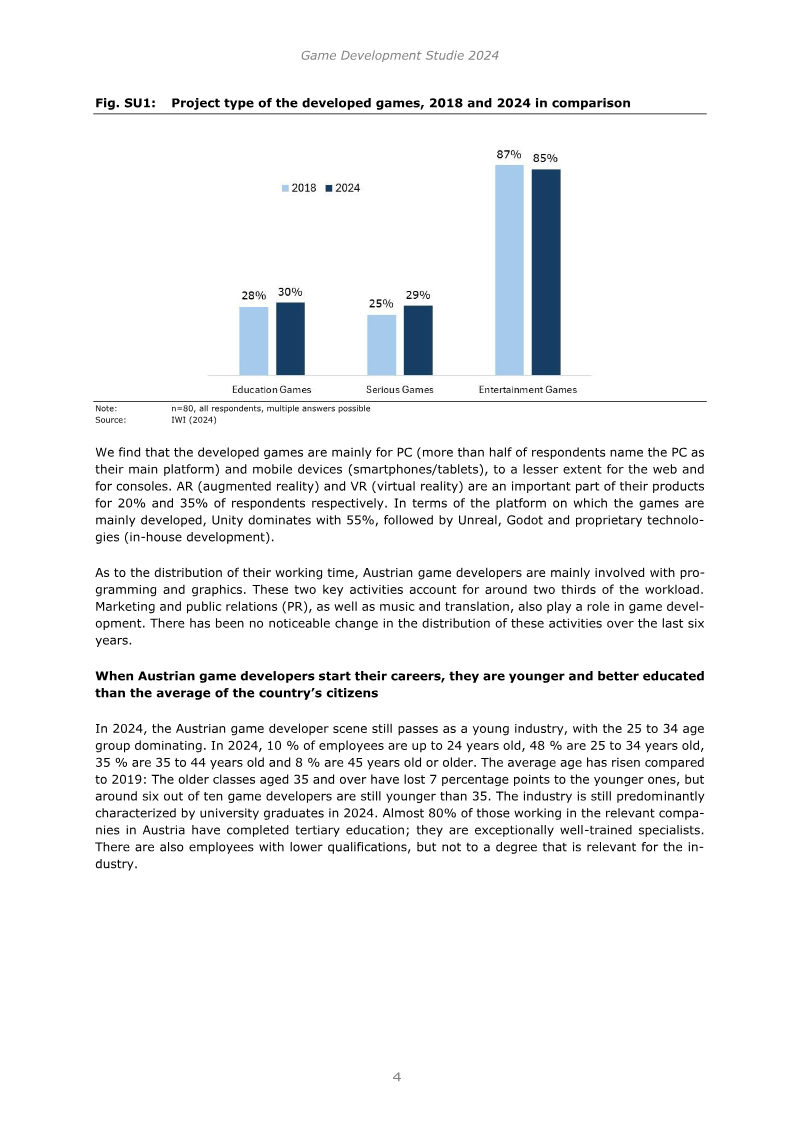
Strategic focus remains heavily concentrated on entertainment-oriented titles, which continue to dominate the market as the largest category. Regarding technical development, PC remains the most profitable platform for local studios. The data reflects a refined scope that focuses exclusively on professional game studios, publishers, service providers, and accelerators, ensuring a targeted analysis of the industry’s core commercial participants. These findings underscore a period of sustained professionalization and economic scaling for the Belgian gaming landscape.
Video Games Europe · 2026
European Games Developer Federation · 2026
European Games Developer Federation · 2025
European Games Developer Federation · 2025
European Games Developer Federation · 2025
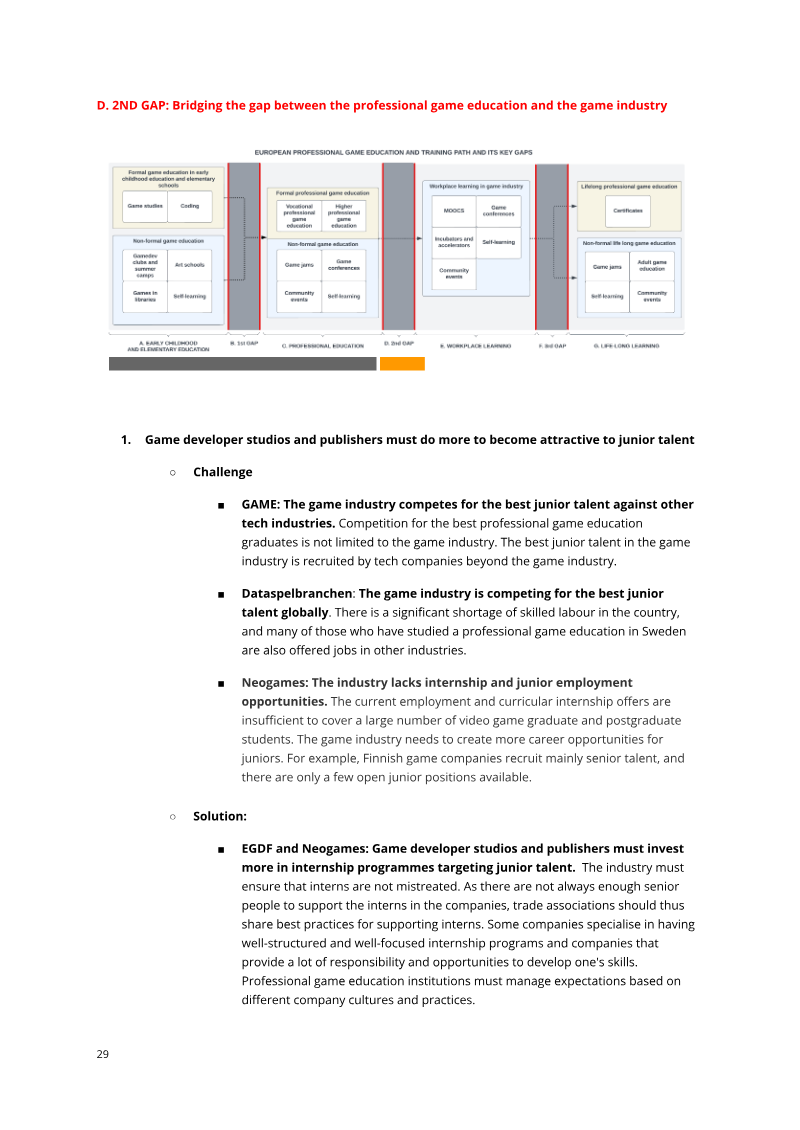
European Games Developer Federation · 2024
Neogames Finland · 2024
European Games Developer Federation · 2024
European Games Developer Federation · 2024
European Games Developer Federation · 2024
European Games Developer Federation · 2023
European Games Developer Federation · 2023
The Game Business · 2026