mixi
Game Co.74 documents
Documents
Financial22 pages
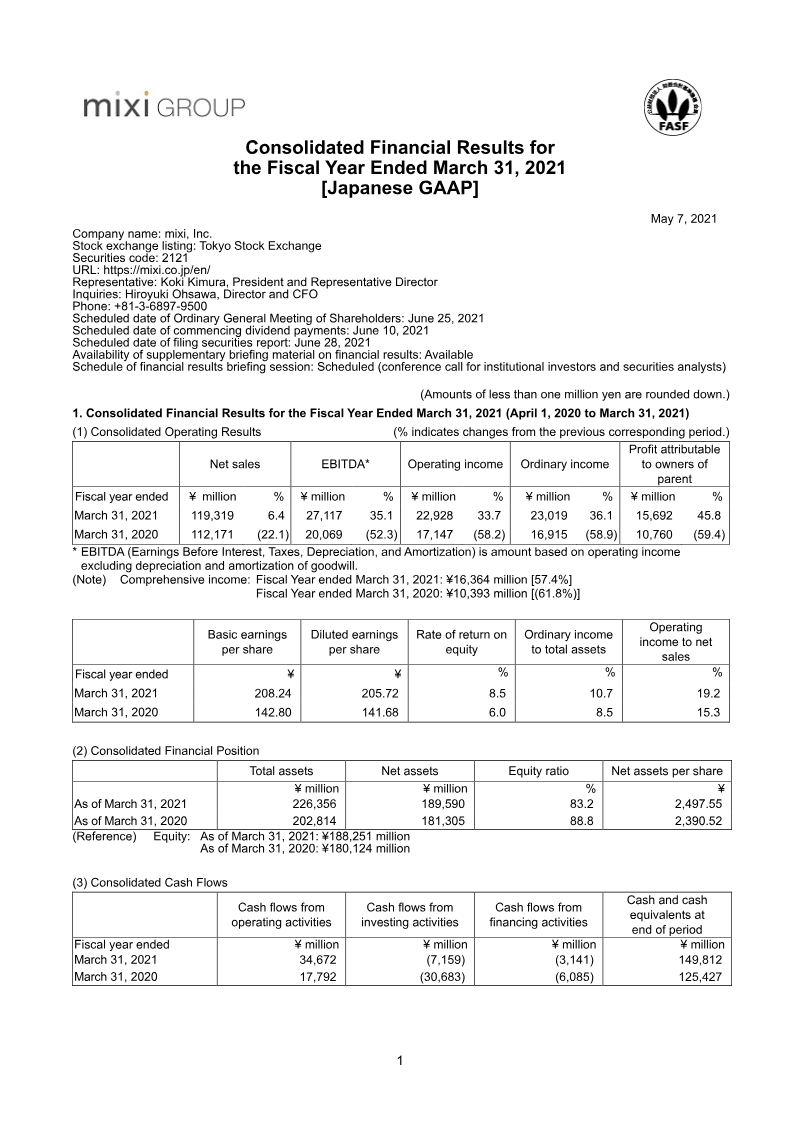
Consolidated Financial Results for the Fiscal Year Ended March 31, 2021
Mixi, Inc. achieved significant financial growth during the fiscal year ended March 31, 2021, characterized by a 6.4% increase in net sales to ¥119.3 billion and a substantial 45.8% rise in profit attributable to owners, totaling ¥15.6 billion. This performance was underpinned by a surge in net cash from operating activities, which nearly doubled to ¥34.7 billion. The company’s liquidity remains exceptionally strong, concluding the period with ¥149.8 billion in cash and cash equivalents. This robust capital position supported a stable dividend of ¥110 per share and the authorization of a ¥10 billion share repurchase program intended to enhance capital efficiency.
Strategic realignments and acquisitions defined the corporate landscape during this period. The group restructured its operations into three core segments: Digital Entertainment, Sports, and Lifestyle. Following the finalized accounting for acquisitions such as Chiba Jets Funabashi and Net Dreamers, the company reallocated significant costs toward customer-related intangible assets. Expansion into the sports and hospitality sectors continued post-period with the acquisition of a 20.02% stake in HUB CO., LTD. for approximately ¥1 billion, signaling a commitment to diversifying the portfolio beyond traditional digital gaming.
Despite the strong historical performance, the outlook for the 2022 fiscal year remains conservative. Projections indicate a potential contraction in profitability, with operating income and net profit forecasted to decline by as much as 47.7% and 45.8%, respectively. This cautious guidance suggests that while the company successfully navigated the previous year's market conditions and improved its cash flow through disciplined investing and operational growth, it anticipates significant headwinds or increased investment requirements that may impact short-term earnings.
- Mixi, Inc. reported a 6.4% increase in net sales to ¥119.3 billion and a 45.8% rise in profit attributable to owners to ¥15.6 billion for the fiscal year ended March 31, 2021.
- The company projects a significant contraction for fiscal year 2022, with forecasts indicating potential declines of 47.7% in operating income and 45.8% in net profit.
- Liquidity remains strong with ¥149.8 billion in cash and cash equivalents, supporting a ¥110 per share dividend and a ¥10 billion share repurchase program.
- Net cash from operating activities nearly doubled during the fiscal year, reaching ¥34.7 billion.
- The company restructured into three core segments—Digital Entertainment, Sports, and Lifestyle—and acquired a 20.02% stake in HUB CO., LTD. for approximately ¥1 billion to diversify beyond digital gaming.
+1
mixiMay 2021
Financial9 pages
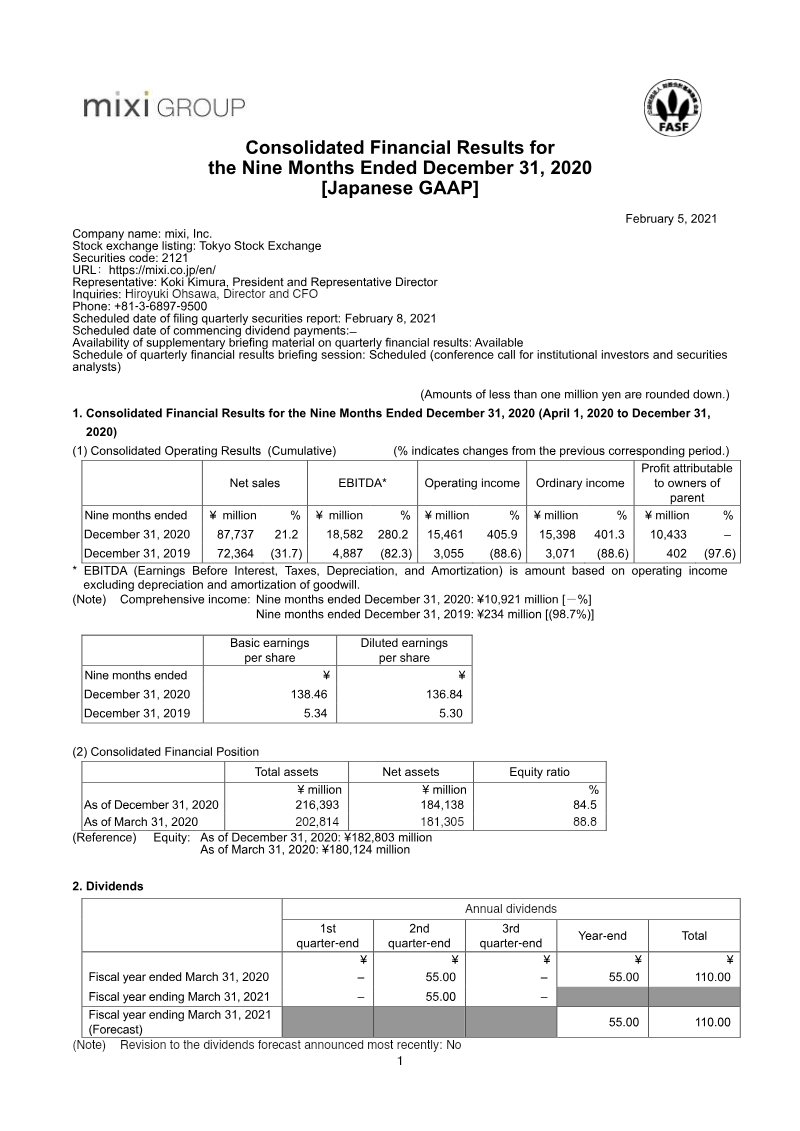
Consolidated Financial Results for the Nine Months Ended December 31, 2020
Mixi, Inc. reported significant growth in its consolidated financial results for the first nine months of the fiscal year ending March 31, 2021. Net sales reached ¥87,737 million, a 21.2% increase over the same period in the previous year. Profitability saw a substantial recovery, with operating income rising 405.9% to ¥15,461 million and profit attributable to owners of the parent reaching ¥10,433 million, compared to just ¥402 million in the prior year. This performance was driven largely by the Digital Entertainment Business, which generated ¥74,027 million in sales and ¥31,731 million in segment profit.
The company restructured its reporting segments during this period to reflect its evolving portfolio, now categorizing operations into Digital Entertainment, Sports, and Lifestyle businesses. While Digital Entertainment remains the primary profit driver, the Sports Business saw a significant revenue increase to ¥8,866 million, though it recorded a segment loss of ¥4,448 million. The Lifestyle Business neared break-even with a minor loss of ¥22 million on sales of ¥4,843 million. Financial stability remains high, with an equity ratio of 84.5% and cash and deposits increasing to ¥144,240 million.
The results also reflect the finalization of provisional accounting for the acquisitions of Chiba Jets Funabashi Co., Ltd. and Net Dreamers Co., Ltd. These adjustments led to a significant reallocation of acquisition costs from goodwill to customer-related intangible assets. Looking forward, the full-year forecast anticipates net sales of ¥120,000 million and a profit of ¥13,000 million. The company maintained its annual dividend forecast at ¥110 per share, signaling confidence in its cash flow and long-term financial position despite the inherent volatility of the entertainment sector.
- Mixi, Inc. reported a 21.2% year-over-year increase in net sales to ¥87,737 million for the nine months ended December 31, 2020.
- Operating income surged 405.9% to ¥15,461 million, while profit attributable to owners of the parent rose to ¥10,433 million from ¥402 million in the prior year.
- The Digital Entertainment Business remains the primary profit driver, contributing ¥74,027 million in sales and ¥31,731 million in segment profit.
- The Sports Business generated ¥8,866 million in revenue but recorded a segment loss of ¥4,448 million, while the Lifestyle Business neared break-even with a ¥22 million loss.
- The company maintains a strong financial position with an equity ratio of 84.5% and cash and deposits totaling ¥144,240 million.
+1
mixiFeb 2021

Financial9 pages
Consolidated Financial Results for the Six Months Ended September 30, 2020
These consolidated financial results for mixi, Inc. cover the six-month period ending September 30, 2020, providing a comprehensive overview of the company’s fiscal performance and segment reclassification. During this period, the company experienced significant growth, with net sales rising 25.4% to ¥58,752 million. Profitability saw a substantial surge compared to the previous year; operating income increased by 257.1% to ¥14,050 million, while profit attributable to owners of the parent grew by 334.3% to reach ¥9,333 million. This performance led to a revised full-year forecast, projecting annual net sales of ¥120,000 million and a 20.8% increase in annual profit.
The results highlight a strategic shift in business reporting, as the company redefined its segments into Digital Entertainment, Sports, and Lifestyle. The Digital Entertainment Business remains the primary revenue driver, contributing ¥51,438 million in sales and ¥24,840 million in segment profit. The Sports Business, which now includes five previously reclassified subsidiaries, saw a significant increase in scale with sales of ¥5,377 million, though it recorded a segment loss of ¥2,452 million. The Lifestyle Business remained relatively stable, contributing ¥1,936 million in sales.
Financially, the company maintains a strong position with total assets of ¥215,582 million and an equity ratio of 86.5%. Cash and deposits increased to ¥141,671 million, supported by ¥22,178 million in net cash provided by operating activities. The period also involved the finalization of provisional accounting for acquisitions, including Chiba Jets Funabashi Co., Ltd. and Net Dreamers Co., Ltd., which resulted in significant adjustments to intangible assets and a reduction in previously estimated goodwill. Dividends remained consistent with forecasts at ¥55.00 per share for the second quarter.
- Mixi, Inc. reported strong growth for the six months ending September 30, 2020, with net sales rising 25.4% to ¥58,752 million and operating income surging 257.1% to ¥14,050 million.
- Profit attributable to owners of the parent increased by 334.3% to ¥9,333 million, leading the company to revise its full-year net sales forecast to ¥120,000 million.
- The Digital Entertainment segment remains the primary revenue driver, generating ¥51,438 million in sales and ¥24,840 million in profit.
- The newly defined Sports Business, which now includes five reclassified subsidiaries such as Chiba Jets Funabashi Co., Ltd., recorded ¥5,377 million in sales but incurred a segment loss of ¥2,452 million.
- The company maintains a strong financial position with an equity ratio of 86.5% and cash and deposits totaling ¥141,671 million.
+1
mixiNov 2020
Financial9 pages
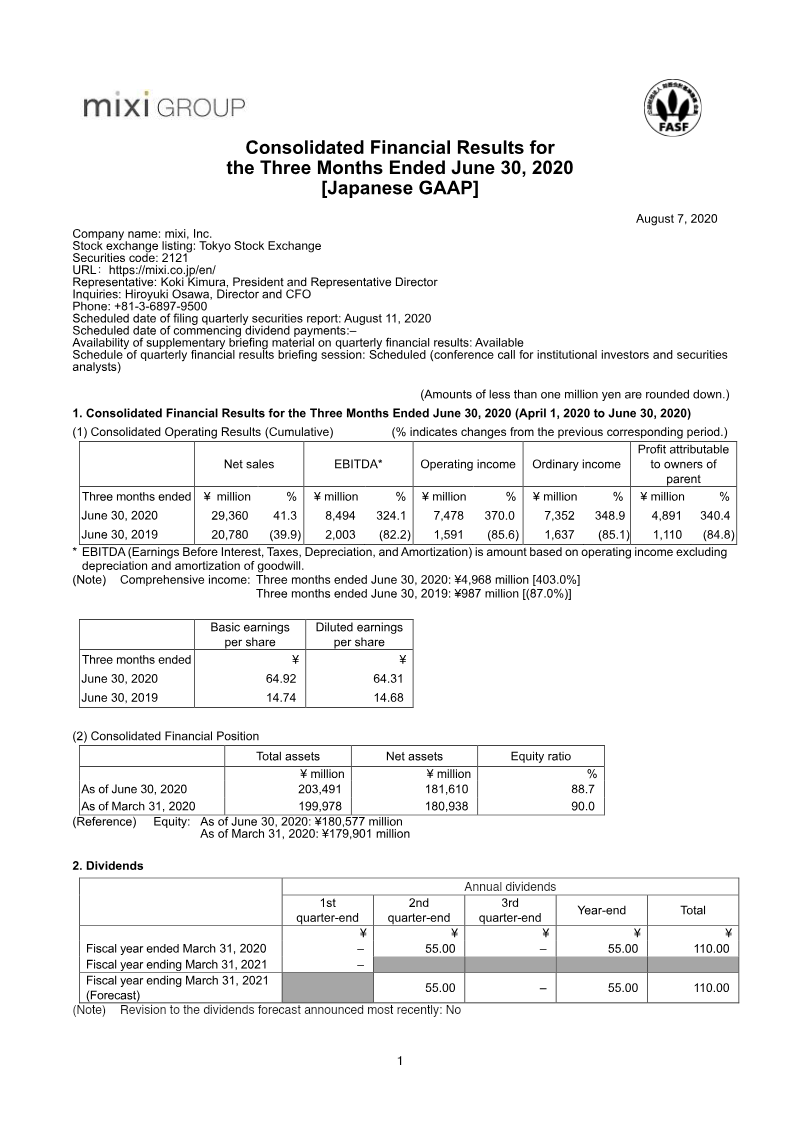
Consolidated Financial Results for the Three Months Ended June 30, 2020
This financial report details the consolidated results for mixi, Inc. during the first quarter of the fiscal year ending March 31, 2021, covering the period from April 1, 2020, to June 30, 2020. The data reveals a period of significant year-over-year growth, with net sales increasing 41.3% to ¥29,360 million. Profitability saw even more dramatic gains; operating income rose 370% to ¥7,478 million, while profit attributable to owners of the parent climbed 340.4% to ¥4,891 million. These results were achieved despite a global economic environment impacted by the COVID-19 pandemic.
The company’s performance is driven primarily by its Digital Entertainment Business, which contributed ¥25,997 million in net sales and ¥12,482 million in segment profit. During this period, the company restructured its reporting segments to better reflect its evolving portfolio, splitting its previous structure into Digital Entertainment, Sports, and Lifestyle businesses. While the Digital Entertainment segment remained the primary profit engine, the Sports Business and Lifestyle Business segments reported operating losses of ¥1,020 million and ¥306 million, respectively, as the company continued to invest in these areas.
The financial position remains robust, with total assets valued at ¥203,491 million and an equity ratio of 88.7%. Cash and deposits increased to ¥132,118 million, providing significant liquidity. Despite the strong first-quarter performance, the full-year forecast was revised to project a decline in annual net sales and profit compared to the previous fiscal year, with net sales estimated at ¥105,000 million. Subsequent to the quarter's end, the company announced the establishment of a ¥3,000 million investment fund focused on digital transformation in the live entertainment field, signaling a continued strategic shift toward technology-driven entertainment synergies.
- Mixi, Inc. reported strong Q1 growth for the period ending June 30, 2020, with net sales rising 41.3% to ¥29,360 million and operating income surging 370% to ¥7,478 million.
- The Digital Entertainment Business served as the primary profit engine, generating ¥25,997 million in net sales and ¥12,482 million in segment profit.
- The company restructured its reporting into three segments—Digital Entertainment, Sports, and Lifestyle—with the latter two reporting operating losses of ¥1,020 million and ¥306 million, respectively, due to ongoing investment.
- Despite the strong quarterly performance, management revised the full-year forecast downward, projecting annual net sales of ¥105,000 million, representing a decline compared to the previous fiscal year.
- The company maintains a robust financial position with an 88.7% equity ratio and ¥132,118 million in cash and deposits as of June 30, 2020.
+1
mixiAug 2020
Financial25 pages
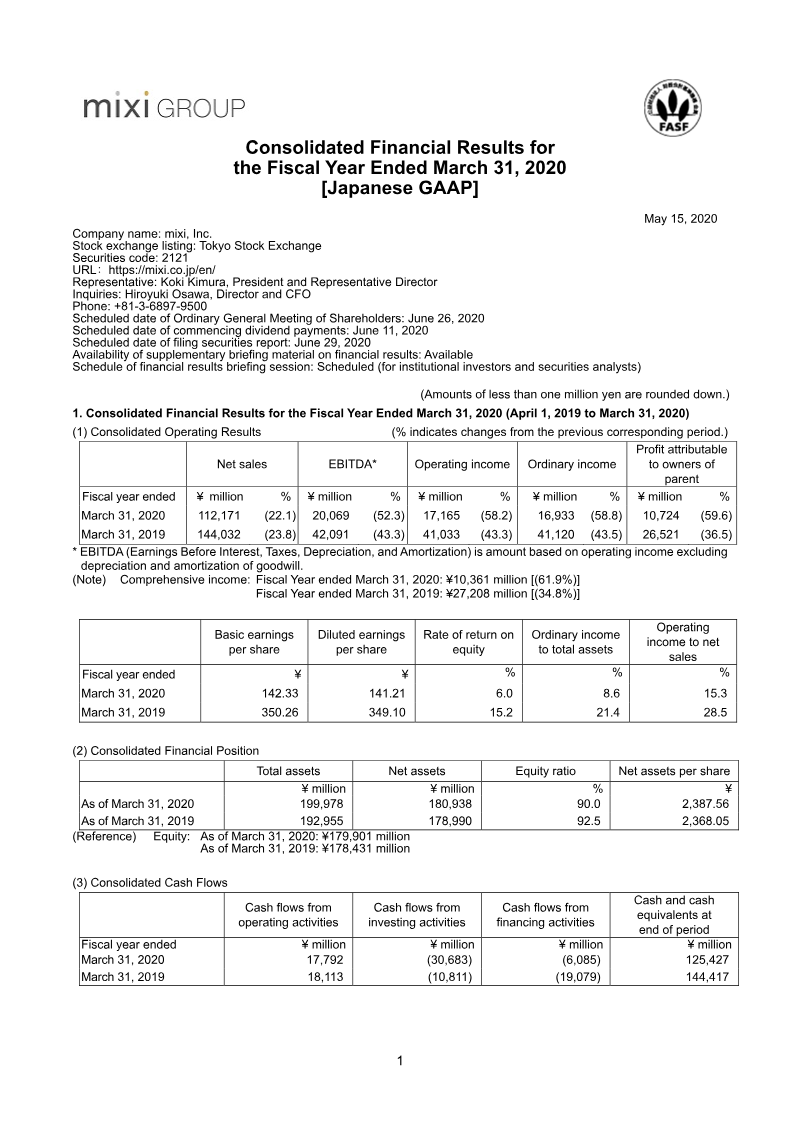
Consolidated Financial Results for the Fiscal Year Ended March 31, 2020
Mixi Group experienced a period of significant financial contraction and strategic transition during the fiscal year ended March 31, 2020. Net sales fell by 22.1% to ¥112,171 million, while profit attributable to owners of the parent plummeted by 59.6% to ¥10,724 million. This downturn was primarily driven by the Entertainment Business, where revenue dropped from ¥138,605 million to ¥107,216 million, causing basic earnings per share to decline from ¥350.26 to ¥142.33. Despite these challenges, the organization maintained a robust equity ratio of 90% and held ¥180,938 million in total net assets, signaling a stable capital base amidst declining operational performance.
The fiscal year was characterized by aggressive inorganic growth and diversification within the Japanese market, which accounts for over 90% of total sales and assets. Cash outflows for investing activities rose sharply to ¥30.7 billion, largely due to the acquisition of subsidiaries such as Chariloto Co., Ltd. and Net Dreamers Co., Ltd. The latter acquisition alone accounted for ¥15 billion, contributing to a substantial increase in unamortized goodwill, which reached ¥17,315 million. These investments reflect a strategic pivot toward integrating sports media and professional team management into the core portfolio, even as impairment losses were recorded in underperforming entertainment retail segments.
Looking toward the 2021 fiscal year, projections indicate continued pressure on the bottom line, with net sales expected to contract further to ¥100,000 million and profits forecasted to drop to ¥6,500 million. Cash and cash equivalents decreased by ¥19 billion during the period to end at ¥125.4 billion, yet the dividend policy remained steady at ¥115 to ¥120 per share. This financial trajectory highlights a company utilizing its significant cash reserves to fund a structural shift toward new lifestyle and entertainment segments while managing the diminishing returns of its legacy business lines.
- Mixi Group's fiscal year 2020 net sales fell 22.1% to ¥112,171 million, while profit attributable to owners of the parent dropped 59.6% to ¥10,724 million.
- The Entertainment Business drove the downturn, with segment revenue declining from ¥138,605 million to ¥107,216 million, resulting in basic earnings per share falling to ¥142.33.
- The company is aggressively diversifying through inorganic growth, spending ¥30.7 billion on investing activities including the acquisitions of Chariloto Co., Ltd. and Net Dreamers Co., Ltd.
- The acquisition of Net Dreamers Co., Ltd. cost ¥15 billion, contributing to a total unamortized goodwill balance of ¥17,315 million.
- Despite operational declines, the company maintains a stable capital base with a 90% equity ratio and ¥125.4 billion in cash and cash equivalents.
+2
mixiMay 2020
Financial10 pages
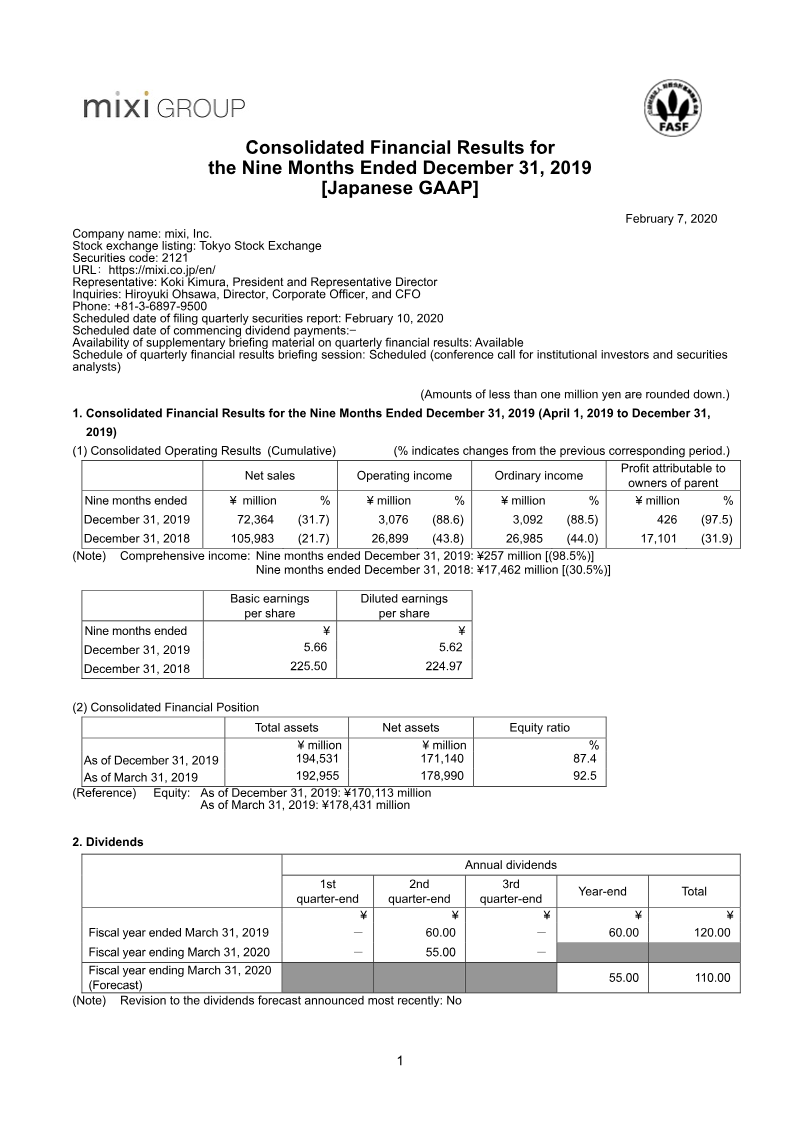
Consolidated Financial Results for the Nine Months Ended December 31, 2019
Mixi, Inc. reported a significant downturn in financial performance for the nine months ended December 31, 2019, characterized by a sharp contraction in both revenue and profitability. Net sales fell 31.7% year-over-year to ¥72,364 million, while operating income plummeted 88.6% to ¥3,076 million. Profit attributable to owners of the parent saw the most drastic decline, falling 97.5% to just ¥426 million. These results reflect a challenging period for the company’s core segments, particularly the Entertainment Business, where segment profit dropped from ¥34,297 million to ¥13,267 million.
The geographic scope of these results is centered on Japan, covering the first three quarters of the 2019 fiscal year. The data highlights a transition in corporate strategy, as the company aggressively pursued acquisitions to diversify its portfolio into the sports and sports betting industries. Key transactions during this period included the acquisition of Chiba Jets Funabashi Inc., a professional basketball team, for ¥1,019 million, and Net Dreamers Co., Ltd., a sports media operator, for ¥15,000 million. These moves contributed to a substantial increase in goodwill, which rose to ¥18,481 million by the end of the period.
Despite the current earnings pressure, the company maintains a strong consolidated financial position with total assets of ¥194,531 million and an equity ratio of 87.4%. Cash and deposits remained substantial at ¥124,196 million, though this was a decrease from the previous year-end due to investment activities and dividend payments. Looking ahead, the full-year forecast was revised downward, with net sales expected to reach ¥103,000 million and profit attributable to owners of the parent projected at ¥4,000 million, representing an 84.9% decrease from the prior fiscal year.
- Mixi, Inc. experienced a severe financial downturn for the nine months ended December 31, 2019, with net sales falling 31.7% to ¥72,364 million and operating income plummeting 88.6% to ¥3,076 million.
- Profit attributable to owners of the parent dropped 97.5% year-over-year to ¥426 million, reflecting significant earnings pressure in the core Entertainment Business segment.
- The company is aggressively pivoting toward sports and sports betting, evidenced by the ¥15,000 million acquisition of Net Dreamers Co., Ltd. and the ¥1,019 million purchase of Chiba Jets Funabashi Inc.
- Full-year projections have been revised downward, with expected profit attributable to owners of the parent now forecasted at ¥4,000 million, an 84.9% decrease from the prior fiscal year.
- Despite declining earnings, the company maintains a robust balance sheet with total assets of ¥194,531 million, an equity ratio of 87.4%, and cash reserves of ¥124,196 million.
+1
mixiFeb 2020
Financial8 pages
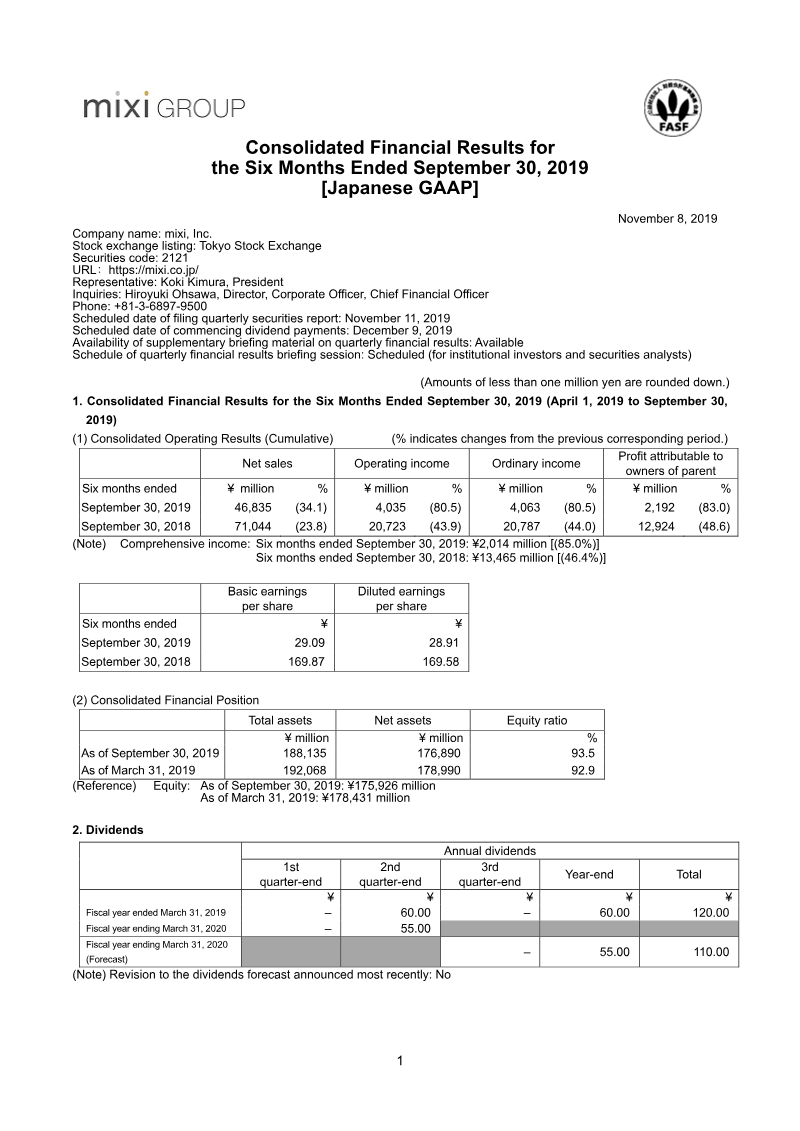
Consolidated Financial Results for the Six Months Ended September 30, 2019
These consolidated financial results for mixi, Inc. cover the six-month period ending September 30, 2019. The data reveals a significant year-over-year contraction in financial performance across all primary metrics. Net sales fell by 34.1% to ¥46,835 million, while operating income and ordinary income both saw a sharp decline of 80.5%, dropping to approximately ¥4,035 million and ¥4,063 million, respectively. Profit attributable to owners of the parent decreased by 83.0% to ¥2,192 million, resulting in basic earnings per share of ¥29.09, down from ¥169.87 in the previous year.
The company’s operations are divided into two reportable segments: Entertainment and Lifestyle. The Entertainment Business remains the primary revenue driver, contributing ¥45,137 million in sales, though its segment profit fell from ¥25,421 million to ¥9,724 million year-over-year. The Lifestyle Business reported a segment loss of ¥439 million on sales of ¥1,697 million. Despite the downturn in earnings, the company maintains a strong financial position with total assets of ¥188,135 million and a high equity ratio of 93.5%. Cash and deposits remain substantial at ¥142,693 million.
The full-year forecast for the fiscal year ending March 31, 2020, anticipates continued downward pressure, with net sales projected at ¥100,000 million and profit attributable to owners expected to reach ¥3,000 million. These projections represent an anticipated annual decrease of over 80% in profitability compared to the prior fiscal year. Cash flow analysis indicates that while operating activities generated ¥8,537 million, significant outflows occurred in investing activities, including ¥1,469 million for subsidiary acquisitions and ¥1,856 million for investment securities, reflecting ongoing efforts to diversify the portfolio despite the current decline in core segment performance.
- Mixi, Inc. experienced a significant financial contraction for the six months ending September 30, 2019, with net sales falling 34.1% to ¥46,835 million and operating income dropping 80.5% to ¥4,035 million.
- Profit attributable to owners of the parent plummeted 83.0% to ¥2,192 million, causing basic earnings per share to decline from ¥169.87 in the previous year to ¥29.09.
- The Entertainment Business remains the company's primary revenue driver at ¥45,137 million, yet its segment profit saw a sharp year-over-year decrease from ¥25,421 million to ¥9,724 million.
- The Lifestyle Business segment reported a loss of ¥439 million on sales of ¥1,697 million, contributing to the overall downward trend in company performance.
- Full-year projections for the fiscal year ending March 31, 2020, anticipate continued decline, with profit attributable to owners expected to reach ¥3,000 million, representing an annual decrease of over 80%.
+2
mixiNov 2019
Financial10 pages
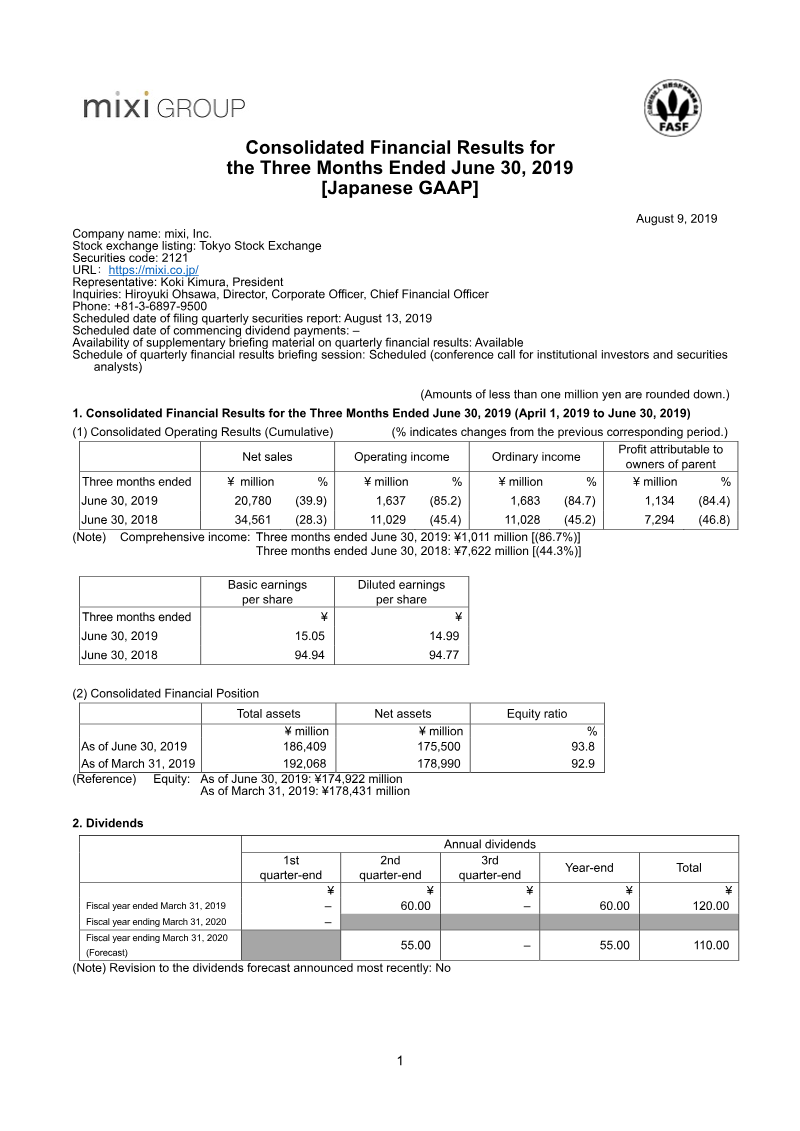
Consolidated Financial Results for the Three Months Ended June 30, 2019
This financial report details the consolidated results for mixi, Inc. during the first quarter of the fiscal year ending March 31, 2020, covering the period from April 1, 2019, to June 30, 2019. The data reveals a significant year-over-year downturn across all primary financial metrics. Net sales fell by 39.9% to ¥20,780 million, while operating income saw a sharp decline of 85.2%, dropping to ¥1,637 million. Profit attributable to owners of the parent followed a similar trajectory, decreasing 84.4% to ¥1,134 million.
The downturn is primarily driven by the Entertainment Business segment, which saw sales contract from ¥32,709 million in the previous year's first quarter to ¥19,969 million. The Lifestyle Business also experienced a decline in revenue and recorded a segment loss of ¥272 million. Despite these operational challenges, the company maintains a robust financial position with total assets of ¥186,409 million and a high equity ratio of 93.8%. Cash and deposits remain substantial at ¥138,393 million, though this represents a decrease from the previous fiscal year-end.
A key strategic development during this period was the 100% acquisition of SFIDANTE Inc. for ¥1,599 million. This move aims to integrate SFIDANTE’s smartphone-photo print services with mixi’s "FamilyAlbum" app to enhance family-oriented communication offerings. The acquisition resulted in the recognition of approximately ¥1,504 million in provisional goodwill.
Looking ahead, the full-year forecast remains cautious, projecting net sales of ¥100,000 million and a profit of ¥3,000 million, representing anticipated annual declines of 30.6% and 88.7%, respectively. To align leadership interests with shareholder value during this transition, the company also authorized the granting of over 400,000 stock options to directors and corporate officers in July 2019.
- Mixi, Inc. experienced a significant Q1 fiscal 2020 downturn, with net sales dropping 39.9% to ¥20,780 million and operating income falling 85.2% to ¥1,637 million compared to the previous year.
- The Entertainment Business segment was the primary driver of the decline, with revenue contracting from ¥32,709 million to ¥19,969 million year-over-year.
- The company projects a difficult full fiscal year, forecasting a 30.6% decline in net sales to ¥100,000 million and an 88.7% drop in profit to ¥3,000 million.
- Despite operational losses, the company maintains a strong balance sheet with ¥138,393 million in cash and deposits and a high equity ratio of 93.8%.
- Mixi acquired SFIDANTE Inc. for ¥1,599 million in Q1 to integrate smartphone-photo print services into its 'FamilyAlbum' app, resulting in ¥1,504 million of provisional goodwill.
+1
mixiAug 2019

Financial23 pages
Consolidated Financial Results for the Fiscal Year Ended March 31, 2019
Mixi, Inc. experienced a significant contraction during the fiscal year ended March 31, 2019, characterized by a 23.8% decline in net sales to ¥144,032 million and a 36.5% drop in profit attributable to owners to ¥26,521 million. Operating income fell by 43.3%, largely due to a downturn in the core Entertainment Business, which includes the flagship title Monster Strike. This downward trend is expected to persist, with forecasts predicting a further 30.6% decrease in net sales for the upcoming fiscal year. Despite these challenges, the firm maintains a robust financial foundation, evidenced by a 92.9% equity ratio and a commitment to shareholder returns through ¥120 per share in dividends and ¥10.1 billion in treasury share purchases.
Strategic restructuring defined the period as the organization sought to pivot away from underperforming assets and toward new growth sectors. The company divested from subsidiaries Diverse, Inc. and nohana, Inc., withdrew from its telecommunications-related business, and absorbed the impact of closing the Ticket Camp service, which involved a substantial extraordinary loss. To diversify its portfolio, the firm acquired Chariloto Co., Ltd. for ¥5,000 million, signaling an expansion into sports entertainment and the keirin betting market. This shift was accompanied by a reclassification of reporting segments into Entertainment and Lifestyle to better align with long-term digital service goals.
Cash flow dynamics reflected the broader operational slowdown, with net cash from operating activities falling from ¥49,975 million to ¥18,113 million. While basic earnings per share decreased from ¥533.48 to ¥350.26, net assets per share grew to ¥2,368.05. The organization enters the next fiscal cycle with a focus on stabilizing its core gaming assets while integrating new sports-related acquisitions to offset the volatility of its traditional entertainment offerings.
- Mixi, Inc. reported a significant fiscal decline for the year ended March 31, 2019, with net sales falling 23.8% to ¥144,032 million and operating income dropping 43.3%.
- The company forecasts a continued downward trend for the upcoming fiscal year, projecting a further 30.6% decrease in net sales.
- Performance was heavily impacted by a downturn in the core Entertainment Business, specifically the flagship title Monster Strike, leading to a 36.5% decline in profit attributable to owners to ¥26,521 million.
- Strategic restructuring included divesting from subsidiaries Diverse, Inc. and nohana, Inc., closing the Ticket Camp service, and withdrawing from telecommunications to focus on new growth sectors.
- Mixi expanded into sports entertainment and the keirin betting market by acquiring Chariloto Co., Ltd. for ¥5,000 million to diversify its portfolio beyond traditional gaming.
+1
mixiMay 2019
Financial10 pages
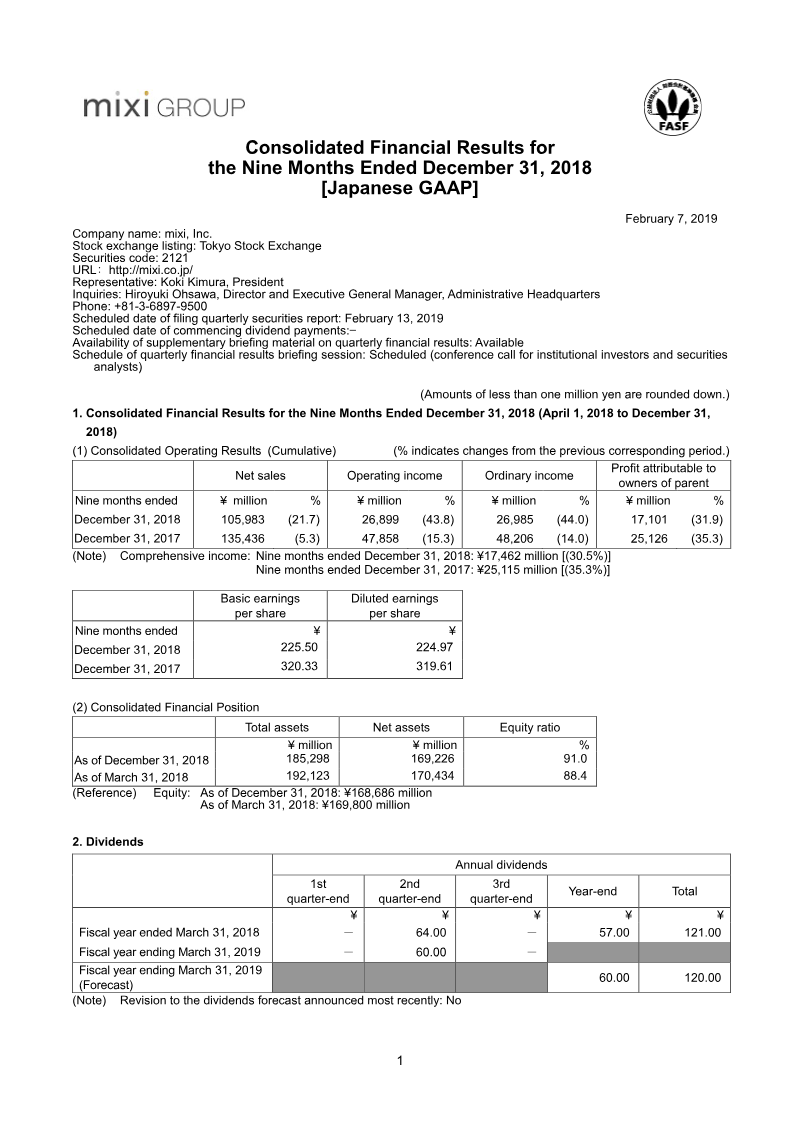
Consolidated Financial Results for the Nine Months Ended December 31, 2018
Mixi, Inc. reported a significant decline in financial performance for the nine-month period ending December 31, 2018, compared to the same period in the previous year. Net sales fell by 21.7% to ¥105,983 million, while operating income and ordinary income both dropped by approximately 44%, reaching ¥26,899 million and ¥26,985 million, respectively. Profit attributable to owners of the parent decreased by 31.9% to ¥17,101 million. These results reflect a downturn in the company’s core business segments and include a ¥2,018 million extraordinary loss related to business withdrawals.
The Entertainment Business remains the primary revenue driver, contributing ¥101,590 million in sales, though this represents a decrease from the ¥124,559 million generated in the prior year. The Lifestyle Business, formerly part of the Media Platform segment, saw a sharper decline, with sales falling from ¥10,876 million to ¥4,393 million. This segment also recorded a loss of ¥1,245 million, exacerbated by the previous year's decision to shut down the Ticket Camp service, which resulted in a total goodwill amortization of ¥7,597 million.
Despite the decline in earnings, the company maintains a strong financial position with an equity ratio of 91.0% and total assets of ¥185,298 million. Cash and cash equivalents stood at ¥140,880 million at the end of the period, following significant outflows for treasury share repurchases totaling over ¥10,000 million and dividend payments of ¥7,991 million. For the full fiscal year ending March 31, 2019, the company forecasts net sales of ¥155,000 million and a 35.4% decrease in annual profit compared to the previous fiscal year.
- Mixi, Inc. experienced a significant financial downturn for the nine months ending December 31, 2018, with net sales falling 21.7% to ¥105,983 million and operating income dropping 44% to ¥26,899 million.
- Profit attributable to owners of the parent declined by 31.9% to ¥17,101 million, impacted by a ¥2,018 million extraordinary loss related to business withdrawals.
- The core Entertainment Business saw revenue decrease to ¥101,590 million, down from ¥124,559 million in the same period the previous year.
- The Lifestyle Business segment suffered a sharp decline, with sales dropping from ¥10,876 million to ¥4,393 million and recording a loss of ¥1,245 million, largely due to the shutdown of the Ticket Camp service.
- Despite the earnings decline, the company maintains a strong financial position with an equity ratio of 91.0% and cash and cash equivalents totaling ¥140,880 million.
+1
mixiFeb 2019
Financial9 pages
Consolidated Financial Results for the Six Months Ended September 30, 2018
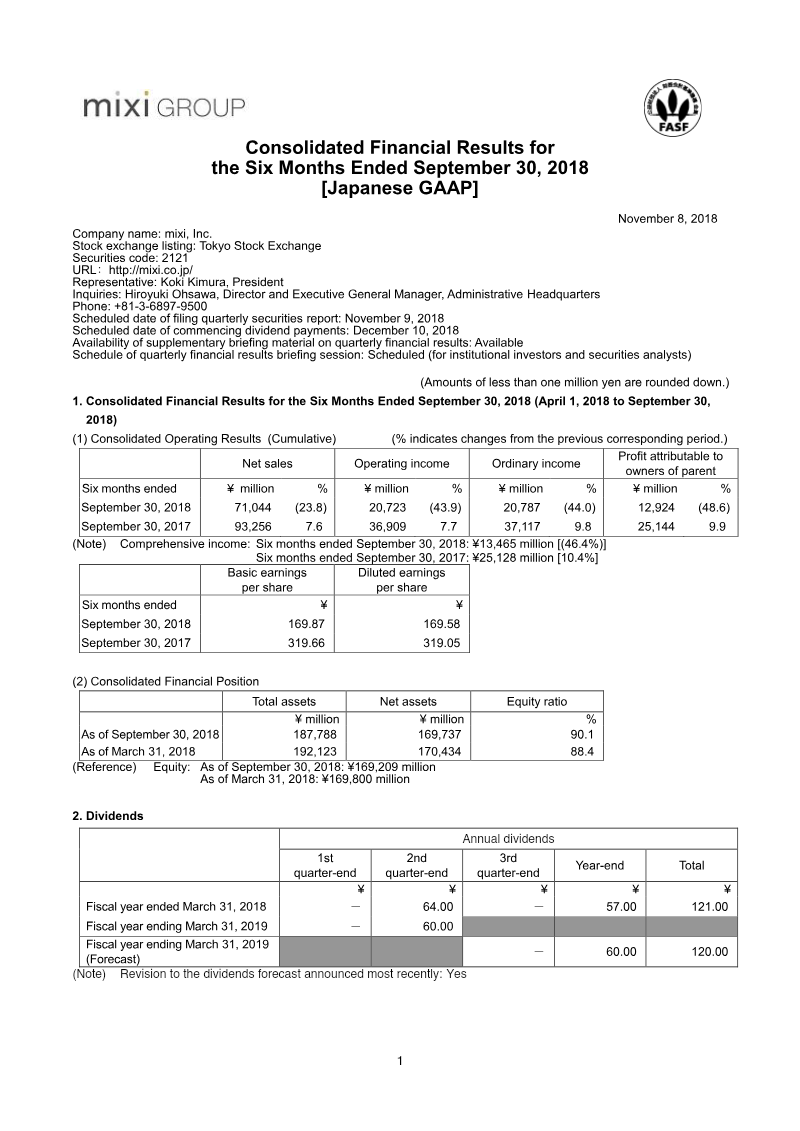
These consolidated financial results for mixi, Inc. cover the six-month period ending September 30, 2018. The data reveals a significant year-over-year downturn in financial performance across all primary metrics. Net sales decreased by 23.8% to ¥71,044 million, while operating income fell 43.9% to ¥20,723 million. Profit attributable to owners of the parent saw the sharpest decline, dropping 48.6% to ¥12,924 million compared to the same period in 2017.
The company’s operations are divided into two primary reportable segments: Entertainment and Lifestyle. The Entertainment Business remains the dominant revenue driver, contributing ¥68,044 million in sales, though this represents a decrease from the ¥86,252 million recorded in the previous year. The Lifestyle Business saw a more drastic contraction, with sales falling from ¥7,003 million to ¥3,000 million, resulting in a segment loss of ¥815 million. This decline is partially attributed to a loss on business withdrawal totaling ¥2,018 million recorded as an extraordinary loss.
Despite the reduction in earnings, the company maintains a strong financial position with total assets of ¥187,788 million and an equity ratio of 90.1%. Cash and deposits remain high at ¥147,921 million. Significant capital activity during the period included the repurchase of 2,795,800 treasury shares, valued at approximately ¥9,455 million.
Looking ahead, the full-year forecast for the fiscal year ending March 31, 2019, has been revised downward. The company expects annual net sales of ¥155,000 million and a 42% decrease in operating income compared to the previous fiscal year. Dividends are projected at ¥120 per share for the full year, a slight decrease from the ¥121 paid in the prior period. These results were prepared under Japanese GAAP and have not been subject to a full quarterly review by an external audit firm.
- Mixi, Inc. reported a significant year-over-year downturn for the six months ending September 30, 2018, with net sales falling 23.8% to ¥71,044 million and operating income dropping 43.9% to ¥20,723 million.
- Profit attributable to owners of the parent declined by 48.6% to ¥12,924 million compared to the same period in 2017.
- The Entertainment Business remains the primary revenue driver at ¥68,044 million, while the Lifestyle Business contracted sharply to ¥3,000 million in sales and incurred a segment loss of ¥815 million.
- The company revised its full-year forecast for the fiscal year ending March 31, 2019, downward, now projecting a 42% decrease in operating income compared to the previous fiscal year.
- Despite the earnings decline, the company maintains a robust financial position with an equity ratio of 90.1% and ¥147,921 million in cash and deposits.
+1
mixiNov 2018

Financial9 pages
Consolidated Financial Results for the Three Months Ended June 30, 2018
Mixi, Inc. reported a significant decline in financial performance for the first quarter of fiscal year 2019, covering the three-month period ended June 30, 2018. Net sales fell by 28.3% year-over-year to ¥34,561 million, while operating income dropped 45.4% to ¥11,029 million. Profit attributable to owners of the parent followed a similar downward trend, decreasing 46.8% to ¥7,294 million. Despite these contractions, the company maintained a strong financial position with an equity ratio of 91.2% and total assets of ¥178,800 million.
The results reflect a transition in the company’s business portfolio, marked by a reclassification of reportable segments into Entertainment and Lifestyle businesses. The Entertainment segment remains the primary revenue driver, contributing ¥32,709 million in sales, though this represents a sharp decline from the ¥44,981 million generated in the same period the previous year. The Lifestyle segment recorded a loss of ¥424 million on sales of ¥1,851 million. Cash flow data indicates a substantial increase in treasury share repurchases, totaling approximately ¥10,000 million during the quarter, which contributed to a decrease in cash and deposits.
Looking ahead, the full-year forecast for the period ending March 31, 2019, anticipates continued pressure on margins. Annual net sales are projected at ¥175,000 million, a 7.5% decrease from the prior year, with operating income expected to fall by 33.7% to ¥48,000 million. To align executive interests with shareholder value during this period, the company resolved to issue share remuneration-type stock options to its directors. The financial data was prepared in accordance with Japanese GAAP and underwent internal review prior to its release to institutional investors and analysts on the Tokyo Stock Exchange.
- Mixi, Inc. reported a significant Q1 FY2019 downturn, with net sales falling 28.3% year-over-year to ¥34,561 million and operating income dropping 45.4% to ¥11,029 million.
- Profit attributable to owners of the parent declined by 46.8% to ¥7,294 million for the three-month period ended June 30, 2018.
- The Entertainment segment remains the primary revenue driver at ¥32,709 million, though this represents a sharp decrease from the ¥44,981 million recorded in the same period the previous year.
- The company’s full-year forecast for the period ending March 31, 2019, projects a 7.5% decrease in annual net sales to ¥175,000 million and a 33.7% drop in operating income to ¥48,000 million.
- Despite declining performance, the company maintains a strong financial position with an equity ratio of 91.2% and total assets of ¥178,800 million.
+1
mixiAug 2018