mixi
Game Co.74 documents
Documents

Financial5 pages
Consolidated Balance Sheets (FY2017)
The consolidated financial results for the fiscal year ending March 31, 2018, reveal a period of significant asset growth contrasted with declining profitability. Total assets increased from ¥176.9 billion to ¥192.1 billion, driven largely by a rise in cash and deposits, which reached ¥156.2 billion. However, net sales fell from ¥207.2 billion in the previous year to ¥189.1 billion. This contraction in revenue, combined with relatively stagnant selling and administrative expenses, resulted in operating profit dropping from ¥89.0 billion to ¥72.4 billion.
Profitability was further impacted by substantial extraordinary losses, most notably a ¥7.6 billion amortization of goodwill that reduced intangible assets to near zero. Consequently, profit attributable to owners of the parent fell by approximately 30%, ending at ¥41.8 billion compared to ¥59.9 billion in the prior fiscal year. Despite lower net income, the financial position remains liquid, with total liabilities decreasing to ¥21.7 billion and net assets rising to ¥170.4 billion.
Cash flow analysis indicates robust operational health, as net cash provided by operating activities grew to ¥50.0 billion, up from ¥41.3 billion. This was supported by a significant reduction in income taxes paid. The organization continued aggressive shareholder return and capital restructuring strategies, including the purchase of ¥10.0 billion in treasury shares and the payment of ¥12.2 billion in dividends. Investment activities focused on property, plant, and equipment, as well as guarantee deposits, while the overall cash position strengthened by over ¥21.9 billion during the period.
- Profit attributable to owners of the parent declined by approximately 30%, falling from ¥59.9 billion in the previous fiscal year to ¥41.8 billion for the year ending March 31, 2018.
- Net sales contracted to ¥189.1 billion from ¥207.2 billion, leading to a decrease in operating profit from ¥89.0 billion to ¥72.4 billion.
- The company recorded a ¥7.6 billion extraordinary loss due to the amortization of goodwill, which effectively reduced intangible assets to near zero.
- Total assets grew to ¥192.1 billion from ¥176.9 billion, supported by a strong cash and deposits position that reached ¥156.2 billion.
- Net cash provided by operating activities increased to ¥50.0 billion from ¥41.3 billion, bolstered by a reduction in income taxes paid.
+1
mixiMay 2018
Financial9 pages
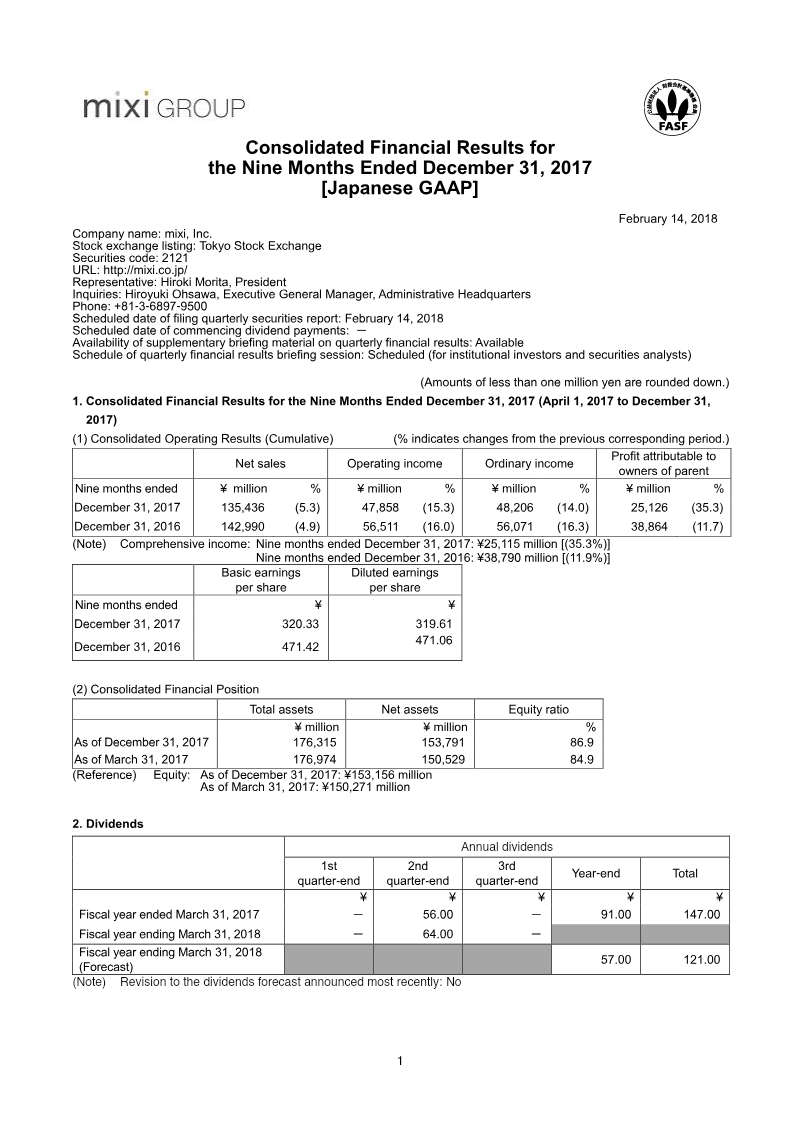
Consolidated Financial Results for the Nine Months Ended December 31, 2017
Mixi, Inc. reported consolidated financial results for the first nine months of the fiscal year ending March 31, 2018, reflecting a period of contraction compared to the previous year. Net sales reached ¥135.4 billion, a 5.3% decrease, while operating income fell 15.3% to ¥47.8 billion. The most significant decline was observed in profit attributable to owners of the parent, which dropped 35.3% to ¥25.1 billion. This sharp decrease in net profit was largely driven by a substantial extraordinary loss of ¥7.59 billion related to the full amortization of goodwill for the Ticket Camp service.
The company’s operations are divided into two primary segments: the Entertainment Business and the Media Platform Business. The Entertainment Business remains the dominant revenue driver, contributing ¥124.5 billion in sales, though this was down from ¥131.8 billion in the prior year. The Media Platform Business saw a slight decline in sales to ¥10.8 billion. A critical development during the third quarter was the decision to terminate the Ticket Camp service operated by subsidiary Hunza, Inc., resulting in the aforementioned goodwill amortization and an additional impairment loss of ¥131 million.
Despite the decline in profitability, the financial position remains stable with an equity ratio of 86.9% and total assets of ¥176.3 billion. Cash and cash equivalents increased to ¥136.7 billion, supported by strong net cash provided by operating activities. The company maintained its full-year forecast, projecting net sales of ¥200 billion and a profit of ¥40.2 billion. Dividend forecasts were also reaffirmed, with a planned total annual dividend of ¥121.00 per share, reflecting a commitment to shareholder returns despite the non-recurring losses associated with the closure of the Ticket Camp platform.
- Mixi, Inc. reported a 35.3% decline in profit attributable to owners of the parent to ¥25.1 billion for the nine months ended December 31, 2017, largely due to a ¥7.59 billion extraordinary loss from the full amortization of goodwill for Ticket Camp.
- Consolidated net sales fell 5.3% to ¥135.4 billion, while operating income decreased 15.3% to ¥47.8 billion compared to the same period in the previous fiscal year.
- The Entertainment Business remains the primary revenue driver, contributing ¥124.5 billion in sales, though this represents a decline from the ¥131.8 billion generated in the prior year.
- The company terminated the Ticket Camp service operated by subsidiary Hunza, Inc. during the third quarter, incurring an additional impairment loss of ¥131 million alongside the goodwill amortization.
- Despite the profit contraction, Mixi maintains a stable financial position with an equity ratio of 86.9% and cash and cash equivalents totaling ¥136.7 billion.
+1
mixiFeb 2018
Financial8 pages
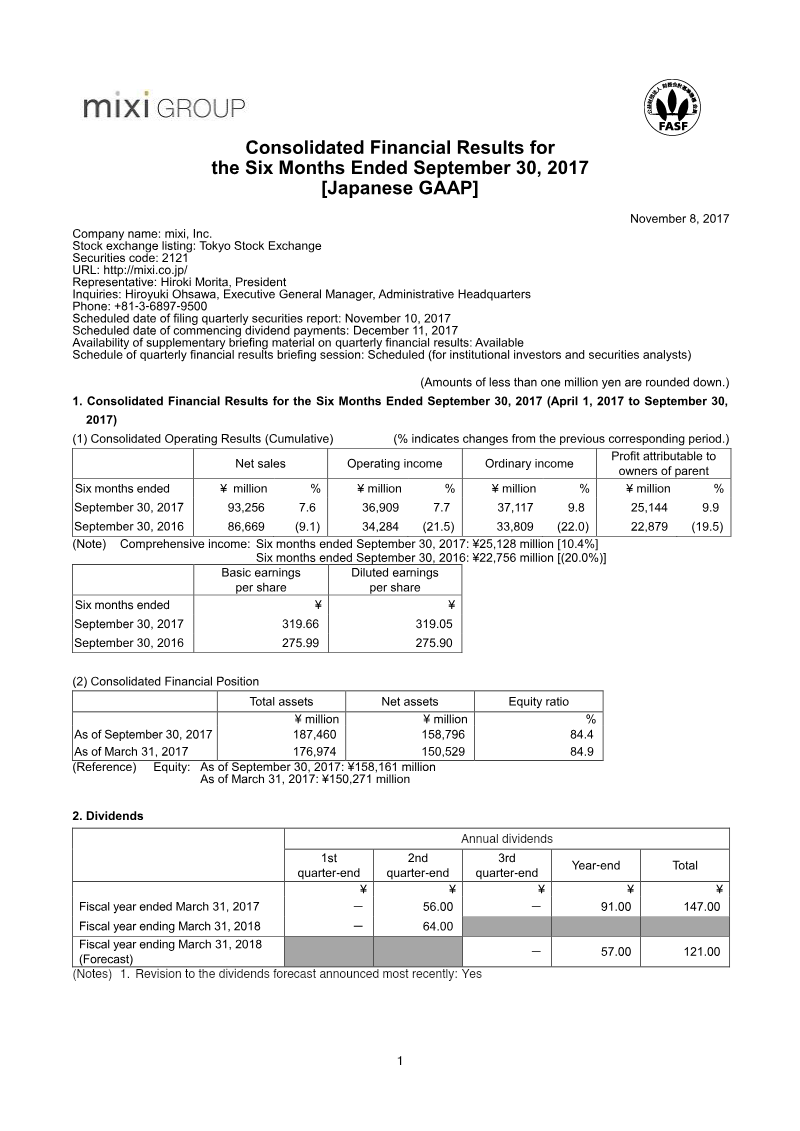
Consolidated Financial Results for the Six Months Ended September 30, 2017
Mixi, Inc. reported consolidated financial results for the first half of the fiscal year ending March 31, 2018, covering the period from April 1, 2017, to September 30, 2017. During this six-month window, the company experienced growth across all primary financial metrics compared to the previous year. Net sales rose 7.6% to ¥93,256 million, while operating income increased 7.7% to ¥36,909 million. Profit attributable to owners of the parent reached ¥25,144 million, representing a 9.9% year-over-year increase. The company maintained a strong financial position with an equity ratio of 84.4% and total assets valued at ¥187,460 million.
Performance was driven largely by the Entertainment Business segment, which accounted for ¥86,252 million in external sales and ¥39,087 million in segment profit. The Media Platform Business contributed ¥7,003 million in sales and ¥1,675 million in profit. Despite the positive mid-year results, the full-year forecast suggests a conservative outlook, with anticipated declines in annual net sales and operating income of 3.5% and 21.4%, respectively. This outlook factors in rising selling, general, and administrative expenses, including costs associated with the planned relocation of the head office to Shibuya Scramble Square scheduled for 2019.
Strategic financial activities during the period included significant treasury share transactions, including the retirement of over 3.6 million shares and the repurchase of 1.5 million shares. Cash flow remains robust, with net cash provided by operating activities increasing significantly to ¥29,553 million. The company also revised its dividend forecast, projecting a total annual dividend of ¥121.00 per share. These results, prepared under Japanese GAAP, reflect a period of operational stability and strategic consolidation as the company prepares for future infrastructure changes and business expansion.
- Mixi, Inc. reported strong H1 growth for the fiscal year ending March 31, 2018, with net sales rising 7.6% to ¥93,256 million and operating income increasing 7.7% to ¥36,909 million.
- The Entertainment Business segment remains the primary driver of performance, generating ¥86,252 million in external sales and ¥39,087 million in segment profit.
- Despite positive mid-year results, the company projects a conservative full-year outlook with anticipated declines in annual net sales of 3.5% and operating income of 21.4%.
- The forecasted decline in annual profitability is attributed to rising SG&A expenses, including costs related to the company's planned 2019 head office relocation to Shibuya Scramble Square.
- Profit attributable to owners of the parent grew 9.9% year-over-year to ¥25,144 million, supported by robust operating cash flow of ¥29,553 million.
+1
mixiNov 2017

Financial9 pages
Consolidated Financial Results for the Three Months Ended June 30, 2017
This financial report details the consolidated results for mixi, Inc. during the first quarter of the fiscal year ending March 31, 2018, covering the period from April 1 to June 30, 2017. The data reveals a period of stable performance with slight year-over-year growth. Net sales reached ¥48,229 million, representing a 1.9% increase compared to the same period in the previous year. Operating income and ordinary income also saw marginal gains, rising to ¥20,209 million and ¥20,130 million respectively. Profit attributable to owners of the parent grew by 1.0% to ¥13,713 million, resulting in basic earnings per share of ¥172.95.
The company’s operations are divided into two primary segments: the Entertainment Business and the Media Platform Business. The Entertainment Business remains the dominant revenue driver, contributing ¥44,981 million in net sales and ¥21,081 million in segment profit. In contrast, the Media Platform Business generated ¥3,247 million in sales and ¥817 million in profit. Despite the steady quarterly performance, the full-year forecast suggests a more conservative outlook, with anticipated declines in net sales (down 3.5%) and operating income (down 21.4%) by the end of the fiscal year in March 2018.
Strategic financial management during the quarter focused heavily on shareholder returns and capital efficiency. The company executed significant treasury share repurchases, totaling over 1.5 million shares for approximately ¥10 billion between May and July 2017. Furthermore, the Board of Directors resolved to retire 1,447,200 treasury shares in August 2017 and approved the issuance of share remuneration-type stock options for directors. The company maintains a strong financial position with an equity ratio of 85.7% and total assets valued at ¥175,816 million as of June 30, 2017.
- Mixi, Inc. reported stable Q1 FY2018 results with net sales of ¥48,229 million, a 1.9% year-over-year increase, and profit attributable to owners of the parent of ¥13,713 million.
- The Entertainment Business remains the primary revenue driver, generating ¥44,981 million in sales and ¥21,081 million in segment profit, significantly outperforming the Media Platform Business.
- Despite a steady first quarter, the company projects a conservative full-year outlook with anticipated declines of 3.5% in net sales and 21.4% in operating income by March 2018.
- The company maintains a strong balance sheet with an equity ratio of 85.7% and total assets valued at ¥175,816 million as of June 30, 2017.
- Between May and July 2017, Mixi executed treasury share repurchases totaling over 1.5 million shares for approximately ¥10 billion.
+1
mixiAug 2017
Financial22 pages
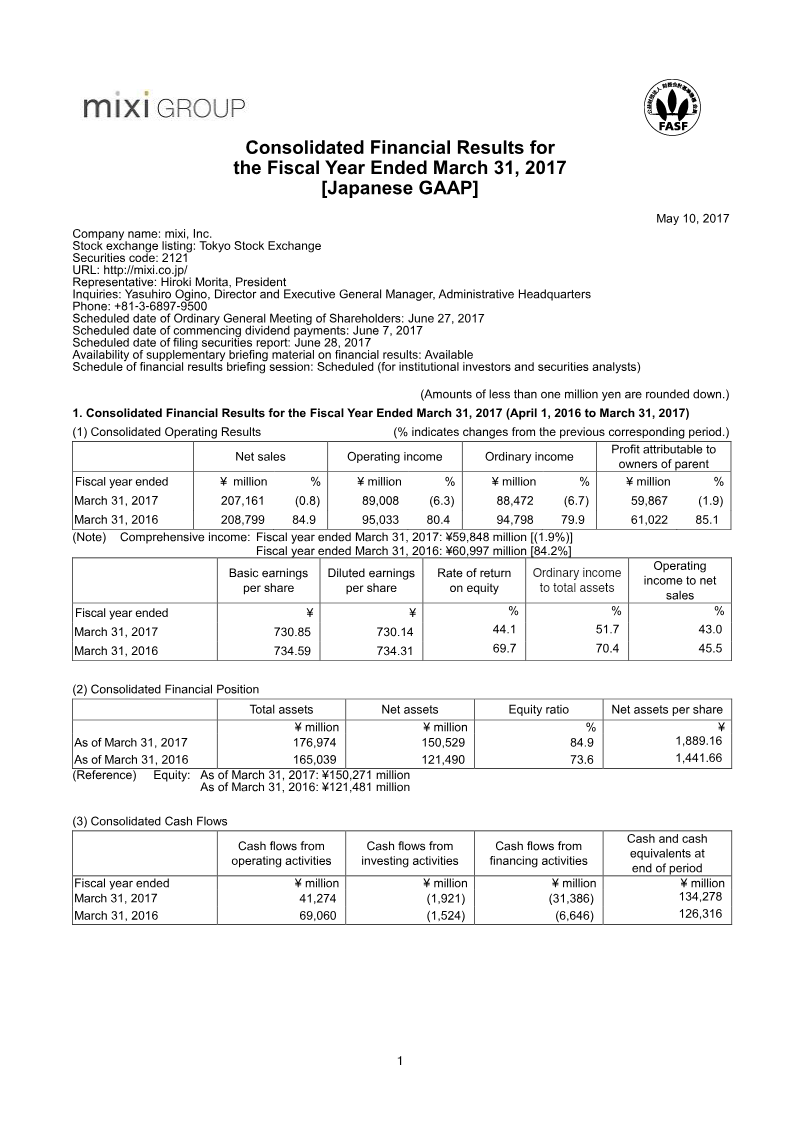
Consolidated Financial Results for the Fiscal Year Ended March 31, 2017
Mixi, Inc. concluded the fiscal year ending March 31, 2017, with a stable but slightly contracting financial performance, reporting net sales of ¥207.1 billion and a profit of ¥59.8 billion. These figures represent marginal year-over-year declines of 0.8% and 1.9%, respectively. Despite this cooling growth, the organization significantly bolstered its balance sheet, increasing its equity ratio to 84.9% and maintaining a robust cash position of ¥134.2 billion. This financial stability was achieved alongside strategic portfolio adjustments, including the acquisition of Compath Me Inc. and the divestiture of non-core assets such as MUSE & Co., Ltd. and mixi research, Inc.
The Entertainment Business remains the primary engine of the company, generating 93% of total revenue and contributing ¥89 billion in segment profit. To sustain this dominance, the organization increased advertising expenditures to ¥20.8 billion. Meanwhile, the Media Platform segment continues to manage significant goodwill assets totaling over ¥8.6 billion. Management has prioritized shareholder returns and capital efficiency through aggressive equity management, retiring 2.4 million treasury shares during the period and authorizing further buybacks of up to ¥10 billion for the following year.
The outlook for the fiscal year ending March 2018 suggests a period of transition and anticipated decline. Projections indicate a 3.5% decrease in net sales and a more substantial 19.8% drop in profit. This forecast reflects a cautious stance as the company navigates a maturing entertainment market and integrates its recent structural changes. While the current financial foundation remains exceptionally strong, the projected downturn highlights the challenges of maintaining the high-growth trajectory established in previous cycles.
- Mixi, Inc. reported fiscal year 2017 net sales of ¥207.1 billion and a profit of ¥59.8 billion, representing marginal year-over-year declines of 0.8% and 1.9%, respectively.
- The company projects a downturn for the fiscal year ending March 2018, forecasting a 3.5% decrease in net sales and a 19.8% drop in profit.
- The Entertainment Business remains the company's primary revenue driver, accounting for 93% of total sales and generating ¥89 billion in segment profit.
- Despite cooling growth, the company maintains a strong financial position with an equity ratio of 84.9% and ¥134.2 billion in cash.
- Management is prioritizing capital efficiency by retiring 2.4 million treasury shares and authorizing up to ¥10 billion in additional share buybacks for the upcoming year.
+1
mixiMay 2017
Financial9 pages
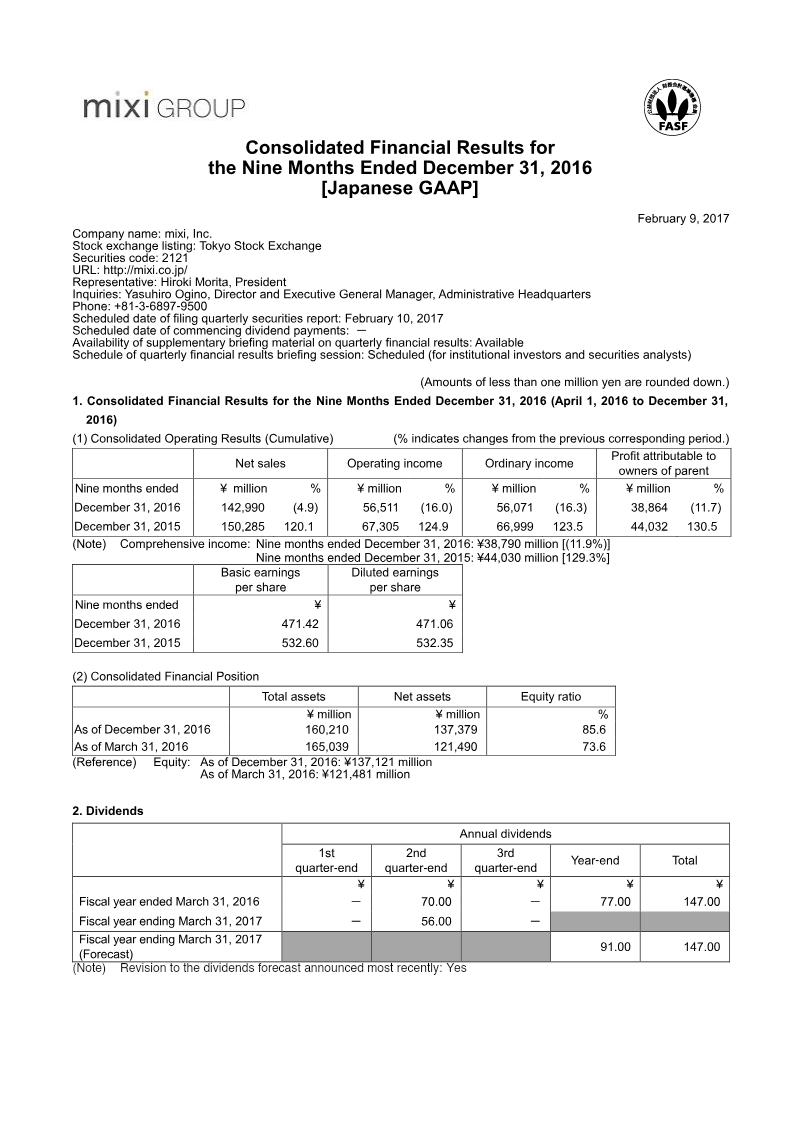
Consolidated Financial Results for the Nine Months Ended December 31, 2016
This financial report details the consolidated results for mixi, Inc. during the first nine months of the fiscal year ending March 31, 2017. The data reflects a period of moderate contraction compared to the previous year’s record growth. Net sales reached ¥142,990 million, representing a 4.9% decrease from the same period in 2015. Operating income fell by 16% to ¥56,511 million, while profit attributable to owners of the parent declined by 11.7% to ¥38,864 million. Despite these year-over-year decreases, the company maintained a strong financial position with an equity ratio of 85.6%, up from 73.6% at the end of the previous fiscal year.
The company’s operations are divided into two primary segments: the Entertainment Business and the Media Platform Business. The Entertainment Business remains the dominant revenue driver, contributing ¥131,805 million in net sales, though its segment profit saw a decline from the previous year. Conversely, the Media Platform Business showed growth in net sales, rising to ¥11,184 million, although its segment profit decreased due to higher costs and adjustments. Significant corporate activity during this period included a substantial share buyback program, with the company repurchasing over 3 million shares and retiring 2.4 million treasury shares to optimize capital efficiency.
Looking ahead, the full-year forecast for the fiscal year ending March 31, 2017, anticipates net sales of ¥206,000 million and a profit of ¥59,000 million. These projections represent a slight downward revision from previous estimates. The report also finalizes accounting for previous acquisitions, specifically Hunza, Inc. and MUSE & Co., Ltd., confirming goodwill amounts and amortization schedules. The methodology follows Japanese GAAP, providing a comprehensive overview of the company’s cash flows, balance sheets, and segment performance for institutional investors and analysts.
- Mixi, Inc. experienced a moderate contraction in the first nine months of the fiscal year ending March 31, 2017, with net sales falling 4.9% to ¥142,990 million and operating income dropping 16% to ¥56,511 million.
- Profit attributable to owners of the parent declined 11.7% to ¥38,864 million compared to the same period in 2015.
- The Entertainment Business remains the primary revenue driver at ¥131,805 million, while the Media Platform Business grew its net sales to ¥11,184 million despite a decrease in segment profit.
- The company strengthened its financial position, increasing its equity ratio to 85.6% from 73.6% at the end of the previous fiscal year.
- Management executed a share buyback program involving the repurchase of over 3 million shares and the retirement of 2.4 million treasury shares to improve capital efficiency.
+2
mixiFeb 2017
Financial8 pages
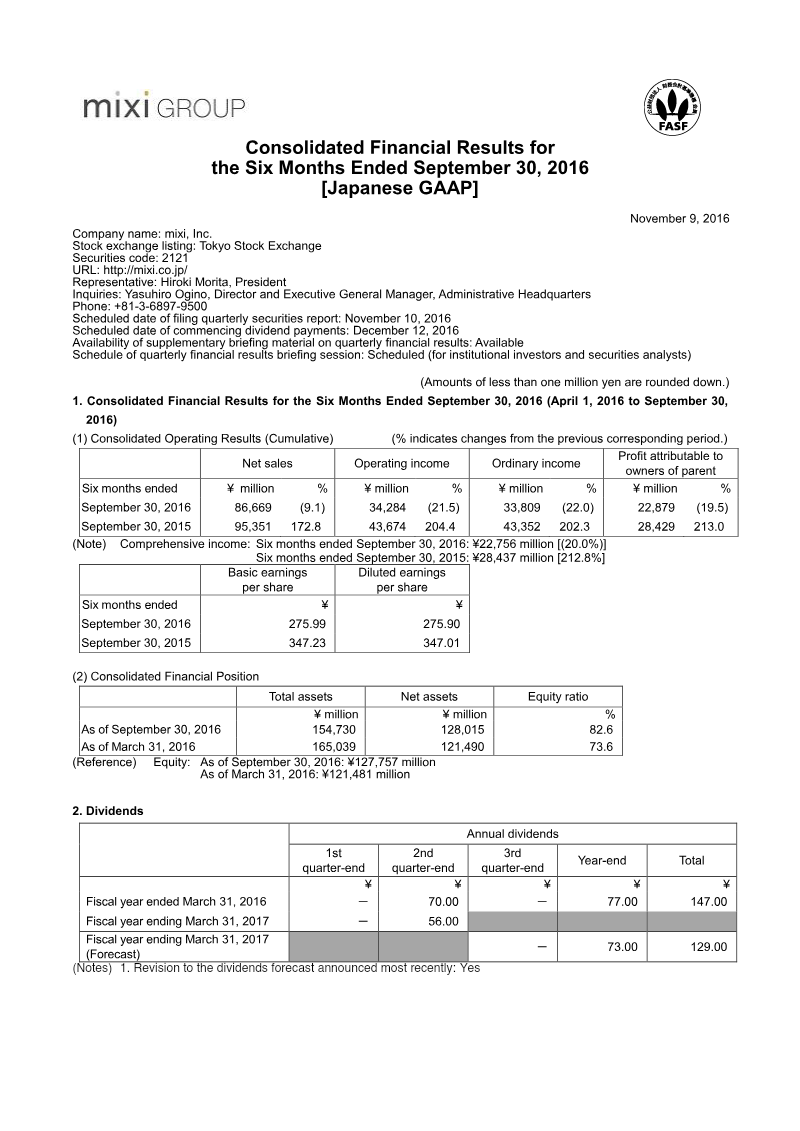
Consolidated Financial Results for the Six Months Ended September 30, 2016
Mixi, Inc. reported consolidated financial results for the first six months of the fiscal year ending March 31, 2017, covering the period from April 1, 2016, to September 30, 2016. The data reveals a period of contraction compared to the previous year’s record growth. Net sales reached ¥86,669 million, representing a 9.1% decrease year-over-year. Profitability also declined, with operating income falling 21.5% to ¥34,284 million and profit attributable to owners of the parent dropping 19.5% to ¥22,879 million. Despite these declines, the company maintained a strong financial position with an equity ratio of 82.6%, up from 73.6% at the end of the previous fiscal year.
The performance is primarily driven by two main industry segments: the Entertainment Business and the Media Platform Business. The Entertainment Business remains the dominant revenue driver, contributing ¥79,452 million in sales, though this was a decrease from the ¥89,027 million recorded in the same period in 2015. Conversely, the Media Platform Business showed growth, with sales increasing from ¥6,324 million to ¥7,217 million. Segment profit followed a similar trend, with Entertainment declining to ¥36,899 million while Media Platform profit dipped slightly to ¥955 million after accounting for adjustments and company-wide expenses.
Looking ahead, the full-year forecast for the period ending March 31, 2017, anticipates total net sales of ¥218,000 million, which would represent a 4.4% increase over the prior full year. However, net income is expected to decline by 11.5% to ¥54,000 million. To improve capital efficiency and shareholder value, the company authorized a significant share repurchase program of up to 3,000,000 shares for a maximum price of ¥10 billion. These results were prepared under Japanese GAAP and reflect the company's transition into a more stable, albeit lower-margin, operational phase following its prior period of rapid expansion.
- Mixi, Inc. experienced a contraction in the first half of fiscal year 2017, with net sales falling 9.1% year-over-year to ¥86,669 million.
- Profitability declined significantly, as operating income dropped 21.5% to ¥34,284 million and profit attributable to owners of the parent fell 19.5% to ¥22,879 million.
- The Entertainment Business remains the primary revenue driver at ¥79,452 million, though it saw a decline from the ¥89,027 million recorded in the same period of 2015.
- The Media Platform Business demonstrated growth, with sales increasing from ¥6,324 million in the prior year to ¥7,217 million.
- The company authorized a share repurchase program of up to 3,000,000 shares, capped at ¥10 billion, to improve capital efficiency and shareholder value.
+1
mixiNov 2016

Financial9 pages
Consolidated Financial Results for the Three Months Ended June 30, 2016
This financial report details the consolidated results for mixi, Inc. during the first quarter of the fiscal year ending March 31, 2017, covering the period from April 1, 2016, to June 30, 2016. The data reflects a period of contraction compared to the previous year’s explosive growth. Net sales reached ¥47,344 million, representing a 5.5% decrease year-over-year, while operating income fell by 17.3% to ¥20,130 million. Profit attributable to owners of the parent declined by 14.9% to ¥13,578 million. Despite these decreases, the company maintained a strong financial position with an equity ratio of 85.6%, up from 73.6% at the end of the previous fiscal year.
The company’s operations are divided into two primary reportable segments: the Entertainment Business and the Media Platform Business. The Entertainment Business remains the dominant revenue driver, contributing ¥44,002 million in net sales, though its segment profit decreased from the prior year. The Media Platform Business saw a slight increase in net sales to ¥3,322 million, but its segment profit dropped significantly from ¥743 million to ¥304 million. Management attributed some of the profit decline to increased selling, general, and administrative expenses, which rose to ¥21,824 million.
Strategic corporate actions during and immediately following the quarter focused on shareholder returns and capital efficiency. The company executed a significant repurchase of treasury shares, totaling approximately ¥10 billion by July 2016, and subsequently resolved to retire over 2.4 million shares to improve capital efficiency. Additionally, the board approved the issuance of share remuneration-type stock options for directors to align leadership interests with shareholder value. For the full fiscal year, the company forecasts net sales of ¥218,000 million and a profit of ¥54,000 million, suggesting a cautious outlook regarding year-over-year profitability.
- Mixi, Inc. experienced a contraction in Q1 of the fiscal year ending March 31, 2017, with net sales falling 5.5% year-over-year to ¥47,344 million and operating income dropping 17.3% to ¥20,130 million.
- The Entertainment Business remains the company's primary revenue driver, generating ¥44,002 million in net sales, though it experienced a decline in segment profit compared to the previous year.
- The Media Platform Business saw a slight increase in net sales to ¥3,322 million, but its segment profit fell sharply from ¥743 million to ¥304 million.
- Profitability was impacted by rising operational costs, with selling, general, and administrative expenses increasing to ¥21,824 million.
- The company maintained a strong balance sheet with an equity ratio of 85.6% as of June 30, 2016, up from 73.6% at the end of the previous fiscal year.
+1
mixiAug 2016
Financial46 pages
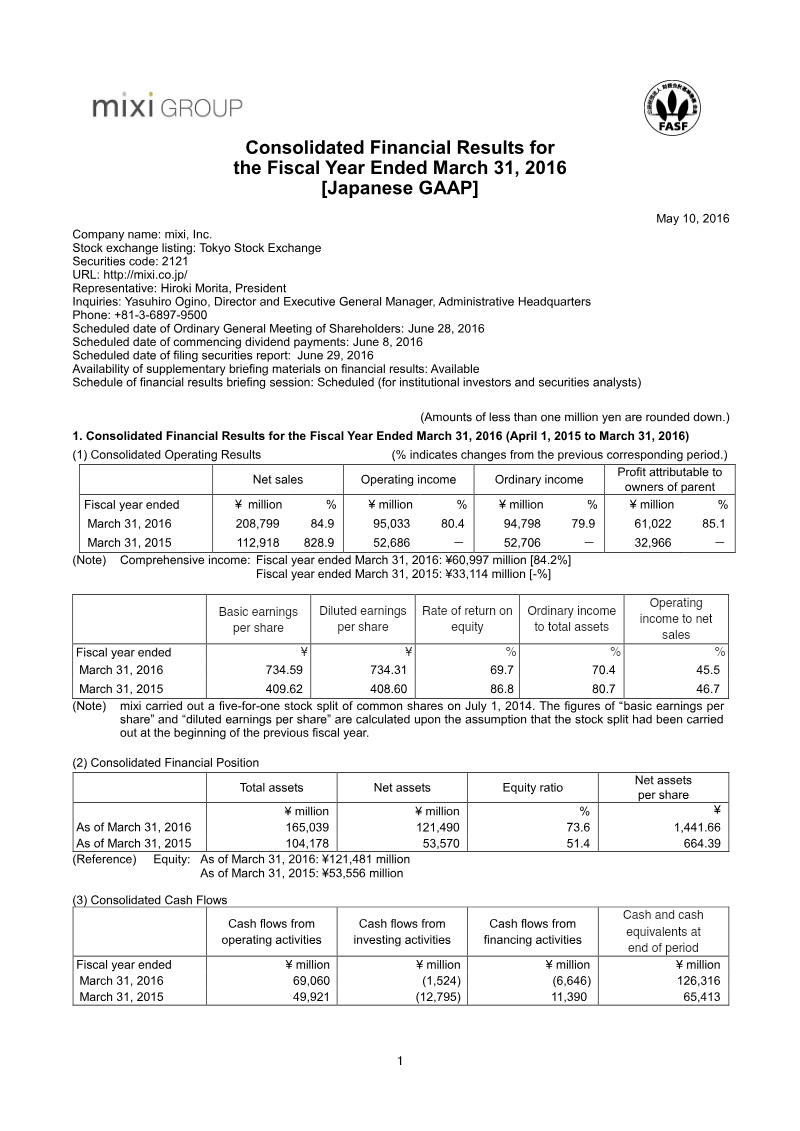
Consolidated Financial Results for the Fiscal Year Ended March 31, 2016
Mixi, Inc. achieved exceptional financial growth during the fiscal year ended March 31, 2016, driven primarily by the expansion of its entertainment and smartphone-based commerce segments. Net sales surged 84.9% to ¥208,799 million, while profit attributable to owners rose 85.1% to ¥61,022 million. This performance significantly bolstered the company’s balance sheet, nearly doubling cash and cash equivalents to ¥126,316 million and increasing the equity ratio from 51.4% to 73.6%. While the Entertainment Business provided the vast majority of the ¥95,033 million in operating income, the company also integrated key acquisitions, including TicketCamp operator Hunza, Inc. and MUSE & Co., Ltd., to diversify its ecosystem.
The period was characterized by substantial operational scaling and capital restructuring. Settlement fees nearly doubled to over ¥60 billion, and advertising expenses rose to ¥15.8 billion, reflecting the intensified costs of supporting a high-growth digital portfolio. Following the previous year’s acquisition of Hunza, Inc. for ¥11,573 million, the company established an eight-year amortization period for its goodwill while opting for a full one-time amortization of MUSE & Co.’s remaining goodwill. To optimize capital efficiency, a five-for-one stock split was executed alongside an overseas share offering and a ¥10 billion share repurchase program.
Despite the record-breaking results of 2016, the outlook for the fiscal year ending March 31, 2017, remains conservative. Projections suggest a modest 4.4% increase in net sales and an anticipated 11.5% decline in net profit. Geographically, operations remain heavily concentrated in the Japanese market, which accounts for over 90% of total sales and assets. The adoption of revised Japanese accounting standards for business combinations further aligned financial reporting with modern regulatory frameworks without impacting the immediate bottom line.
- Mixi, Inc. achieved significant growth in the fiscal year ending March 31, 2016, with net sales rising 84.9% to ¥208,799 million and profit attributable to owners increasing 85.1% to ¥61,022 million.
- The company’s financial position strengthened substantially, with cash and cash equivalents nearly doubling to ¥126,316 million and the equity ratio improving from 51.4% to 73.6%.
- Operating income reached ¥95,033 million, primarily driven by the Entertainment Business, while the company diversified its ecosystem through the acquisitions of Hunza, Inc. and MUSE & Co., Ltd.
- Operational scaling led to increased costs, with settlement fees rising to over ¥60 billion and advertising expenses reaching ¥15.8 billion.
- Capital efficiency measures included a five-for-one stock split, an overseas share offering, and a ¥10 billion share repurchase program.
+1
mixiMay 2016

Financial2 pages
FY2016 Business Report
The FY2016 Business Report for mixi, Inc. details a year of record-breaking financial performance driven primarily by the company’s Entertainment Business. Covering the fiscal period from April 1, 2015, to March 31, 2016, the data reveals a significant surge in growth, with net sales reaching ¥208.799 billion, an 84.9% increase year-on-year. Operating income rose by 80.4% to ¥95.033 billion, while profit attributable to owners of the parent grew by 85.1% to ¥61.022 billion. These results significantly exceeded the company’s previously upgraded January 2016 forecasts.
The primary driver of this growth was the mobile title Monster Strike, which surpassed 35 million global users by April 2016. Success was bolstered by aggressive cross-media strategies, including IP collaborations, the launch of a Monster Strike anime, and the opening of physical pop-up stores. Additionally, the February 2016 release of Marvel Tsum Tsum reached 4 million users within months. The Media Platform Business also contributed stable income through the steady performance of SNS mixi and the strategic acquisition of services like TicketCamp and the matchmaking business Diverse, Inc.
Looking toward FY2017, the strategic focus shifts toward increasing the lifespan of existing services and diversifying revenue streams beyond core gaming. Plans include the overseas expansion of Marvel Tsum Tsum and further investment in the XFLAG Pictures department to monetize video content. In the Media Platform segment, the company intends to proactively create and expand long-term services in the family communication and beauty sectors. To reward shareholders for this performance, the company issued an annual dividend of ¥147 per share and authorized a treasury stock buyback of up to 3 million shares.
- Mixi, Inc. achieved record FY2016 financial results with net sales of ¥208.799 billion, an 84.9% year-on-year increase, and operating income of ¥95.033 billion, up 80.4%.
- The mobile game Monster Strike was the primary growth driver, reaching over 35 million global users by April 2016 through cross-media strategies including anime and physical pop-up stores.
- Profit attributable to owners of the parent grew by 85.1% to ¥61.022 billion, significantly exceeding the company's upgraded January 2016 forecasts.
- The Media Platform Business provided stable income through the performance of SNS mixi and strategic acquisitions, including TicketCamp and Diverse, Inc.
- The February 2016 launch of Marvel Tsum Tsum reached 4 million users within its first few months of availability.
+1
mixiMar 2016
Financial12 pages
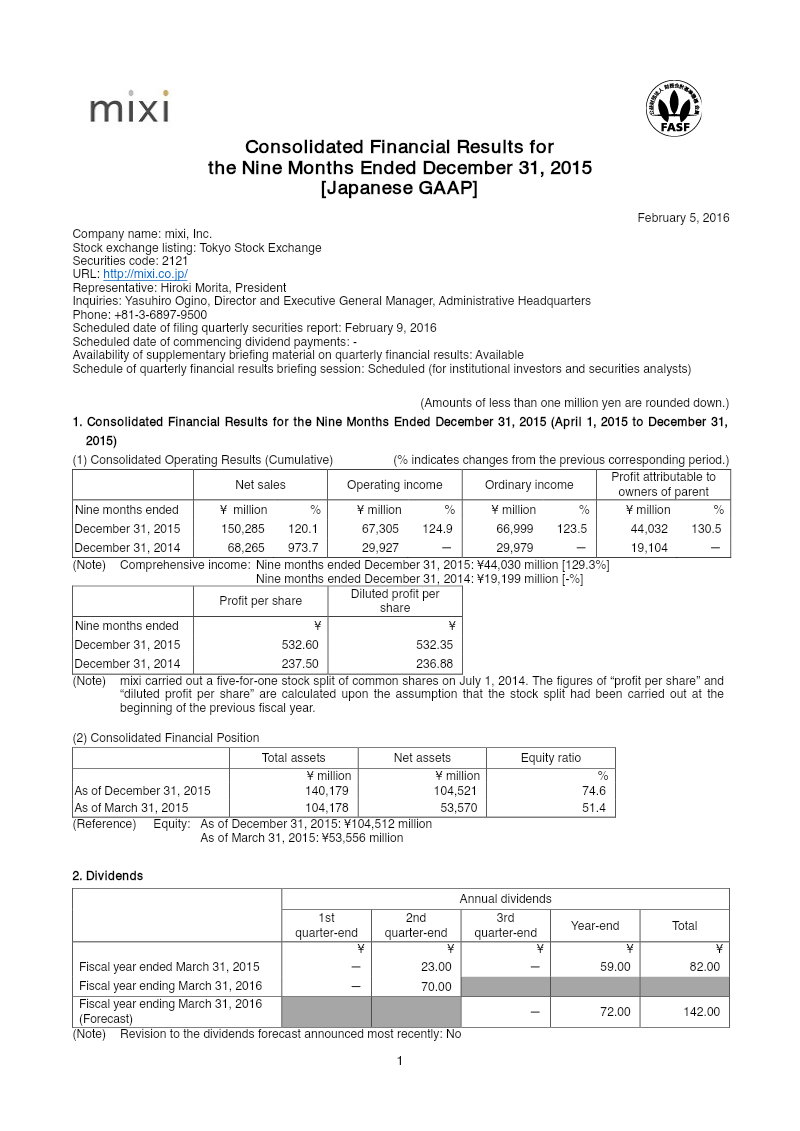
Consolidated Financial Results for the Nine Months Ended December 31, 2015 (Japanese GAAP)
Mixi, Inc. reported substantial year-over-year growth in its consolidated financial results for the nine months ended December 31, 2015. Net sales reached ¥150,285 million, representing a 120.1% increase compared to the same period in 2014. Operating income rose 124.9% to ¥67,305 million, while profit attributable to owners of the parent grew 130.5% to ¥44,032 million. This performance was driven primarily by the Entertainment Business segment, centered on the mainstay service Monster Strike, which contributed ¥140,303 million in net sales and ¥70,348 million in segment profit.
The financial position strengthened significantly during this period, with total assets increasing from ¥104,178 million to ¥140,179 million and the equity ratio improving from 51.4% to 74.6%. Cash and deposits grew to ¥90,380 million, bolstered by the issuance of new shares and the disposal of treasury shares through an overseas offering in July 2015. The Media Platform Business, which includes the social network mixi.jp and recently acquired services like TicketCamp and MUSE & Co., contributed ¥9,981 million to net sales.
The reporting period reflects a strategic reorganization of business segments into Entertainment and Media Platform categories. To better evaluate performance following major acquisitions, the company transitioned to using EBITDA as its primary measure for segment income. For the full fiscal year ending March 31, 2016, the company maintained its forecast of ¥205,000 million in net sales and ¥59,000 million in profit. These results were prepared under Japanese GAAP and cover the company’s operations primarily within the Japanese digital entertainment and social media sectors.
- Mixi, Inc. reported substantial growth for the nine months ended December 31, 2015, with net sales reaching ¥150,285 million, a 120.1% increase year-over-year.
- Operating income surged 124.9% to ¥67,305 million, while profit attributable to owners of the parent rose 130.5% to ¥44,032 million.
- The Entertainment Business segment, driven primarily by the game Monster Strike, accounted for the vast majority of performance with ¥140,303 million in net sales and ¥70,348 million in segment profit.
- The company’s financial position strengthened significantly, with the equity ratio improving from 51.4% to 74.6% and cash and deposits rising to ¥90,380 million.
- The Media Platform Business, encompassing mixi.jp and acquisitions like TicketCamp and MUSE & Co., contributed ¥9,981 million to total net sales.
+1
mixiFeb 2016
Financial11 pages
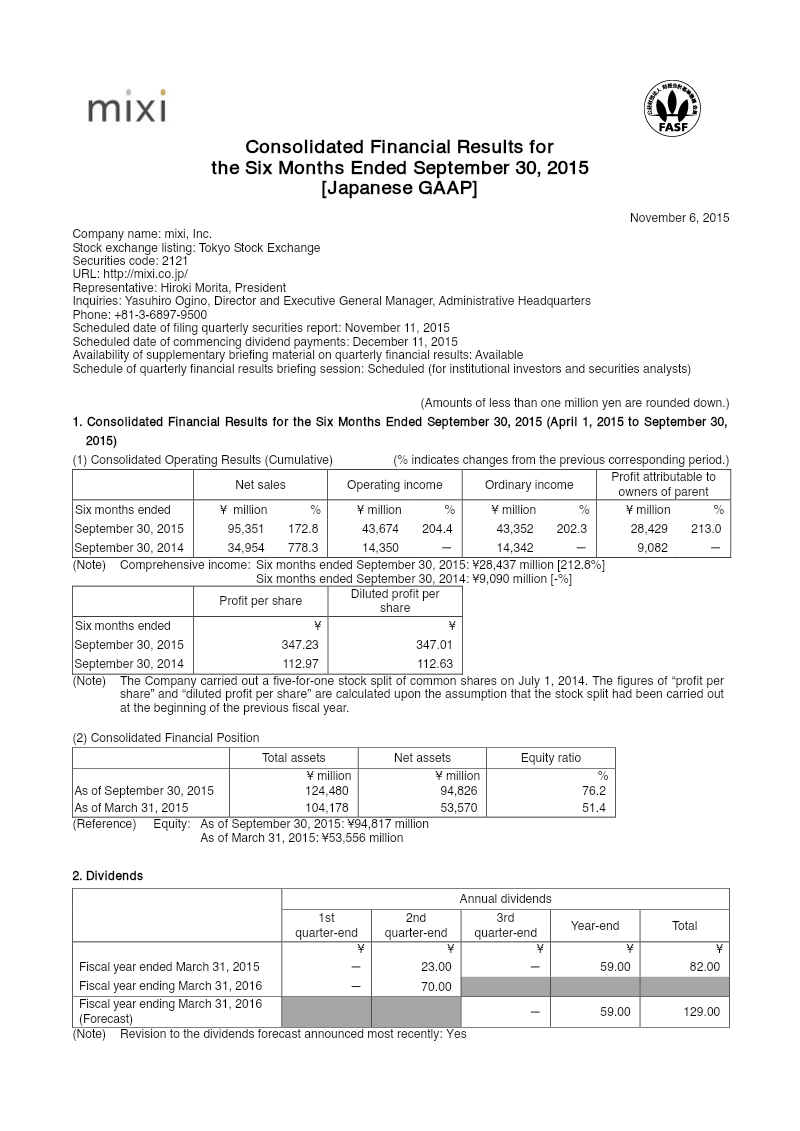
Consolidated Financial Results for the Six Months Ended September 30, 2015
Mixi, Inc. reported significant growth in its consolidated financial results for the six months ended September 30, 2015. Net sales reached ¥95,351 million, representing a 172.8% increase compared to the same period in the previous year. Operating income rose by 204.4% to ¥43,674 million, while profit attributable to owners of the parent surged 213% to ¥28,429 million. This performance was largely driven by the Entertainment Business segment, which includes the mainstay title Monster Strike and accounted for ¥89,027 million of total net sales.
The company’s financial position strengthened during this period, with total assets increasing from ¥104,178 million at the end of March 2015 to ¥124,480 million by September 30, 2015. Net assets grew to ¥94,826 million, resulting in an equity ratio of 76.2%. This growth was supported by an overseas offering in July 2015, which involved the issuance of new shares and the disposal of treasury shares, significantly increasing capital stock and capital surplus. Cash and cash equivalents also saw a substantial rise, ending the period at ¥84,133 million.
Strategic shifts during the period included a reorganization of reportable segments into Entertainment and Media Platform businesses. The Media Platform segment, which includes the mixi SNS and newly acquired entities like Hunza, Inc. and MUSE & Co., Ltd., contributed ¥6,324 million in sales. To better evaluate performance following these acquisitions, the company transitioned to using EBITDA as its primary measure for segment income. Looking forward, the full-year forecast for the fiscal year ending March 31, 2016, projects net sales of ¥185,000 million and a profit of ¥52,000 million, maintaining a positive outlook for the remainder of the year.
- Mixi, Inc. experienced massive growth for the six months ending September 30, 2015, with net sales rising 172.8% to ¥95,351 million and operating income increasing 204.4% to ¥43,674 million.
- The Entertainment Business segment, anchored by the title Monster Strike, served as the primary revenue driver, accounting for ¥89,027 million of total net sales.
- Profit attributable to owners of the parent surged 213% to ¥28,429 million, supported by a strong financial position that saw total assets grow to ¥124,480 million and an equity ratio of 76.2%.
- An overseas share offering in July 2015 significantly bolstered the company's capital, contributing to a cash and cash equivalents balance of ¥84,133 million by the end of September.
- The company reorganized into two reportable segments—Entertainment and Media Platform—with the latter contributing ¥6,324 million in sales through the mixi SNS and acquisitions like Hunza, Inc. and MUSE & Co., Ltd.
+2
mixiNov 2015