Report6 pages
FY2025 Third Quarter Financial Highlights: Japan
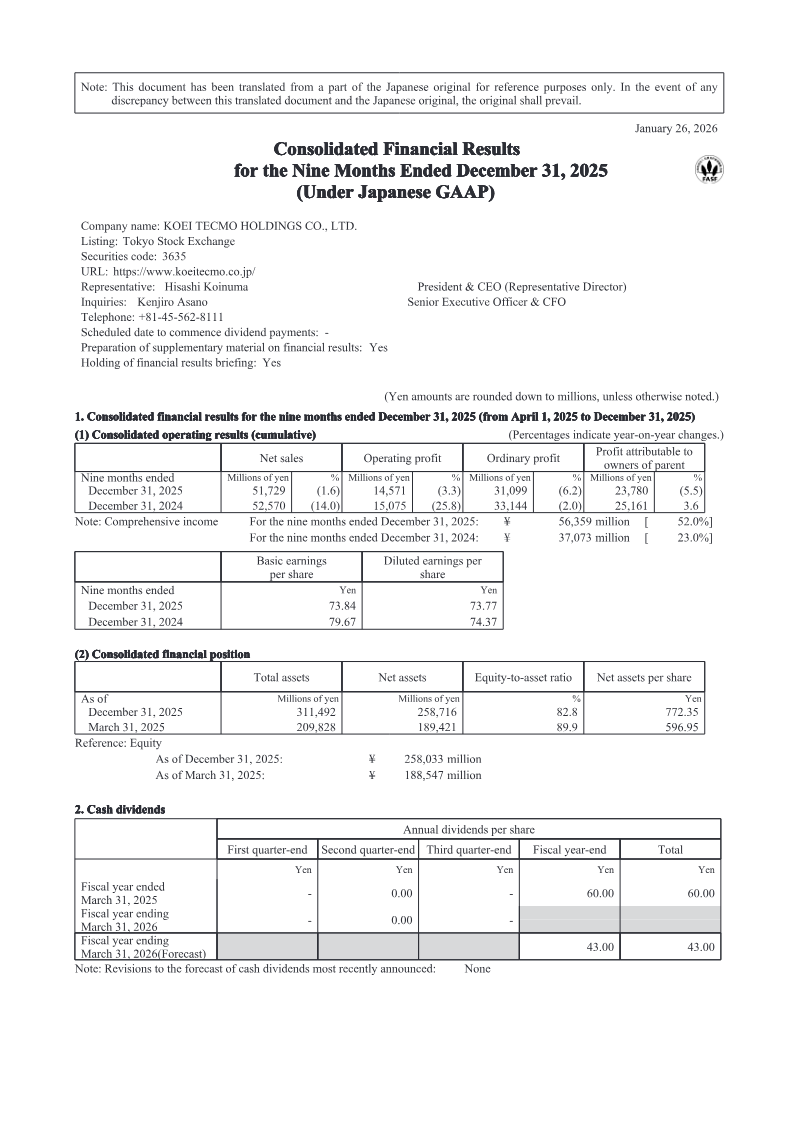
The FY2025 third‑quarter financial highlights for Koei Tecmo Holdings detail a modest decline in core operating metrics while comprehensive income rises sharply. Net sales for the nine months ended December 31, 2025 fell 1.6% to ¥51,729 million from ¥52,570 million in the prior year. Operating profit slipped 3.3% to ¥14,571 million, and ordinary profit decreased 6.2% to ¥31,099 million. Despite these contractions, comprehensive income surged 52.0% year‑on‑year to ¥56,359 million, driven by significant gains in non‑operating items such as interest income and foreign exchange gains. Basic earnings per share declined slightly to ¥73.84 from ¥79.67, reflecting a higher weighted‑average share count due to treasury share disposals and secondary offerings.
Total assets expanded from ¥209,828 million at March 31, 2025 to ¥311,492 million by December 31, 2025, largely through increases in investment securities and property, plant, and equipment. Net assets rose to ¥258,716 million, with the equity‑to‑asset ratio improving to 82.8% from 89.9%. Treasury shares reduced dramatically, lowering the average number of outstanding shares to 322 million from 315 million.
Dividend policy remains unchanged, with a forecast of ¥43.00 per share for the fiscal year ending March 31, 2026, and no revisions to cash dividend forecasts. The report covers Japan‑based operations for FY 2025, presenting consolidated quarterly financial statements without significant changes in consolidation scope or accounting policies.
- Koei Tecmo Holdings reported a 1.6% decline in net sales to ¥51,729 million and a 3.3% drop in operating profit to ¥14,571 million for the nine months ended December 31, 2025.
- Comprehensive income surged 52.0% year-on-year to ¥56,359 million, primarily fueled by non-operating gains from interest income and foreign exchange fluctuations.
- Total assets grew significantly to ¥311,492 million by December 31, 2025, up from ¥209,828 million at the start of the fiscal year, driven by increases in investment securities and property, plant, and equipment.
- Basic earnings per share fell to ¥73.84 from ¥79.67, impacted by an increase in the weighted-average share count following treasury share disposals and secondary offerings.
- The company maintains its dividend forecast at ¥43.00 per share for the fiscal year ending March 31, 2026, with no changes to its current dividend policy.
+2
Koei Tecmo
Report8 pages
Consolidated Financial Data: FY2025 3rd Quarter
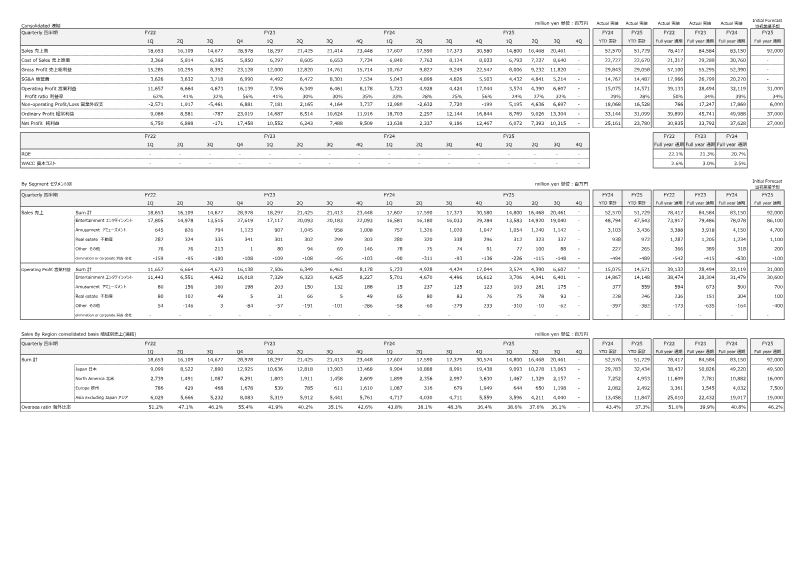
The consolidated financial data for FY2025 third quarter presents a mixed performance across the company’s core segments. Total sales reached ¥30,580 million in Q3 FY25, a 5.4% increase from the same period in FY24 but still below the ¥28,978 million recorded in Q3 FY22. Gross profit improved to ¥22,547 million, up 0.6% YoY, while operating profit fell to ¥17,044 million, a 15.5% decline driven by higher SG&A and cost of sales in the entertainment segment. Net profit for Q3 FY25 stood at ¥12,467 million, a 6.4% YoY increase, supported by a positive non‑operating profit of ¥3,737 million. Profitability ratios show operating margin at 56% and ROE rising to 22.1%, reflecting efficient capital use.
Geographically, Japan remains the largest market with ¥19,438 million in Q3 FY25, followed by North America at ¥3,630 million and Europe at ¥1,949 million. Overseas sales accounted for 51.0% of total revenue in FY25, up from 46.2% in FY24, indicating a strategic shift toward international expansion. The entertainment segment dominated sales at ¥29,284 million (95% of total), with console/PC and online/mobile channels contributing 60.5% and 71.2% of digital sales respectively.
Headcount increased from 2,384 to 2,531 employees by year‑end FY25, a 6.7% rise aligned with new product launches and expanded online services. Capital expenditures for FY25 totaled ¥1,967 million, primarily in real estate and equipment, while depreciation expenses reached ¥1,776 million. The data suggest a focus on sustaining growth through digital monetization and overseas market penetration, while managing cost pressures in traditional entertainment operations.
- Operating profit declined 15.5% YoY to ¥17,044 million in Q3 FY25, primarily due to rising SG&A and cost of sales within the entertainment segment.
- Total sales grew 5.4% YoY to ¥30,580 million, though this figure remains below the ¥28,978 million recorded in Q3 FY22.
- Overseas revenue grew to 51.0% of total sales in FY25, up from 46.2% in FY24, signaling a successful strategic shift toward international market penetration.
- Net profit rose 6.4% YoY to ¥12,467 million, bolstered by a positive non-operating profit of ¥3,737 million.
- The entertainment segment accounts for 95% of total sales, with digital revenue driven by a 60.5% contribution from console/PC channels and 71.2% from online/mobile.
+1
Koei Tecmo
Report2 pages
Summary of Q&A: FY2016 4Q GREE Results Briefing
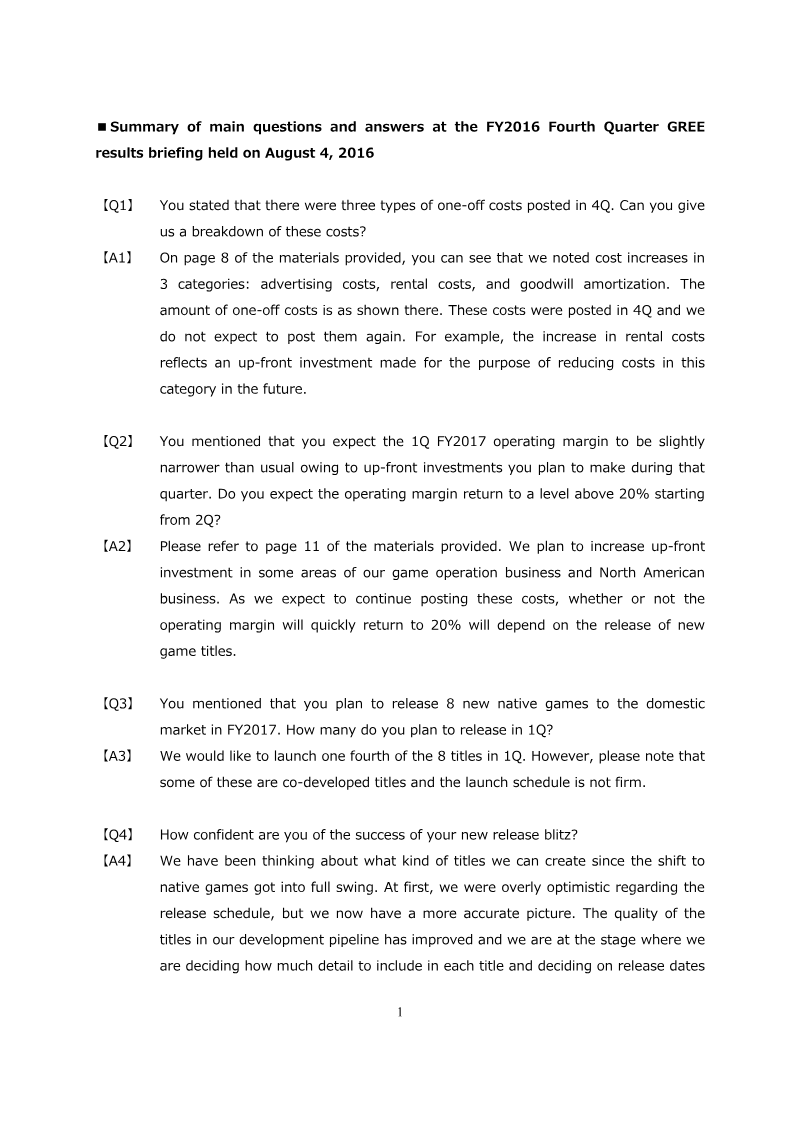
The briefing clarified GREE’s financial and strategic outlook for FY2016–FY2017. One‑off costs in Q4 were broken into advertising, rental and goodwill amortization, with rental increases reflecting upfront investments aimed at future cost reductions. These expenses are not expected to recur. Operating margin for Q1 FY2017 is projected to be slightly below normal due to continued upfront spending, particularly in game operations and North America; a return above 20% is contingent on new title releases. GREE plans to launch eight native games in FY2017, with a quarter‑backed schedule of one‑quarter releases for roughly two titles, though co‑development timelines remain fluid. Confidence in the release blitz has improved as development pipelines mature and release dates are refined based on competitive market conditions.
Strategically, each studio is positioned to leverage core strengths: Wright Flyer focuses on action RPGs and IP integration, while Pokelabo targets GvG titles built on card‑battle expertise. Hit titles are defined by top‑ten App Store rankings in the games category. Financially, GREE aims to use its strengthened capital base to sustain long‑term game development and pursue selective M&A or IP acquisitions, exemplified by the 4Q acquisition of ad‑media firm ADFULLY. The scope covers domestic Japanese markets, with implications for North American expansion, and the time frame spans FY2016 Q4 through FY2017. The briefing relied on internal financial statements and strategic planning documents to outline cost structures, margin expectations, product pipelines, studio focus areas, success metrics, and capital deployment strategies.
- GREE plans to launch eight native games in FY2017, targeting a release cadence of two titles per quarter.
- Operating margins for Q1 FY2017 are expected to remain below 20% due to upfront investments in game operations and North American expansion, with a return to higher margins contingent on new title performance.
- The company defines 'hit titles' as games that achieve top-ten rankings within the App Store games category.
- One-off costs incurred in Q4 FY2016—including advertising, rental, and goodwill amortization—are non-recurring expenses intended to facilitate future cost reductions.
- Studio strategies are specialized: Wright Flyer is focused on action RPGs and IP integration, while Pokelabo is focused on GvG titles leveraging card-battle expertise.
+1
GREE
Report1 pages
Summary of main supplementary explanations questions and answers at the FY 2020 Second Quarter GREE results briefing held on February 3, 2020
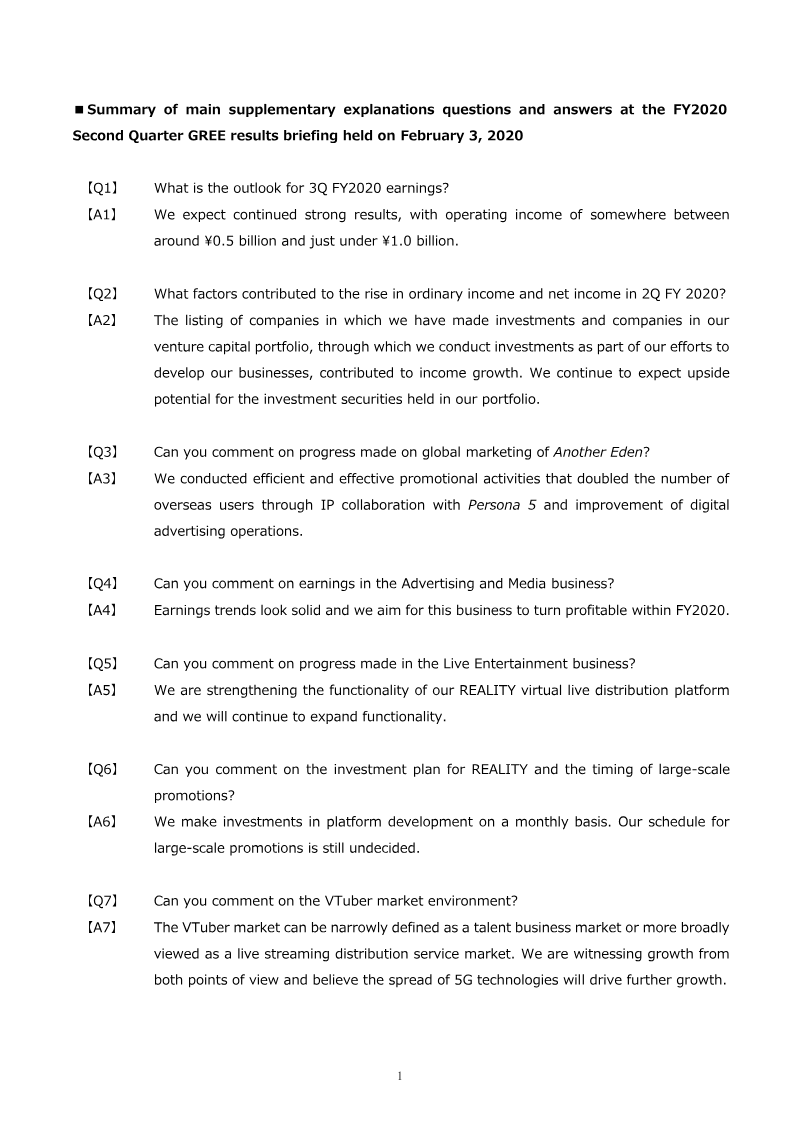
The briefing focused on GREE’s financial outlook, investment performance, and strategic initiatives across its entertainment and advertising segments. Management projected operating income for the third quarter of FY2020 to range between ¥0.5 billion and just under ¥1.0 billion, reflecting confidence in continued strong results. The rise in ordinary and net income during the second quarter was attributed to gains from listed companies and venture‑capital investments, with expectations of further upside in portfolio securities.
Marketing efforts for the game “Another Eden” were highlighted, noting a doubling of overseas users through an IP collaboration with Persona 5 and enhanced digital advertising operations. In the Advertising and Media business, earnings trends were described as solid, with a target of achieving profitability within FY2020. The Live Entertainment division emphasized ongoing enhancements to the REALITY virtual live‑distribution platform, with monthly investments in development and an undecided schedule for large‑scale promotions.
Regarding the broader VTuber market, management characterized it as both a talent‑based business and a live‑streaming distribution service, observing growth from both angles. The anticipated impact of 5G technology was cited as a catalyst for further expansion in the sector. Overall, the briefing underscored GREE’s focus on diversified revenue streams, strategic investment in emerging platforms, and a proactive marketing approach to sustain growth across its core business segments.
- GREE projects Q3 FY2020 operating income to range between ¥0.5 billion and just under ¥1.0 billion.
- Q2 FY2020 net and ordinary income growth was driven by gains from venture capital investments and listed company holdings.
- The game 'Another Eden' doubled its overseas user base following an IP collaboration with Persona 5 and optimized digital advertising.
- The Advertising and Media segment is performing steadily with a firm target to reach profitability within the 2020 fiscal year.
- The Live Entertainment division is prioritizing ongoing development of the REALITY virtual live-distribution platform, with large-scale promotional spending currently on hold.
+1
GREE
Report1 pages
Summary of Main Supplementary Explanations Questions and Answers: FY2024 Fourth Quarter GREE Results Briefing
The briefing clarified GREE’s strategic outlook for FY2024, focusing on console game development and the VTuber business. The company confirmed that its console gaming venture remains in early planning, with no concrete release dates or platform commitments disclosed. This indicates a cautious approach as GREE evaluates market entry points and potential partnerships before committing resources.
In contrast, the VTuber segment is progressing toward profitability. GREE reported steady sales growth aligned with its initial projections, despite operating losses that have risen due to aggressive talent acquisition and merchandise production. These losses fall within the company’s planned range, suggesting disciplined financial management amid expansion efforts. GREE projects that monthly operating losses will be eliminated in FY2026, marking the anticipated break‑even point for its VTuber investments.
The briefing covered a domestic Japanese market focus, with no mention of international expansion for either segment. The time frame discussed spans FY2024 through FY2026, highlighting short‑term challenges and medium‑term profitability goals. Methodological details were limited; the company referenced internal financial metrics rather than external surveys or third‑party data. Overall, GREE’s communication signals a phased growth strategy: cautious console game development coupled with aggressive scaling of its VTuber platform, aiming for profitability by the middle of FY2026.
- GREE targets a break-even point for its VTuber business by the middle of FY2026, with monthly operating losses expected to be eliminated by that time.
- The VTuber segment is currently experiencing rising operating losses due to aggressive investments in talent acquisition and merchandise production, though these costs remain within the company's planned budget.
- GREE’s console game development remains in the early planning stages, with no confirmed release dates, platforms, or resource commitments disclosed.
- The company is pursuing a phased growth strategy that prioritizes cautious evaluation for console gaming while aggressively scaling its VTuber platform.
- GREE’s current strategic outlook is focused exclusively on the domestic Japanese market, with no stated plans for international expansion in the console or VTuber segments.
+2
GREE
Report1 pages
Summary of main supplementary explanations questions and answers at the FY2025 First Quarter GREE results briefing held on November 5, 2024
The briefing clarified GREE’s strategic focus for FY2025 first‑quarter results, emphasizing both gaming and investment operations. In the gaming segment, the company confirmed that advance registrations for the English version of “Heaven Burns Red” are strong and that distribution will be handled by Yostar Games, whose track record in expanding English‑speaking fan communities is expected to generate significant buzz. GREE highlighted ongoing community building efforts prior to launch, underscoring a proactive marketing approach.
Regarding the investment business, management acknowledged that valuation‑loss risk remains comparable to Q1 FY2025 levels. The primary driver of past losses was large investments in funds nearing the end of their operating periods; however, diversification and limited exposure to such funds mitigate long‑term impact. GREE maintains that while short‑term volatility may persist, medium‑to‑long‑term earnings should remain stable as funds mature and yield dividends or asset sales. The company reiterated its commitment to investing in GREE‑Group managed funds, including GREE Ventures, and expects related risks to surface only after several years.
Overall, the briefing presented a balanced outlook: aggressive growth in the gaming arm through strategic partnerships and community engagement, coupled with cautious yet steady investment practices aimed at preserving earnings stability amid inherent valuation risks.
- GREE is launching the English version of 'Heaven Burns Red' in partnership with Yostar Games, leveraging the publisher's expertise in growing English-speaking fan communities.
- The company is prioritizing proactive community building and marketing efforts ahead of the 'Heaven Burns Red' English launch to drive engagement.
- Management expects valuation-loss risks in the investment segment to remain consistent with Q1 FY2025 levels in the near term.
- While short-term volatility persists, GREE anticipates stable medium-to-long-term earnings as existing funds mature through asset sales and dividend yields.
- The company has mitigated long-term investment risk by diversifying its portfolio and limiting exposure to funds nearing the end of their operating cycles.
+3
GREE
Report3 pages
Summary of Main Supplementary Explanations Questions and Answers: FY2025 Full-Year Results
GREE Holdings outlines its FY2025 full‑year results and forward strategy across several business segments. In the game division, the company acknowledges the typical post‑launch decline in live‑service titles and counters it by expanding both its live‑service portfolio—leveraging a proven RPG engine—and investing in console games built on proprietary IP to create a steadier earnings base. The company reports multiple recent hit releases and anticipates further inquiries for third‑party IP adaptations, positioning itself to capture high profitability in the live‑service arena.
The platform business remains growth‑oriented, with steady increases in room and gifting revenue offsetting a temporary dip in avatar sales. New avatar features are expected to revive this segment, while the company continues to push other monetization channels. In the VTuber sector, GREE pursues a two‑stage growth model: first expanding its talent roster—now about 90 talents—and then boosting sales per talent through diversified merchandise channels and nascent live‑event advertising. Sales per talent have doubled since FY2024, and the company maintains a balanced portfolio to avoid over‑reliance on any single talent.
The DX business is undergoing a structural shift from one‑time project sales to recurring revenue, with modest growth projected through FY2026 as the transition completes. Investment activities in FY2026 will see increased volatility due to fund maturity and potential impairment, yet the company expects stable income streams from dividends and performance fees. Overall, GREE projects balanced returns while navigating market challenges across its diversified entertainment portfolio.
- GREE is shifting its game division strategy to balance post-launch live-service volatility by investing in console titles built on proprietary IP.
- The VTuber business has doubled sales per talent since FY2024, supported by a roster of approximately 90 talents and expanded merchandise and advertising channels.
- The DX business is transitioning from a one-time project sales model to a recurring revenue structure, with modest growth expected through FY2026.
- Platform revenue growth is currently driven by room and gifting monetization, which is offsetting a temporary decline in avatar sales.
- Investment activities in FY2026 are expected to experience increased volatility due to fund maturity and potential impairments, though stable income from dividends and performance fees is anticipated.
+4
GREE
Report65 pages
Annual Report and Consolidated Financial Statements: 2020
ANNUAL REPORT AND CONSOLIDATED FINANCIAL STATEMENTS FOR THE YEAR ENDED 31 DECEMBER 2020 Strategic report 3 Highlights of the year 4 Chairman’s statement 6 History and background 7 Strategy 9 Business model 10 tinyBuild portfolio 14 Chief Executive’s ...
- tinyBuild aims for growth through both organic strategies, leveraging existing partnerships and in-house developers, and inorganic strategies, utilizing a low-risk M&A approach focused on 'acquihiring' development teams and acquiring relevant IP.
- The 'Hello Neighbor' franchise serves as a template for tinyBuild's multimedia strategy, having grown organically and through M&A, expanding into merchandise, books, and potential animated TV series, and generating over 60 million downloads for its first game.
- tinyBuild's organic growth strategy focuses on increasing the quality of its game pipeline with 23 games planned for 2021 and 2022, and accumulating IP through standard partnership agreements to extend franchise lifespans.
- The company mitigates risks associated with early-stage developer partnerships by typically providing funding at specific milestones, ensuring investments are tied to key development stages over a limited time horizon.
- tinyBuild's cash generated from operations increased from $11,732,000 in 2019 to $16,470,000 in 2020, with a net increase in cash and cash equivalents of $9,304,000 in 2020, bringing the total to $26,313,000 by year-end.
+3
tinyBuild
Report70 pages
Annual Report and Consolidated Financial Statements 2022
ANNUAL YEARENDED 31DECEMBER2022 REPORT AND CONSOLIDATED FINANCIAL STATEMENTS FOR THE YEAR ENDED 31 DECEMBER 2022 Highlights of the year 5 Business model 11 Chief Executive’s review 16 Chief Financial Officer’s review 19 Environmental, Social and Governance (ESG) 21 Principal risks and uncertainties 22 Corporate Governance ...
- tinyBuild's total revenue for the year ended December 31, 2022, was $63,295,000, an increase from $52,153,000 in 2021.
- Game and merchandise royalties contributed $40,020,000 to revenue in 2022, while development services generated $22,744,000, significantly up from $11,477,000 in 2021.
- The company incurred $1,678,000 in non-recurring costs related to the Ukraine/Russia conflict in 2022, which included relocating contractors and establishing tinyBuild d.o.o. in Serbia.
- tinyBuild focuses on organic growth by signing new genre-defining titles (e.g., Tinykin), investing in acquired studios (e.g., Deadside), empowering publishing labels (e.g., Versus Evil), and creating new IP (e.g., Potion Craft).
- The 'Hello Neighbor' franchise, discovered by tinyBuild in 2015, has accumulated over 70 million downloads and is expanding with new titles like 'Hello Neighbor Search and Rescue' (VR) and 'Hello Engineer' (PC/Consoles).
+1
tinyBuild
Report66 pages
Annual Report and Consolidated Financial Statements: 2021
ANNUAL REPORT AND CONSOLIDATED FINANCIAL STATEMENTS FOR THE YEAR ENDED 31 DECEMBER 2021 Strategic Report 3 Highlights of the year 5 Chairman’s statement 6 History and background 7 Strategy 9 Business model 11 Chief Executive’s review 16 Chief ...
- tinyBuild achieved record growth in 2021 through mergers and acquisitions and organically, and listed on the London Stock Exchange on March 9, 2021.
- The company's back catalog revenue has consistently grown, representing 51% of gaming revenue in FY17, increasing to 83% in FY19, and settling at 79% in FY21.
- tinyBuild has a strong focus on influencer marketing, having achieved over 5 billion content-related views on YouTube by December 31, 2021, and maintaining relationships with over 10,000 verified influencers.
- tinyBuild is actively relocating staff from Ukraine due to the war, setting up a temporary location in the Balkans and planning a third studio in Western Europe to assist with relocation and visa processes.
- The company has a policy against 'crunching' and provided an extra week of holiday to all direct employees in 2021 as appreciation for their work during the pandemic.
+3
tinyBuild
Report72 pages
Annual Report and Consolidated Financial Statements 2023
ANNUAL R THE YEAR ENDED FINANCIAL STATEMENTS FOR THE YEAR ENDED Business model 10 Chief Executive’s review 15 Chief Financial Officer’s review 17 Environmental, social and governance (ESG) 19 Principal risks and uncertainties 20 Corporate Governance 25 Board of Directors 25 Corporate governance report ...
- Revenue generated from own-IP (1st and 2nd party games) decreased to 65% of gaming revenues in 2023, down from 77% in 2022, due to changes in the portfolio mix. Conversely, revenues from the back-catalogue increased to 92% of total revenues in 2023 (up from 80% in 2022), driven by successful new releases like "I am Future" (Early Access) and "Punch Club 2".
- The company maintains a strong social media presence with over 1.7 million followers across platforms by the end of 2023, placing it competitively with other gaming companies like Devolver Digital (1.1m) and Paradox Interactive (0.9m). They also boast c.5 billion YouTube views and over 10,000 verified influencers.
- The top 5 games generated 46.8% of total revenues in 2023 (up from 44.8% in 2022), and the top 10 games generated 65.44% (down from 66.3% in 2022), indicating broad diversification across audiences, genres, and technologies.
- The company incurred $3.5 million in legal settlement fees in 2023 and continues to face costs related to the Ukraine/Russia conflict, which are now included in operating expenses, with potential for future charges.
- The company mitigates risks associated with early-stage developer engagement by providing milestone-based funding, acquiring IP as part of agreements, and adjusting budgets using data-driven approaches. They also intensify audience validation through playtests and demos to align with consumer trends.
+1
tinyBuild
Report2 pages
Summary of main supplementary explanations questions and answers at the FY2026 Second Quarter GREE Holdings, Inc. results briefing held on February 5, 2026
The briefing clarified GREE Holdings’ strategic priorities across its core business segments for FY2026. In the Anime Business, earnings from the newly announced “Mushoku Tensei: Jobless Reincarnation – Chronicle of Echoes” are recorded under the IP Business segment, reflecting the company’s focus on monetizing anime titles it has invested in. The Platform Business within the VTuber segment is expanding beyond traditional gifting revenue by piloting merchandise sales and event features on its REALITY platform; early feedback indicates positive reception, and the company plans to extend these monetization tools to a broader streamer base while offering corporate marketing solutions. In the DX Consulting Business, GREE emphasizes its niche in end‑user entertainment services and acknowledges that generative AI may automate routine maintenance but is unlikely to erode its creative‑driven value proposition in the short term. Regarding financial outlook, a downward revision of FY26 earnings was justified by recent softness in existing game titles; however, the company maintains confidence in its three‑year medium‑term targets (FY28) by shifting emphasis toward continuous growth businesses and reducing reliance on volatile game revenues. Finally, the Anime Business will pursue acquisition of production capabilities—through both in‑house development and M&A—within 2–3 years to secure control over high‑quality, timely anime output. These initiatives collectively aim to diversify revenue streams, strengthen creative control, and sustain long‑term growth across GREE’s entertainment ecosystem.
- GREE Holdings revised its FY26 earnings downward due to recent performance softness in existing game titles.
- The company is shifting its long-term strategy toward continuous growth businesses to reduce reliance on volatile game revenue, maintaining its medium-term targets for FY28.
- GREE plans to acquire anime production capabilities through in-house development and M&A within the next 2–3 years to secure control over output quality and timing.
- The REALITY platform is expanding its VTuber monetization model beyond gifting by piloting merchandise sales and event features, with plans to integrate corporate marketing solutions.
- Revenue from the new title 'Mushoku Tensei: Jobless Reincarnation – Chronicle of Echoes' is being categorized under the IP Business segment to reflect the company's focus on monetizing its anime investments.
+1
GREE
Report71 pages
Annual Report 2012: 11 bit studios S.A.
I. PISMO ZARZĄDU ............................................................................................................. 3 II. WYBRANE JEDNOSTKOWE DANE FINANSOWE ZAWIERAJĄCE PODSTAWOWE POZYCJE ROCZNEGO SPRAWOZDANIA FINANSOWEGO WRAZ Z DANYMI PORÓWNYWALNYMI ................ 4 III. SPRAWOZDANIE FINANSOWE ZA ROK 2012 11 BIT STUDIOS S.A. ........................................ 4 IV. SPRAWOZDANIE ZARZĄDU Z DZIAŁALNOŚCI SPÓŁKI W ROKU 2012....................................
- 11 bit studios S.A. reported a net profit of 1,344,700.33 PLN in 2012, a slight increase from 1,292,777.32 PLN in 2011.
- The company's equity significantly increased from 2,560,977.91 PLN in 2011 to 6,913,931.74 PLN in 2012, primarily due to an increase in share capital and reserve capital.
- Share capital increased from 187,076.10 PLN to 221,719.90 PLN in 2012 through the issuance of Series D and E shares, with nominal values of 0.10 PLN per share.
- Revenue from sales in 2012 totaled 3,346,593.68 PLN, with 95.5% of this revenue coming from foreign sales.
- Operating costs amounted to 3,007,118.43 PLN in 2012, with salaries constituting 59.7% and external services 31.9% of these costs.
+2
11 bit studios
Report70 pages
Annual Report and Consolidated Financial Statements 2024
ANNUAL REPORT AND CONSOLIDATED FINANCIAL STATEMENTS FOR THE YEAR ENDED Chairman’s statement 4 History and background 5 Strategy 7 Business model 9 Chief Executive’s review 14 Chief Financial Officer’s review 16 Environmental, social and governance (ESG) 18 Principal risks and uncertainties ...
- tinyBuild experienced a significant decline in revenue and continued operating losses in 2024, with revenue dropping by 22% year-over-year to $34.7 million (from $44.7 million in 2023) and an operating loss of $20.4 million (compared to $63.8 million in 2023).
- The revenue decline was primarily due to limited flow-through from new games released in 2023 and a 50% drop in development revenues, largely from platform deals.
- Adjusted EBITDA remained negative at -$3.681 million in 2024, an improvement from -$7.113 million in 2023, impacted by revenue decline and a $13.7 million impairment of software development costs.
- tinyBuild raised over $11 million in new capital in January 2024 and welcomed Atari as a new core investor, helping to fund promising projects.
- The company maintains an organic growth strategy focusing on diversification, internal development teams (e.g., DUCKSIDE), established partnerships (e.g., Potion Craft), and leveraging influencer relationships for marketing, achieving over 5 billion content-related views on YouTube by December 31, 2024.
+2
tinyBuild
Report54 pages
Annual Report 2010: 11 bit studios
I. PISMO ZARZĄDU ............................................................................................................. 3 II. WYBRANE JEDNOSTKOWE DANE FINANSOWE ZAWIERAJĄCE PODSTAWOWE POZYCJE ROCZNEGO SPRAWOZDANIA FINANSOWEGO WRAZ Z DANYMI PORÓWNYWALNYMI ................ 4 III. SPRAWOZDANIE FINANSOWE ZA ROK 2010 11 BIT STUDIOS S.A. ........................................ 5 IV. SPRAWOZDANIE ZARZĄDU Z DZIAŁALNOŚCI SPÓŁKI W ROKU 2010....................................
- 11 bit studios S.A. reported a net loss of 231,199.53 PLN for the financial year ending December 31, 2010. This was attributed to lower than projected game production costs for "Anomaly Warzone Earth" and a delay in a planned distribution agreement from Q4 2010 to Q1 2011.
- The company's share capital on December 31, 2010, was 187,076.10 PLN, with a share capital increase from 100,000.00 PLN at the beginning of the period. Total equity stood at 1,268,200.59 PLN.
- 11 bit studios S.A. was founded on December 7, 2009, and its shares (Series A, B, and C) were first listed on the New Connect alternative trading system on January 12, 2011.
- The company signed publishing agreements for "Anomaly Warzone Earth" in early 2011: with Just a Game GmbH for PC and Mac boxed versions worldwide (excluding Poland), and with Licomp Empik Multimedia Sp. z o.o. for PC boxed distribution in Poland.
- "Anomaly Warzone Earth" was released in Poland on May 9, 2011, and in German-speaking countries on May 31, 2011.
+1
11 bit studios
Report86 pages
Consolidated Annual Report 2016: 11 bit studios
Kapitat PISMO ZARZĄDU z nadwyzki rezerwowy Przypadajace Przypadajace Kapitat wartosci Kapitat z tytutu z przeliczenia Zyski akcjonariuszom dziatom podstawowy emisyjnej jednostek Warszawa, 30 marca 2017 roku ponad wartosc zapasowy ptatnosci w zagranicznych i zatrzymane dominujacej kontro nominal...
- 11 bit studios S.A. achieved its best financial year ever in 2016, with revenues reaching PLN 27 million, a 16.6% increase from 2015, and net profit growing by 11.8% to PLN 12.9 million, despite a one-time non-cash write-off of PLN 0.64 million from the Games Republic platform.
- The company's operational profit increased by nearly 3% to PLN 14.1 million in 2016, and it held PLN 29.11 million in cash by the end of December 2016, indicating strong financial health.
- The game "This War of Mine" (TWoM), released in autumn 2014, has generated over PLN 60 million in cumulative revenue, establishing 11 bit studios' brand recognition and financial stability.
- 11 bit studios S.A. is focusing on developing PC games using its proprietary engine, with "Frostpunk" being the main project, scheduled for release in the second half of 2017, with a significantly larger production and marketing budget than TWoM.
- The company's primary activities are the production and sale of multi-platform video games and global digital distribution of video games, with its shares publicly traded since its founding in 2009.
+1
11 bit studios
Report67 pages
Annual Report 2014: 11 bit studios S.A.
I. PISMO ZARZĄDU ........................................................................................................3 II. WYBRANE JEDNOSTKOWE DANE FINANSOWE ZAWIERAJĄCE PODSTAWOWE POZYCJE ROCZNEGO SPRAWOZDANIA FINANSOWEGO WRAZ Z DANYMI PORÓWNYWALNYMI...........4 III. SPRAWOZDANIE FINANSOWE 11 BIT STUDIOS S.A. ZA ROK 2014 ...................................5 IV. SPRAWOZDANIE ZARZĄDU Z DZIAŁALNOŚCI SPÓŁKI W ROKU 2014. ............................. 40 V.
- 11 bit studios S.A. released "This War of Mine" in 2014, a milestone game developed in-house, and also launched "Spacecom" through its 11 bit launchpad publishing division.
- The company's total assets significantly increased from 589,514.42 PLN in 2013 to 1,745,563.16 PLN in 2014, driven by growth in intangible assets (from 466,671.58 PLN to 1,444,226.03 PLN) and tangible assets (from 63,180.84 PLN to 103,579.73 PLN).
- Net profit for 2014 was 890,745.75 PLN, a substantial increase from the previous year, with operating profit at 1,248,589.34 PLN.
- 11 bit studios S.A. generates most of its revenue in foreign currencies (primarily USD), meaning a weaker Polish Zloty positively impacts its income.
- The company faces risks including strong competition from other publishers, increasing competition in the game market, the risk of ideas being copied, and the challenge of keeping up with dynamic market trends like Virtual Reality (VR).
+3
11 bit studios
Report84 pages
Annual Report 2018: 11 bit studios S.A.
wynagrodzenia róznicowana jest w zaleznosci od petnionej funkcji czy zajmowanego stanowiska). Wynagrodzenia uzyskiwane przez osoby zarzadzajace oraz osoby zarzadzajace wyzszego szczebla w Spótce obejmuje wynagradzanie akcjami, opcjami na akcje lub innymi prawami nabycia akcji, jak równiez wynagrodzenie nie jest ustalane w oparciu o zmiany cen akcji. PISMO ZARZĄDU WEWNETRZNEJ I ZARZADZANIA RYZYKIEM Szanowni Akcjonariusze i Inwestorzy raportów finansowych.
- 11 bit studios S.A. had an exceptional year in 2018, driven by the successful launches of "Frostpunk" (April 24) and "Moonlighter" (May 29), both of which quickly became bestsellers on platforms like Steam.
- The company actively supported its top games, "Frostpunk" and "Moonlighter," with significant free DLC releases throughout 2018, including "Survivor Mode," "The Fall of Winterhome," and "Endless Mode" for "Frostpunk," and "The Binding of Will" for "Moonlighter," which boosted sales and player engagement.
- Total capital expenditures on tangible assets (primarily real estate for a new office at Brzeska 2) and intangible assets (primarily game production) significantly increased from PLN 7,372,863 in 2017 to PLN 26,571,879 in 2018.
- NN Investment Partners TFI S.A. increased its stake in 11 bit studios S.A. to 5.21% of the share capital (119,229 shares) on June 15, 2018, up from 4.93% (112,476 shares) previously.
- 11 bit studios S.A. continued its charitable activities in 2018, donating a portion of revenue from the "War Child Charity DLC" for "This War of Mine" to War Child UK, an organization assisting child victims of war.
+1
11 bit studios
Report74 pages
Annual Report 2017: 11 bit studios
2.2. SPRAWOZDANIE Z SYTUACJI FINANSOWEJ (PLN) AKTYWA PISMO ZARZĄDU Nota Stan na Stan na 31.12.2017 31.12.2016 Aktywa trwate Warszawa, 26 marca 2018 roku Rzeczowe aktywa trwate 3.11. 814 332 779 540 Szanowni Akcjonariusze i Inwestorzy 3.12.
- 11 bit studios S.A. focused heavily on "Frostpunk" in 2017, anticipating it will drive financial results for years, with its release scheduled for April 24, 2018.
- The company continued developing "This War of Mine" in 2017, releasing the "Fathers Promise" DLC on November 14, with two more "TWoM: Stories" DLCs planned for 2018. They also began work on a new game, "Projekt 8," involving a 20-person team, to be released after "Frostpunk."
- 11 bit publishing released two external games in 2017: "Beat Cop" (March 30) and "Tower 57" (November 16), with external game sales contributing over 10% to total revenue and recouping investment within months.
- Operating profit for 2017 was 7,619,936 PLN, a 50.69% decrease from 15,454,560 PLN in 2016, despite a 5.64% increase in operating costs to 11,845,351 PLN (from 11,212,540 PLN in 2016) and increased promotional spending.
- 11 bit studios S.A. sold its 100% stake in subsidiary Games Republic Limited to Lousva Trading Limited on April 11, 2017, dissolving the 11 bit studios S.A. Capital Group.
+3
11 bit studios
Report38 pages
Annual Report 2015: Financial Statement
RAPORT ROCZNY11 BIT STUDIOS S.A. SPRAWOZDANIE FINANSOWE 11 BIT STUDIOS S.A. ZA 2015 ROK Pozostate koszty operacyjne 226 247 0,00 226 247 Zysk / (Strata) z dziatalnosci operacyjnej 11 244 147 - 54 945 11 189 201 1.
- 11 bit studios S.A. reported an operating profit of 11,189,201 PLN for the 2015 fiscal year.
- The company's operating profit figure of 11,189,201 PLN was derived from an initial operating profit of 11,244,147 PLN adjusted by 54,945 PLN in losses.
- Other operating costs for the 2015 period totaled 226,247 PLN.
11 bit studios