Report18 pages
Key Insights Into French Gamers
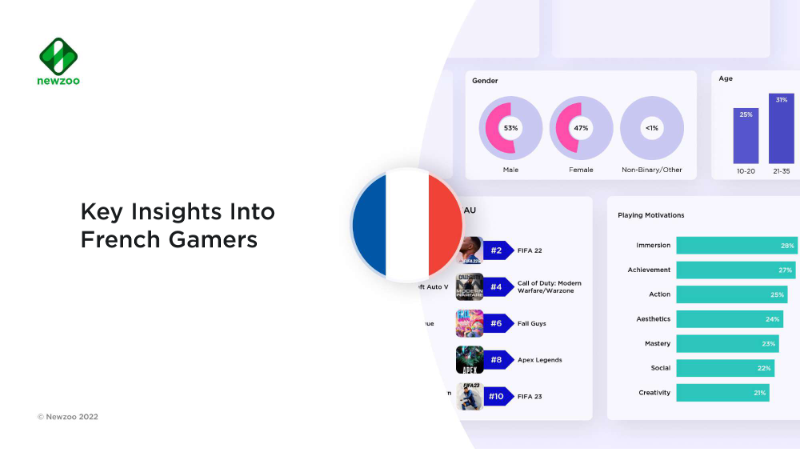
France represents a significant gaming market, ranking seventh globally in terms of revenue and fifteenth in total player count as of 2022. The French gaming population is highly engaged, with 71% of the online population aged 10 to 65 identifying as game enthusiasts. While 38% of this group only plays games, a substantial 34% also views gaming video content, and 15% are classified as esports enthusiasts who watch professional competitive gaming at least once a month.
The demographic profile of French players is nearly balanced by gender, consisting of 52% men and 48% women. The largest age cohort is the 21-35 bracket, representing 31% of the player base. In terms of behavior, Time Fillers and Mainstream Gamers are the most common personas. Time Fillers use games primarily to pass the time and show less interest in viewing content, whereas Mainstream Gamers are deeply invested in both playing and watching gaming media. Mobile is the most popular platform, utilized by 44% of the online population, followed by console at 41% and PC at 30%. Despite mobile's reach, PC players record the highest average weekly playtime at four hours and forty minutes.
Monetization data indicates that 56% of French players are payers, driven primarily by value-based incentives such as sales or special offers. Other significant spending motivators include unlocking exclusive content and the desire to play with friends or family, underscoring the social nature of the market. This analysis is based on a 2022 survey of 2,080 online consumers in France, part of a broader global study covering 36 markets and over 75,000 respondents.
- France is a top-tier global gaming market, ranking seventh in revenue and fifteenth in player count as of 2022.
- The French gaming population is highly engaged, with 71% of online users aged 10–65 identifying as enthusiasts, including 15% who follow esports monthly.
- Mobile is the leading platform with 44% reach, followed by console at 41% and PC at 30%, though PC users record the highest average weekly playtime at four hours and forty minutes.
- The player base is gender-balanced at 52% men and 48% women, with the 21–35 age bracket serving as the largest demographic segment at 31%.
- 56% of French players are payers, with spending primarily motivated by value-based incentives, exclusive content, and social play with friends or family.
NewzooJan 2022
Report11 pages
Key Insights Into Spanish Gamers
Spain represents a significant global gaming market, ranking 13th in the world with an annual revenue of $2.38 billion. The industry maintains a massive reach within the country, as 83% of the online population aged 10 to 65 are classified as game enthusiasts. Engagement is multifaceted, with 82% of the population playing games and 45% viewing gaming content. Notably, there is a high degree of overlap between these behaviors; 38% of the population both plays and watches games, while only 7% are exclusive viewers.
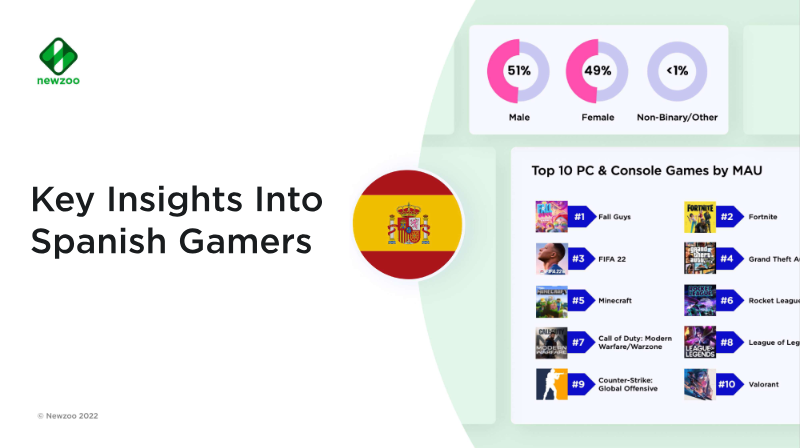
The demographic profile of Spanish gamers is nearly evenly split between genders, with 51% female and 49% male. Participation remains strong across age groups, though it peaks among those aged 21 to 50. Achievement, action, and mastery serve as the primary motivations for play. While mobile is the most popular platform by reach, utilized by 60% of the population, PC and console players demonstrate higher engagement depth, averaging four hours of play per week compared to three hours on mobile.
Market behavior indicates a strong propensity for spending, with 48% of the online population identified as payers. The primary drivers for monetization include sales or special offers and the desire to play with friends or family. In terms of content, the market is dominated by major global franchises such as Fall Guys, Fortnite, and FIFA 22, with adventure and sports ranking as the top genres by monthly active users. These findings are based on a 2022 consumer study involving a sample of 2,086 online respondents in Spain, forming part of a broader global research initiative covering 36 markets.
- Spain is the 13th largest global gaming market, generating $2.38 billion in annual revenue with 83% of the online population aged 10 to 65 identified as enthusiasts.
- The Spanish gaming audience is gender-balanced at 51% female and 49% male, with peak participation occurring between the ages of 21 and 50.
- While mobile is the most popular platform with 60% reach, PC and console users exhibit higher engagement, averaging four hours of weekly play compared to three hours for mobile users.
- Gaming engagement is highly integrated, as 38% of the population both plays and watches gaming content, while only 7% are exclusive viewers.
- 48% of the online population are payers, primarily motivated by sales, special offers, and the desire to play with friends or family.
+1
NewzooJan 2022
Report42 pages
For the Game
The global gaming industry is undergoing a transformative shift into a primary mass medium, projected to reach 3.5 billion players and $225 billion in revenue by 2025. This evolution is characterized by gaming’s role as a central pillar of culture and social connection, with over a third of players utilizing the medium specifically for socialization. Analysis across 21 global markets reveals that gamers are highly engaged "super-consumers" who spend nearly 60 hours a week across television and internet platforms, making them a critical demographic for brand attention.
To effectively reach this audience, the industry must move beyond traditional demographic stereotypes and adopt a motivation-based segmentation. This approach identifies six distinct player types, allowing for more authentic engagement. However, a significant gap remains between the diverse player base and the industry’s internal demographics, which remain predominantly male and white. Prioritizing equity, inclusion, and accessibility is essential for future growth, as evidenced by the commercial success of titles that prioritize inclusive design and representation.
Successful brand integration requires a departure from standard advertising in favor of intrinsic in-game experiences and value-driven partnerships. Strategies such as gamified commerce, immersive virtual events, and the utilization of original intellectual property yield higher attention and recall rates than traditional social media formats. By fostering mutually beneficial relationships and respecting established gaming codes, brands can leverage the medium not just for visibility, but as a sophisticated tool for long-term community building and commercial innovation.
- The global gaming industry is projected to reach 3.5 billion players and $225 billion in revenue by 2025.
- Gamers are high-value 'super-consumers' who engage with television and internet platforms for nearly 60 hours per week.
- Over one-third of the global player base uses gaming primarily as a social platform, necessitating a shift toward community-focused engagement strategies.
- Effective audience targeting requires moving beyond traditional demographics to a motivation-based segmentation model that identifies six distinct player types.
- Internal industry demographics remain predominantly white and male, creating a strategic gap that can be addressed through inclusive design to drive commercial success.
+2
dentsuJan 2022
Report11 pages
Key Insights Into South Korean Gamers
South Korea represents the fourth largest gaming market globally by revenue, valued at $8.3 billion, with a highly engaged population of 33 million gamers. Research conducted in 2022 indicates that 76% of the online population are game enthusiasts who engage with the medium through playing, viewing, or social interaction. While 72% of the population plays games, there is a significant overlap with viewership; 48% of South Koreans both play and watch gaming content, while 22% specifically engage with esports.
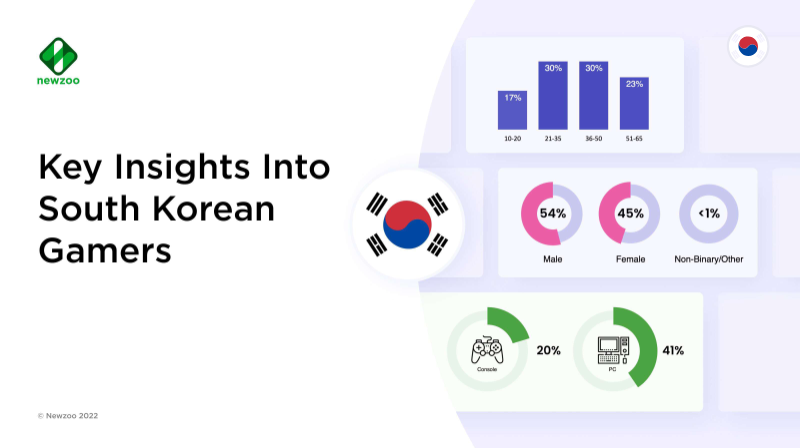
The demographic profile of South Korean gamers is diverse, with a nearly even split between males (54%) and females (45%) and broad representation across age groups, particularly those between 21 and 50. Socializing is the primary motivator for play, followed by action and achievement. Despite the high engagement levels, player personas vary; the most common types are Time Fillers, who play casually to pass the time, and Mainstream Gamers, who invest heavily in both playing and viewing.
Mobile is the dominant platform, utilized by 59% of the online population, though PC players record the highest average weekly engagement at five hours. In terms of software, League of Legends and Shooter genres lead in monthly active users. Monetization is also robust, with 38% of the population spending money on games. The primary drivers for spending include the desire to advance more quickly or easily in-game, followed by responding to sales or special offers.
The findings are based on a 2022 consumer insights survey of 2,094 respondents from the South Korean online population. The data highlights a mature market where gaming is a mainstream social activity integrated into daily life across all demographics, supported by a strong esports culture and a high propensity for in-game spending.
- South Korea is the world's fourth-largest gaming market, generating $8.3 billion in annual revenue from a highly engaged base of 33 million gamers.
- Gaming is a deeply integrated social activity, with 76% of the online population participating, 48% both playing and watching content, and 22% specifically following esports.
- Mobile is the primary platform for 59% of the online population, though PC gamers demonstrate higher engagement with an average of five hours of play per week.
- The player base is demographically balanced, with a 54% male and 45% female split and strong representation across the 21–50 age range.
- Monetization is robust, with 38% of the population spending money on games, primarily driven by the desire for faster progression or to capitalize on special offers.
+1
NewzooJan 2022
Report18 pages
Consumer Insights: Games & Esports 2022
Gaming has evolved into a multi-dimensional entertainment ecosystem where traditional play is no longer the sole driver of engagement. Findings indicate that 79% of the global online population are game enthusiasts, participating through playing, viewing content, or socializing in virtual worlds. This shift is most pronounced among younger generations; for Gen Alpha, gaming has surpassed social media and streaming video as the primary source of entertainment.
The research highlights a significant trend toward the "metaverse," with 75% of players and 44% of non-players engaging in game worlds for social interaction without playing the core game. This high level of engagement translates into substantial economic impact, with consumer spending in the sector projected to exceed $200 billion in 2023. Approximately half of Gen Alpha, Gen Z, and Millennial gamers are already classified as payers, a figure expected to rise as younger cohorts gain independent purchasing power.
Data suggests that gamers are a highly receptive audience for brands, exhibiting 36% more positive attitudes toward brand messaging compared to non-players. However, the diversity of the audience necessitates a nuanced approach. Using proprietary segmentation, the analysis shows that while older generations often act as "Time Fillers," younger audiences are more likely to be "Ultimate Gamers" or "All-Round Enthusiasts." Even within the same genre, such as Battle Royale, player demographics and motivations vary significantly between titles like Fortnite and Apex Legends, affecting their preferences for products like energy drinks or alcohol.
The findings are based on a 2022 study utilizing Computer Assisted Web Interviewing (CAWI) with a representative sample of 75,930 respondents. The scope covers 36 global markets across North America, Europe, Latin America, and Asia-Pacific, targeting the online population aged 10 to 65. Additional sentiment studies on the metaverse and blockchain gaming supplement the core consumer data.
- Gaming has become a primary entertainment ecosystem for 79% of the global online population, with Gen Alpha prioritizing gaming over social media and streaming video.
- Consumer spending in the gaming sector is projected to exceed $200 billion in 2023, driven by a payer base that includes approximately 50% of Gen Alpha, Gen Z, and Millennial gamers.
- Game worlds are increasingly used for social interaction rather than gameplay, with 75% of players and 44% of non-players utilizing these environments for non-gaming social engagement.
- Gamers are a highly receptive audience for advertising, demonstrating a 36% more positive attitude toward brand messaging compared to non-players.
- Audience motivations vary significantly by demographic, with older users often acting as 'Time Fillers' while younger cohorts are more likely to be 'Ultimate Gamers' or 'All-Round Enthusiasts'.
+1
NewzooJan 2022
Report61 pages
The New Destination to Reach Global Gamers: The 2021 Global Mobile Gamers Whitepaper
Mobile gaming represents the largest and fastest-growing segment of the global entertainment industry, generating $93.2 billion in 2021 with a projected trajectory toward $126.1 billion by 2024. Within this landscape, a distinct synergy has emerged between mobile gaming and social media platforms, particularly TikTok, where nearly half of all mobile gamers are active. These users demonstrate significantly higher value than non-users, installing 50% more games, playing 36% longer, and showing a 66% higher likelihood of making in-game purchases. This demographic functions as a highly social and evangelical audience that consumes an average of seven different genres and responds more favorably to innovative advertising formats like sponsored livestreams and user-generated content.
Global player behavior reveals a consistent preference for realistic art styles and fantasy or mystery settings, though regional nuances remain critical for market penetration. While Southeast Asian markets are dominated by MOBA titles, Japanese and South Korean audiences show a marked preference for immersive RPGs and Puzzle RPGs. Across all regions, the primary motivation for gameplay is relaxation or passing time, yet monetization is driven by progression-based incentives, such as the desire to unlock content or bypass difficult levels. This suggests that while the initial draw of a game is often casual, long-term financial viability depends on structured advancement and consistent content updates.
Retention and re-engagement strategies must address the primary drivers of player churn, which are identified as technical bugs and slow leveling speeds. Conversely, the introduction of new missions, story-driven updates, and technical optimizations are the most effective methods for reclaiming lapsed players. To maximize impact, advertisers and developers should prioritize action-packed, narrative-driven creative content that leverages the social metaverse. By focusing on regional aesthetic preferences—such as "cute" or anime styles in Asia versus cartoonish realism in Western markets—and addressing the specific progression needs of players, stakeholders can better navigate the increasingly competitive global mobile gaming ecosystem.
- The global mobile gaming market generated $93.2 billion in 2021 and is projected to reach $126.1 billion by 2024.
- Mobile gamers active on TikTok install 50% more games, play 36% longer, and are 66% more likely to make in-game purchases than non-users.
- While players primarily game to relax or pass time, long-term monetization is driven by progression-based incentives like unlocking content and bypassing difficult levels.
- Technical bugs and slow leveling speeds are the primary drivers of player churn, while new missions and story-driven updates are the most effective methods for re-engagement.
- Regional preferences vary significantly, with MOBA titles dominating Southeast Asia, while Japan and South Korea favor immersive RPGs and Puzzle RPGs.
+2
NewzooJan 2022
Report19 pages
Video Games – A Force for Good: Europe's Video Game Industry
This analysis provides a comprehensive overview of the European video games industry as of 2021, detailing its economic impact, demographic reach, and social contributions. Jointly produced by ISFE and EGDF, the findings highlight a sector that remained stable following the pandemic-induced surge of 2020, maintaining a market value of €23.3 billion across key European territories. The industry supports a significant workforce, employing over 98,000 people across Europe, with 74,000 located within the EU. Data is primarily sourced from Ipsos, GameTrack, and GSD, covering major markets including France, Germany, Italy, Spain, and the United Kingdom.
The demographic data reveals that video gaming is a mainstream cultural activity, with 52% of the European population aged 6 to 64 participating. The average player age is 31.3 years, and women represent nearly 48% of the total player base. While engagement remains high, average weekly playtime returned to pre-pandemic levels of nine hours. The digital ecosystem dominates the market, accounting for 81% of total revenue, driven largely by app-based gaming and in-game extras.
A significant portion of the analysis focuses on industry responsibility and social impact. It underscores the effectiveness of the PEGI age rating system and the prevalence of parental control tools, noting a sharp decline in unsupervised in-game spending by minors. Furthermore, the industry is positioned as a driver for digital literacy and mental well-being, with specific initiatives targeting STEM education for girls and climate change through the Green Game Jam. The report concludes that the sector is a vital component of Europe’s digital economy, increasingly recognized for its pedagogical value and commitment to diversity and environmental sustainability.
- The European video game market maintained a stable value of €23.3 billion in 2021, following the initial pandemic-driven surge.
- The industry employs over 98,000 people across Europe, with 74,000 of those roles based within the EU.
- Digital revenue dominates the sector, accounting for 81% of total market value through app-based gaming and in-game purchases.
- Video gaming is a mainstream activity in Europe, engaging 52% of the population aged 6 to 64 with an average player age of 31.3 years.
- Gender representation in gaming is nearly balanced, with women accounting for 48% of the total player base.
+1
Interactive Software Federation of EuropeJan 2022
Report32 pages
Member Survey & Report 2021
The blockchain gaming industry experienced a transformative period of expansion in 2021, driven primarily by the emergence of play-to-earn mechanics and the implementation of true digital asset ownership. Industry professionals identify these features as the most significant catalysts for growth, with a vast majority anticipating that traditional gaming entities will integrate blockchain technology within the next two years. This momentum is further evidenced by approximately $4 billion in capital inflows from venture firms and decentralized autonomous organizations, signaling strong institutional confidence in the sector’s long-term viability.
Despite this rapid financial and technological acceleration, the industry faces substantial structural headwinds. Regulatory uncertainty remains the most pressing concern for over half of the organizations operating in the space, followed closely by a general lack of public understanding regarding core blockchain concepts. Additionally, the sector must navigate technical challenges related to user-friendliness and a shortage of specialized engineering talent. While environmental sustainability has been a point of external criticism, the industry is actively transitioning toward carbon-neutral protocols and Proof of Stake networks to mitigate its ecological footprint.
The ecosystem is characterized by a diverse and collaborative landscape that spans game studios, major traditional publishers like Ubisoft, and specialized firms in decentralized finance, legal, and infrastructure. While financial incentives have been the primary driver of initial adoption, long-term sustainability is widely believed to depend on the development of high-quality gameplay that can compete with traditional titles. This cross-sector synergy suggests that the future of the industry relies on balancing innovative monetization models with the fundamental entertainment value required for mainstream appeal.
- The blockchain gaming sector saw $4 billion in capital inflows from venture firms and DAOs in 2021, signaling strong institutional confidence in the industry's long-term viability.
- Industry professionals expect traditional gaming entities to integrate blockchain technology within the next two years, driven by the adoption of play-to-earn mechanics and true digital asset ownership.
- Regulatory uncertainty is the primary concern for over 50% of organizations in the space, followed by challenges regarding public education, user-friendliness, and a shortage of specialized engineering talent.
- Long-term industry sustainability is contingent upon shifting from financial-incentive models to the development of high-quality gameplay that competes directly with traditional titles.
- The industry is actively addressing environmental criticism by transitioning toward carbon-neutral protocols and Proof of Stake networks.
+1
Blockchain Game AllianceDec 2021
Report52 pages
Swedish Games Industry 2021
The Swedish games industry experienced a transformative period of growth in 2020, reaching a record revenue of EUR 3.3 billion. This 43% increase significantly outpaced global market trends, marking the sector's twelfth consecutive year of profitability. The landscape is increasingly defined by corporate consolidation and international expansion, with 667 active companies and 19 listed entities commanding a combined market capitalization of EUR 10.7 billion. Major players such as Embracer Group, King, and Mojang have transitioned Sweden from a target for foreign acquisition into a dominant global investor, with Swedish-owned firms now employing more personnel abroad than domestically across 126 international studios.
Despite this commercial success, the industry faces a critical bottleneck regarding skilled labor. While domestic employment rose to over 6,500 positions, a severe talent shortage and a cumbersome work permit process hinder further expansion. These systemic issues are compounded by a lack of early-stage financing and tax incentives for smaller developers, who must also navigate digital regulations often tailored for larger tech platforms. Furthermore, while Swedish-developed titles like Minecraft and Candy Crush have achieved over six billion downloads, the sector continues to grapple with internal demographic challenges. Women currently represent only 21% of the workforce, and over 100 companies remain entirely male-operated, prompting a surge in diversity initiatives aimed at leveling the playing field.
Geographically, while Stockholm remains the primary hub with over 4,000 employees, regional development clusters and educational programs are expanding throughout Sweden to support the growing ecosystem. The industry is also pivoting toward long-term sustainability, addressing workplace culture and the environmental implications of energy-intensive cloud gaming. As the sector matures, its primary challenges have shifted from achieving market viability to managing rapid globalization, securing specialized talent, and fostering a more inclusive and sustainable professional environment.
- The Swedish games industry reached a record revenue of EUR 3.3 billion in 2020, marking a 43% growth rate and the sector's twelfth consecutive year of profitability.
- Sweden has shifted from an acquisition target to a global investor, with 19 listed entities commanding a combined market capitalization of EUR 10.7 billion and Swedish-owned firms operating 126 international studios.
- A severe talent shortage and restrictive work permit processes are critical bottlenecks, despite domestic employment rising to over 6,500 positions.
- The workforce faces significant demographic imbalances, with women representing only 21% of employees and over 100 companies remaining entirely male-operated.
- Stockholm remains the primary industry hub with over 4,000 employees, though development clusters are expanding regionally to support the growing ecosystem.
+1
DataspelsbranschenOct 2021
Presentation17 pages
Prezentacja Wyników Q3 2021
The financial results for PCF Group (People Can Fly) through the third quarter of 2021 reflect a period of significant scaling and strategic expansion. The group reported a 66.2% year-over-year increase in revenue, reaching 131.8 million PLN, while net profit rose by 112.6% to 46.4 million PLN. This growth was accompanied by a substantial increase in cash reserves, which grew by 262.6% to 149.8 million PLN, and a 62.7% expansion of the workforce to over 450 employees across global hubs including Warsaw, New York, and Montreal.
The operational focus centered on the continued development of the Outriders franchise and the diversification of the production pipeline. Following the release of the New Horizon update, the game saw a significant resurgence in player engagement, including a peak of over 10,000 concurrent users on Steam and an increase in positive player sentiment to 80%. Looking forward, the group is developing several major projects: Project Gemini with Square Enix and Project Dagger with Take-Two Interactive, both slated for 2024, alongside a self-published original IP and two additional projects in the conceptual phase.
The updated corporate strategy aims to establish the group as a leading independent developer capable of releasing at least one game annually starting in 2024. This roadmap includes expanding into new genres and the "compact AAA" segment. Financial stability is supported by a shift in revenue structure, where development services remain the primary driver, supplemented by royalties. The group’s methodology for these results follows IFRS standards, with adjusted EBITDA figures accounting for IPO costs and stock-based compensation to provide a normalized view of operational performance.
- PCF Group achieved significant financial growth in Q3 2021, with revenue increasing 66.2% year-over-year to 131.8 million PLN and net profit rising 112.6% to 46.4 million PLN.
- The company is executing a strategic roadmap to release at least one game annually starting in 2024, focusing on the 'compact AAA' segment and genre diversification.
- Development is underway for major titles including Project Gemini with Square Enix and Project Dagger with Take-Two Interactive, both targeted for 2024 release.
- Cash reserves grew by 262.6% to 149.8 million PLN, while the workforce expanded by 62.7% to over 450 employees across global hubs in Warsaw, New York, and Montreal.
- The Outriders franchise saw a resurgence in engagement following the New Horizon update, reaching a peak of over 10,000 concurrent users on Steam and achieving an 80% positive sentiment rating.
+1
PCF GroupOct 2021
Report16 pages
Strategy Genre Snapshot: October 2021
The strategy genre represents a cornerstone of the mobile gaming market, accounting for approximately 17% of total revenue on the US iOS platform as of October 2021. Analysis reveals that the genre is heavily dominated by the 4X strategy subgenre, which comprises 20 of the top 25 grossing strategy titles. While the market is characterized by aging hits and high competition, recent success has been driven by genre-blending, where developers integrate mechanics from other categories—such as merge, match-3, or RPG elements—to broaden player appeal.
Key market leaders include State of Survival, which became the top-grossing 4X title following a massive year-long collaboration with The Walking Dead, and Supercell, which remains the primary outlier succeeding with non-4X strategy titles like Clash of Clans. In contrast, the MOBA subgenre continues to face sustainability challenges in the US; despite a strong launch, League of Legends: Wild Rift struggled to maintain a position in the top 200 grossing charts, leaving the long-term viability of newer entries like Pokémon UNITE uncertain.
The core appeal of the genre is rooted in long-term power progression, complex live operations, and deep social integration. Data indicates that successful titles leverage permanent boosts, recurring event loops, and competitive guild mechanics to drive engagement. According to a survey of over 7,000 mobile gamers in English-speaking Western markets, the primary motivational drivers for strategy players are strategic planning, resource optimization, and social competition. These findings suggest that while the 4X subgenre remains the revenue leader, the path to growth lies in sophisticated monetization through battle passes and the continuous expansion of social and competitive features.
- As of October 2021, the strategy genre accounts for 17% of total mobile revenue on the US iOS platform, with 4X titles occupying 20 of the top 25 grossing spots.
- Genre-blending is the primary growth strategy, with developers integrating merge, match-3, and RPG mechanics to broaden appeal beyond traditional 4X gameplay.
- State of Survival leads the 4X market following a year-long collaboration with The Walking Dead, while Supercell remains the primary outlier succeeding with non-4X titles like Clash of Clans.
- The MOBA subgenre faces significant sustainability challenges in the US, as evidenced by League of Legends: Wild Rift failing to maintain a top 200 grossing position.
- Strategy players are primarily motivated by strategic planning, resource optimization, and social competition, according to a survey of over 7,000 mobile gamers in Western markets.
+1
VungleOct 2021
Report16 pages
Strategy Genre Snapshot 2021
The strategy genre remains a cornerstone of the mobile gaming market, currently ranking as the third-largest genre in the United States on iOS with a 17% revenue market share. The landscape is heavily dominated by the 4X strategy subgenre, which accounts for 20 of the top 25 grossing strategy titles. While the market is crowded with aging titles, recent growth is driven by genre-blending, where developers integrate mechanics from other categories—such as merge, match-3, or RPG elements—to broaden player appeal.
Market analysis reveals that 4X strategy games rely on three primary pillars: long-term power progression through permanent boosts and deep economies, complex live operations featuring recurring events, and robust social frameworks centered on competition and collaboration. High-performing examples include State of Survival, which reached the top of the 4X subgenre through massive IP collaborations, and Top War, which successfully scaled using merge mechanics. Conversely, the MOBA subgenre continues to face challenges in the U.S. market; despite a strong launch, League of Legends: Wild Rift struggled to maintain its top-grossing position, leaving the subgenre's future performance to newer entries like Pokémon UNITE.
Player motivation data, derived from a survey of over 7,000 respondents across English-speaking Western territories, indicates that strategy players are primarily driven by strategic planning, resource optimization, and social competition. Successful titles capitalize on these drivers by offering deep technology trees, competitive guild mechanics, and diverse PvP modes. While Supercell remains the only major player finding significant success outside the 4X subgenre with titles like Clash of Clans, the broader trend suggests that sustained revenue in this space requires a sophisticated mix of deep monetization loops and constant feature innovation.
- The 4X subgenre dominates the U.S. mobile strategy market, accounting for 20 of the top 25 grossing titles within a genre that holds a 17% total iOS revenue share.
- Successful strategy titles are increasingly driven by genre-blending, integrating mechanics like merge, match-3, or RPG elements to expand their player base beyond traditional core audiences.
- High-performing 4X games rely on three core pillars: long-term power progression through deep economies, complex live operations with recurring events, and social frameworks built on competition and collaboration.
- Player motivation data from over 7,000 Western respondents confirms that strategic planning, resource optimization, and social competition are the primary drivers for engagement in the genre.
- While Supercell remains a notable exception with Clash of Clans, the broader strategy market is currently defined by aging titles that require constant feature innovation and deep monetization loops to maintain revenue.
GameRefineryOct 2021
Report91 pages
Sports & Racing Games Report: Q3 2021
The sports and racing gaming sectors experienced a transformative period throughout 2020 and early 2021, characterized by a 40.2% year-over-year revenue increase to $2 billion. This growth was underpinned by a clear bifurcation in market dynamics: while realistic sports and racing titles consistently outperformed arcade-style counterparts in revenue generation, arcade games maintained higher download volumes. The industry remains highly concentrated, with a small cohort of major publishers—including Electronic Arts, Konami, Tencent, and Zynga—exerting significant control over both market share and intellectual property. Strategic consolidation through high-profile mergers and acquisitions, such as the integration of Glu Mobile and Codemasters into Electronic Arts, reflects a broader industry trend toward portfolio expansion and market dominance.
Geographic performance reveals distinct regional preferences that dictate global revenue flows. The United States remains the primary revenue driver for Western-centric sports and drag racing, while Japan serves as the critical hub for baseball and soccer titles. Conversely, emerging markets such as India and Brazil lead in total download volume, highlighting a disparity between user acquisition and monetization potential. Within the racing segment, kart racing has emerged as a superior model for long-term player retention and balanced gender demographics, contrasting with the gradual revenue decline observed in racing simulators since late 2019.
Despite a temporary pandemic-induced surge in arcade racing downloads during 2020, the market has largely normalized to pre-pandemic levels. The sports manager sub-genre exemplifies the industry’s shift toward high-value monetization, as it has successfully increased net revenue despite a multi-year decline in download volume. Ultimately, the sector is defined by a reliance on established intellectual property and a strategic focus on realistic simulation, with revenue spikes frequently tethered to the launch of major new titles. These trends underscore a mature, consolidated market where success is increasingly dependent on publisher scale and the ability to sustain engagement within specific, high-performing sub-genres.
- The sports and racing sectors saw a 40.2% year-over-year revenue increase to $2 billion between 2020 and early 2021.
- Market power is highly concentrated among major publishers like Electronic Arts, Konami, Tencent, and Zynga, who are driving growth through strategic acquisitions such as Glu Mobile and Codemasters.
- Realistic simulation titles consistently outperform arcade-style games in revenue, while arcade games continue to lead in total download volume.
- The United States remains the primary revenue driver for Western-centric titles, whereas India and Brazil lead in download volume, revealing a significant gap between user acquisition and monetization.
- Sports manager games have successfully increased net revenue despite a multi-year decline in download volume, signaling a shift toward high-value monetization strategies.
+1
Sensor TowerSept 2021
Presentation17 pages
Omówienie wyników H1 2021
PCF Group S.A. presents a comprehensive financial and operational overview for the first half of 2021, highlighting a period of significant scaling and strategic evolution. The group reported a 47% year-over-year increase in revenue, reaching 77.3 million PLN, while EBITDA rose by 36.5% to 28.8 million PLN. Net profit for the period grew by 25.4% to 21.7 million PLN. This financial growth was accompanied by a substantial expansion of the workforce, which increased by nearly 42% to over 420 employees across global hubs including Warsaw, New York, and Montreal.
The strategic focus centers on transitioning toward a dual-model production cycle involving both major publisher partnerships and self-publishing. Key projects include continued support for Outriders, despite publisher reports indicating no royalties were earned in the first quarter post-launch. Future growth is anchored by Project Gemini with Square Enix and Project Dagger with Take-Two Interactive, both slated for 2024 releases. Additionally, the group is developing a new proprietary IP funded internally and exploring two conceptual projects.
Geographically, the group has strengthened its North American presence, with 120 employees now based in that region. This expansion is supported by a robust cash position of 150.3 million PLN, representing a 263.9% increase from the end of 2020. The long-term objective is to achieve a position as a leading independent global developer, targeting annual game releases starting in 2024 through the development of the PCF Framework and potential future acquisitions.
- PCF Group achieved strong H1 2021 financial growth, with revenue rising 47% to 77.3 million PLN, EBITDA up 36.5% to 28.8 million PLN, and net profit increasing 25.4% to 21.7 million PLN.
- The company is scaling its global operations, increasing its workforce by 42% to over 420 employees and significantly strengthening its North American presence with 120 staff members.
- Strategic growth is anchored by two major publisher-partnered titles, Project Gemini with Square Enix and Project Dagger with Take-Two Interactive, both scheduled for release in 2024.
- The group is transitioning toward a dual-model production strategy that combines major publisher partnerships with internal self-publishing of new proprietary IP.
- Financial stability is supported by a robust cash position of 150.3 million PLN, representing a 263.9% increase compared to the end of 2020.
+1
PCF GroupSept 2021
Report21 pages
Gaming Deals Activity Report Q1‑Q3 ’21
The global video games industry experienced a period of significant financial expansion during the first three quarters of 2021, characterized by a 2.5x year-over-year growth in cumulative deal value. Total closed transactions reached $57.7 billion across 667 deals, nearly tripling the $22.7 billion recorded during the same period in 2020. This surge was driven by a robust performance in mergers and acquisitions, which accounted for 48% of total value, followed by public offerings at 37% and private investments at 15%.
The gaming segment remained the primary driver of activity, representing 75% of total deal value. Mobile gaming emerged as a particularly dominant force, contributing 84% of M&A value in the third quarter alone, highlighted by Electronic Arts’ $1.4 billion acquisition of Playdemic. While public offerings faced a cooling period in the third quarter due to market turbulence and share price declines among industry leaders, the period still saw massive exits, including the $3.75 billion IPO of Krafton. Private placements also hit record levels, with late-stage funding rounds for companies like Sorare and Discord signaling sustained investor confidence.
A notable shift in the industry landscape is the rapid ascent of blockchain gaming. This sub-sector saw a 34x year-over-year increase in deal value, reaching $1.56 billion. Investment is currently concentrated in companies building platform layers and infrastructure for non-fungible tokens and play-to-earn models. Geographically, China remained a focal point for strategic activity, largely led by Tencent, which closed 69 deals during the nine-month period.
The data is compiled through the tracking of closed transactions across the gaming, platform, tech, and esports segments, excluding pure gambling and betting. Methodology involves a combination of public media monitoring, business partner insights, and S&P Capital IQ data. The findings suggest that despite a slight quarterly deceleration in public markets, the broader gaming ecosystem continues to attract record-breaking capital from both venture funds and strategic corporate investors.
- The global video games industry saw a 2.5x year-over-year increase in deal value, totaling $57.7 billion across 667 closed transactions during the first three quarters of 2021.
- Mergers and acquisitions dominated the market, accounting for 48% of total deal value, with mobile gaming specifically driving 84% of M&A value in Q3, exemplified by Electronic Arts' $1.4 billion acquisition of Playdemic.
- Blockchain gaming experienced explosive growth, recording a 34x year-over-year increase in deal value to reach $1.56 billion, with investment focused on NFT infrastructure and play-to-earn platforms.
- Public offerings contributed 37% of total deal value, highlighted by the $3.75 billion IPO of Krafton, despite a cooling trend in the third quarter due to market turbulence.
- Tencent remained a primary strategic force in the industry, closing 69 deals during the nine-month period to maintain China's position as a focal point for investment.
+1
InvestGameSept 2021
Report3 pages
India Market Update: September 2021
The Indian gaming and esports landscape is undergoing a period of rapid institutional growth and diversification, characterized by significant foreign investment and the expansion of domestic infrastructure. During the 2021 period, international developers such as Sumo Digital, Kwalee, and CrazyLabs have deepened their commitment to the region. Sumo Digital’s establishment of a second studio in Bangalore and the expansion of its Pune facility highlight a strategic shift toward utilizing India as a hub for end-to-end creative development rather than just a support center. This trend aligns with forecasts predicting substantial increases in India’s online population, player base, and total number of paying users over the next four years.
The mobile gaming sector remains a primary driver of market activity, though it faces operational hurdles. Krafton’s Battlegrounds Mobile India has seen explosive growth but must navigate the technical challenge of maintaining competitive integrity. The company has permanently sanctioned over 1.52 million accounts to combat cheating, illustrating the friction between accessibility in free-to-play titles and the necessity of robust anti-cheat measures. Simultaneously, the real-money and fantasy gaming segments are accelerating, evidenced by Mobile Premier League reaching a $2.3 billion valuation following a $150 million Series E funding round intended to fuel global expansion into markets like the United States.
The esports ecosystem is maturing through consolidation and the convergence of gaming with broader entertainment sectors. Market leader NODWIN Gaming has expanded its reach into the casual and mid-core demographics by acquiring OML Entertainment’s IP business and partnering with PVR Cinemas to pilot in-theater esports viewing. These moves signify a transition toward a more integrated media model where gaming, music, and comedy intersect to drive brand engagement. Overall, the Indian market is evolving into a sophisticated environment defined by high-value capital raises, localized content strategies, and the professionalization of the broader creator economy.
- India is transitioning from a support-focused hub to a center for end-to-end creative development, evidenced by Sumo Digital expanding its Bangalore and Pune facilities.
- Mobile Premier League achieved a $2.3 billion valuation following a $150 million Series E funding round, signaling significant investor confidence in the real-money and fantasy gaming segments.
- Krafton’s Battlegrounds Mobile India has permanently banned over 1.52 million accounts to address cheating, highlighting the operational challenges of maintaining competitive integrity in high-growth free-to-play titles.
- NODWIN Gaming is diversifying its esports model by acquiring OML Entertainment’s IP business and partnering with PVR Cinemas to bring esports content into theater environments.
- International developers including Sumo Digital, Kwalee, and CrazyLabs are deepening their strategic commitments to the Indian market in anticipation of growth in the online population and paying user base.
NewzooSept 2021
Report22 pages
Shooter Genre Snapshot: September 2021
Shooter Genre Snapshot – September 2021 (GameRefinery)
1. Market Overview | Metric | Insight | |--------|----------| | Genre rank (US iOS) | 6th largest mobile genre, ~6 % of total iOS revenue. | | Revenue share | The “Big Three” – Call of Duty: Mobile, PUBG Mobile, and Garena Free Fire – generate > 84 % of shooter revenue. | | Impact of Fortnite removal | Apple‑Epic lawsuit (Fortnite removed Aug 2020) erased a game that once held ~30 % of the shooter market on iOS. | | Growth leader | Garena Free Fire doubled its iOS revenue in 2021, climbing from ~10 % to ~30 % market share and now rivals CoD Mobile for the top spot (Q2 2021). | | New‑entry stagnation | No shooter launched in the last 2 years cracked the top‑grossing 200; only Bullet Echo (May 2020) entered the top‑500. |
2. Top‑Performing Titles (US iOS – Q2 2021)
| Rank | Game | Publisher | Sub‑genre | Share | |------|------|-----------|-----------|-------| | 1 | Garena Free Fire – 4th Anniversary | Garena International | Battle‑Royale | 28.56 % | | 2 | Call of Duty: Mobile | Activision | Classic FPS/TPS | 28.17 % | | 3 | PUBG Mobile – Ignition | Tencent | Battle‑Royale | 26.55 % | | 4 | War Robots | Pixonic | Tactical Shooter | 3.5 % | | 5 | Sniper 3D | Fun Games | Sniper | 3.5 % | | 6 | Pixel Gun 3D | Cubic Games | Classic FPS/TPS | 2.12 % | | 7 | War Machines: Tank | Fun Games | Tactical Shooter | 1.9 % | | 8 | Zooba: Zoo Battle Royale | Wildlife Studios | Battle‑Royale | 1.88 % | | 9 | World of Tanks Blitz | Wargaming | Tactical Shooter | 1.61 % | | 10| Tacticool | – | – | ~1 % |
Key takeaway: The top three dominate ~83 % of the genre’s revenue; the rest of the field is highly fragmented.
3. Why the “Big Three” Stay on Top
| Driver | How It’s Implemented | |--------|----------------------| | Battle Pass | Seasonal “free + paid” tracks that reward playtime, cosmetics, and progression. | | Limited‑time Gachas | Time‑bound loot‑box style draws with increasing price/odds, often tied to events or milestones. | | Live Events & New Modes | Frequent, high‑visibility updates (e.g
- The shooter genre on US iOS is highly concentrated, with the 'Big Three'—Garena Free Fire, Call of Duty: Mobile, and PUBG Mobile—collectively generating over 84% of total genre revenue.
- Garena Free Fire experienced significant growth in 2021, doubling its iOS revenue and capturing approximately 30% of the market share to rival Call of Duty: Mobile for the top position as of Q2 2021.
- The shooter genre accounts for roughly 6% of total US iOS revenue, currently ranking as the platform's 6th largest mobile genre.
- The removal of Fortnite from the App Store in August 2020 eliminated a title that previously commanded approximately 30% of the iOS shooter market.
- New-entry performance is stagnant, as no new shooter titles launched in the two years prior to September 2021 have cracked the top 200 grossing list.
+1
GameRefinerySept 2021
Report34 pages
Global Mobile Market Report 2021
The 2021 global mobile market analysis underscores a rapidly expanding ecosystem in which smartphone ubiquity, rising active‑device counts, and the early rollout of 5G networks are driving unprecedented growth in mobile gaming. By integrating socio‑economic indicators, device‑usage data from more than 400 million monthly active devices, and revenue tracking from major app‑store partners, the study projects that mobile‑game spending will climb from $90.7 billion in 2021 to $116.4 billion by 2024, reflecting an 11.2 % compound annual growth rate. Smartphone penetration reached 3.9 billion users in 2021, a 6 % year‑over‑year increase, while 5G‑ready devices are beginning to reshape gameplay experiences and monetisation models.
Regulatory shifts, notably Apple’s App‑Tracking Transparency and Google’s parallel privacy policies, together with the high‑profile Apple‑Epic litigation, are redefining user‑acquisition strategies and prompting developers to explore platform‑driven revenue streams such as in‑game advertising, subscriptions, and direct storefronts. Revenue distribution remains heavily skewed: the top 20 % of spenders—players who spend $25 or more per month—account for roughly 80 % of total income, favouring socially rich, competitive titles and showing greater openness to ads and subscription offers.
A consumer survey of 5,400 gamers aged 10‑50 across the United States, China, Germany, and Japan reveals modest regional variation in intellectual‑property preferences, suggesting that aligning established entertainment IPs—books, comics, movies, and TV series—with appropriate game genres can enhance engagement. Overall, the findings highlight a market poised for continued expansion, driven by technological adoption, evolving privacy landscapes, and a concentrated core of high‑value players.
- Mobile game spending is projected to grow from $90.7 billion in 2021 to $116.4 billion by 2024, representing an 11.2% compound annual growth rate.
- The top 20% of players, defined as those spending $25 or more per month, generate approximately 80% of total mobile gaming revenue.
- Smartphone penetration reached 3.9 billion users in 2021, marking a 6% year-over-year increase that continues to drive market expansion.
- Regulatory changes, including Apple’s App-Tracking Transparency and Google’s privacy policies, are forcing developers to pivot toward in-game advertising, subscriptions, and direct storefronts for user acquisition.
- The rollout of 5G-ready devices is actively reshaping mobile gameplay experiences and monetization models.
NewzooSept 2021
Report39 pages
Global Cloud Gaming Report: The Infrastructure Edition 2021
This analysis provides a comprehensive overview of the cloud gaming sector in 2021, focusing on how network infrastructure and global economic conditions have accelerated industry adoption. The primary thesis asserts that while the COVID-19 pandemic provided an initial surge in engagement, the market is now transitioning toward sustainable growth driven by technological maturity, strategic business partnerships, and a global semiconductor shortage that has made cloud streaming a viable alternative to expensive, unavailable local hardware.
The scope of the research is global, with specific emphasis on ten subregions and thirty-three individual markets, including deep dives into China, North America, and Western Europe. Data was gathered through a proprietary model incorporating internet connection speeds, urbanization rates, and service availability, supplemented by a July 2021 survey of 6,788 gamers across China, Germany, Japan, and the United States. The methodology utilizes three forecasting scenarios—base, optimistic, and pessimistic—to account for the inherent volatility of a nascent technology market.
Key findings indicate that the global cloud gaming market reached $1.6 billion in revenues and 23.7 million paying users in 2021. Projections suggest significant expansion, with revenues expected to exceed $6.5 billion and paying users reaching 60.7 million by 2024. While North America and Europe currently account for 59% of consumer spending, emerging markets in Asia-Pacific, Latin America, and the Middle East are poised for rapid growth due to the rollout of 5G infrastructure and high consumer interest in regions where gaming hardware is prohibitively expensive.
The analysis concludes that the industry is moving toward a more frictionless user experience through edge computing and B2B partnerships between service providers and telecommunications companies. Despite the closure of some first-party studios, investment remains high among stakeholders like NVIDIA, Haima Cloud, and now.gg. Consumer sentiment remains positive, characterized by high satisfaction levels and low churn, though long-term success depends on overcoming hardware ownership preferences and continuing to improve global network stability.
- The global cloud gaming market reached $1.6 billion in revenue and 23.7 million paying users in 2021, with projections estimating growth to over $6.5 billion and 60.7 million users by 2024.
- North America and Europe currently dominate the sector, accounting for 59% of total consumer spending.
- The global semiconductor shortage has acted as a catalyst for cloud gaming adoption by positioning streaming services as a viable alternative to scarce and expensive local hardware.
- Rapid growth is expected in Asia-Pacific, Latin America, and the Middle East, driven by the rollout of 5G infrastructure and high demand in regions where local gaming hardware is cost-prohibitive.
- Industry stakeholders, including NVIDIA, Haima Cloud, and now.gg, are prioritizing edge computing and B2B partnerships with telecommunications companies to improve service stability and user experience.
+1
NewzooSept 2021
Report26 pages
Mobile Game Genre Report: Puzzle Games
This analysis examines the mobile puzzle game market, contrasting dynamics between Western and Eastern regions with a focus on the United States, United Kingdom, Japan, and South Korea. In 2021, mobile emerged as the primary gaming platform globally, with puzzle games representing a significant 8% of total mobile game revenues, totaling $6.9 billion in 2020. The United States leads as the largest market for the genre ($2.0 billion), followed by Japan ($1.2 billion) and China ($0.9 billion).
While puzzle games are the most popular genre across all surveyed markets, regional player behaviors and monetization preferences vary significantly. In the West, players favor casual experiences and show a higher tolerance for in-app advertising (IAA). Conversely, Eastern markets, particularly Japan, demonstrate a higher propensity for in-app purchases (IAP) and deeper engagement with character collection, progression mechanics, and "gacha" systems. Demographically, puzzle gamers worldwide skew female and hold mid-to-high incomes, though players in the East tend to be younger and more highly educated than their Western counterparts.
The findings highlight a shift toward hybrid monetization models that combine IAP, IAA, and subscription-based "Battle Passes." While classic Match-3 remains the dominant subgenre, developers are increasingly integrating "meta" elements such as narrative, decoration, and RPG mechanics to drive retention. Successful global expansion requires localized user acquisition strategies; for instance, Japanese players respond better to longer intervals between ads and collaborative events with popular anime IPs, whereas U.S. marketing often benefits from performance-based ads and localized creative content. The data suggests that while the core appeal of puzzle solving is universal, long-term commercial success depends on tailoring the in-game economy and social engagement tools to specific regional expectations.
- The global mobile puzzle game market generated $6.9 billion in 2020, with the United States leading at $2.0 billion, followed by Japan at $1.2 billion and China at $0.9 billion.
- Puzzle games account for 8% of total mobile game revenue and represent the most popular genre across the United States, United Kingdom, Japan, and South Korea.
- Western markets favor casual experiences and in-app advertising (IAA), whereas Eastern markets demonstrate a higher propensity for in-app purchases (IAP) and complex mechanics like gacha systems.
- Developers are increasingly integrating 'meta' elements—such as narrative, decoration, and RPG mechanics—into classic Match-3 gameplay to improve player retention.
- Successful monetization is shifting toward hybrid models that combine IAP, IAA, and subscription-based 'Battle Passes' to maximize revenue.
+3
Newzoo & PangleAug 2021