More from Homo Ludens
View all
Report
Historical Game Consulting: A Modular Syllabus
Homo Ludens · 2025
Report
Historical Game Consulting: A Modular Syllabus
Homo Ludens · 2025
Report
Historical Consulting for Analog Games in Poland and in Context
Homo Ludens · 2025
Report
Historical Consultants in the CEE Video Game Industry: Part 2: Competence Building
Homo Ludens · 2025
Article
On the So-Called Politeness Game, Distance Shortening and Communication Effectiveness in (New-)Polish
Homo Ludens · 2024
Article
Researching Historical Consultancy in the CEE Region and in Global Context
Homo Ludens · 2024
Article
Performatyka i gry komputerowe w służbie edukacji. Wprowadzenie do zagadnienia
Homo Ludens · 2024
Article
Board Game Instruction's Genre
Homo Ludens · 2024
Whitepaper
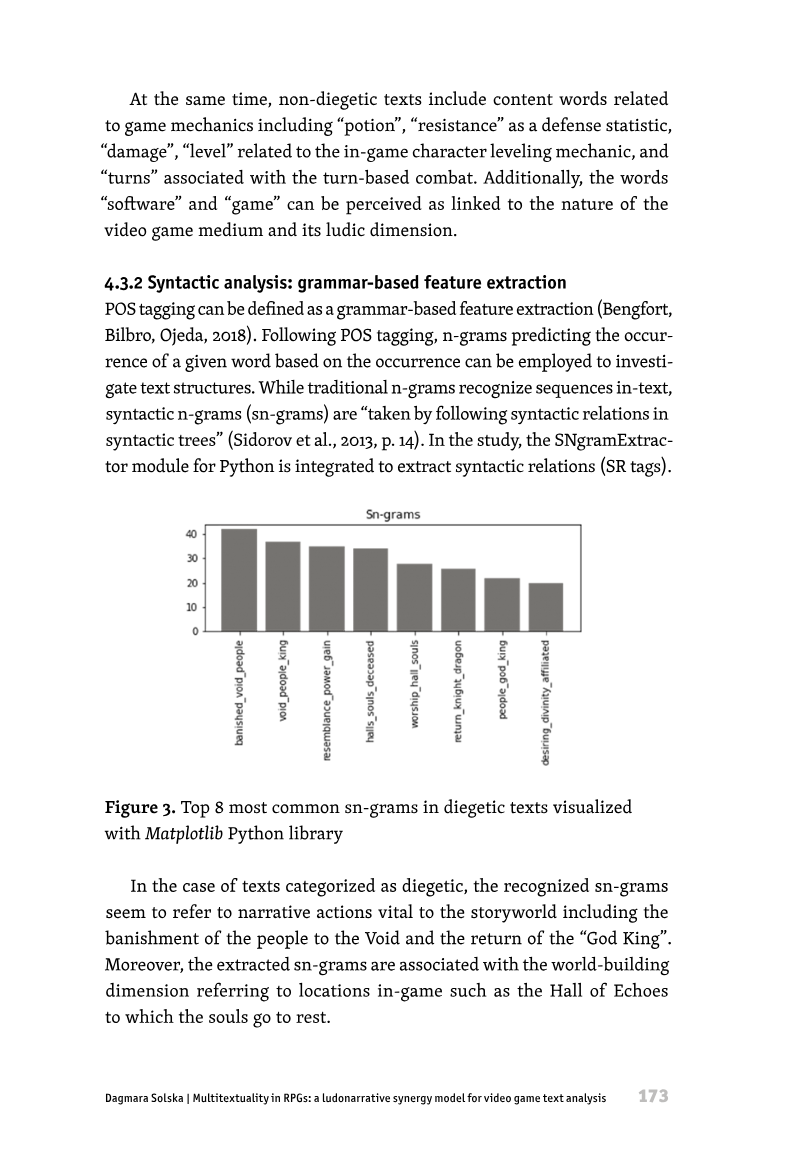
Multitextuality in RPGs: A Ludonarrative Synergy Model for Video Game Text Analysis
Homo Ludens · 2024
Article
Does Minecraft Support Endangered Languages?
Homo Ludens · 2024
Whitepaper
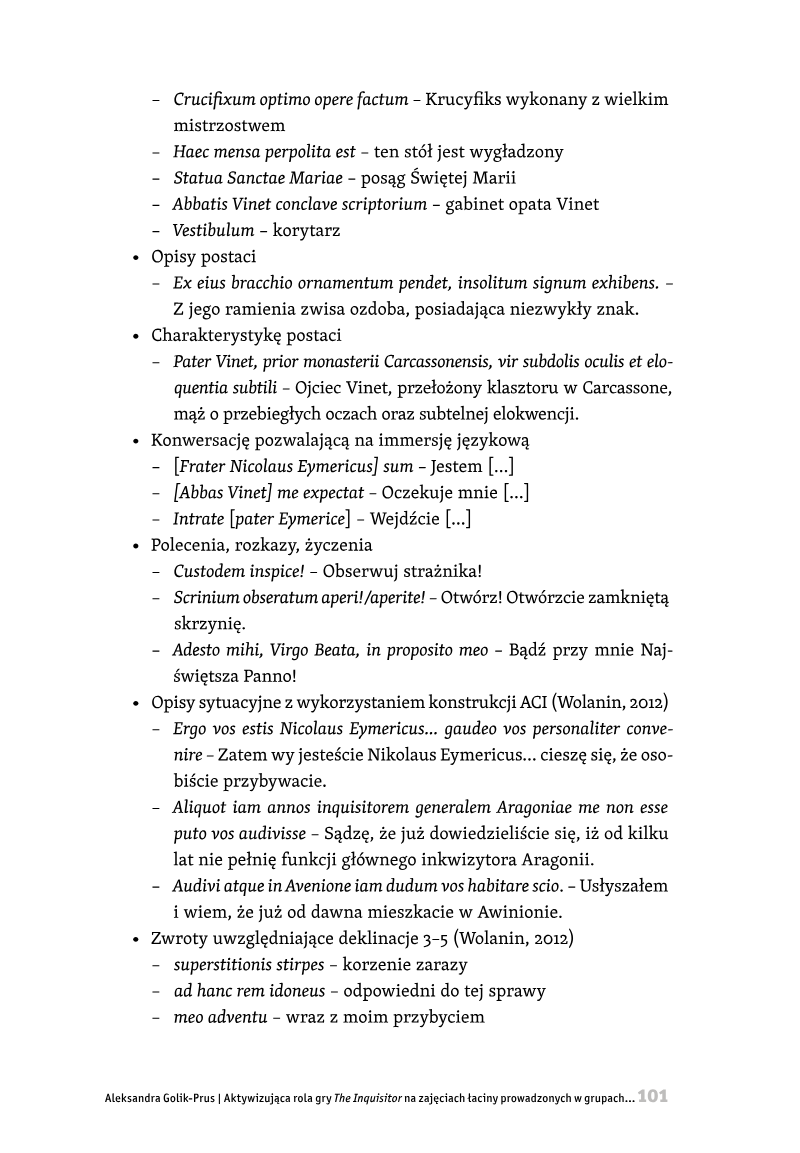
Aktywizująca Rola Gry the Inquisitor Na Zajęciach Łaciny Prowadzonych w Grupach o Specjalności Projektowanie Rozrywki Interaktywnej Oraz Lokalizacja Gier i Oprogramowania Spring-Write
Homo Ludens · 2024
Report
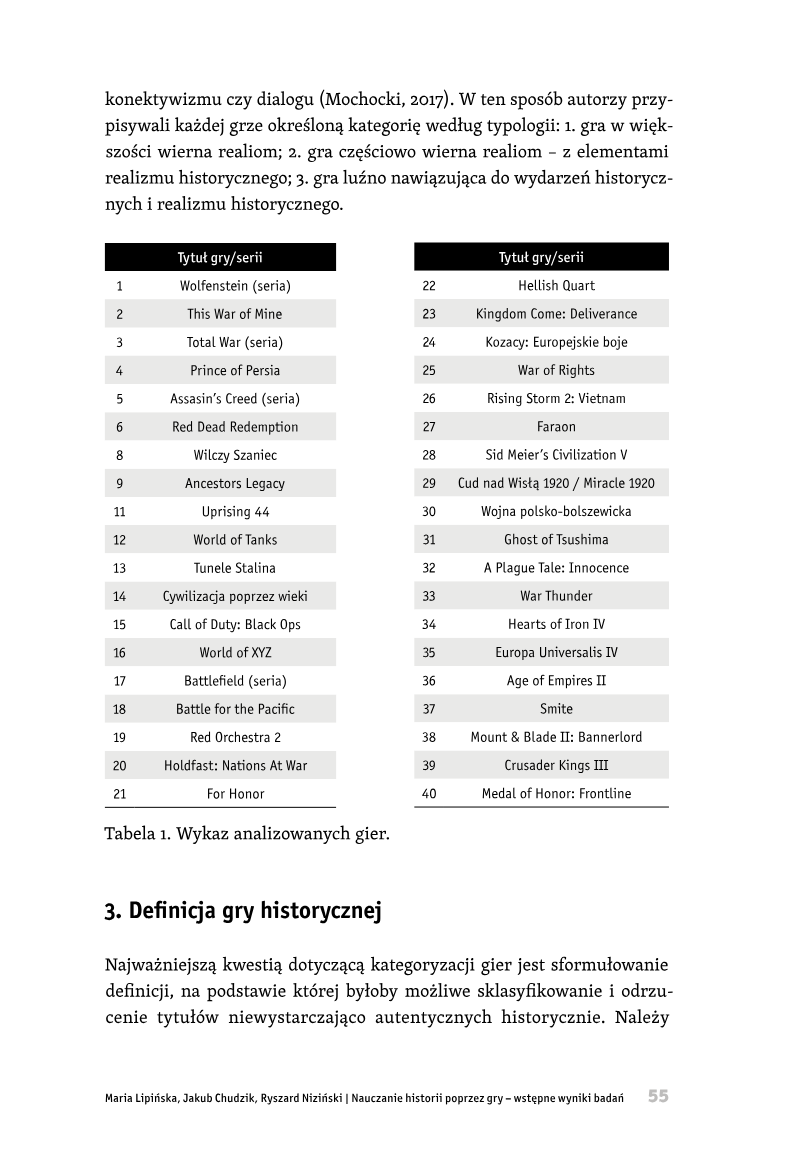
Teaching History Through Games: Preliminary Findings
Homo Ludens · 2024