VideoPocketGamer.biz
Session: 2024 & Beyond – Opportunities & Challenges in Mobile Gaming - Jack Barrett, Sensor Tower
7 Feb 202519 min video
Transcript
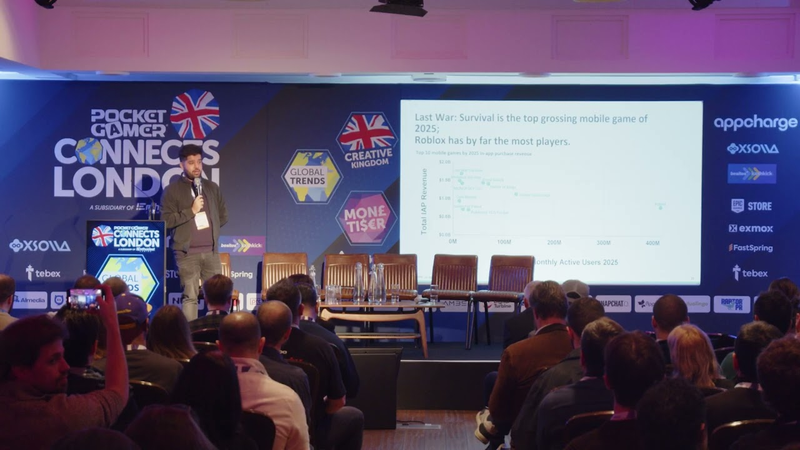
[Music] up next I would like to welcome Jack from sensor Tower who's going to be talking about opportunities and challenges in Mobile gaming so welcome Jack thanks Johnny good morning can you hear me okay awesome excellent my name is Jack as Charlie mentioned I leave the team that looks after sensor Towers gaming customers across the Amir region many of you probably know sensor Tower many of you are probably customers of sensor Tower but just a quick recap our Core Business is Market intelligence and competitor analysis in the mobile app ecosystem but our goal is to measure the world's digital economy which means going Beyond mobile and I've got a a few
data points Beyond mobile uh today that I'll go through as well but in terms of today we'll be looking at year- on-year Trends some themes that shaped 2024 um a few expectations for 2025 um and hopefully give you a few reasons to be optimistic one thing for the guys at the back do you mind just expanding the size of the speaker notes just there if that's okay just bring it up a bit perfect thank you very much right let's get into it so what themes shaped 20 2024 well firstly we continue to see a boom in non-gaming apps especially in terms of time spent versus gaming post pandemic people started going back outside how dare they so demand for apps that connected them back to reality back to the real world such as health and fitness and social media apps they saw a big big boom secondly post pandemic post Apple introducing app tracking transparency we've seen much more focus on efficiency of spent less focus on launching costly new titles extra focus
on uh Publishers on their existing titles making better use of live Ops and uh inapp events and as you'll see in some of the data Legacy titles were actually the number one driver of Revenue growth in 2024 and then thirdly we've seen a uh more of a shift away from just Performance Marketing app installed growth marketing towards better use of brand marketing and using IP and trans media specifically to find and expand new audiences in a more cost effective way so you'll see these popup over the next few slides but let's start high level so I don't need to tell you it's been a tough couple of years after the boom of covid I will give you some reasons to be optimistic but not just yet in terms of downloads we've seen this year-on-year decline on the left we've got gaming and non-gaming apps 1% down and on the right we've got gaming only 6 and 1 half% down I'm afraid the situation is even worse but 136 billion 49 billion downloads are still very large numbers the app stores are still driving huge consumer demand but in both
instances as you can see in blue there uh the Google Play Store is what drove that decline so Apple was still relatively stable for downloads despite them introducing at so what is one of the main reasons for this download decline in gaming well the simple answer is casual games which was 16% down year onye in 2024 so since Apple introduced at uh CIT installs have gone up some have been calling it The Death of hyper casual games our data obviously doesn't suggest that um last year hyper casual downloads only declined by 2% and their relative download market share actually went up um so I'll talk about hybrid casual and midcore uh in the next slide but you can see their downloads s a little bit of growth last year but overall the takeaway is primarily casual game developers were the ones that were doing less to find new players and drive up those installs however this doesn't quite paint the entire picture because then if we look at revenue and this is in Revenue um consumer spending app um
for Revenue growth casual games were the main driver behind that growth so uh looking at this data it suggests higher cpis are driving two big changes in gaming so firstly casual game developers in particular are focusing Less on finding new players more on improving that lifetime value Monopoly go is one example of a casual game success in 2024 and 20123 and hybrid casual is obviously growing rapidly so this is where some Developers are moving away from hyper casual games and finding that sweet spot in hybrid casual so with less emphasis on ad Revenue so recent successful games in the hybrid casual space include screw jam and match Factory from Zinger and triple match from mini clip so you can see mid midcore uh the market has been shrinking but it's still over half of the market Ben so there's still appetite for games that are not casual by Nature so hopefully you can see all these numbers the growth markets there are showing hinting at my next slide the
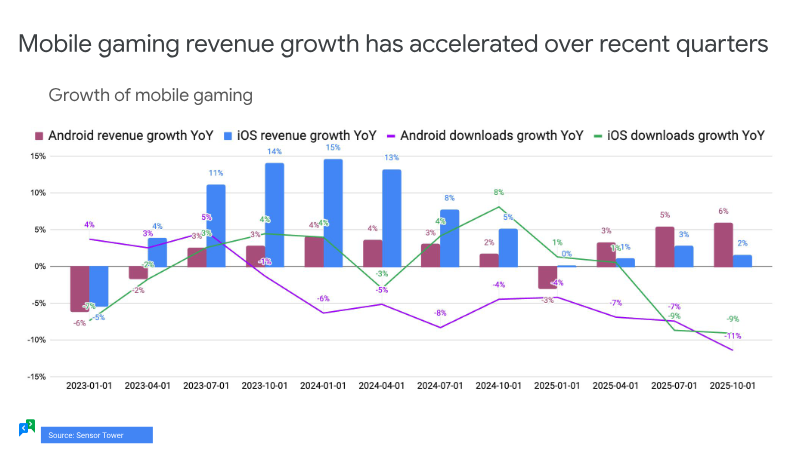
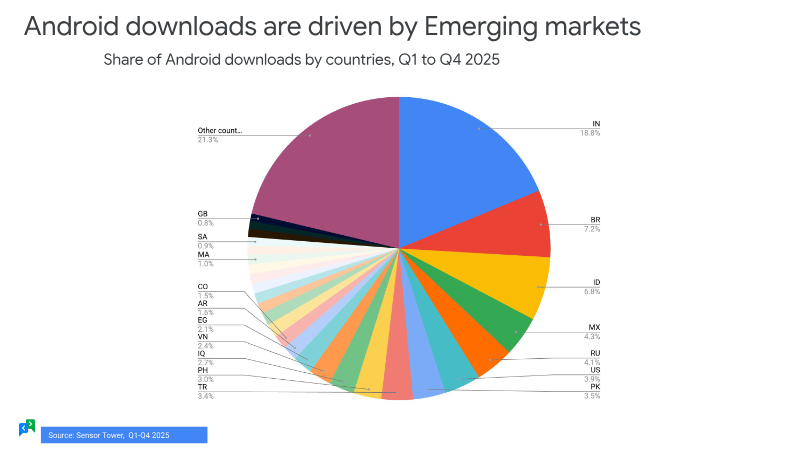
fact that we've got another reason or our first reason to be optimistic and that is that revenue is up so downloads are down but revenue is up so $150 billion in uh apps and games and $82 billion in gaming very big numbers again on the right hand side for gaming you can see all that Revenue growth has been driven by the Apple App Store and so why is why is this well relative stagnation across Asia as we'll see later where Google Play is dominant whereas the US and Europe where the Apple app store tends to be uh kind of have greater presence has had a much stronger year there um but then if we look at the left hand side so gaming and non-gaming you can see they've outperformed games in terms of Revenue growth and that link links back to that first theme that I mentioned which is that strong strong competition for time uh versus non-gaming apps so let's just quickly look at non-gaming in a little more detail um so it's sometimes said that a game developer's largest competitor is not necessarily other games but it's the
other ways their players spend their time well this is how things looked across the app ecosystem on the left there you can see that's percentage change in time spent for the main App Store categories uh that starting point there is about 3 to six months after the end of covid when time spent in gaming was the lowest it has been in recent years and so we can see firstly in 2023 for gaming that kind of dark blue line there in 2023 that growth was was not not massive about 10 to 15% uh in that first year but then we saw a huge huge uplift in 2024 as that accelerated to about a 60% increase from the the previous low and that then moves into my second reason to be optimistic and the the chart on the right hand side there for the last 12 months we've seen that gaming has accelerated in terms of total time spent much much faster uh than for non-gaming in 2024 so that's second reason to be optimistic going into 2025 so let's have a look at how the data links to that second theme that I mentioned that
Publishers are launching less and focusing more on their existing titles so I'm not going to spend too much time on this hopefully it's pretty clear this chart shows that decline you can see puzzle is pretty much the only genre to release more in 2024 but it does seem that this is starting to level out now so we might get to a happy medium but Publishers are launching less so why is this happening well this is why you can see in in the blue there apps launch 5 years ago versus app apps launch in that same year how much revenue they're making in in those years so you can see Legacy apps have absolutely dominated the last few years and new apps are really struggling to break through and Publishers have learned that they can earn more money on their existing titles cpis are still high so acquiring new users is still less attractive and then now St to focus on taking something good and refining up refining it driving up that lifetime value driving up that that retention as well um so in fact and it's not on here games that launched in 2024 actually earned as much much as games
launched in 20 2016 in their same launch year despite the overall Market nearly tripling in size for Revenue so and as you can see that difference does seem to to be Plateau now but the difference is still very very uh you know quite Stark and we do expect that dominance by Legacy apps to continue into the future and then this is reinforced by the publisher landscape so this is worldwide consumer spend in 2024 so apologies I know there's a lot a lot of data here um and you can see Market concentration by publisher so what is clear is the complete dominance and lack of competition across most genas in the market um you can see most genres have about a third of their Global Revenue taken by just two Publishers if we look at a few of them RPG at the top there is by far the most competitive 57% of spend came uh from outside the top 10 Publishers whereas if we look down at the other end shusa for example more than 50% came from just one publisher all going to 10 cent and and the top
Publishers in shooter controlled almost 90% of that entire Market geolocation even more extreme example uh utter dominance by Niantic with Pokémon go and Monster Hunter now and in terms of a Trends we we're seeing most genres are actually becoming more entrenched they're becoming more dominated by these top game Publishers in recent years however not All Is Lost puzzle is a great example of um the fact that lack of competition means that things can be right for disruption as shown in puzzle in the last few years with the Royal match coming to Dethrone Candy Crush uh in the last couple of years in that space so I've mentioned a few different Regional performances so let's just dive into that in a little more detail um so this is market share of consumer spend by genre and subgenre in 2024 so I'll go into each region in in more details in the next three slides but I thought it would just be interesting uh to see kind of the whole landscape here how they all compare and the most obvious difference is this utter dominance in Asia for RPG
mobile games whereas North America and Europe you can see for the top six there apart from casino and strategy which you could swap around the top six are more or less the same in terms of size and scale um but Asia one key cultural difference that we see is that whereas in the West in in North America and Europe uh Gamers soing uh sorry Gamers tend to socialize via kind of PC and console titles whereas across Asia much more of the social gaming happens via these RPG games on on mobile so let's just dive into each one quickly so North America uh again on the left is consumer spend for the last 12 months these Legacy categories of casino and puzzle are still dominating almost half of the total spend um there and they tend to also have the most competition um on the right there you can see the year-on-year growth for each and so in terms of kind of what's driving this uh so if we look at casino 16% up year on-year mainly driven by Monopoly go scop le coin looser set a number of Records um it was the biggest launch ever in April 2023 in Mobile gaming it
took just 473 days to reach $3 billion consumer spending which is the fastest ever so that's been that that's what's been driving that huge growth there if we look at puzzle 133% mainly driven by one game again Royal match released in 2021 by dream games they took the top spot from Candy Crush this year and is now the number two title globally and then strategy games 177% up again mainly driven by one game last war survival made uh released in 2023 by first fun which is a Singaporean based developer um they've seen rapid rapid growth they're now taking a top five uh spot globally you've probably seen some of their creatives online with Anthony star who plays homelander in the boys um so yeah it's interesting how it's really just specific apps specific games in each genre that are driving that growth and then one last thing to point out RPG double digit decline in North America this is the only genre that declined across the board across each region as we'll see so quickly for Europe it was a
very good year for Europe like I say RPG was the only one that actually declined growth in consumer spend for every other genre and in terms of top games it is a very similar story uh to North America this time strategy takes the top spot again driven by last war then puzzle again driven by Royal match and casino again driven by Monopoly go but I mean one key Point here is Europe tends to get lumped in with North America when it comes to um developers focusing on the west but hopefully this shows that Europe has had quite a different year much more growth across across all the different categories and so there's definitely lots of money to be had lots of reasons to localize your approach in Europe and so lastly um let's look at Asia so obviously very mixed results if we start at RPG Still Still dominating but massive massive 19% decline there and if we look at the games um that are driving that miyo's two large RPGs honkai star Rail and genin impact they're still dominating but seeing huge amounts of Revenue decline genin imp impact almost 50% down year on-ear in
terms of Revenue but we can see across the board clear opportunities as gaming preferences are shifting we're seeing double digit growth in action puzzle and lifestyle um if we look at action 74% growth massive growth mainly driven by again one game 10 cents dungeon fighter mobile uh game which launched in China in May um that's that's been a big big boost to 10 cent that I've seen declining revenues across their other titles puzzle 11% up year on year again mainly driven by Royal match which s 100% year-on-year Revenue growth in the region Japan is actually now Royal match's number two Market globally for Revenue which I was quite surprised to see um so what's the main takeaway here well if you're going to take away one thing is that there is a fast growing market for casual games in Asia historically that wasn't the case historically it was dominant by RPG but things are are shifting quite quickly um so this is my last section here um focusing on that final theme of how the marketing landscape has been changing as Brands and Gam are looking for more cost- effective way to reach
new audiences but firstly where do you start when each game uh has a completely different kind of audience type well as you can see you know you got in in puzzle it tends to attract women and older players who spend more time in shopping apps strategy games tend to attract men and younger audiences who spending more time using fast food apps so our gaming and and brand customers are now using this data to better understand who to partner with and where to place their ads but beyond just placing ads in the right places in 2024 we saw some great examples of big Brands and big gaming companies using their IP and using trans media strategies to expand their audiences even further in a more cost- effective way so in terms of using pre-existing IP I've already mentioned some success stories Monopoly go in the casino genre in the US and Europe dungeon fighter Mobile in China which was a massive South Korean game IP and very recently Pokemon uh Trading Card Game pocket which released uh sorry two weeks into its release had already
recorded $90 million in worldwide consumer spend so those are some great examples of of kind of using IP in gaming but let's look more specifically at collaboration across Brands and gaming um and how they can be Rocket Fuel so this is just a very very specific example looking at brawl Stars this is brawl stars um worldwide weekly revenue and they hit their alltime largest day of Revenue the day after the SpongeBob SquarePants event began on the 5th of September so context August 2024 to September 2024 they saw a 60% download increase mainly driven by this if you compare that to the year before they only saw an 8% increase in that same period of time and you might have seen some of these creatives yourself leveraging two massive massive well-known Brands John Cena and SpongeBob they were all over the Internet this is obviously a very very strong example of getting everything right and combining two big Brands but broad Stars keep doing this they keep leveraging IP in this way and it's helped them have their largest year ever in terms of Revenue collaborations they've done include Paper Mario
Godzilla South Park Splatoon Powerpuff Girls um and they just keep going and so we only see this happening more and more and we expect other game developers to follow as they see the success of of people like braw stars um so just one last example and how about trans media then so this year we've SE we've seen a couple of great examples The Fallout TV show being being one of them but I was going to speak about Arcane and League of Legends so in November Netflix released Arcane season 2 based on on the League of Legends Universe if you haven't seen it I'd highly recommend Arcane season 1 and two they fantastic show um but you can see what the release of the show did in terms of the impact on their mobile game wild Rift so on the left we've got weekly downloads and on the right we've got daily revenue both worldwide and we saw very similar spikes for the Mobile card strategy game Legends of run Tera and then beyond the show to further capitalize on this both games have been running inapp in-game events related to the show and also the show release was timed just after um one week after the
League of Legends World final to capture that momentum so really amazing uh work from Riot games here to to make good use of trans media so what do we expect in 2025 um well firstly we are expecting a strong return to growth which is obviously good news however and the controversial take here is that we expect the biggest winners will be those largest Publishers who already dominate their genres um with those and and those well established green games as long as they do a good job of building on those audiences on on using IP trans media and other things that I mentioned secondly we expect smaller deel smaller developers will likely look AC crossplatform more as they realize they can't necessarily take Revenue away from those larger titles for example putting their games on on Steam doing more direct to Consumer using web Stores um and then lastly it is still hard to do Marketing in a postat environment so having those pre-established IPS uh and and finding a new audience in cost
effective ways is going to be the way that you win in the market and that is it for me thank you very much [Applause]
Auto-generated captions from YouTube — names and numbers may be misheard.
Key insights
Distilling the key insights…
Ask AI about this video
Cite this video
Citation
Generating citation…
Comments