1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticle InvestGame
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticleInvestGame
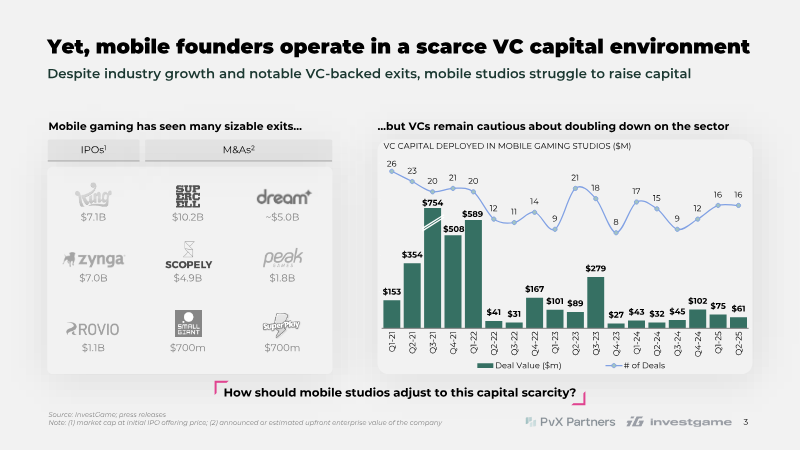
In the first three quarters of 2026, committed UA financing for mobile games totaled $398 million, versus $254 million in early-stage equity rounds.
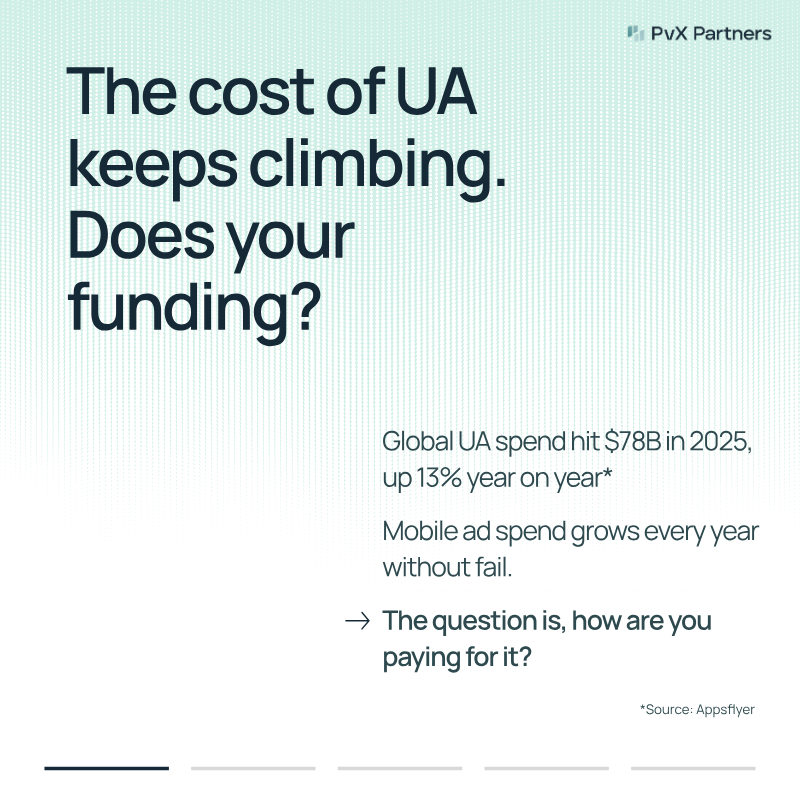
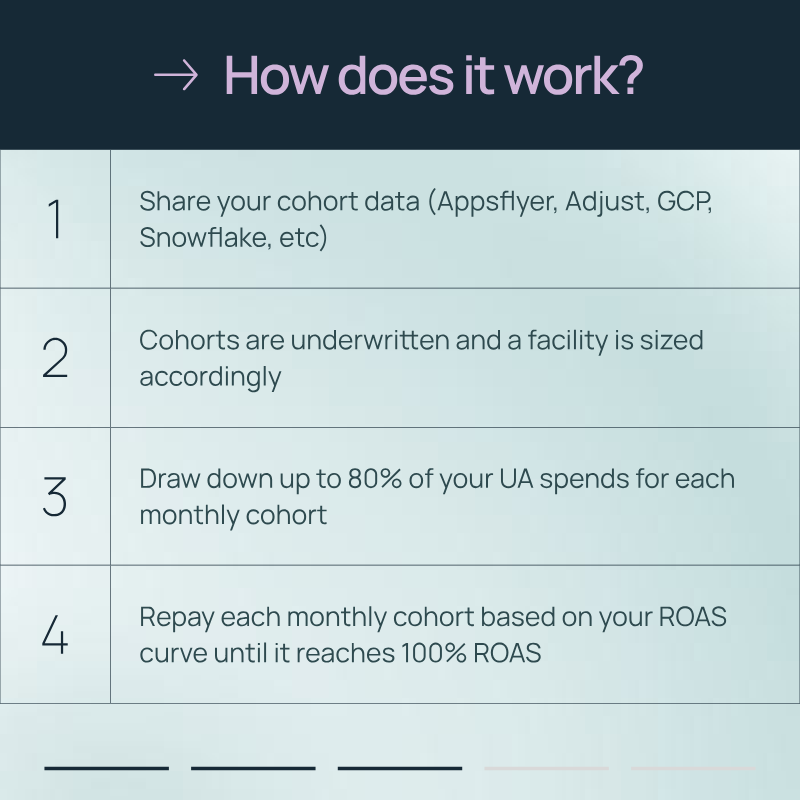
Committed user acquisition (UA) financing has overtaken early-stage equity as a funding source for mobile games and consumer apps, according to this InvestGame.net article. The piece reports that in the first three quarters of 2026, committed UA facilities totaled $398 million against $254 million in early-stage rounds, meaning UA facilities made up 61% of the combined $652 million. Under this model, studios draw capital to buy users and repay advances from the revenue those users generate, without surrendering equity, which allows them to retain ownership for product development and hiring.
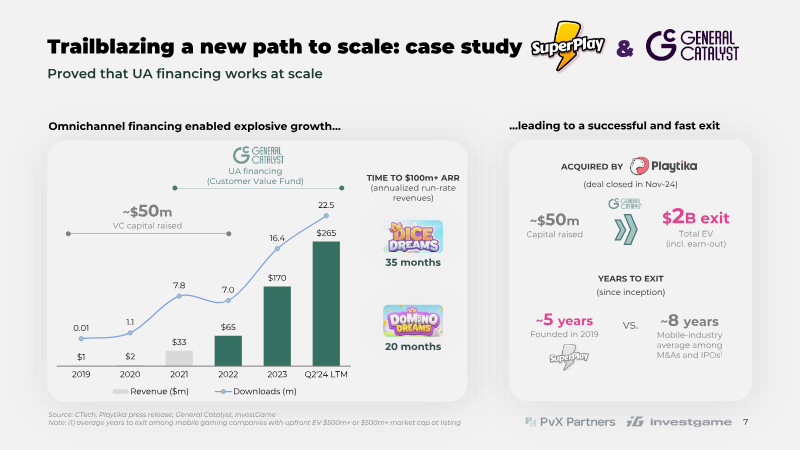
The article describes differing provider terms. PvX Partners repays through a share of cohort revenue up to a pre-agreed return cap, while Plan A Games charges a fixed interest rate on drawn capital plus a success fee tied to a revenue target set at the outset. General Catalyst is identified as the largest backer of the model, with its Customer Value Fund supporting PvX, the most active provider. PvX's committed facilities reportedly grew from more than $250 million across 20 companies in December 2025 to over $750 million by April 2026, and Israel-based vgames had deployed over $350 million into UA and marketing financing by December 2025.
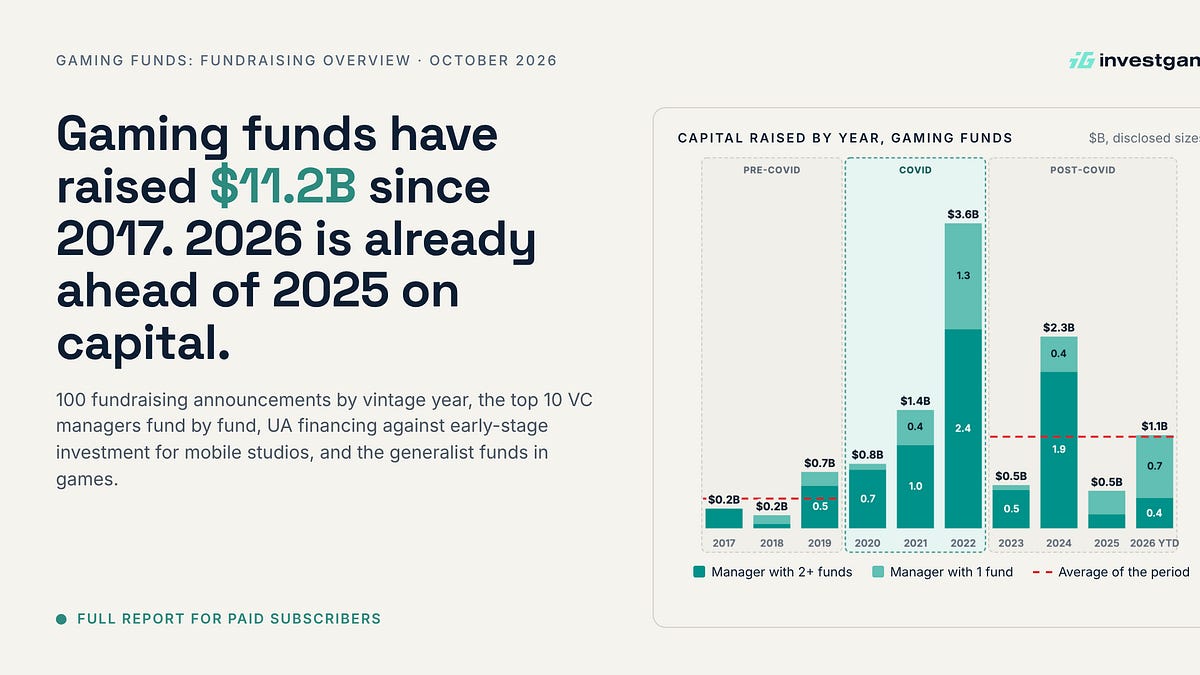
The article also notes that similar capital is flowing into other structures beyond mobile, including Griffin Gaming Partners' $100 million indie-game fund, Denmu's $50 million game-specific fund, and GreaterThan Group, a holding company with $40 million raised and around $60 million in further commitments. The coverage is primarily based on reported deal announcements and provider disclosures rather than a systematic survey, and the figures should be read as company-reported data.
InvestGame · 2026
Naavik · 2025