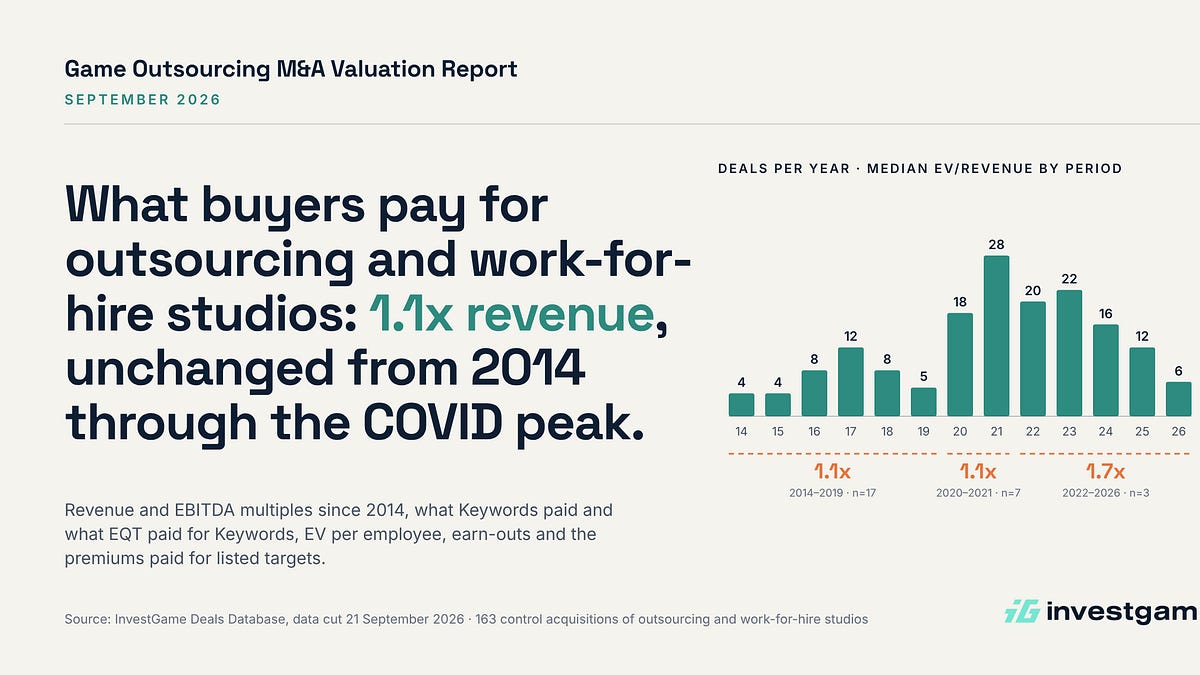
The median revenue multiple for work-for-hire studios stayed at 1.1x, even during the 2020–2021 COVID peak. This is consistent with 2014–2019 levels.
The game outsourcing and work-for-hire sector has experienced significant M&A activity since 2014, yet valuation multiples for individual studios have remained remarkably stable. Despite a surge in deal volume during the 2020–2021 period, the median revenue multiple for these acquisitions has held steady at 1.1x. While recent data suggests a rise to 1.7x revenue and 6.8x EBITDA, this shift is largely attributed to a small number of high-value transactions; when excluding major platform-level deals, the underlying valuation for individual studios remains consistent with historical norms.
The analysis covers 163 control acquisitions recorded between January 2014 and September 2026, with a specific focus on 40 deals that provided sufficient financial disclosure. A primary driver of this market has been Keywords Studios, which accounted for 52 of the 163 acquisitions and established the industry standard of 1.1x revenue. The subsequent 2024 acquisition of Keywords itself by EQT at a 2.8x revenue multiple highlights a significant re-rating of the platform compared to the individual studios it acquired.
Valuations vary considerably based on deal size and scale. Transactions valued at $20 million or more command higher premiums, with a median of 1.7x revenue and 8.6x EBITDA, compared to 0.9x revenue and 5.0x EBITDA for smaller deals. This disparity is also reflected in per-employee valuations, which average $234,000 for larger deals versus $54,000 for smaller ones. The findings underscore that while the broader gaming market saw volatile valuation swings during the pandemic, the work-for-hire segment has maintained a disciplined, consistent pricing structure for individual studio acquisitions.
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
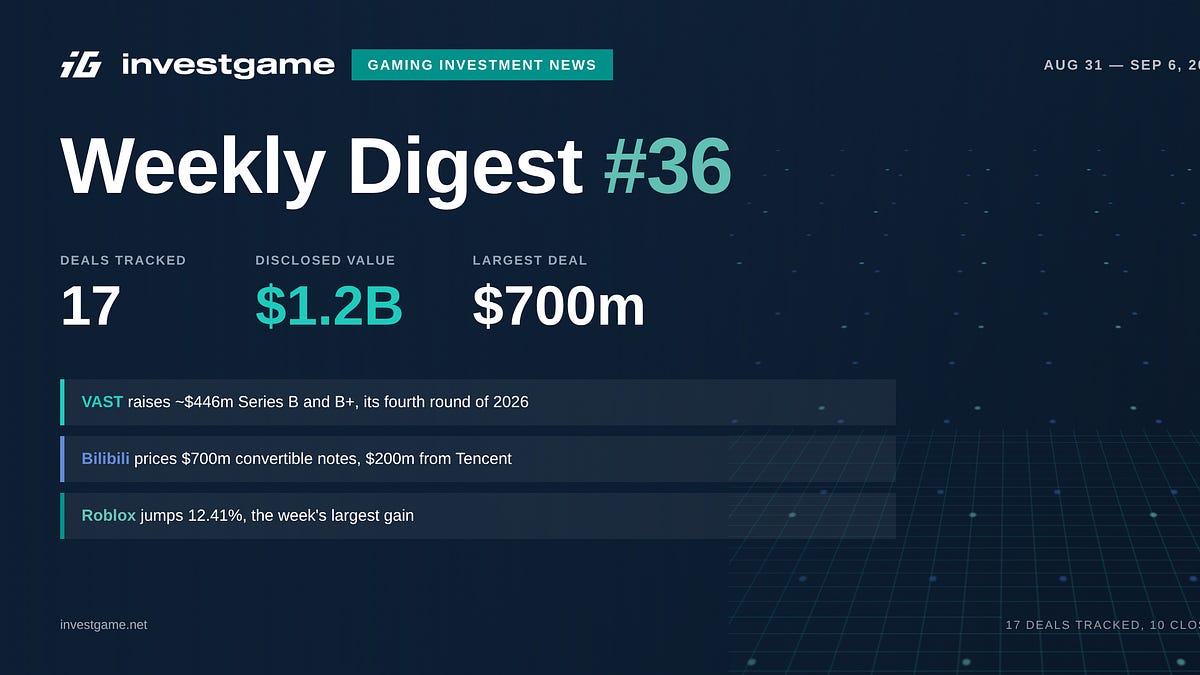
InvestGame · 2026
Deconstructor of Fun · 2024
Jason Schreier · 2026
The Game Business · 2026
Jason Schreier · 2026
PocketGamer.biz · 2026
Two & a Half Gamers · 2026
Deconstructor of Fun · 2026
Two & a Half Gamers · 2026
Deconstructor of Fun · 2026
The Game Business · 2026
The Game Business · 2026
Extra Credits · 2026
Comments