1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticle InvestGame
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticleInvestGame
The gaming investment landscape has seen significant evolution.
The gaming investment landscape has undergone significant evolution between 2017 and 2026, characterized by $11.2 billion in total capital raised across 100 distinct fundraisings. The market has moved through three distinct phases: a pre-COVID growth period, a peak capital influx during 2020–2022, and a post-COVID reset followed by a 2026 rebound. As of October 2026, the year-to-date performance has already surpassed the total capital raised in 2025, signaling renewed momentum in the sector.
Capital concentration remains a defining feature of the industry, with the top ten venture capital managers controlling approximately 64% of the $11.3 billion in total announced gaming funds. While 65 distinct managers have entered the space since 2011, the majority have raised only a single fund, highlighting a market dominated by a small group of repeat institutional players such as Griffin Gaming Partners, Makers Fund, Andreessen Horowitz, and BITKRAFT Ventures.
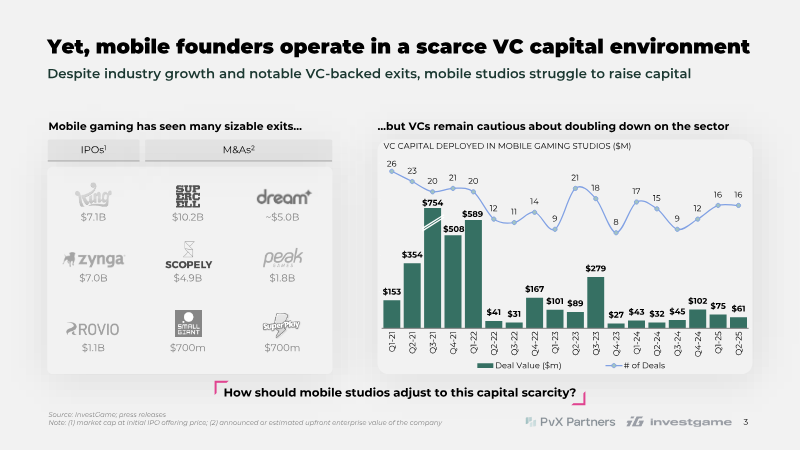
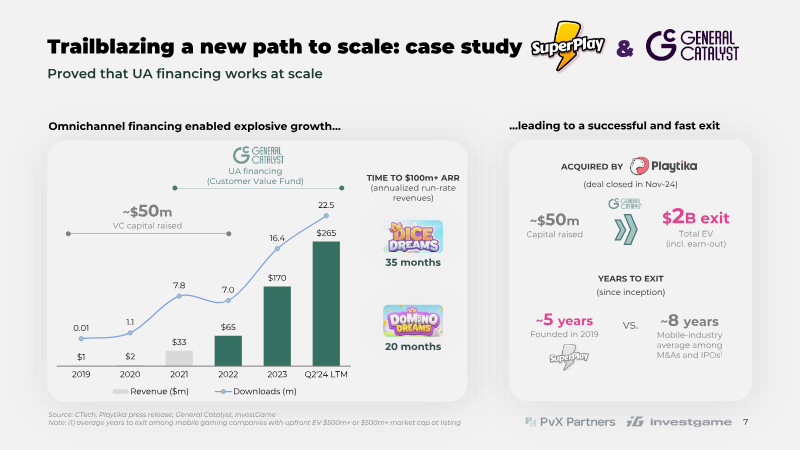
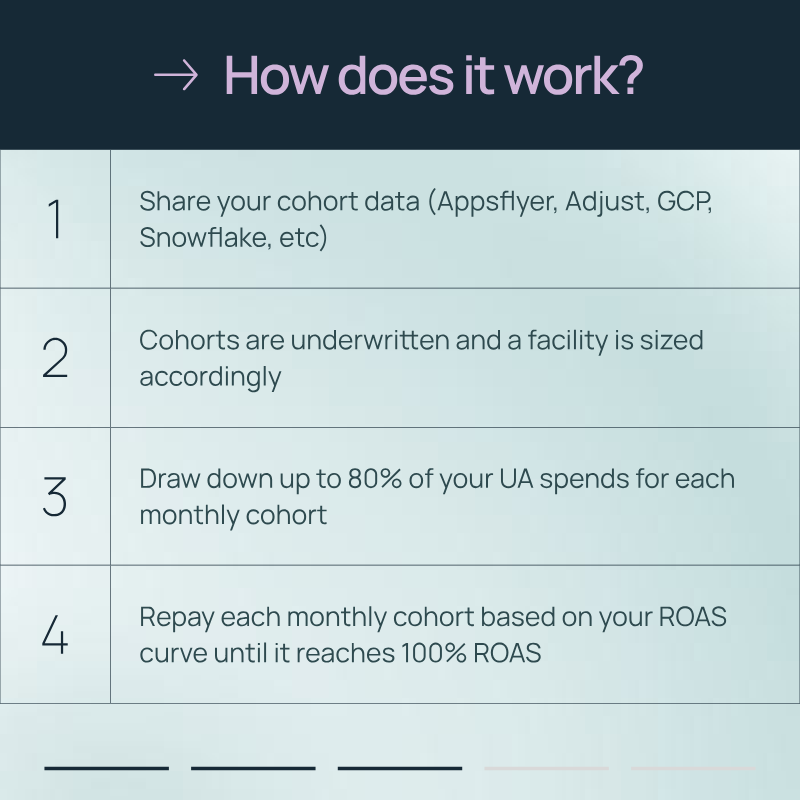
A primary shift in capital deployment is the emergence of User Acquisition (UA) financing as a mainstream alternative to traditional early-stage investment for mobile studios. In the first three quarters of 2026, UA financing accounted for 61% of combined early-stage and UA capital, reflecting a rapid adoption of debt-based or performance-linked financing models. This trend underscores a fundamental change in how mobile developers secure liquidity to scale operations. The analysis, which draws on market data through October 2026, confirms that while traditional venture capital remains vital, the diversification of funding instruments—specifically through specialized UA providers and credit facilities—has become a critical component of the modern gaming finance ecosystem.
InvestGame · 2026
Deconstructor of Fun · 2026