mixi
Game Co.74 documents
Documents
Financial12 pages
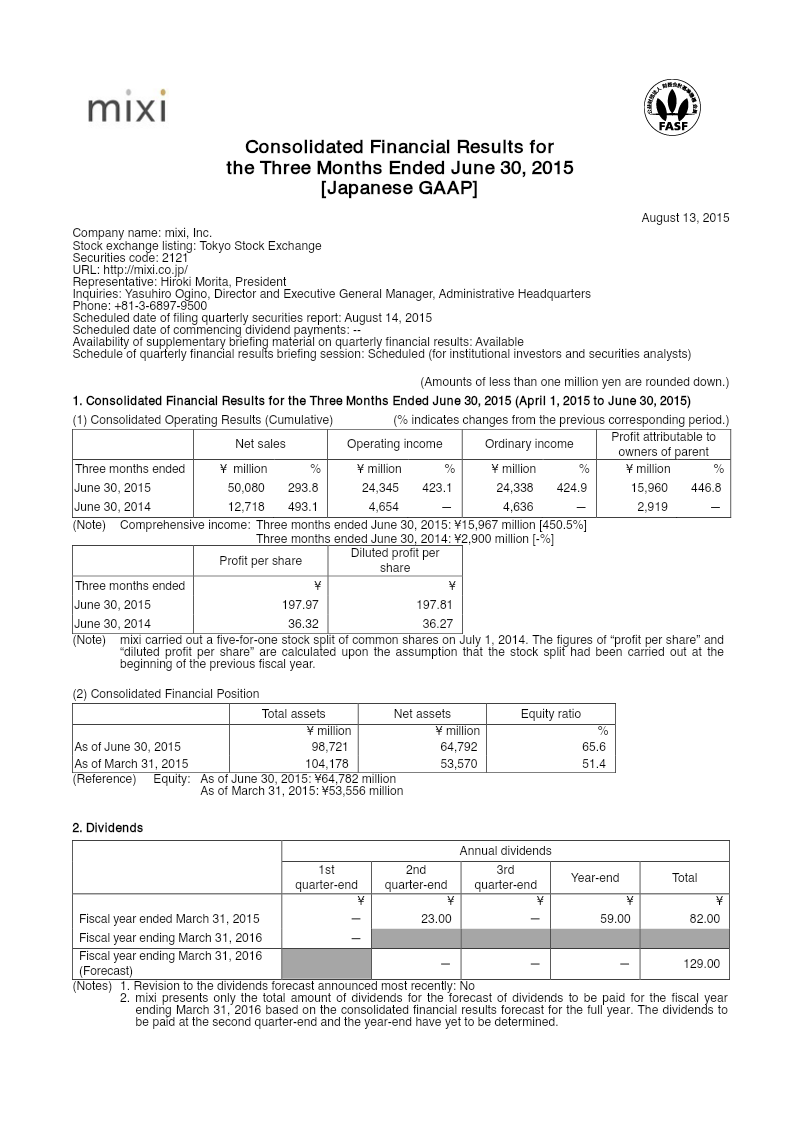
Consolidated Financial Results for the Three Months Ended June 30, 2015
This financial report details the consolidated results for mixi, Inc. during the first quarter of the fiscal year ending March 31, 2016, covering the period from April 1, 2015, to June 30, 2015. The findings reveal a period of massive growth for the Japanese company, primarily driven by the expansion of its Entertainment Business. Net sales reached ¥50,080 million, representing a 293.8% increase over the same period in the previous year. Operating income rose by 423.1% to ¥24,345 million, while profit attributable to owners of the parent surged 446.8% to ¥15,960 million.
The report highlights a strategic shift in business segments following the acquisition of Hunza, Inc. and MUSE & Co., Ltd. in early 2015. The company now operates under two primary segments: the Entertainment Business, which includes the flagship title Monster Strike, and the Media Platform Business, which encompasses mixi.jp and newly acquired e-commerce and ticketing services. The Entertainment Business was the dominant contributor to the quarter's success, accounting for ¥47,002 million in net sales and ¥25,024 million in segment income. In contrast, the Media Platform Business contributed ¥3,078 million in sales.
Financial stability remains strong, with total assets valued at ¥98,721 million and an equity ratio of 65.6%, up from 51.4% at the end of the previous fiscal year. Cash flows from operating activities saw a net use of ¥4,542 million, largely due to a significant income tax payment of ¥22,897 million. Subsequent to the quarter's end, the company raised approximately ¥17,560 million through an overseas offering of new shares and treasury shares. These funds are earmarked for the repayment of loans related to recent acquisitions and for future advertising expenses within the Entertainment Business. For the full fiscal year, the company forecasts net sales of ¥185,000 million and a profit of ¥52,000 million.
- Mixi, Inc. experienced massive growth in Q1 of the fiscal year ending March 31, 2016, with net sales reaching ¥50,080 million, a 293.8% increase year-over-year.
- Operating income surged 423.1% to ¥24,345 million, while profit attributable to owners of the parent rose 446.8% to ¥15,960 million.
- The Entertainment Business, anchored by the flagship title Monster Strike, was the primary driver of success, generating ¥47,002 million in sales and ¥25,024 million in segment income.
- The company restructured into two segments—Entertainment and Media Platform—following the 2015 acquisitions of Hunza, Inc. and MUSE & Co., Ltd.
- Financial stability improved significantly, with the equity ratio rising to 65.6% from 51.4% at the end of the previous fiscal year.
+2
mixiAug 2015

Financial2 pages
FY2015 Business Report
The Mixi Group’s fiscal year 2015 business report details a period of transformative financial growth and strategic restructuring for the Japanese technology firm. Covering the period from April 1, 2014, to March 31, 2015, the findings highlight a massive surge in performance, with net sales reaching ¥112.9 billion and operating income hitting ¥52.6 billion. This represents a dramatic recovery from the previous year’s net loss, driven primarily by the global success of the mobile game Monster Strike, which surpassed 30 million cumulative unique device downloads by May 2015.
The primary thesis centers on the company’s transition into two core reportable segments: the Entertainment Business and the Media Platform Business. The Entertainment division focuses on the "bringing people together" concept, utilizing a media-mix strategy that includes TV commercials, merchandise, and an upcoming Nintendo 3DS title to turn Monster Strike into a national intellectual property. Geographically, the company is expanding its footprint in Taiwan, North America, and China, tailoring localization and promotion to specific regional usage patterns.
Simultaneously, the Media Platform Business is diversifying through aggressive M&A activity and in-house incubation. Key developments include the acquisition of Hunza, Inc. (TicketCamp) and MUSE & Co., Ltd., alongside the growth of internal startups like the nohana photobook service and the minimo salon reservation app. The strategic goal is to leverage the marketing and customer support expertise gained from the original mixi.jp social network to scale these B2C and C2C services. Consequently, the company has significantly increased shareholder returns, paying an annual dividend of ¥82 per share with plans to increase this to ¥129 in the following fiscal year.
- Mixi Group achieved a major financial turnaround in FY2015, reporting ¥112.9 billion in net sales and ¥52.6 billion in operating income.
- The mobile game Monster Strike drove the company's fiscal recovery, reaching over 30 million cumulative unique device downloads by May 2015.
- The company restructured into two core segments: the Entertainment Business, focused on expanding Monster Strike as a global intellectual property, and the Media Platform Business.
- Mixi is scaling its Media Platform segment through acquisitions, including TicketCamp operator Hunza, Inc. and MUSE & Co., Ltd., alongside internal startups like nohana and minimo.
- International expansion efforts for the Entertainment division are currently targeting Taiwan, North America, and China with region-specific localization strategies.
+1
mixiJun 2015
Financial49 pages
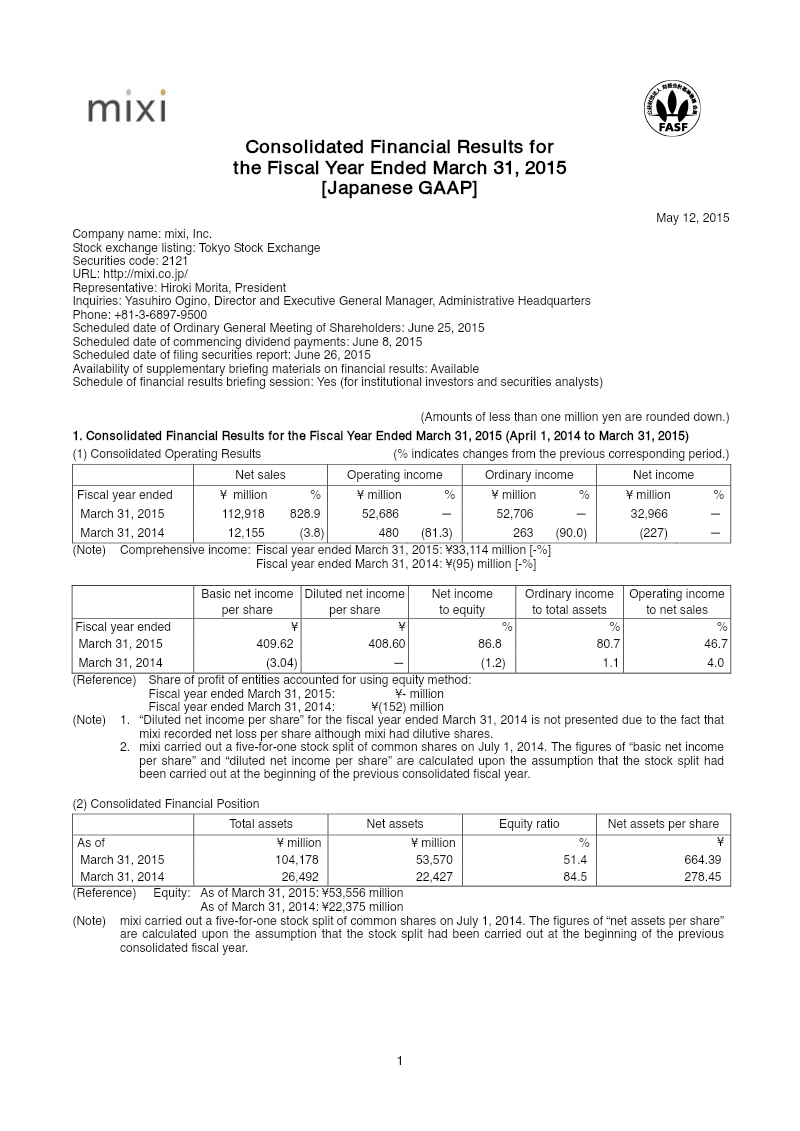
Consolidated Financial Results for the Fiscal Year Ended March 31, 2015
The fiscal year ended March 31, 2015, marked a transformative period of hyper-growth and financial recovery for mixi, Inc., primarily driven by the explosive success of the mobile title Monster Strike. Net sales surged by 828.9% to ¥112.9 billion, facilitating a dramatic turnaround from a net loss in the previous year to a net income of ¥32.9 billion. This performance significantly bolstered the balance sheet, with total assets expanding from ¥26.4 billion to ¥104.1 billion and cash reserves increasing nearly fourfold to ¥65.4 billion.
The Entertainment Business segment became the primary engine of this expansion, with sales rising from ¥3.3 billion to over ¥102.2 billion. To sustain this momentum, the company aggressively scaled its operational investments, increasing advertising expenditures nearly ninefold to ¥9.7 billion and settlement fees to ¥32.7 billion. This liquidity also funded a strategic diversification of the Media Platform Business through high-profile acquisitions, including the ¥11.5 billion purchase of ticket marketplace Hunza, Inc. and the acquisition of fashion e-commerce platform MUSE & Co., Ltd. These moves, alongside entries into the matchmaking and marriage support sectors, resulted in a substantial increase in goodwill to ¥14.1 billion.
Geographically, the company remains heavily concentrated in the Japanese market, which accounts for over 90% of sales and assets. Following a five-for-one stock split and a significant rise in net assets per share, the company has shifted toward a more robust shareholder return policy, including increased dividend payouts. Projections for fiscal year 2016 anticipate continued growth, with net sales expected to reach ¥185 billion as the company leverages its strengthened capital structure and diversified service portfolio.
- Driven by the success of the mobile title Monster Strike, mixi, Inc. achieved a net sales surge of 828.9% to ¥112.9 billion for the fiscal year ended March 31, 2015.
- The company transitioned from a net loss in the previous year to a net income of ¥32.9 billion, with cash reserves increasing nearly fourfold to ¥65.4 billion.
- The Entertainment Business segment became the primary growth engine, with segment sales rising from ¥3.3 billion to over ¥102.2 billion.
- To sustain growth, the company increased advertising expenditures nearly ninefold to ¥9.7 billion and settlement fees to ¥32.7 billion.
- Strategic diversification included the ¥11.5 billion acquisition of ticket marketplace Hunza, Inc. and the purchase of fashion e-commerce platform MUSE & Co., Ltd.
+1
mixiMay 2015
Financial10 pages
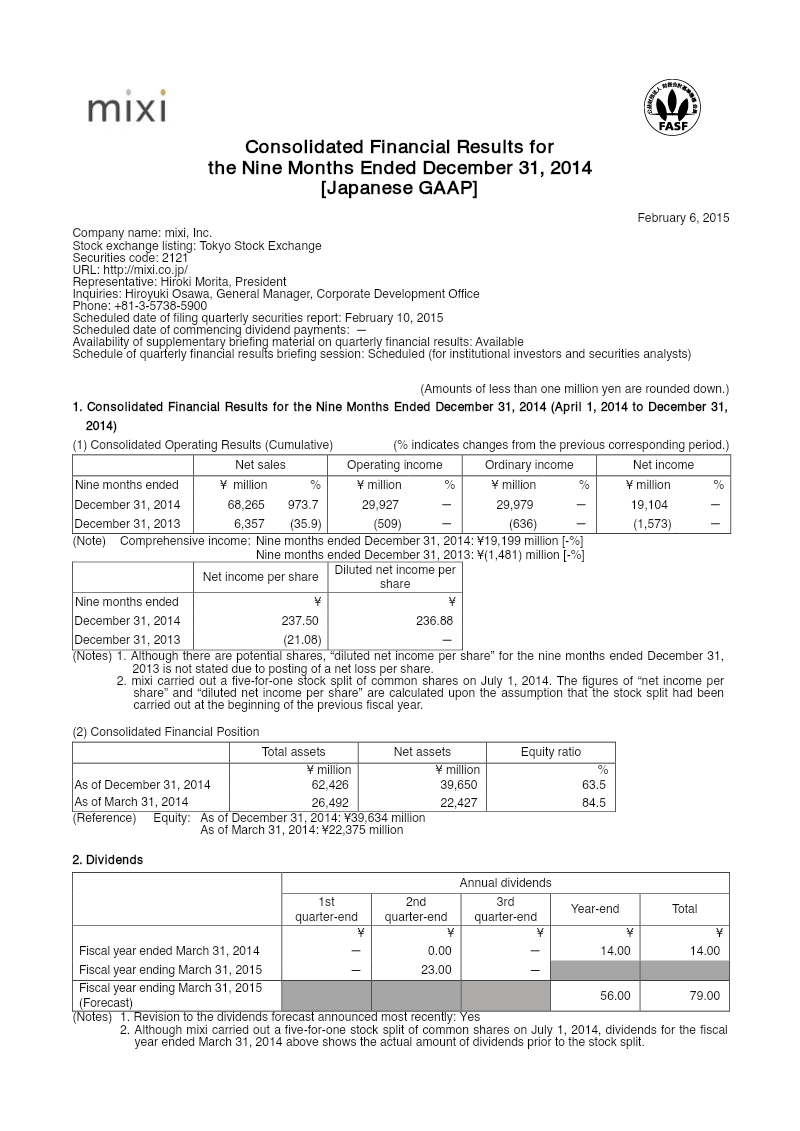
Consolidated Financial Results for the Nine Months Ended December 31, 2014
This financial report details the consolidated results for mixi, Inc. during the first nine months of the fiscal year ending March 31, 2015, covering the period from April 1, 2014, to December 31, 2014. The data reveals a period of explosive growth for the Japanese company, primarily driven by its Media & Content Business. Net sales surged to 68,265 million yen, representing a 973.7% increase compared to the same period in the previous year. This growth facilitated a dramatic turnaround in profitability, moving from an operating loss of 509 million yen in 2013 to an operating income of 29,927 million yen in 2014. Net income for the period reached 19,104 million yen, compared to a net loss of 1,573 million yen in the prior year.
The scope of the report encompasses two primary reportable segments: Media & Content and Life Events. The Media & Content segment was the dominant contributor, accounting for 63,658 million yen in sales and 31,198 million yen in segment income. The Life Events segment, which includes marriage support and photobook businesses, contributed 4,390 million yen in sales. Geographically, the results focus on the Japanese market, though the report notes the previous liquidation of subsidiaries in Shanghai. To reflect its expanded business portfolio, the company reorganized its reporting segments during this period, renaming the former Social Net and Find Job! divisions.
The financial position of the company strengthened significantly, with total assets increasing from 26,492 million yen at the end of March 2014 to 62,426 million yen by December 31, 2014. Cash and deposits grew to 42,065 million yen, largely due to 26,303 million yen provided by operating activities. Based on these strong results, the company revised its full-year forecasts upward, projecting annual net sales of 110,000 million yen and net income of 32,000 million yen. The report also accounts for a five-for-one stock split executed on July 1, 2014, adjusting per-share calculations retroactively for accurate year-over-year comparison.
- Mixi, Inc. experienced explosive growth in the first nine months of fiscal year 2015, with net sales surging 973.7% year-over-year to 68,265 million yen.
- The company achieved a significant profitability turnaround, moving from an operating loss of 509 million yen in 2013 to an operating income of 29,927 million yen by December 31, 2014.
- The Media & Content segment served as the primary growth engine, generating 63,658 million yen in sales and 31,198 million yen in segment income.
- Net income reached 19,104 million yen for the nine-month period, a substantial recovery from the 1,573 million yen net loss recorded during the same period in the prior year.
- Driven by strong performance, the company revised its full-year forecasts upward to 110,000 million yen in net sales and 32,000 million yen in net income.
+1
mixiFeb 2015

Financial10 pages
Consolidated Financial Results for the Six Months Ended September 30, 2014
Mixi, Inc. reported a significant financial turnaround and exponential growth for the six-month period ending September 30, 2014. Following a net loss in the previous year, the company achieved a dramatic increase in net sales, which rose 778.3% year-over-year to ¥34.95 billion. This surge drove an operating income of ¥14.35 billion and a net income of ¥9.08 billion, compared to a net loss of ¥1.35 billion in the same period of 2013. The results reflect a successful pivot in business strategy, primarily led by the Media & Content Business segment.
The Media & Content Business emerged as the primary revenue driver, contributing ¥31.91 billion in sales and ¥15.15 billion in segment income. This growth was accompanied by a substantial rise in operating expenses, specifically settlement fees and advertising costs, which reached ¥9.93 billion and ¥4.13 billion respectively. The Life Events Business also showed growth, contributing ¥2.89 billion in sales. Geographically focused on Japan, the company’s consolidated balance sheet strengthened significantly, with total assets increasing from ¥26.49 billion to ¥43.617 billion and cash and deposits rising to ¥28.55 billion.
Based on these results, the company issued a robust full-year forecast for the fiscal year ending March 31, 2015, projecting net sales of ¥100 billion and net income of ¥29 billion. To reflect this performance, the dividend forecast was revised upward to a total of ¥72 per share for the year. The reporting period also included a five-for-one stock split effective July 1, 2014, and a reorganization of reportable segments to better classify the expanding portfolio into Media & Content and Life Events categories. These financial statements were prepared under Japanese GAAP and represent the consolidated performance of the parent company and its subsidiaries.
- Mixi, Inc. achieved a major financial turnaround for the six months ending September 30, 2014, reporting net sales of ¥34.95 billion, a 778.3% increase year-over-year.
- The company shifted from a ¥1.35 billion net loss in the same period of 2013 to a net income of ¥9.08 billion and an operating income of ¥14.35 billion.
- The Media & Content Business segment served as the primary growth driver, generating ¥31.91 billion in sales and ¥15.15 billion in segment income.
- Management issued a strong full-year forecast for the fiscal year ending March 31, 2015, projecting ¥100 billion in net sales and ¥29 billion in net income.
- The company increased its annual dividend forecast to ¥72 per share, supported by a strengthened balance sheet that saw cash and deposits rise to ¥28.55 billion.
+1
mixi Inc.Nov 2014

Financial10 pages
Consolidated Financial Results for the Three Months Ended June 30, 2014
Mixi, Inc. reported a significant financial turnaround for the first quarter of the fiscal year ending March 31, 2015, covering the period from April 1 to June 30, 2014. Following a net loss in the previous year’s corresponding quarter, the company achieved a dramatic surge in performance, with net sales increasing by 493.1% to ¥12,718 million. This growth translated into an operating income of ¥4,654 million and a net income of ¥2,919 million, compared to an operating loss of ¥84 million and a net loss of ¥253 million in the same period of 2013.
The primary driver of this expansion was the Media & Content Business segment, which saw its net sales rise from ¥1,877 million to ¥11,258 million year-over-year. The Life Events Business also experienced growth, increasing its revenue from ¥226 million to ¥1,393 million. During this period, the company restructured its reporting segments to better reflect its expanding portfolio, renaming the former Social Net and Find Job! divisions to Media & Content and Life Events, respectively.
The financial position remained robust with total assets growing to ¥31,594 million and an equity ratio of 79.4%. Cash and deposits increased to over ¥20 billion, supported by ¥2,918 million in net cash provided by operating activities. Per-share data reflects a five-for-one stock split executed on July 1, 2014, resulting in a net income per share of ¥36.32 for the quarter.
Looking ahead, the company issued a revised forecast for the six months ending September 30, 2014, projecting net sales of ¥33,000 million and a net income of ¥8,000 million. While the dividend for the first quarter was set at ¥20.00 per share, the year-end dividend forecast remained undecided at the time of the report. These results indicate a successful strategic pivot toward high-growth digital content and diversified internet services.
- Mixi, Inc. achieved a major financial turnaround in Q1 2014, reporting net sales of ¥12,718 million, a 493.1% increase compared to the same period in 2013.
- The company transitioned from a net loss of ¥253 million in Q1 2013 to a net income of ¥2,919 million for the quarter ending June 30, 2014.
- The Media & Content Business was the primary growth driver, with segment net sales surging from ¥1,877 million to ¥11,258 million year-over-year.
- The Life Events Business segment also saw significant expansion, with revenue increasing from ¥226 million to ¥1,393 million during the same period.
- The company maintains a strong financial position with an equity ratio of 79.4% and cash and deposits exceeding ¥20 billion.
+1
mixiAug 2014
Financial2 pages
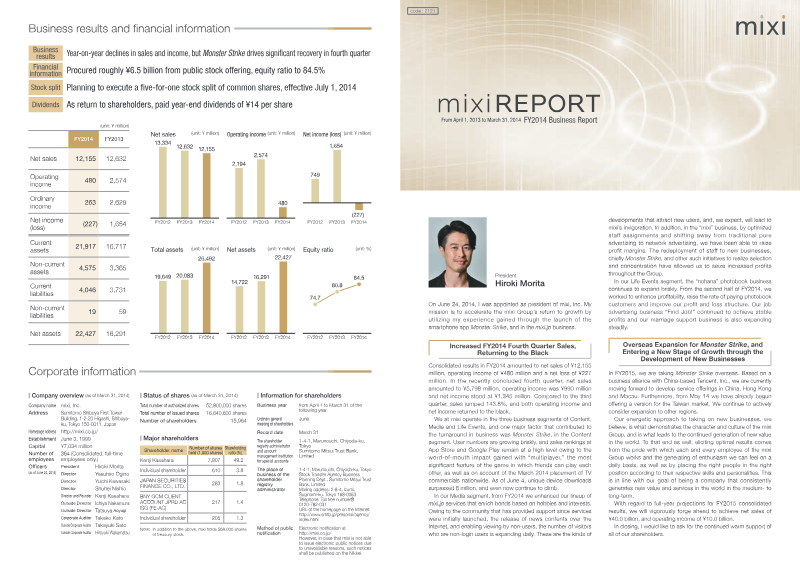
FY2014 Business Report
This business report details the financial performance and strategic pivot of mixi, Inc. for the fiscal year ending March 31, 2014. While the company experienced year-on-year declines in annual sales and income—reporting net sales of ¥12.1 billion and a net loss of ¥227 million—the fourth quarter marked a significant turnaround. Driven by the explosive success of the mobile game Monster Strike, fourth-quarter sales jumped 143.8% compared to the third quarter, returning the company to profitability.
The primary catalyst for this recovery was the Content segment, specifically Monster Strike, which surpassed 8 million users by June 2014. The game achieved the top sales ranking on the App Store following a nationwide television advertising campaign. Beyond gaming, the company optimized its Media segment by shifting from pure advertising to network advertising and removing login requirements for certain services to increase traffic. The Life Events segment also saw growth through the "nohana" photobook service and the acquisition of marriage support businesses like Diverse, Inc. and Confianza & Co., Inc.
Geographically, the company is focused on the Japanese market while aggressively expanding into Greater China. Following a May 2014 launch in Taiwan, mixi established a partnership with Tencent to enter China, Hong Kong, and Macau. Financially, the company strengthened its position by procuring ¥6.5 billion through a public stock offering, raising its equity ratio to 84.5%. Looking forward to FY2015, leadership has set ambitious targets of ¥40.0 billion in net sales and ¥10.0 billion in operating income, supported by a five-for-one stock split to enhance shareholder liquidity.
- Driven by the success of Monster Strike, mixi achieved a 143.8% quarter-over-quarter sales increase in Q4 FY2014, successfully returning the company to profitability after a net loss of ¥227 million for the full fiscal year.
- Monster Strike became the primary revenue driver for the Content segment, reaching over 8 million users by June 2014 and securing the top sales ranking on the App Store following a national TV advertising campaign.
- The company set aggressive growth targets for FY2015, aiming for ¥40.0 billion in net sales and ¥10.0 billion in operating income.
- mixi strengthened its balance sheet by raising ¥6.5 billion through a public stock offering, resulting in an equity ratio of 84.5%.
- International expansion is centered on Greater China, supported by a May 2014 launch in Taiwan and a strategic partnership with Tencent to enter China, Hong Kong, and Macau.
+2
mixiJun 2014
Financial48 pages
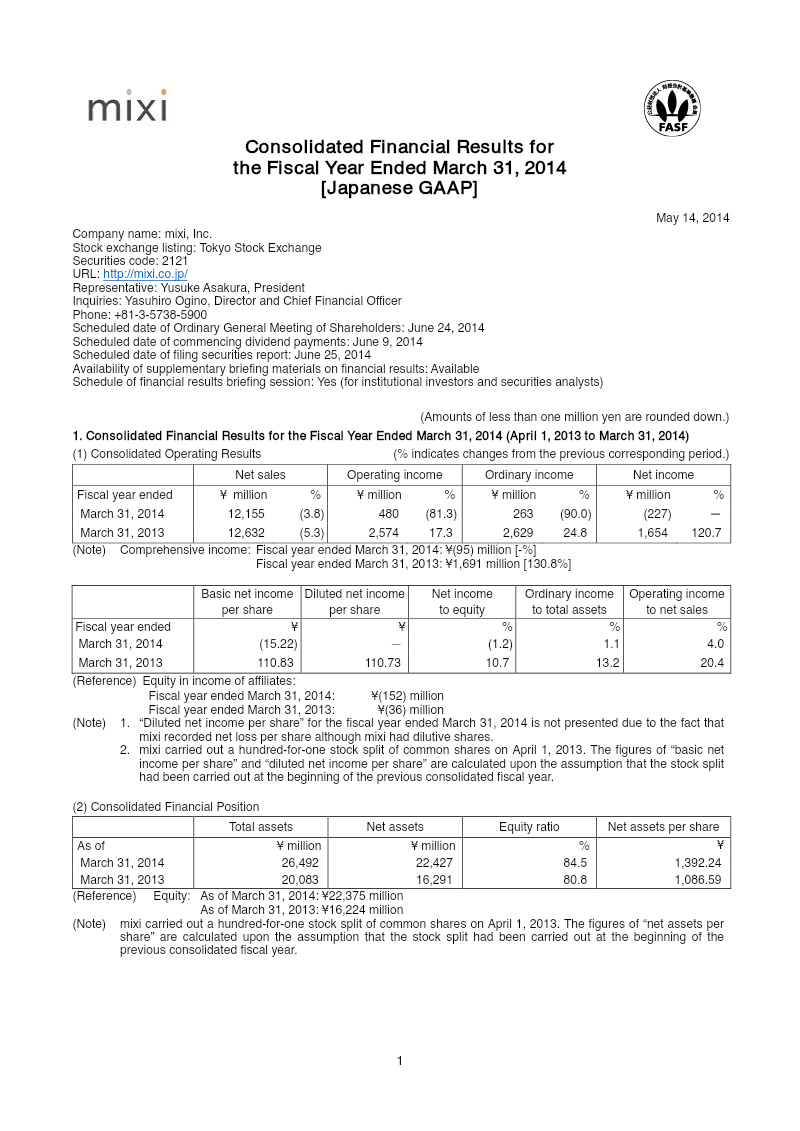
Consolidated Financial Results for the Fiscal Year Ended March 31, 2014
The fiscal year ended March 31, 2014, represented a period of significant structural transition and strategic reinvestment for the Japanese social networking and gaming firm. While net sales experienced a modest 3.8% decline to ¥12,155 million, the company recorded a net loss of ¥227 million, a sharp reversal from the previous year’s profit. This downturn was largely attributed to impairment losses from the liquidation of Chinese subsidiaries, the closure of local bases, and high effective tax rates resulting from goodwill amortization. Despite these losses, the company’s financial foundation remained robust, with total assets increasing to ¥26,492 million and an equity ratio of 84.5%.
The Social Net Business segment served as the primary revenue engine, contributing ¥11,550 million in external sales. This performance was bolstered by the growth of the mobile title Monster Strike, which signaled a shift in the company’s core growth drivers. To support this evolution, the group pursued aggressive portfolio expansion through the 100% acquisitions of Diverse, Inc. and Confianza & Co., Inc. for approximately ¥1.2 billion, alongside a strategic business transfer to enhance research and matchmaking services. These moves were complemented by internal restructuring, including the disposal of aging server infrastructure and software assets totaling ¥337 million.
Capital management was a central focus throughout the period, characterized by a hundred-for-one stock split and new share issuances that raised ¥6.5 billion. These actions nearly doubled cash and cash equivalents to ¥16.8 billion, providing the liquidity necessary for future scaling. Looking toward fiscal year 2015, the outlook is highly optimistic, with projections suggesting net sales will more than triple to ¥40,000 million and net income will reach ¥6,000 million. To further improve share liquidity and broaden the investor base in anticipation of this growth, the board approved an additional five-for-one stock split effective July 2014.
- The company reported a net loss of ¥227 million for the fiscal year ending March 31, 2014, driven by impairment losses from liquidating Chinese subsidiaries and high tax rates, despite net sales of ¥12,155 million.
- Management projects a significant turnaround for fiscal year 2015, forecasting net sales to triple to ¥40,000 million and net income to reach ¥6,000 million.
- The mobile title 'Monster Strike' emerged as the primary growth driver within the Social Net Business segment, which generated ¥11,550 million in external sales.
- Cash and cash equivalents nearly doubled to ¥16.8 billion following a hundred-for-one stock split and new share issuances that raised ¥6.5 billion.
- The company expanded its portfolio through the ¥1.2 billion acquisition of Diverse, Inc. and Confianza & Co., Inc. while simultaneously disposing of ¥337 million in aging infrastructure assets.
+2
mixiMay 2014

Financial4 pages
Quarterly Consolidated Balance Sheets (FY2013 Q3)
The financial statements for the third quarter of fiscal year 2013 reveal a significant downturn in performance compared to the previous year. Net sales dropped by approximately 36%, falling from ¥9,922 million in the prior year’s third quarter to ¥6,357 million. This decline in revenue, coupled with relatively high selling, general, and administrative expenses, resulted in an operating loss of ¥509 million, a sharp reversal from the ¥2,342 million operating income reported during the same period in 2012.
The bottom-line results show a net loss of ¥1,573 million for the nine-month period ending December 31, 2013. This deficit was exacerbated by non-operating expenses, including ¥152 million in equity losses of affiliates, and a substantial increase in deferred income taxes totaling ¥685 million. Total assets decreased from ¥20,083 million at the end of the previous fiscal year to ¥17,623 million, primarily driven by a reduction in cash and deposits and accounts receivable.
Cash flow data indicates a shift in corporate strategy and liquidity management. While operating activities resulted in a net cash outflow of ¥570 million, investing activities provided a net inflow of ¥1,231 million, largely due to the withdrawal of time deposits. Notable investments included ¥925 million for the purchase of investments in subsidiaries and ¥303 million for business transfers, which contributed to a significant increase in goodwill from ¥178 million to ¥1,036 million. Despite the reported net loss, the company maintained a cash and cash equivalents balance of ¥9,628 million at the end of the period, supported by its existing reserves and investment liquidations.
- Net sales for Q3 FY2013 fell 36% year-over-year to ¥6,357 million, resulting in an operating loss of ¥509 million compared to a ¥2,342 million profit in the same period of 2012.
- The company recorded a net loss of ¥1,573 million for the nine-month period ending December 31, 2013, impacted by ¥152 million in equity losses and ¥685 million in deferred income taxes.
- Total assets declined to ¥17,623 million from ¥20,083 million at the end of the previous fiscal year, driven primarily by reductions in cash, deposits, and accounts receivable.
- Despite the net loss, the company maintained a cash and cash equivalents balance of ¥9,628 million, bolstered by the liquidation of time deposits.
- Investing activities generated a net inflow of ¥1,231 million, largely fueled by the withdrawal of time deposits to fund ¥925 million in subsidiary investments and ¥303 million in business transfers.
+1
mixiFeb 2014

Financial4 pages
FY2013 Second-Quarter Financial Statements
The financial results for the second quarter of fiscal year 2013, covering the six-month period ending September 30, 2013, reveal a significant downturn in performance compared to the same period in the previous year. Net sales fell sharply from ¥6,817 million to ¥3,979 million, representing a decline of approximately 41.6%. This contraction in revenue led to an operating loss of ¥398 million, a stark reversal from the ¥1,612 million operating income recorded in the second quarter of fiscal year 2012.
The bottom-line results show a net loss of ¥1,352 million for the period, contrasted with a net income of ¥1,205 million in the prior year. This deficit was exacerbated by a substantial increase in deferred income taxes, which rose to ¥666 million, and equity in losses of affiliates totaling ¥126 million. Consequently, retained earnings decreased from ¥10,409 million at the end of fiscal year 2012 to ¥8,728 million, contributing to a reduction in total net assets to ¥14,664 million.
Despite the reported losses, the consolidated statement of cash flows indicates a stable liquidity position. While operating activities resulted in a net cash outflow of ¥448 million, investing activities generated a significant inflow of ¥2,774 million, primarily driven by ¥4,000 million in proceeds from the withdrawal of time deposits. These movements resulted in a net increase in cash and cash equivalents, ending the period at ¥11,247 million. The balance sheet remains deleveraged with total liabilities decreasing to ¥2,816 million, down from ¥3,791 million at the start of the fiscal year.
- Net sales for the six-month period ending September 30, 2013, plummeted 41.6% to ¥3,979 million, down from ¥6,817 million in the same period of the previous year.
- The company shifted from an operating income of ¥1,612 million in FY2012 to an operating loss of ¥398 million in the current period.
- The bottom line recorded a net loss of ¥1,352 million, a significant reversal from the ¥1,205 million net income reported in the prior year.
- Retained earnings declined from ¥10,409 million at the end of FY2012 to ¥8,728 million, resulting in a reduction of total net assets to ¥14,664 million.
- Liquidity remains stable with cash and cash equivalents totaling ¥11,247 million, bolstered by ¥4,000 million in proceeds from the withdrawal of time deposits.
+1
mixiNov 2013

Financial4 pages
Quarterly Consolidated Balance Sheets: 1Q FY2013
The financial results for the first quarter of fiscal year 2013, covering the period from April 1, 2013, to June 30, 2013, indicate a significant downturn in performance compared to the same period in the previous year. Net sales fell sharply by approximately 39%, dropping from ¥3,539 million in 2012 to ¥2,144 million in 2013. This contraction in revenue led to an operating loss of ¥84 million, a stark reversal from the ¥889 million operating income recorded in the prior year’s first quarter.
The bottom-line results further reflect this decline, with the company reporting a net loss of ¥253 million for the quarter, compared to a net income of ¥562 million a year earlier. This deficit was exacerbated by non-operating expenses, specifically a ¥117 million loss from equity in affiliates, and an extraordinary impairment loss of ¥34 million. Consequently, retained earnings decreased from ¥10,409 million at the end of fiscal year 2012 to ¥9,827 million by June 30, 2013.
Despite the operational losses, the consolidated balance sheet shows a stable liquidity position. Total assets stood at ¥18,868 million, with cash and deposits remaining a primary component at ¥12,643 million. Cash flow analysis reveals that while operating activities resulted in a net outflow of ¥210 million, investing activities generated a significant inflow of ¥2,371 million, primarily driven by the withdrawal of time deposits. This resulted in a net increase in cash and cash equivalents, ending the period at ¥11,143 million. The overall financial position remains characterized by a high equity ratio, though the period was defined by shrinking sales and a transition into net losses.
- Net sales for 1Q FY2013 dropped 39% year-over-year, falling from ¥3,539 million to ¥2,144 million.
- The company shifted from an operating income of ¥889 million in 1Q FY2012 to an operating loss of ¥84 million in 1Q FY2013.
- Net income declined from ¥562 million in the prior year to a net loss of ¥253 million, impacted by a ¥117 million loss from equity in affiliates and a ¥34 million impairment loss.
- Retained earnings decreased from ¥10,409 million at the end of FY2012 to ¥9,827 million by June 30, 2013.
- Despite operational losses, the company maintained a strong liquidity position with ¥12,643 million in cash and deposits out of ¥18,868 million in total assets.
+1
mixiAug 2013

Financial6 pages
Consolidated Balance Sheets (FY2012)
These consolidated financial statements detail the fiscal performance and position of a corporate entity for the period ending March 31, 2013, with comparative data from the previous fiscal year. The reporting covers a full twelve-month cycle, providing a comprehensive view of assets, liabilities, net income, and cash flows. The data indicates a period of significant profitability and liquidity growth, despite a slight contraction in top-line revenue.
Net sales decreased from ¥13.3 billion in FY2012 to ¥12.6 billion in FY2013. However, the entity achieved a substantial increase in net income, which rose from ¥749 million to ¥1.65 billion. This bottom-line growth was driven by improved operational efficiency, as evidenced by a rise in operating income from ¥2.19 billion to ¥2.57 billion, and a significant extraordinary gain of ¥406 million from the sale of subsidiary stocks. Consequently, total net assets grew from ¥14.7 billion to ¥16.3 billion, bolstered by the retention of earnings.
The balance sheet reflects a strong liquidity position, with cash and deposits increasing to ¥13.2 billion. Total assets grew slightly to ¥20.1 billion, while total liabilities decreased from ¥4.9 billion to ¥3.8 billion, primarily due to reductions in income taxes payable and deposits received. Cash flow analysis confirms this healthy position, showing ¥2.8 billion provided by operating activities, a significant improvement over the ¥1.0 billion generated in the prior year. This financial stability was maintained even as the entity engaged in investment activities and paid out ¥149 million in dividends.
- Net income more than doubled from ¥749 million in FY2012 to ¥1.65 billion in FY2013, despite a decline in net sales from ¥13.3 billion to ¥12.6 billion.
- Operational efficiency improved significantly, driving operating income up from ¥2.19 billion to ¥2.57 billion.
- The company strengthened its balance sheet by reducing total liabilities from ¥4.9 billion to ¥3.8 billion while increasing total net assets from ¥14.7 billion to ¥16.3 billion.
- Cash and deposits reached ¥13.2 billion, supported by a substantial increase in cash provided by operating activities from ¥1.0 billion in the prior year to ¥2.8 billion in FY2013.
- Profitability was bolstered by a one-time extraordinary gain of ¥406 million resulting from the sale of subsidiary stocks.
+1
mixiMay 2013