GameDev Reports
Media68 documents
Documents
Article
Weekly Gaming Reports Recap: August 10 – August 14, 2026
The gaming industry experienced significant performance milestones between July 29 and August 11, 2026, characterized by long-term franchise success and notable indie title momentum. Grand Theft Auto V reached 230 million units sold, anchoring the broader Grand Theft Auto series at nearly 475 million copies. Meanwhile, Red Dead Redemption 2 contributed 87 million units to its franchise’s 116 million total. Hardware performance remained a focal point, with the PlayStation 5 surpassing 95 million units sold globally and maintaining 125 million monthly active users as of June 2026. Conversely, Nintendo Switch 2 sales saw a 34.4% year-on-year decline for the quarter, totaling 3.82 million units, though software sales for the platform rose by 9.2%.
Indie and mid-market titles demonstrated varied commercial trajectories. ReStory: Chill Electronics Repairs achieved $1.1 million in gross revenue within 24 hours, while Machine Party sold 500,000 copies in its first week, bolstered by strong performance in the Chinese market. Other successes included Sir, We Have an Orc Problem, which generated $361,600 in gross revenue from 43,700 units in its first day on a minimal $200 marketing budget. In contrast, the experimental title This Game Costs 200 Dollars saw high initial sales volume—primarily from China—that were almost entirely negated by subsequent refund requests.
Mobile gaming activity was highlighted by Pokémon GO, which recorded a record-breaking week during its 10th-anniversary celebrations, generating $48.5 million. This figure represented a 5.9-fold increase over the previous week’s revenue. The data, sourced from various industry reports and financial disclosures, underscores a market environment where established intellectual property continues to drive massive volume, while niche or experimental titles rely heavily on viral engagement and strategic platform integration to achieve rapid, albeit sometimes volatile, commercial results.
- Grand Theft Auto V has surpassed 230 million units sold, contributing to nearly 475 million total sales for the series, while PlayStation 5 global console sales have reached 95 million units.
- Pokémon GO generated $48.5 million during its 10th-anniversary week, representing a 5.9x increase over the previous week and a new revenue record for the title.
- ReStory: Chill Electronics Repairs recouped its budget within 12 hours of release, generating over $1.1 million in gross revenue from 75.7 thousand copies sold on Steam.
- Nintendo Switch 2 hardware sales declined 34.4% year-on-year to 3.82 million units for the quarter, while software sales for the original Switch increased 33.6% to 33.81 million copies.
- Machine Party sold 500,000 copies in its first week, achieving a peak concurrent player count of 22,629, which outperformed the developer's previous title, Buckshot Roulette.
+1
GameDev ReportsAug 2026
Article
Games and Numbers: July 29 — August 11, 2026
This bi-weekly industry update provides a comprehensive overview of performance milestones across the PC, console, and mobile gaming sectors for the period of July 29 to August 11, 2026. The summary tracks commercial success, player engagement metrics, and hardware sales data to illustrate current market trends and the ongoing impact of subscription services like Game Pass on title performance.
Key findings highlight significant longevity and growth in established franchises. Grand Theft Auto V continues to dominate, reaching 230 million units sold, while Pokémon GO achieved a record-breaking $48.5 million in revenue during its 10th-anniversary week. Newer releases also demonstrated strong momentum, with titles like Machine Party and ReStory: Chill Electronics Repairs achieving rapid commercial success. Notably, the data reveals a shift in engagement patterns, such as the 90% surge in daily active users for Assassin’s Creed Odyssey following the release of a related film, and the high volume of wishlists for upcoming titles like Resident Evil Veronica and The Eternal Life of Goldman.
Hardware performance shows a mixed landscape. PlayStation 5 has surpassed 95 million units sold, with a notable preference for digital software, which accounted for 82% of quarterly game sales. Conversely, Nintendo Switch 2 sales experienced a 34.4% year-on-year decline, though software sales for the original Switch platform saw a 33.6% increase. The data, sourced from corporate financial reports, industry analytics firms, and developer announcements, underscores the critical role of multi-platform strategies and digital distribution in shaping modern gaming revenue and player acquisition.
- Grand Theft Auto V has surpassed 230 million units sold, maintaining its position as the best-selling title of the past decade, while the entire GTA series has reached nearly 475 million copies sold.
- PlayStation 5 hardware sales have reached 95 million units globally, with digital game sales accounting for 82% of the 66.1 million units sold during the most recent quarter.
- Pokémon GO generated $48.5 million during its 10th-anniversary week, a record-breaking performance that was 5.9 times higher than the previous week's revenue.
- Nintendo Switch 2 console sales declined 34.4% year-on-year to 3.82 million units for the quarter, though software sales for the platform increased 9.2% to 9.46 million copies.
- ReStory: Chill Electronics Repairs recouped its development budget within 12 hours of release, generating over $1.1 million in gross revenue from 75.7 thousand copies sold on Steam.
+2
GameDev ReportsAug 2026
Article
Weekly Gaming Reports Recap: August 3 - August 7, 2026
The global gaming industry experienced a notable structural shift during the first half of 2026, characterized by a transition toward independent labor models and a strategic pivot in mobile market investment. A significant majority of developers now report higher earnings and increased demand for freelance work compared to traditional full-time employment. This labor evolution coincides with a mobile sector that remains largely stable, though it is increasingly defined by the dominance of specific subgenres. While the broader casual gaming market generated $11 billion in revenue during the first half of the year, growth is increasingly concentrated in hybridcasual puzzle titles, such as sort and block games, which are attracting substantial capital, exemplified by major acquisitions like Scopely’s purchase of Loom Games.
Market performance across mobile, PC, and console platforms reveals a clear preference for established intellectual property and proven mechanics. In the mobile space, puzzle games remain the primary revenue driver, contributing $4.9 billion through in-app purchases, while simulation titles have emerged as a secondary growth engine with $1.1 billion in earnings. Conversely, the casino genre has faced a slight decline as revenue migrates toward direct-to-consumer channels. On PC and consoles, the market is currently anchored by high-profile remasters of legacy franchises, which continue to command significant sales volume.
Despite the reliance on established brands, the industry maintains a capacity for organic growth, as evidenced by the record-breaking $101.1 million monthly revenue for Pokémon GO and the emergence of viral hits on platforms like Steam. These findings suggest that while the industry is currently prioritizing risk mitigation through remasters and proven hybridcasual mechanics, there remains a robust appetite for high-engagement, innovative titles. The overall landscape reflects a mature market that is successfully balancing the stability of legacy franchises with the agility of a growing freelance workforce and emerging mobile subgenres.
- Studio spending on contractors grew 55% globally and 63% in Europe between 2022 and 2025, with 94% of surveyed freelancers reporting increased demand for their services.
- The Merge-2 genre nearly doubled its revenue to $1.24 billion in H1 2026, driven by market leader Gossip Harbor, which reached over $100 million in monthly revenue by March 2026.
- Scopely acquired Loom Games for over $1 billion following the success of Pixel Flow!, a title that generated more than $125 million in IAP revenue in less than a year.
- Hybrid casual block puzzles experienced rapid growth in H1 2026, with revenue increasing 46% and the number of new launches rising 89% year-over-year.
- Casual gaming revenue remained flat at $11 billion for H1 2026, while the Casino genre saw a 9% decline in earnings to $3.3 billion compared to H1 2025.
+2
GameDev ReportsAug 2026
Article
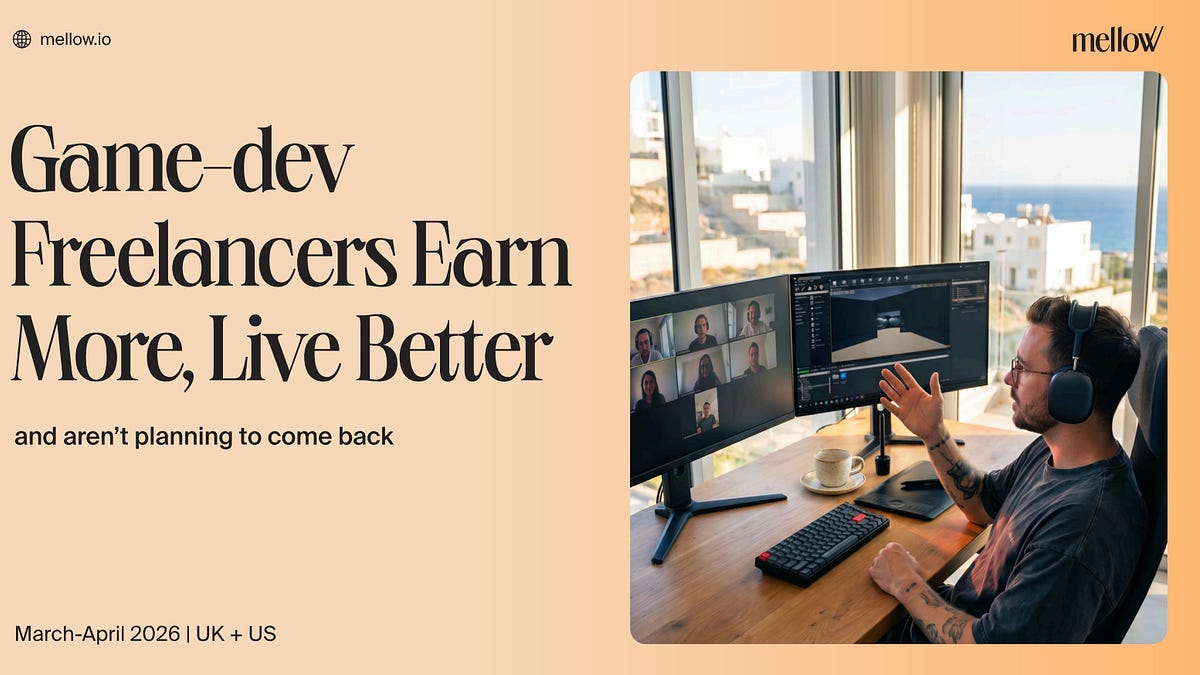
GameDev Freelancers: 2026
The 2026 landscape for game development freelancing reflects a significant shift toward independent work, driven by improved quality of life and higher earning potential. The industry is experiencing a structural transition where studios are increasingly relying on external contractors to maintain agility. This trend is supported by data from a survey of over 1,000 active freelancers in the US and UK, alongside platform metrics covering 2,000 contractors and 150 studios across the EU, Cyprus, the UK, MENA, and North America between 2022 and 2025.
Freelancers report high levels of satisfaction, with 95% noting an improved quality of life after leaving full-time employment. Primary motivators include increased income, project autonomy, and flexible scheduling. Financial gains are substantial, as 91% of freelancers report higher earnings than in previous full-time roles, with 62% earning at least 50% more. Notably, only 14.9% of these individuals entered the freelance market due to layoffs, while the majority made a deliberate career choice. Most freelancers are not seeking a return to traditional employment, with over 50% actively working toward launching their own studios or independent game projects.
Studios are mirroring this shift by increasing their reliance on external talent. Global studio spending on contractors rose by 55%, with European studios seeing a 63% increase. On average, studios now engage 10 contractors simultaneously, and 72% of freelancers reported working with three or more studios over the past year. This data confirms that the move toward a freelance-heavy model is a strategic, long-term adjustment in the gaming industry rather than a temporary response to market volatility.
- Studio spending on contractors has surged significantly, with global expenditure rising 55% and European spending increasing by 63% year-over-year.
- Game development studios are increasingly reliant on external talent, with a 21% global increase in the number of studios hiring freelancers and an average of 10 contractors now working with a studio simultaneously.
- Freelancing in the game industry is a deliberate career choice for 67% of practitioners, with only 14.9% of current freelancers entering the field specifically due to layoffs.
- Quality of life for game industry freelancers is high, with 95% of surveyed professionals reporting an improvement after leaving full-time roles and 91% earning more than they did as employees.
- Despite high satisfaction, 58% of freelancers would consider returning to full-time employment, though only 9.5% have active plans to do so, with over half (50.8%) aiming to launch their own studios or release their own games.
GameDev ReportsAug 2026
Article
Games and Numbers: July 14 – July 28, 2026
This report provides a bi-weekly summary of key performance milestones and commercial data for the global video game industry, covering the period from July 14 to July 28, 2026. The analysis focuses on major PC, console, and mobile titles, highlighting sales figures, player engagement metrics, and pre-order performance to illustrate current market trends.
Recent industry data reveals significant commercial success for several high-profile titles. Palworld surpassed $700 million in revenue with 30.5 million copies sold, while Resident Evil Requiem reached 8 million units sold within four months. Pre-order activity for GTA VI has set new industry benchmarks, generating over $260 million in its first week, with projections suggesting between 37 million and 60 million units sold upon release. Additionally, Ubisoft’s Assassin’s Creed Black Flag Resynced achieved 3.5 million sales in two weeks, and Capcom’s Pragmata reached 2.5 million copies in two and a half months.
Engagement metrics remain robust across established titles and upcoming releases. Human Fall Flat has expanded its total audience to 60 million players, and Wuchang: Fallen Feathers has reached 5 million users since its launch. Anticipation for upcoming games is also high, evidenced by significant wishlist activity: Dear Passengers has secured over 1.5 million wishlists, Hela: of Mice & Magic has surpassed 1 million, and The Mound: Omen of Cthulhu has exceeded 800,000. In the mobile sector, the PvP strategy game Ludus: Merge Arena has generated $50 million in net revenue since its October 2023 launch, supported by a player base of 11 million. These figures underscore a period of strong performance driven by both established franchises and successful new intellectual properties.
- GTA VI pre-orders generated over $260 million in the first week, with projections estimating at least 37 million units sold and $3.25 billion in revenue during its release week.
- Palworld has surpassed $700 million in revenue with 30.5 million copies sold, seeing a massive surge in average daily active users to 3.7 million following its full release on July 10.
- Ubisoft’s Assassin’s Creed Black Flag Resynced reached its full-year sales target by selling 3.5 million copies within its first two weeks.
- Capcom’s Resident Evil franchise reached 213 million lifetime sales as of June 30, 2026, while its new title Pragmata sold 2.5 million copies in two and a half months.
- The co-op simulator Dear Passengers has secured over 1.5 million wishlists in under two weeks, while Hela: of Mice & Magic has surpassed 1 million wishlists ahead of its Q4 2026 launch.
+2
GameDev ReportsJul 2026
Article
Weekly Gaming Reports Recap: July 20–24, 2026
The global gaming landscape is undergoing a structural shift toward hybrid monetization as developers seek to maximize revenue from both paying and non-paying users. The Chinese mini-games sector serves as a primary engine for this expansion, with market valuations climbing from $7.65 billion in 2025 toward a projected $9.72 billion in 2026. Simultaneously, mobile gaming ad revenue reached $12 billion across 19 major markets in 2025, driven by a transition where 56% of titles now incorporate ad-supported frameworks. This trend is particularly pronounced in the casual and puzzle genres, which currently command the majority of ad-driven income.
Market concentration remains a defining characteristic of the advertising ecosystem, as AppLovin and Google AdMob maintain a combined 65% share of global ad revenue. While non-gaming sectors like fintech and retail are increasingly utilizing gaming platforms for impressions, the internal economics of user-generated content platforms remain highly stratified. On platforms such as Roblox, a significant earnings disparity persists, where the vast majority of developers earn less than $1,500 annually despite the high-earning potential of top-tier creators.
Geographic diversification is emerging as a strategic priority, with the Gulf region identified as a high-growth area due to its superior average revenue per user. These trends, coupled with the impact of delayed major releases and evolving content strategies, underscore a broader industry pivot. Developers are increasingly moving away from pure in-app purchase models toward integrated monetization strategies to stabilize revenue streams in an environment characterized by high competition and shifting consumer engagement patterns.
- China’s WeChat mini games market reached RMB 53.535 billion (~$7.65 billion) in 2025, a 34.39% year-over-year increase, with projections to exceed RMB 70 billion (~$9.72 billion) in 2026.
- Global mobile game ad revenue reached $12 billion across 19 major markets in 2025, driven by 2.4 trillion ad impressions and 25 billion downloads of ad-monetized games.
- AppLovin and Google AdMob dominated the global mobile game ad market from January 2025 to May 2026, collectively capturing 65% of total ad revenue.
- In the WeChat mini games ecosystem, IAP accounted for 68.11% of 2025 revenue, while the number of games running paid ads grew by 54% year-over-year to over 51,000 titles.
- Non-gaming brands represent 31-49% of all ad impressions in top-tier ad-monetized games, with fintech and shopping apps being the most aggressive buyers in their respective genres.
+3
GameDev ReportsJul 2026
Article
Weekly Gaming Reports Recap: July 13 - July 17, 2026
The global gaming industry in mid-2026 is defined by a profound divergence in platform performance and investment sentiment. While Steam achieved a record-breaking $11.1 billion in revenue for the first half of the year, the mobile sector struggled, recording its weakest quarterly performance since 2023 with $19.4 billion in in-app purchase revenue and a five-year low in new installs. Console markets similarly faced volatility, as Sony and Microsoft reported revenue declines, contrasting sharply with Nintendo’s 90% revenue surge fueled by the successful launch of the Switch 2.
Despite underperforming public gaming stocks, the broader financial landscape remains resilient. Private investment reached a two-year high of $3.1 billion, heavily concentrated in artificial intelligence initiatives, while merger and acquisition activity climbed to its highest deal count since 2022. This influx of capital suggests that investors are prioritizing long-term technological integration and strategic consolidation over immediate public market returns.
Structural challenges persist within creator-led ecosystems and regional markets. On platforms like Roblox, a significant earnings disparity remains, with top-tier developers generating millions while the median annual payout stays below $1,500. Meanwhile, the Gulf region has emerged as a critical growth area characterized by high average revenue per user. These trends, coupled with the lingering market impact of the absence of major titles like GTA VI in 2025, indicate an industry in transition. Steam’s increasing reliance on back-catalog sales further underscores a shift in consumer behavior, where established libraries are currently driving growth more effectively than new releases.
- Steam generated $11.1 billion in gross revenue during H1 2026, marking a 14.5% year-over-year increase and nearly matching the platform's total revenue for the entire year of 2021.
- Private investment in the gaming sector reached $3.1 billion in Q2 2026, a nearly 6x year-over-year increase driven largely by a $1 billion round for AppsFlyer and significant capital flowing into AI-focused companies.
- Series A funding reached a five-year high of $0.8 billion in Q2 2026 (up 530% year-over-year), while pre-seed and seed funding dropped to a multi-year low of $0.1 billion (down 56% year-over-year).
- Xbox Game Pass has reached approximately 30 million subscribers, falling significantly short of Microsoft's original target of 77 million by 2026.
- Gaming company valuations are compressing across all segments, with mobile publishers currently trading at the lowest multiples (4.5x–4.7x EV/NTM EBITDA) despite many firms reporting solid revenue growth.
+2
GameDev ReportsJul 2026
Article
Weekly Gaming Reports Recap: July 6 - July 10, 2026
The global gaming landscape in mid-2026 reflects a period of significant structural transition, characterized by shifting monetization models, evolving consumer engagement patterns, and the continued dominance of independent creative successes. While established mobile giants like Honor of Kings face revenue contractions, the market is simultaneously buoyed by the unexpected performance of solo-developed titles, exemplified by the 11.5 million units sold by Meccha Chameleon on Steam. This indicates a broader market trend where players are increasingly gravitating toward lower price points and diverse, high-quality indie experiences rather than relying solely on traditional blockbuster releases.
Strategic shifts are also evident in how studios approach distribution and accessibility. Direct-to-Consumer payment models are gaining traction as a potential alternative to platform-controlled ecosystems, though most developers currently lack the internal infrastructure to execute these strategies at scale. Simultaneously, the web gaming sector is expanding as a viable platform for multi-platform users who prioritize accessibility. Despite this growth, technical barriers regarding porting and optimization remain a primary hurdle for developers looking to capitalize on browser-based gaming.
Esports continues to serve as a critical pillar of industry growth, particularly among Gen Z audiences. With a global reach of 640 million viewers generating $3 billion in annual revenue, the sector is undergoing a demographic shift marked by rising female participation and a move away from traditional broadcast media. Engagement is increasingly concentrated on short-form and social-video platforms like YouTube and TikTok, where branded content effectively captures the attention of a diversifying fan base. These findings underscore a market that is moving toward decentralized distribution and platform-agnostic consumption, requiring developers to prioritize technical agility and community-focused engagement to remain competitive.
- Mobile gaming revenue for top titles saw a significant decline in June 2026, with the top 10 titles earning 10.6 million, a 29% decrease from the previous month.
- Direct-to-consumer (D2C) payment channels are increasingly utilized in mobile gaming, with 35% of studios building solutions in-house and 28% of companies reporting that D2C accounts for over 50% of their total revenue.
- Last War: Survival experienced its third consecutive month of revenue decline, dropping to $71.4 million in June as user acquisition efforts appear to have stalled to their lowest levels since November 2023.
- Steam new-release revenue was notably quiet in June 2026, with only two games exceeding $10 million in revenue compared to six games in May, as developers adjusted release schedules around industry events.
- The web gaming market is expanding, with the platform Poki reaching over 100 million monthly active users, and 53% of surveyed developers planning to port mobile titles to the web within the next 12 months.
+1
GameDev ReportsJul 2026
Article
The Impact of Mobile Games in Europe: 2026
The report demonstrates that mobile gaming remains a dominant force in Europe’s digital economy, with 2025 revenues reaching €7.53 billion and a projected €8 billion by 2028 (CAGR –2.2 %). Nordicity’s economic analysis, covering over 1,000 studios across 32 countries and drawing on Sensor Tower data, assigns a €5.89 billion Gross Value Added (GVA) contribution to the broader economy and 63,340 jobs in 2025. For EU member states alone, GVA is €5.2 billion with 50,330 jobs, rising to €6.17 billion by 2028 (+4.8 %). The methodology bases GVA on studios’ in‑country expenditures—wages, user acquisition spend and other costs—rather than operating profit, a conservative approach acknowledged by the authors.
Globally, mobile games account for 55 % of the €167.26 billion games market in 2025, with Europe’s share reflecting a similar proportion. Over 300 million Europeans play on mobile devices (61 % of active players), and 97 % engage with free‑to‑play titles, totaling more than 320 million users. The average player age is 31, with 75 % adults. Mobile publishers allocate 41 % of annual budgets to player acquisition and retention, underscoring intense competition amid falling download volumes.
Revenue distribution highlights Finland (€1.4 billion), the UK (€895 million), Ireland (€868 million), Spain (€722 million) and Sweden (€630 million) as top markets. Smaller economies such as Cyprus, Serbia and Ukraine generate disproportionate revenue relative to GDP size.
Social impact findings from a 1,500‑person survey in the UK, Spain and Sweden show that daily mobile gamers report higher confidence with technical tools. The Sea Hero Quest title, developed in partnership with Alzheimer’s Research UK, collected data from 4.3 million players, contributing to dementia research.
The study draws on Nordicity data, Sensor Tower metrics, Newzoo and ESA figures, and a UK/Spain/Sweden youth survey conducted between January 1 and December 31 2025. The commissioned report aims to underscore the economic and social value of European mobile studios amid forthcoming regulatory scrutiny.
- Mobile games generated €91.25 billion globally in 2025, representing 55% of the total games market, significantly outperforming console (€40.66 billion) and PC (€35.35 billion).
- European mobile game studios contributed €5.89 billion in Gross Value Added (GVA) to the economy in 2025 and supported 63,340 jobs across 32 European countries, with GVA projected to grow to €6.17 billion by 2028.
- Over 300 million people in Europe played mobile games in 2025, accounting for 61% of the region's active players, with 97% playing free-to-play (F2P) games.
- European mobile companies generated €7.53 billion in revenue from global players in 2025, with a projected increase to over €8 billion by 2028.
- Finland was the top European market by mobile game revenue in 2025 (€1.4 billion), followed by the UK (€895 million), Ireland (€868 million), Spain (€722 million), and Sweden (€630 million).
+1
GameDev ReportsJul 2026
Article
Games and Numbers (June 17 - June 30, 2026)
The bi‑weekly “Games and Numbers” update tracks milestone achievements for PC, console, and mobile titles released between June 17 and June 30, 2026. It aggregates sales figures, download counts, and revenue milestones from a mix of press releases, social media announcements, and third‑party analytics. The report highlights several high‑profile successes: “Black Myth: Wukong” surpasses 30 million copies worldwide, with China contributing nearly half; “Meccha Chameleon” reaches 10 million copies in just 16 days, peaking at 209.7 k concurrent users and entering Steam’s top‑100 most popular titles; “Kingdom Come: Deliverance II” exceeds 6 million copies in 16 months; “Warhammer 40,000: Rogue Trader” hits 2 million copies sold; and “Paralives” delivers over 1 million copies in a month, far exceeding its own projections. Other notable entries include “SAND: Raiders of Sophie,” which sold 200 k copies in a week and earned $2 million in five days, and “KIBORG,” which surpassed 100 k copies within a year. Mobile performance is underscored by “Rush Royale,” which has generated over $500 million in revenue from 105 million downloads. Platform‑wide data notes that Epic Games has paid creators over $1 billion through Unreal Editor for Fortnite, with creator‑built islands accounting for 47 % of playtime in May 2026. The summary draws on publicly available sales data, Steam analytics, and publisher statements to provide a concise snapshot of commercial momentum across the industry during the reporting period.
- Epic Games has paid content creators over $1 billion through Unreal Editor for Fortnite since its March 2023 launch. By May 2026, creator-built islands accounted for 47% of Fortnite's total playtime, an increase from 35% a year prior.
- Black Myth: Wukong by Game Science has sold over 30 million copies, with nearly half of these sales originating from China.
- Meccha Chameleon by lemorion_1224 sold over 10 million copies within 16 days of release, reaching a peak concurrent user count of 209.7k on Steam, placing it among the top 100 most popular titles in Steam's history.
- Kingdom Come: Deliverance II by Warhorse Studios sold over 6 million copies within 16 months of its release.
- Rush Royale by MY.GAMES has generated over $500 million in revenue and accumulated 105 million downloads over five and a half years.
+2
GameDev ReportsJun 2026
Article
Weekly Gaming Reports Recap: June 15–June 19, 2026
The recap compiles key market movements and developer insights for the week of June 15–19, 2026. It highlights a forecast from Niko Partners that the combined Asian and MENA gaming market will exceed $100 billion by 2030, driven primarily by China’s continued growth to an estimated $59.8 billion and a 3.1 % CAGR across the region, while India and Southeast Asia show strong revenue expansion at 14–15 % annually. The report notes China’s ARPU surpassing $70 in 2025 and a projected rise to nearly $78 by 2030, with player counts reaching 769 million. In the Middle East, MENA‑3 is projected to hit $2.94 billion by 2030 with an ARPU jump to $38, and the UAE alone could reach a $100 ARPU.
Almedia’s survey of 912 developers across ten tier‑1 markets reveals that 93 % already invest in rewarded user acquisition, with 61 % planning to increase budgets and only 2 % cutting spend. The data shows that 76 % of studios use rewarded UA, allocating an average of 11–24 % of their total acquisition spend to the channel. Minimum daily spend thresholds are identified at $3,000, and 74 % of studios partner with four or more rewarded channels. The survey also outlines common concerns such as churn, fraud, and data volatility.
Game‑file analysis of Sony’s first‑party titles indicates a four‑year decline in sales from 58.4 million copies in fiscal 2020 to 28.9 million in fiscal 2024, with a partial rebound to 32.1 million in fiscal 2025 thanks to “Ghost of Yotei.” The report projects optimism with upcoming releases like Marvel’s Wolverine. Overall, the recap provides a concise snapshot of regional market trajectories, developer acquisition strategies, and platform sales trends for mid‑2026.
- Niko Partners projects the combined Asia and MENA gaming markets to reach $103.6 billion by 2030, with a 3.1% CAGR, and a player base of 1.99 billion. China, Japan, and South Korea will account for 88.6% of this revenue.
- China's gaming market surpassed $50 billion for the first time in 2025, reaching $51.8 billion (+5.4% YoY), and is expected to grow to $59.8 billion by 2030.
- Rewarded User Acquisition (UA) is widely adopted, with 93% of surveyed developers already spending on it and 61% planning to increase their budgets. Most studios allocate 11-24% of their total UA budget to this method.
- Several PC/Console games saw significant sales in a short period: Crimson Desert sold over 6 million copies in under three months, 007 First Light sold over 3 million in under two weeks, and Meccha Chameleon sold over 2 million in six days.
- The Nintendo Switch 2 experienced an 87% sales drop in Japan in the week following a price increase, after an initial surge.
+2
GameDev ReportsJun 2026
Article
Sony's First-Party Games Sales Trends
Sony’s first‑party game sales on PlayStation have fallen steadily since fiscal 2020, when the platform sold 58.4 million copies—boosted by high‑profile releases such as The Last of Us: Part II, Ghost of Tsushima, and the launch of the PS5. By fiscal 2024, sales had dropped to 28.9 million copies, the lowest level since 2018, reflecting a nearly 50 % decline. The downturn coincided with titles that underperformed commercially, including Astro Bot and the controversial Concord.
Fiscal 2025 marked a modest rebound, with sales rising to 32.1 million copies largely due to the strong performance of Ghost of Yotei. Analysts note that Sony’s upcoming launch of Marvel’s Wolverine could further stabilize sales, suggesting a potential turnaround in the near term.
The data set covers Sony’s fiscal years (April – March) from 2020 to 2025, focusing exclusively on first‑party titles released for the PlayStation console family. Sales figures are sourced from industry tracking services that compile physical and digital unit counts across global markets. No survey methodology is involved; the analysis relies on publicly reported sales data.
Overall, the trend indicates a significant contraction in first‑party game revenue over four years, with recent releases providing limited relief. Future performance will likely hinge on the commercial success of upcoming flagship titles and Sony’s ability to sustain consumer interest in its exclusive lineup.
- Sony’s first-party game sales experienced a nearly 50% decline from a peak of 58.4 million units in fiscal 2020 to a low of 28.9 million units in fiscal 2024.
- The sales drop between 2020 and 2024 represents the lowest volume of first-party units sold by Sony since 2018.
- Fiscal 2025 saw a modest recovery in sales to 32.1 million units, driven primarily by the commercial performance of Ghost of Yotei.
- Recent sales performance was negatively impacted by the underperformance of specific titles, including Astro Bot and Concord.
- Future stabilization of Sony's first-party sales is contingent on the commercial success of upcoming flagship releases, most notably Marvel’s Wolverine.
+2
GameDev ReportsJun 2026