CyberAgent
Game Co.111 documents
Internet/media company, parent of Cygames (Granblue Fantasy, Uma Musume, Princess Connect). Game segment is major revenue driver.
Documents
Presentation43 pages
2Q FY2020 Presentation Material: January to March 2020
CyberAgent achieved record-high financial performance during the second quarter of fiscal year 2020, with consolidated sales reaching 129.1 billion yen and operating profit surging 45.3% year-over-year to 12.4 billion yen. This growth was primarily anchored by the Game Business, which generated 44.8 billion yen in revenue. Success in this segment was driven by high-profile anniversary events for established titles like Granblue Fantasy and the strong market debut of KonoSuba: Fantastic Days. By the end of the first half, the company had already secured between 63% and 72% of its full-year profit targets, though projections for the remainder of the year remain cautious due to anticipated declines in advertising demand stemming from the COVID-19 pandemic.
The media segment, centered on the ABEMA streaming platform, demonstrated significant momentum as stay-at-home orders accelerated user adoption. ABEMA reached 52 million downloads and grew its premium subscriber base to 676,000, with a clear trajectory toward one million subscribers by the end of the calendar year. While the segment still operates at a loss, these losses narrowed to 4.2 billion yen as sales rose nearly 19%. Monetization efforts are diversifying beyond traditional advertising into subscriptions and related services, such as the WinTicket betting platform, which saw transaction volumes double quarter-on-quarter to 3.5 billion yen.
Strategic priorities for the future focus on balancing short-term gains with long-term operational stability. In the gaming sector, the emphasis remains on high-quality development and extending the lifecycle of existing intellectual properties. Simultaneously, the media division is pivoting toward a multi-faceted revenue model to ensure the sustainability of its expanding digital ecosystem. Despite the broader economic uncertainty introduced by global health trends, the current fiscal trajectory suggests a robust foundation built on digital entertainment and diversified media services.
- CyberAgent achieved record-high Q2 FY2020 consolidated sales of 129.1 billion yen and a 45.3% year-over-year increase in operating profit to 12.4 billion yen.
- The Game Business drove performance with 44.8 billion yen in revenue, bolstered by anniversary events for Granblue Fantasy and the successful launch of KonoSuba: Fantastic Days.
- By the end of the first half of FY2020, CyberAgent had already achieved 63% to 72% of its full-year profit targets.
- The ABEMA streaming platform reached 52 million downloads and 676,000 premium subscribers, with management targeting one million subscribers by the end of the calendar year.
- The media segment narrowed its operating loss to 4.2 billion yen as sales grew nearly 19%, supported by a doubling of WinTicket betting transaction volumes to 3.5 billion yen.
+1
CyberAgentApr 2020
Financial10 pages
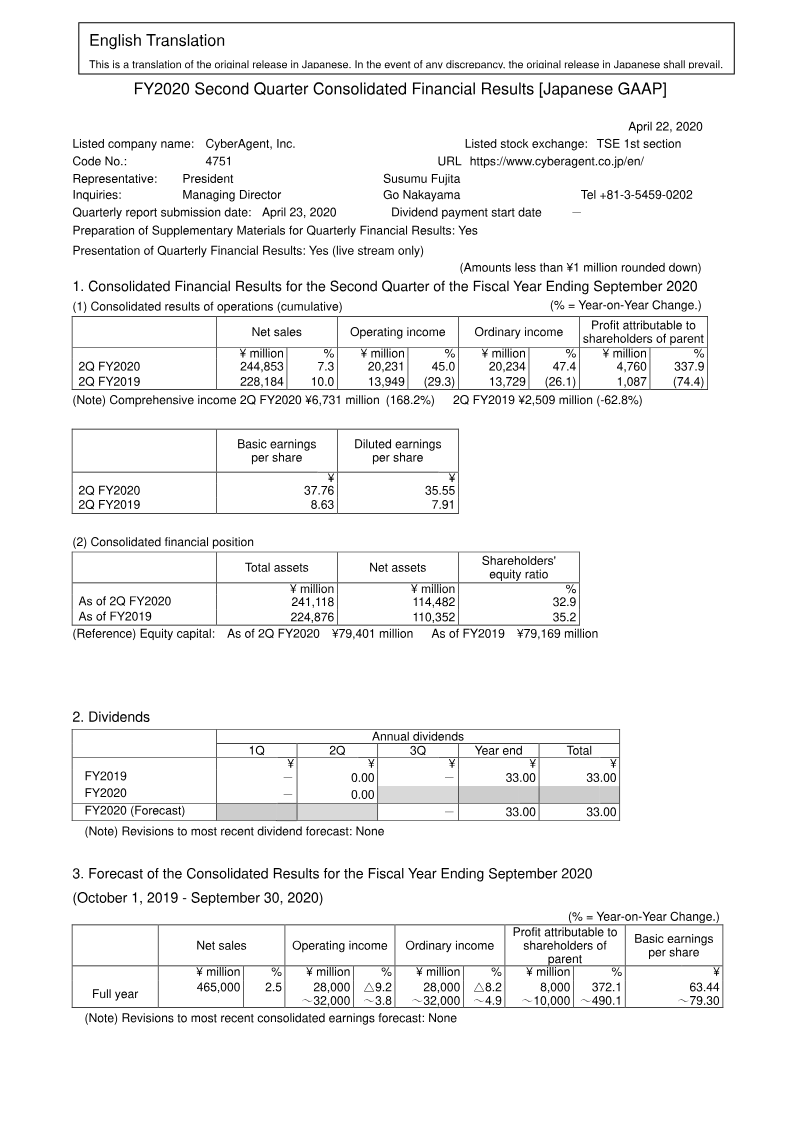
FY2020 Second Quarter Consolidated Financial Results (Japanese GAAP)
CyberAgent, Inc. reported strong financial growth for the first half of fiscal year 2020, covering the period from October 1, 2019, to March 31, 2020. Net sales reached ¥244.85 billion, a 7.3% increase over the previous year, while operating income rose significantly by 45.0% to ¥20.23 billion. Profit attributable to shareholders of the parent saw the most dramatic surge, increasing 337.9% to ¥4.76 billion. These results were driven by the steady expansion of the smartphone advertisement market and successful performance across the company's core business segments.
The Game Business was a primary driver of profitability, with operating income increasing 45.9% to ¥15.56 billion, bolstered by anniversary events for major titles and successful new releases. The Internet Advertisement Business also performed well, recording a 28.1% increase in operating income to ¥12.39 billion through the acquisition of new advertisers. Conversely, the Media Business, which includes the ABEMA streaming platform, reported an operating loss of ¥9.28 billion as the company continues to invest in the service as a long-term mainstay. The Investment Development Business saw declines in both sales and income compared to the prior year.
The consolidated financial position remains stable with total assets of ¥241.12 billion. Cash and cash equivalents increased slightly to ¥84.96 billion, supported by strong net cash provided by operating activities. Despite the positive mid-year performance, the company maintained its original full-year earnings forecast, citing various risks and uncertainties. The report covers CyberAgent’s operations primarily within the Japanese market and utilizes Japanese GAAP accounting standards. No revisions were made to the dividend forecast, which remains at ¥33 per share for the fiscal year.
- CyberAgent reported strong H1 FY2020 growth with net sales of ¥244.85 billion (up 7.3%) and operating income of ¥20.23 billion (up 45.0%).
- Profit attributable to shareholders surged 337.9% year-over-year to ¥4.76 billion.
- The Game Business served as the primary profit driver, achieving a 45.9% increase in operating income to ¥15.56 billion due to successful new releases and anniversary events.
- The Internet Advertisement Business grew operating income by 28.1% to ¥12.39 billion, driven by the acquisition of new advertisers.
- The Media Business, including the ABEMA streaming platform, recorded an operating loss of ¥9.28 billion as the company continues long-term investment in the service.
CyberAgentApr 2020
Presentation26 pages
1Q FY2020 Presentation Material: October to December 2019
Financial performance for the first quarter of fiscal year 2020, covering October to December 2019, reflects a period of strategic investment and steady growth across core digital segments. Net sales reached 115.6 billion yen, representing approximately 25% of the full-year forecast of 465 billion yen. Operating income and ordinary income both stood at 7.7 billion yen, tracking toward an annual target range of 28 billion to 32 billion yen. Profit attributable to owners of the parent was 1.4 billion yen, fulfilling roughly 15% to 18% of the projected 8 billion to 10 billion yen annual goal.
The gaming segment maintained momentum through the performance of established titles and new releases. Key contributors included the third anniversary of Princess Connect! Re:Dive and the ongoing success of Granblue Fantasy and BanG Dream! Girls Band Party. New market entries such as Kick-Flight and the global expansion of Monster Strike further diversified the portfolio. In the media sector, the Abema platform demonstrated significant scaling, reaching 48 million downloads by the end of the quarter. Weekly active users showed consistent upward trends, supported by diverse programming including news, sports, and original reality content like Weekend Homestay.
Strategic focus remains on the medium- and long-term monetization of the media business. The revenue model is evolving to balance advertising and subscription income with expanding peripheral businesses, such as the WinTicket betting service. This diversification aims to accelerate the path to profitability for the streaming segment. Geographically centered in Shibuya, Japan, the organizational strategy emphasizes integrated reporting and a unified corporate culture to drive innovation across advertising, gaming, and digital media services.
- The company generated 115.6 billion yen in net sales for 1Q FY2020, meeting approximately 25% of its 465 billion yen full-year revenue target.
- Operating and ordinary income both reached 7.7 billion yen, tracking toward the annual target range of 28 billion to 32 billion yen.
- Profit attributable to owners of the parent was 1.4 billion yen, representing 15% to 18% of the projected 8 billion to 10 billion yen annual goal.
- The Abema media platform reached 48 million total downloads by the end of December 2019, supported by growth in weekly active users across news, sports, and original reality programming.
- Gaming segment momentum was driven by established titles including Granblue Fantasy, BanG Dream! Girls Band Party, and the third anniversary of Princess Connect! Re:Dive.
+1
CyberAgentJan 2020