Showing 30 of 2,310 results · 1.76s
Jan 2022
Global White Paper on Mobile Advertising & Marketing Game H1 2022
SocialPeta
dropping 27 % to 40 million assets. This downward pressure was most pronounced among mobile‑game advertisers, whose pool shrank to about 83 000 in January, while non‑game
Whitepaper191 pages
Jan 2025
Reclaiming the Game Distribution Landscape
Aptoide
This analysis examines the shifting dynamics of the mobile game distribution market as of Summer 2025, focusing on the transition from a duopoly dominated by Apple and Google
Report21 pages
Dec 2020
Steam's End of Year Bonanza Gets 'Experimental'
GameDiscoverCo
preceding Autumn Sale. Beyond PC storefronts, the analysis addresses the ethics of mobile game acquisition, highlighting the prevalence of misleading advertising. Many free-to-play mobile titles utilize
Article1 pages
Mar 2026
Weekly Gaming Reports Recap: March 2 – March 6, 2026
GameDev Reports
This industry update provides a comprehensive overview of mobile gaming performance for February 2026 and a detailed analysis of the Chinese gaming market’s 2025 performance. The primary
Article1 pages
Jan 2019
Czech Video Game Industry: PC, Console and Mobile Game Developers in Czech Republic 2019
Institute for Digital Economy
CONSOLE AND MOBILE GAME DEVELOPERS IN CZECH REPUBLIC 2019 DEVELOPERS IN CZECH REPUBLIC 2019 This Study was prepared by the Institute for Digital Economy (www.digitalniekonomika.cz) in cooperation with
Report47 pages
Sep 2023
Insights into Marketing Trends of Global Mobile Games: Q3 2023
SocialPeta
analysis focuses on contemporary marketing dynamics within the global mobile gaming sector, emphasizing how creative diversification and platform targeting shape user acquisition performance. In the third quarter
Report42 pages
May 2022
Two & a Half Gamers Session #15: Can UA Save Your Game?
Brutally Honest
This discussion provides a comprehensive overview of User Acquisition (UA) strategies within the mobile gaming industry, specifically addressing the misconception that UA can serve as a panacea
Article1 pages
Jan 2026
Top Mobile Game Ad Creatives and Advertising Trends: December 2025
SocialPeta
analysis focuses on global mobile game advertising activity in December 2025, drawing from a database of over 1.7 billion creatives across more than 80 countries. Key findings show
Article1 pages
Jan 2024
State of Mobile Games in Japan
Sensor Tower
analysis provides a comprehensive overview of Japan’s mobile‑gaming ecosystem in 2024, measuring the market’s size, growth dynamics, and competitive landscape. Total in‑app purchase
Report30 pages
Jan 2025
Sensor Tower India: Mobile Game Market Insights 2025
Sensor Tower
India is positioned as the world’s largest mobile‑gaming market, with 8.45 billion downloads recorded in FY 2024‑25 yet only $400 million in in‑app purchase
Report29 pages
Mar 2026
ByteDance Sells MLBB Publisher Moonton to Saudi Savvy Games Group
Esports Charts
mobile gaming market, Savvy Games Group significantly expands its influence over global competitive gaming ecosystems. This transaction underscores the increasing capital intensity of the gaming industry
Article1 pages
Jan 2015
Brand Marketing and Performance Marketing Can Co‑exist on Mobile
Mobile Dev Memo
evolution of the mobile gaming industry necessitates a dual approach to advertising that integrates both brand and performance marketing. While performance marketing remains the primary driver for user
Article
Mar 2026
Hybrid Casual UA Playbook
Matej Lancaric
provide actionable user acquisition (UA) strategies for the burgeoning hybrid-casual mobile gaming sector. The central thesis posits that success in the post-IDFA landscape requires a sophisticated
Article
Jan 2022
Two & a Half Gamers Session #8: Game Design Fundamentals & When to Kill a Game
Two & a Half Gamers
mobile game design and the critical decision-making processes involved in product lifecycles. The analysis centers on the professionalization of the game designer role, contrasting the mobile gaming
Article
Dec 2025
Global Mobile Games in November: November 2025 Market Trends
SocialPeta
November 2025 snapshot of the global mobile gaming market highlights a continued dominance of established IPs and the rapid rise of new casual titles. In advertising spend, Nexon
Article1 pages
Sep 2025
Global Mobile Games in August 2025: Advertising, Revenue, and Downloads
SocialPeta
analysis focuses on August 2025 mobile game performance worldwide, covering advertising spend, revenue generation, and download volumes across the Apple App Store and Google Play. Key findings show
Article1 pages
Public Mobile Gaming Publishers: Resilience & Adaptation in a Shifting Landscape
InvestGame
analysis examines the post‑IDFA mobile gaming landscape, focusing on revenue dynamics, user acquisition spending, profitability trends, and market valuation shifts across key publishers. Data reveal that annual
Report7 pages
Nov 2025
Global Mobile Games in October 2025: Advertising, Revenue, and Download Trends
SocialPeta
October 2025 snapshot of the global mobile gaming market highlights a resurgence of line‑drawing puzzle mechanics, with Tile Explorer from Oakever Games leading download growth on Google
Article1 pages
Jan 2025
Annual Report of the German Games Industry 2025
game
game purchases, which fell 17 %, while online gaming and subscription services surged 43 % to €3.26 billion, underscoring a decisive shift toward digital and cloud‑based play. In‑game
Report39 pages
Sep 2026
Weekly Gaming Reports Recap: August 31 - September 4, 2026
GameDev Reports
highlighting a reliance on international products. In Japan, the mobile app market shows shifting consumption patterns. While mobile game installs grew 3% in the first half
Article1 pages
Dec 2024
Insights into Global Mobile Game Marketing Trends for H1 2025
SocialPeta
first half of 2025 reveals a rapid shift in mobile‑game user‑acquisition toward AI‑driven creative production, with short‑form video, live‑action clips and in‑game
Report66 pages
Jan 2021
Mobile Game Genre Report: Comparing & Contrasting Eastern and Western Markets 2021
Newzoo
This report examines the mobile gaming landscape in 2021, focusing on the strategic differences between Eastern and Western markets regarding genre popularity, monetization, and user acquisition. While mobile
Report25 pages
Jan 2022
Brutally Honest #44
Brutally Honest
industry observation and qualitative deconstruction of existing mobile titles. It addresses the broader mobile ecosystem by offering guidance on selecting Mobile Measurement Partners (MMPs) within an increasingly privacy
Article
Mar 2026
Top Mobile Game Ad Creatives and Advertising Trends: February 2026
SocialPeta
February 2026 analysis reveals that global mobile game publishers are scaling creative output to accelerate user acquisition. In February, the 3D match‑3 title 3D Bolt Master deployed
Article1 pages
Jul 2026
Brutally Honest #219
Brutally Honest
This analysis focuses on mobile game user acquisition (UA) and creative strategy in the post-IDFA landscape, emphasizing the necessity of operational efficiency to bridge the gap between
Article1 pages
Jan 2023
2023 A Liftoff Company Midcore Gaming Apps Report
A Liftoff Company
Midcore mobile games now represent roughly one‑third of U.S. iOS gaming revenue, a share that has expanded thanks to higher player engagement and diversified monetization streams
Report32 pages
Mar 2026
Podcast: Understanding Unity’s Vector
Mobile Dev Memo
leveraging high-fidelity, sequential runtime data, Unity aims to improve predictive modeling for mobile game advertisers, effectively addressing challenges related to data fragmentation, causality, and the extreme class
Article1 pages
Apr 2025
Global Top Mobile Games: February 2025
SocialPeta
February 2025 global mobile game landscape shows a pronounced resurgence of IP‑driven titles, with the Ragnarok franchise launching three new games that all entered
Article1 pages
Jan 2021
Newzoo Trends to Watch 2021
Newzoo
sector, mobile titles like PUBG Mobile and Garena Free Fire are now challenging traditional PC giants in viewership, signaling a shift toward mobile-first competitive gaming. Methodologically
Report23 pages
Mar 2023
Gametech Report: Global & MENAP Outlook Q1 2023
Shorooq Partners
spotlighting the rapid evolution of the MENAP (Middle East, North Africa, and Pakistan) mobile‑gaming sector. Globally, the market is valued at roughly $201 billion, expanding 9 percent
Financial98 pages
Global White Paper on Mobile Advertising & Marketing Game H1 2022
Jan 2022191 pages39k words
Summary
The first half of 2022 saw a contraction across the mobile‑app advertising ecosystem, with the total number of advertisers falling 5.79 % to a historic low of roughly 83 400 and creative volume dropping 27 % to 40 million assets. This downward pressure was most pronounced among mobile‑game advertisers, whose pool shrank to about 83 000 in January, while non‑game categories such as shopping apps retained the largest share of spend (≈12.5 % of advertisers and 17.2 % of creatives). Regional variation was stark: Europe and North America dominated non‑game advertising, whereas the Asia‑Pacific region, excluding China, was the only market with a net increase in advertisers.
Mobile‑game advertising displayed divergent cost dynamics. The United States and Japan posted the highest average CPMs at $27.54 and $25.93 respectively, with iOS campaigns costing roughly 15 % more than Android. Female users and the 55‑64 age cohort commanded a 13 % premium on impressions, while South Korea recorded the peak CPI at $13.90. Playable ads delivered the lowest CPI but suffered the weakest return on ad spend, whereas banner formats generated the strongest ROAS. Strategy titles leaned heavily on video‑only creatives (>90 %) and began integrating casual‑puzzle mechanics to broaden appeal; interest in emerging formats remained modest, with only 16 % of players expressing curiosity about NFTs and 32 % about metaverse features.
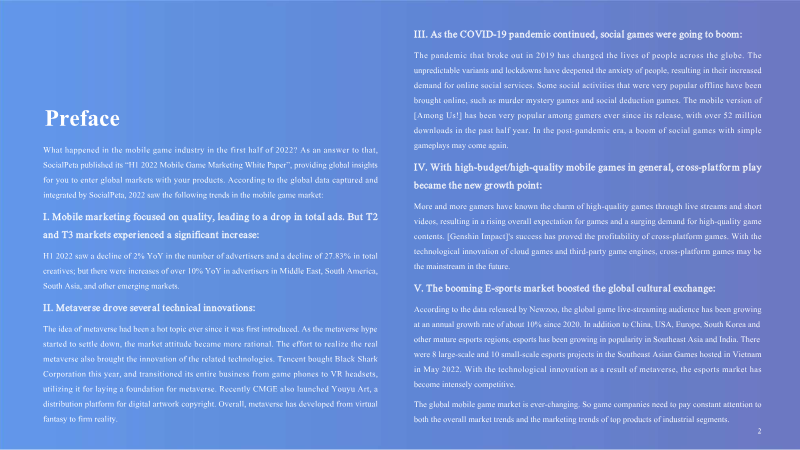
Creative strategies are shifting toward motivation‑driven, user‑centric formats such as rewarded video and playable ads to counter post‑IDFA fragmentation. Narrative‑driven ads are proving effective for simulation games targeting female audiences, delivering $12 million in revenue across key Western markets. AR‑enhanced placements on platforms like Snapchat achieve double the attention and 1.7 × the immersion of standard formats, while friend‑based recommendations outperform celebrity influencers by a factor of four. Regional opportunities are emerging in Tier‑2/3 India through vernacular campaigns and OEM inventory, and Turkey’s
Pages
Insights
- The mobile advertising ecosystem contracted in H1 2022, with the total number of advertisers falling 5.79% to approximately 83,400 and creative volume dropping 27% to 40 million assets.
- Mobile-game advertising costs remain high in key markets, with the U.S. and Japan recording average CPMs of $27.54 and $25.93, while iOS campaigns command a 15% price premium over Android.
- While playable ads offer the lowest cost-per-install (CPI), banner formats currently generate the strongest return on ad spend (ROAS).
- Audience targeting premiums are significant, with impressions for female users and the 55–64 age demographic costing 13% more than other segments.
- Consumer interest in emerging tech remains low, with only 16% of players expressing curiosity about NFTs and 32% about metaverse features.
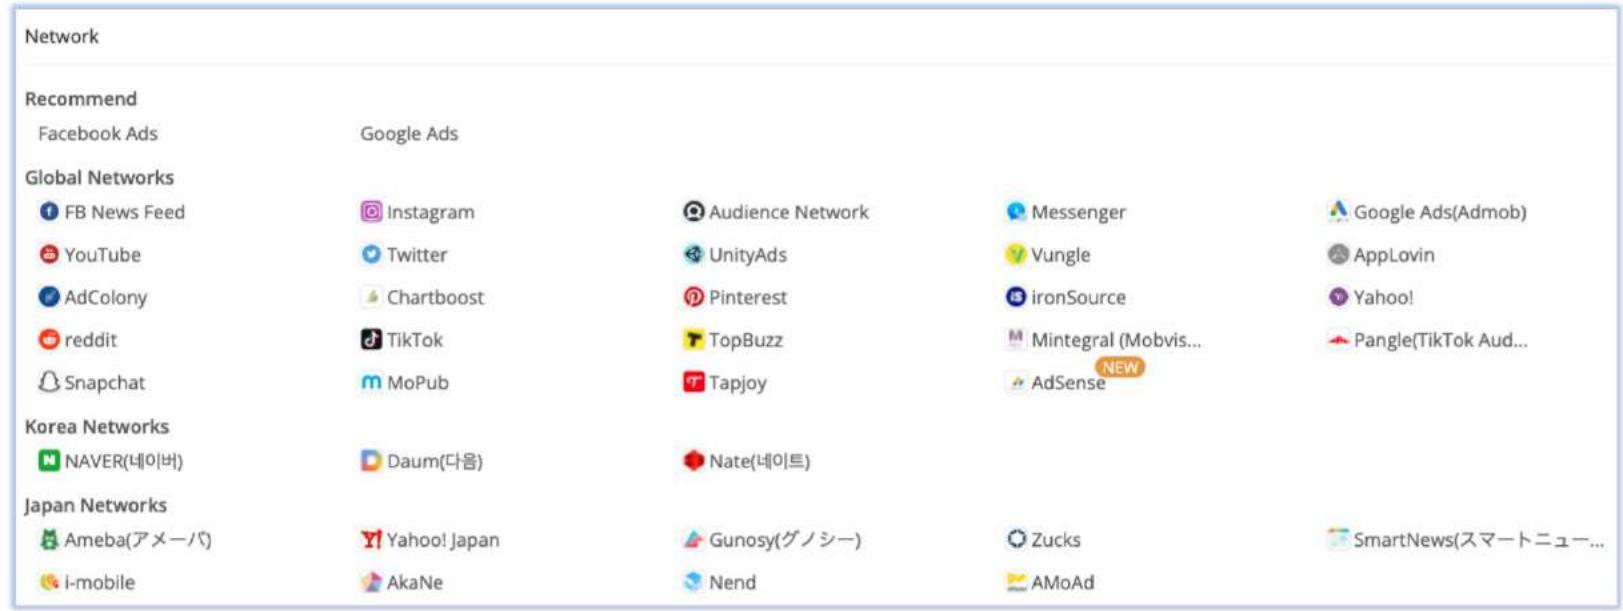
This image from a game industry report displays a comprehensive list of advertising networks, categorized by "Recommend," "Global Networks," "Korea Networks," and "Japan Networks." It provides an overview of various platforms available for game developers to advertise their products, including major global players like Facebook Ads, Google Ads, YouTube, and TikTok, as well as region-specific networks such as Naver and Ameba.