Showing 25 of 85 results · 0.28s
Jan 2023
Gaming Spotlight 2023 Review
data.ai
concentrated among high-performing titles that leveraged Gen Z engagement and sophisticated in-app purchase models. Monopoly GO and Honkai: Star Rail emerged as standout performers, generating hundreds
Report33 pages
Jun 2024
Q2’24 Gaming Deals Report
InvestGame
mobile gaming hits, with titles like Dungeon & Fighter: Origin generating significant in-app purchase revenue. On PC and console platforms, Steam full-game sales grew 27% year-over
Report19 pages
Mar 2024
AI Apps Market Insights 2024
Sensor Tower
months of 2024 and projected to hit 3.3 billion by year-end. In-app purchase revenue is expected to grow 51% year-over-year to $3.3 billion. While
Report31 pages
Jun 2026
Vietnam Game Industry Monthly Report: May 2026
Gamota
underscoring a reliance on consistent launch pipelines and recognizable themes. Conversely, total in-app purchase (IAP) revenue grew by 3.13% month-over-month, with midcore revenue rising
Report23 pages
Jan 2020
From Playing to Paying: The Art of Monetizing Games in Asia
Niko Partners
modeling. The conclusions suggest that developers must move toward hybrid monetization—blending in-app purchases with rewarded ads—to mitigate economic risks and appeal to diverse player segments
Report15 pages
Jan 2024
Levelling Up: State of India Interactive Media and Gaming Research FY24
Lumikai
toward midcore gaming, which experienced a 53% year-on-year revenue increase. In-app purchases remain the primary growth driver, with the average revenue per paying user rising
Report15 pages
May 2025
2025 GDC Trends Report: Connecting the World Through Games
Game Developers Conference
game ad market to $100 billion in 2024, officially surpassing in-app purchase revenue. Simultaneously, the industry is embracing social responsibility through the Accessible Games Initiative, which introduces
Report37 pages
May 2026
Digital Market Index: Q1 2026
Sensor Tower
mobile gaming toward generative artificial intelligence and short-form entertainment. While global in-app purchase revenue climbed 9.3% to $43.5 billion, this growth was primarily fueled
Report57 pages
May 2021
Match3 Genre Snapshot: US iOS (May 2021)
GameRefinery
Data indicates that recurring live events, special event rewards, and limited-time in-app purchase offers have the highest impact on revenue. Furthermore, social features such as guild
Report20 pages
Jan 2025
Gaming CEO Survey: 2024 in Review
Aream & Co
strongest in the mobile sector, where 41% of leaders anticipate expansion in in-app purchases and 31% expect growth in advertising revenue. While the PC segment remains relatively
Report13 pages
Jan 2021
Mobile Game Genre Report: Comparing & Contrasting Eastern and Western Markets 2021
Newzoo
revenue model. Conversely, Japanese players exhibit a greater willingness to engage in in-app purchases, resulting in a more balanced or IAP-heavy approach. Live-ops, including limited
Report25 pages
Jan 2024
Mobile Gaming Spender Report: Decoding Today’s Mobile IAP Spenders to Understand Motivations, Engagement
Mistplay
Mistplay examines the evolving motivations, behaviors, and shifting financial priorities of mobile in-app purchase (IAP) spenders. The analysis is based on a survey of approximately
Report33 pages
Jan 2021
Match3 Genre Snapshot Report May 2021 (2021)
GameRefinery
Data indicates that recurring live events, special event rewards, and limited-time in-app purchase offers have the highest impact on revenue. Social features, including guild mechanics
Report20 pages
May 2022
Gaming Spotlight: 2022 Review
International Data Corporation
toward hybrid models, with 42% of top-grossing U.S. games now combining in-app purchases with advertising. Although global audiences generally accept advertisements in exchange for free content
Report32 pages
Jan 2019
Mobile Benchmarks Report GameAnalytics
GameAnalytics
reflects a significant structural shift as developers increasingly pivot from in-app purchases toward ad-based monetization models. Analysis of 100,000 titles and 1.2 billion monthly active
Report34 pages
Jan 2023
Gaming Report 2023
Unity
player behavior, moving toward a balanced model where ad-supported structures and in-app purchases hold nearly equal weight. To ensure financial viability, 70% of studios now integrate
Report57 pages
Jan 2024
Casual Gaming Apps Report 2024
GameRefinery
traditional advertising. The rise of "progressive offers" and "engagement offers" has transformed in-app purchases by tying discounts and rewards directly to active gameplay milestones. Furthermore, the industry
Report40 pages
Jan 2024
Mobile Growth and Monetization Report 2024
Unity
value retention and diversified monetization. While only 1.83% of users convert to in-app purchases, nearly 29% of those individuals become repeat buyers, with the vast majority
Report48 pages
Jan 2023
Mobile Growth & Monetization Report 2023
Unity
reflects a strategic pivot toward operational efficiency as developers navigate softening in-app purchase (IAP) and advertising revenues. Success currently hinges on capturing player interest within the first
Report41 pages
Jan 2023
Gaming Spotlight 2023: The Year in Review
data.ai
leveraged strong intellectual property and sophisticated monetization strategies, such as high-value in-app purchases and social engagement features. A significant portion of the analysis examines user acquisition
Report33 pages
Jan 2021
Games Marketing Insights for 2021
King
analysis recommends a mixed monetization model that balances ad-supported content with in-app purchases to capture diverse spending habits. It concludes that developers must embrace "always
Report24 pages
Jan 2026
Gaming Deep Dive: Ad Monetization 2026
Sensor Tower
profitability. Instead, top-tier publishers are shifting toward hybrid strategies that integrate in-app purchases with ad monetization. This approach allows developers to capture value from non-spending
Report39 pages
Adjust Guide to Deep Linking
Adjust
data and support within major apps like Facebook. Key data points emphasize the commercial impact of native app environments, noting that consumers purchase at three times the rate
Report17 pages
Jan 2025
Mobile App Trends Spotlight Edition: Türkiye 2025
Adjust
The mobile application economy in Türkiye is entering a high-growth, maturing phase, with total
Report22 pages
Jan 2020
2020 Mobile Gaming Apps Report
Liftoff
in-app payments. While the average cost per install has reached a record low of $1.47, the industry faces a tightening conversion landscape where install-to-purchase costs
Report64 pages
Gaming Spotlight 2023 Review
Jan 202333 pages7k words
Summary
The global gaming market in 2023 was defined by a complex interplay between mobile contraction and steady growth in the PC and console sectors. While mobile remains the industry’s largest segment, consumer spending fell 2% to $108 billion, a decline attributed to macroeconomic instability and privacy-related shifts such as Apple’s App Tracking Transparency framework. Conversely, the PC and home console markets expanded by 4% and 3% respectively, bolstered by the rising popularity of subscription services. Handheld gaming also experienced a demographic fragmentation, with the Nintendo Switch Lite attracting a younger, female-leaning audience while the Steam Deck appealed to older, male gamers. Emerging technologies like cloud-streamed gaming are gaining significant traction, projected to reach $3.8 billion in revenue with mobile devices facilitating over a quarter of global streaming hours.
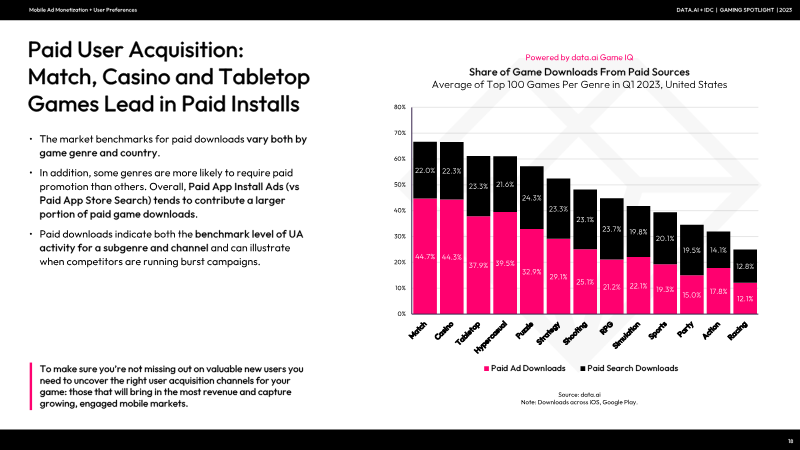
Success in the first half of 2023 was concentrated among high-performing titles that leveraged Gen Z engagement and sophisticated in-app purchase models. Monopoly GO and Honkai: Star Rail emerged as standout performers, generating hundreds of millions in revenue within their first months of release. Established franchises like Royal Match and FIFA Soccer also reached significant lifetime milestones, surpassing $1.7 billion and $1 billion respectively. These successes occurred despite a challenging user acquisition landscape where gamer sentiment toward traditional advertising formats has turned increasingly negative. While rewarded video and playable ads remain the most tolerated formats, overall ad fatigue is rising due to market oversaturation.
To navigate this evolving environment, the industry must adapt to shifting privacy standards and the impending implementation of Google’s Privacy Sandbox. Although data suggests that privacy frameworks have not directly damaged iOS ad sentiment, the general decline in ad acceptance necessitates a move toward more diverse formats and contextual market data. Strategic focus is shifting toward combating rising acquisition costs through high-value player engagement and the optimization of cross-platform experiences. As the market stabilizes, the integration of cloud services and the continued dominance of mobile-first economies in emerging regions will likely dictate the next phase of global industry growth.
Pages
Insights
- The global mobile gaming market contracted by 2% to $108 billion in 2023, driven by macroeconomic instability and privacy-related shifts like Apple’s App Tracking Transparency.
- PC and home console markets grew by 4% and 3% respectively, largely supported by the increasing adoption of subscription-based models.
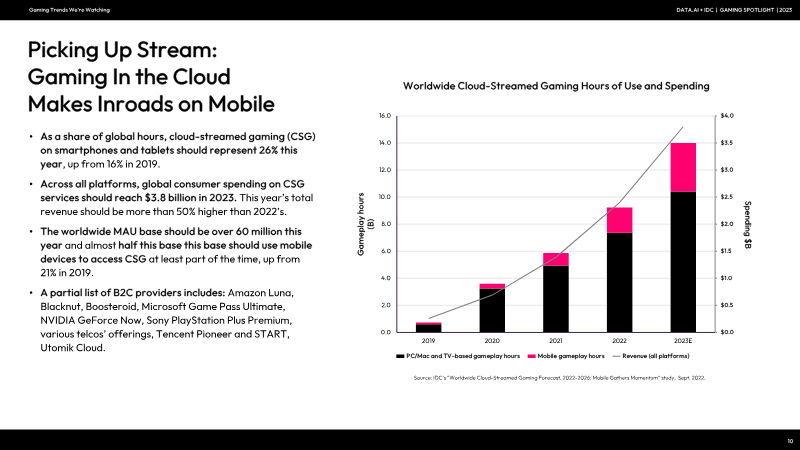
- Cloud-streamed gaming is a growing revenue stream projected to reach $3.8 billion, with mobile devices accounting for over 25% of total streaming hours.
- High-performing titles like Monopoly GO and Honkai: Star Rail achieved rapid, massive revenue success by targeting Gen Z and utilizing sophisticated in-app purchase models.
- Rising ad fatigue and negative sentiment toward traditional advertising are forcing developers to move away from standard formats toward rewarded video, playable ads, and contextual market data.
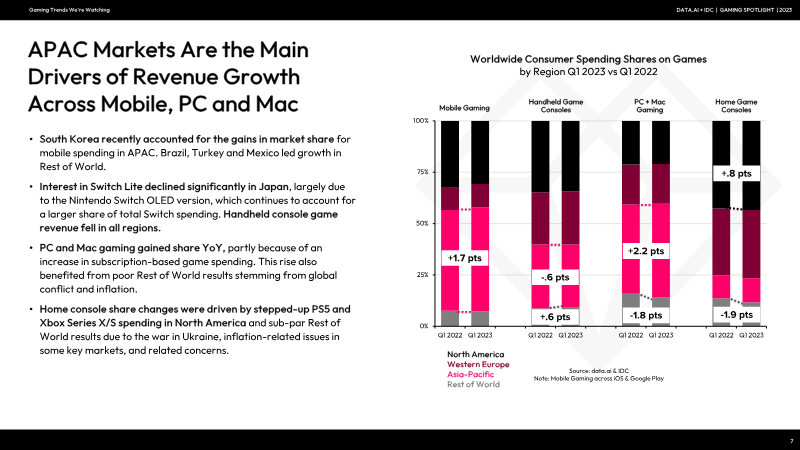
The image displays a bar graph and a pie chart. The bar graph shows the global mobile gaming market share by region from 2020 to 2022. The pie chart shows the percentage of mobile gaming revenue generated by each region in 2020 and 2022. The bar graph is divided into three sections, with the first section showing the market share of mobile gaming in North America, the second section showing the market share of mobile gaming in Western Europe, and the third section showing the market share of mob
Showing 61 – 85 of 85