Reports matching your filters
The report examines U.S. mobile game advertising in 2021, focusing on ad network share of voice (SOV), creative formats, genre‑specific trends, and demographic alignment. Five gaming‑centric networks—Chartboost, Unity, Adcolony, ironSource, and Vungle—dominated game advertising, each maintaining over 90 % SOV from games on iOS and Android. In contrast, mainstream social platforms (Facebook, Instagram, TikTok, YouTube) displayed a more balanced mix of gaming and non‑gaming ads, with SOV from games ranging 40–60 %. AppLovin and MoPub shifted toward gaming in late‑2018, investing heavily in hypercasual publishers; this pivot increased their game SOV to roughly 90 % on iOS and 80 % on Android by early‑2021. AdMob’s focus on Google Play titles grew, with its game SOV rising from 60 % to 80 % by Q2 2021.
Creative analysis shows video ads remain the dominant format across networks, accounting for >50 % of game ad spend on iOS and Android. Playable ads gained traction among hypercasual publishers (e.g., AppLovin) and, more recently, mid‑core titles such as Call of Duty: Mobile and State of Survival. Full‑screen ads were more common on Android, especially for Google Play games.
Genre‑level insights reveal puzzle and hypercasual games rely heavily on gaming‑focused networks (Chartboost, Unity), while mid‑core and strategy titles favor broader platforms like Facebook and YouTube. Casino games concentrated on Adcolony, which also hosts many real‑money reward creatives.
The study concludes that despite IDFA changes, game advertising volumes remained stable into 2021. Publishers can optimize spend by matching network demographics to target audiences—YouTube for younger, male strategy players; Adcolony for older, female casino gamers—and by adopting emerging creative trends such as simple playable ads and background music to differentiate in a crowded market.
CyberAgent achieved record-high consolidated sales of 131 billion yen during the first quarter of fiscal year 2021, representing a 13.3% year-over-year increase. This growth was primarily propelled by the Media and Advertising segments, offsetting a temporary downturn in the Game business. While the Game segment saw revenue decline 15% to 29.9 billion yen and operating profit drop 77.8% due to seasonal factors and elevated marketing expenditures, the company maintained a strong financial foundation with 252 billion yen in total assets. This performance establishes a solid trajectory toward meeting full-year targets despite the mixed results across different business units.
The Media segment emerged as a significant growth engine, with ABEMA driving a 67% surge in revenue to 20.4 billion yen. This expansion was supported by a premium subscriber base exceeding 921,000 users and an elevenfold increase in transaction volume for the WINTICKET platform. To capitalize on this momentum, the company restructured ABEMA into distinct Free and Premium business units. Simultaneously, the Game business prepared for a recovery through the high-profile launches of titles such as Uma Musume Pretty Derby and NieR Re[in]carnation, signaling a strategic focus on high-quality content to stabilize future earnings.
Corporate strategy remains centered on governance and technological adaptation within the Japanese market. The organizational structure utilizes a clear distinction between supervision and execution, supported by a board of eight directors that includes significant outside representation. By emphasizing environmental data disclosure and the integration of artificial intelligence within advertising and media functionality, the company aims to align with modern ESG standards. These initiatives, framed within the context of the New Normal, reflect a commitment to long-term sustainability and operational agility in a rapidly evolving digital landscape.
The global mobile marketing landscape experienced a massive surge in activity during the first half of 2021, characterized by a 108% year-on-year increase in advertising creatives totaling over 19 million. This growth was primarily driven by hard-core gaming titles and a significant expansion in the non-game sector, where creatives rose 38% to 47.6 million. Despite this volume increase, Apple’s IDFA policy changes caused a 13% decline in the share of iOS creatives, shifting more focus toward Android platforms. Geographically, the United States remained the largest advertising market, while Oceania emerged as the fastest-growing region for non-game advertisers.
Chinese companies solidified their global dominance during this period, accounting for 70% of top-charting mobile game media buying and over 25% of the total global market share. These developers maintained a particularly strong presence on major social platforms, representing 100% of the top ten advertisers on Facebook’s News Feed. However, this increased competition contributed to a sharp rise in acquisition costs, with Facebook’s average CPC and CPM both climbing 128% year-over-year. RPG and Puzzle genres led in total creative volume, while Strategy games exhibited the highest media buying intensity per advertiser.
Marketing strategies have evolved toward high-engagement, "snackable" short-form video content and influencer-led campaigns to combat rising costs and privacy-related tracking challenges. In the gaming sector, creative tactics shifted toward live-action footage and gameplay extensions, while non-game apps—particularly in the education and shopping sectors—capitalized on pandemic-related lifestyle shifts. As the industry navigates the post-IDFA era, the integration of high-quality in-game ads and diverse creative formats has become essential for maintaining user retention and driving monetization across both domestic Chinese and international markets.
The analysis quantifies how Apple’s post‑IDFA privacy updates have reshaped user‑acquisition economics for mobile games, contrasting casual titles with core experiences. By aggregating 13.5 billion programmatic ad impressions from iOS and Android between January 1 2021 and September 30 2021, the study tracks cost‑per‑install (CPI) trends across three intervals—pre‑iOS 14.5, during the iOS 14.5‑14.6 rollout, and post‑iOS 14.6—using Moloco’s proprietary game taxonomy to separate titles into casual and core categories.
Casual games experienced a sharp decline in iOS CPI, falling 38 % after the iOS 14.6 release, while Android CPI for the same segment rose modestly by 16 %. In contrast, core games saw iOS CPI surge 78 % and Android CPI increase 36 % over the same period, reflecting intensified competition for a shrinking pool of high‑value, trackable users. The narrowing of the historical iOS‑Android CPI gap for casual titles indicates that Android installs now command comparable monetary value, whereas iOS remains the premium channel for core audiences due to higher in‑app‑purchase conversion rates.
Methodologically, the research averages weekly CPI data across the defined date ranges, applying a taxonomy that classifies games by genre and engagement depth, with subcategories overlapping between casual and core groups. Findings suggest that the divergent CPI trajectories are driven by user churn characteristics and lifetime‑value differentials rather than seasonal factors.
Strategic recommendations emphasize diversifying media spend, allocating budget to campaigns optimized for return‑on‑ad‑spend, and leveraging machine‑learning‑based bidding to mitigate volatility. These practices aim to preserve profitability amid the evolving privacy‑driven market dynamics for both casual and core mobile game publishers.
Mobile game advertising in the United States remained resilient through the first half of 2021, showing no immediate negative impact from privacy changes such as the deprecation of IDFA. Analysis of the advertising landscape reveals a strategic divide between ad networks. Specialized platforms like AppLovin, Chartboost, and Vungle maintain a high concentration of gaming content, often exceeding 90 percent share of voice. In contrast, diversified platforms like Facebook, TikTok, and YouTube maintain a more balanced split between gaming and non-gaming advertisements, serving as critical channels for reaching broader audiences.
Market trends indicate that ad network selection is increasingly driven by genre and demographic alignment. Puzzle and Hypercasual games dominate gaming-focused networks, while mid-core genres like Strategy and Shooter find higher engagement on social platforms like YouTube and Instagram. Notably, Adcolony emerged as a primary hub for Casino games, catering to an older, female-leaning demographic. Across most platforms, video remains the dominant creative format, though playable ads have gained significant traction, particularly on AppLovin where they account for over 40 percent of gaming share of voice.
Creative strategies are evolving to include "fake playables," relaxing music for casual titles, and real-world testimonial-style conversations. Even mid-core titles with complex mechanics, such as Call of Duty: Mobile, have begun adopting simplified playable "mini-games" to lower the barrier for user acquisition. This data, compiled by Sensor Tower using its Ad Intelligence platform, covers U.S. trends across iOS and Android from 2018 through the second quarter of 2021, suggesting that success in the current market requires a sophisticated mix of genre-specific network targeting and experimental creative formats.
CyberAgent achieved record-high financial performance in fiscal year 2020, reporting consolidated sales of 478.5 billion yen and an operating profit of 33.8 billion yen. These results represent year-over-year increases of 5.5% and 9.9% respectively, surpassing initial forecasts despite the operational challenges posed by the global pandemic. Growth was primarily catalyzed by the Game business, which generated 155.8 billion yen in sales. This segment benefited from the sustained performance of legacy titles and the successful launch of Project SEKAI, which acquired over two million users within its first three weeks.
The Media business, centered on the ABEMA streaming platform, remains a critical pillar for long-term expansion. ABEMA experienced a 22.6% increase in annual sales to 57 billion yen, supported by a cumulative download base exceeding 59 million. While the segment continues to operate at a loss of 18.5 billion yen due to aggressive up-front investments, these losses are narrowing as new monetization streams mature. Specifically, the rapid adoption of Pay-Per-View services and a seventeen-fold increase in transaction volume for the WINTICKET cycling betting service have diversified the platform's revenue model beyond traditional advertising.
Looking toward fiscal year 2021, the strategic focus shifts toward scaling consolidated sales to 500 billion yen while maintaining a robust financial position. To manage this growth, a new governance structure has been implemented to separate management oversight from execution. Although increased selling, general, and administrative expenses led to a quarterly dip in operating profit during the final months of 2020, the overall trajectory remains positive. The combination of a highly profitable gaming portfolio and the accelerating monetization of digital media assets positions the organization for sustained domestic leadership in the Japanese internet services market.
CyberAgent’s performance during the third quarter of fiscal year 2020 remained resilient despite the economic disruptions caused by the COVID-19 pandemic. Consolidated sales reached 112.8 billion yen, a marginal year-over-year decrease of 0.7%, while operating profit stood at 8.2 billion yen. By the end of this period, the company had already achieved between 89% and 102% of its full-year operating profit forecasts. This stability was largely driven by the Internet Advertisement segment, which successfully offset declining demand in certain sectors by pivoting toward advertisers benefiting from stay-at-home trends, and the Game business, which generated 36.7 billion yen in quarterly revenue following major title anniversaries.
The media segment, centered on the streaming platform ABEMA, demonstrated significant growth with a 19.2% year-over-year increase in sales to 13.3 billion yen. This expansion was supported by a record 56 million downloads and a surge in the WINTICKET gambling transaction business, which doubled its volume to 7.2 billion yen. Strategic priorities for this segment include reaching one million ABEMA Premium subscribers by late 2020 and leveraging new virtual production technologies, such as Pay-Per-View systems, to enhance monetization.
Looking forward, the corporate strategy focuses on establishing ABEMA as a long-term financial pillar while maintaining market share in the advertising sector through AI-driven efficiency. In the gaming division, the emphasis remains on the dual approach of developing new intellectual properties and extending the lifecycle of existing titles through robust operational management. These efforts are underpinned by a broader commitment to ESG initiatives and information security, ensuring sustainable value creation across the company’s diverse digital portfolio.
CyberAgent achieved record-high financial performance during the second quarter of fiscal year 2020, with consolidated sales reaching 129.1 billion yen and operating profit surging 45.3% year-over-year to 12.4 billion yen. This growth was primarily anchored by the Game Business, which generated 44.8 billion yen in revenue. Success in this segment was driven by high-profile anniversary events for established titles like Granblue Fantasy and the strong market debut of KonoSuba: Fantastic Days. By the end of the first half, the company had already secured between 63% and 72% of its full-year profit targets, though projections for the remainder of the year remain cautious due to anticipated declines in advertising demand stemming from the COVID-19 pandemic.
The media segment, centered on the ABEMA streaming platform, demonstrated significant momentum as stay-at-home orders accelerated user adoption. ABEMA reached 52 million downloads and grew its premium subscriber base to 676,000, with a clear trajectory toward one million subscribers by the end of the calendar year. While the segment still operates at a loss, these losses narrowed to 4.2 billion yen as sales rose nearly 19%. Monetization efforts are diversifying beyond traditional advertising into subscriptions and related services, such as the WinTicket betting platform, which saw transaction volumes double quarter-on-quarter to 3.5 billion yen.
Strategic priorities for the future focus on balancing short-term gains with long-term operational stability. In the gaming sector, the emphasis remains on high-quality development and extending the lifecycle of existing intellectual properties. Simultaneously, the media division is pivoting toward a multi-faceted revenue model to ensure the sustainability of its expanding digital ecosystem. Despite the broader economic uncertainty introduced by global health trends, the current fiscal trajectory suggests a robust foundation built on digital entertainment and diversified media services.
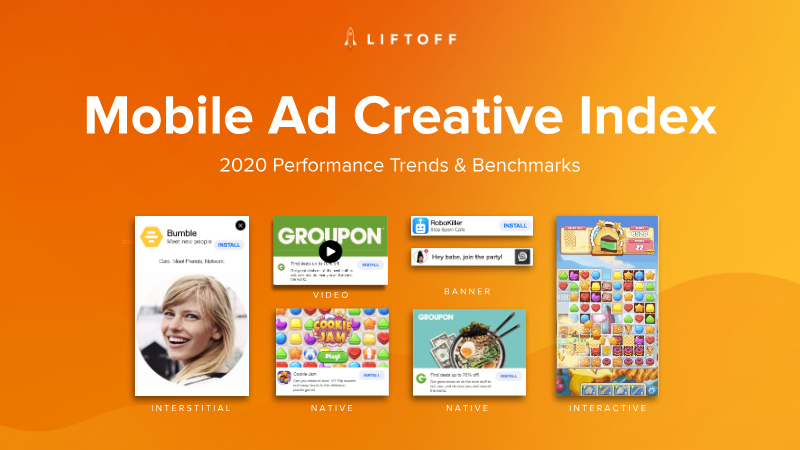
The 2020 mobile advertising landscape is defined by a stark divergence in performance metrics across creative formats, operating systems, and geographic regions. While banner ads remain the most cost-effective entry point for driving initial installs, native and video formats demonstrate superior efficacy in securing high-value, deep-funnel actions such as in-app purchases. Native ads, in particular, achieve conversion rates as high as 52.8%, signaling their importance for long-term user retention. However, these performance gains come at a premium on iOS, where costs consistently dwarf those on Android. For instance, the cost of securing an in-app purchase through native ads on iOS reaches $218.09, nearly triple the $73.62 required on Android.
Geographically, North America persists as the most expensive market for user acquisition across all formats, while the LATAM and APAC regions offer significantly more accessible pricing for advertisers. Seasonal trends also influence these costs, with install expenses typically peaking during the summer months. To navigate these fluctuations, successful campaigns increasingly rely on iterative A/B testing and dynamic creative strategies. Case studies from major brands like Credit Karma and Groupon illustrate that disciplined testing can yield lifts in click-to-install rates exceeding 120%, underscoring the necessity of a data-driven approach to creative optimization.
The industry is shifting toward a performance-based, cost-per-action model that prioritizes post-install revenue events over simple downloads. By leveraging machine learning and focusing on single-deal creative strategies, advertisers can better align their spending with actual user value. Ultimately, the data suggests that while the cost of acquisition is rising, particularly on premium platforms and in mature markets, the integration of dynamic product ads and rigorous testing frameworks remains the most effective path toward achieving sustainable return on ad spend.
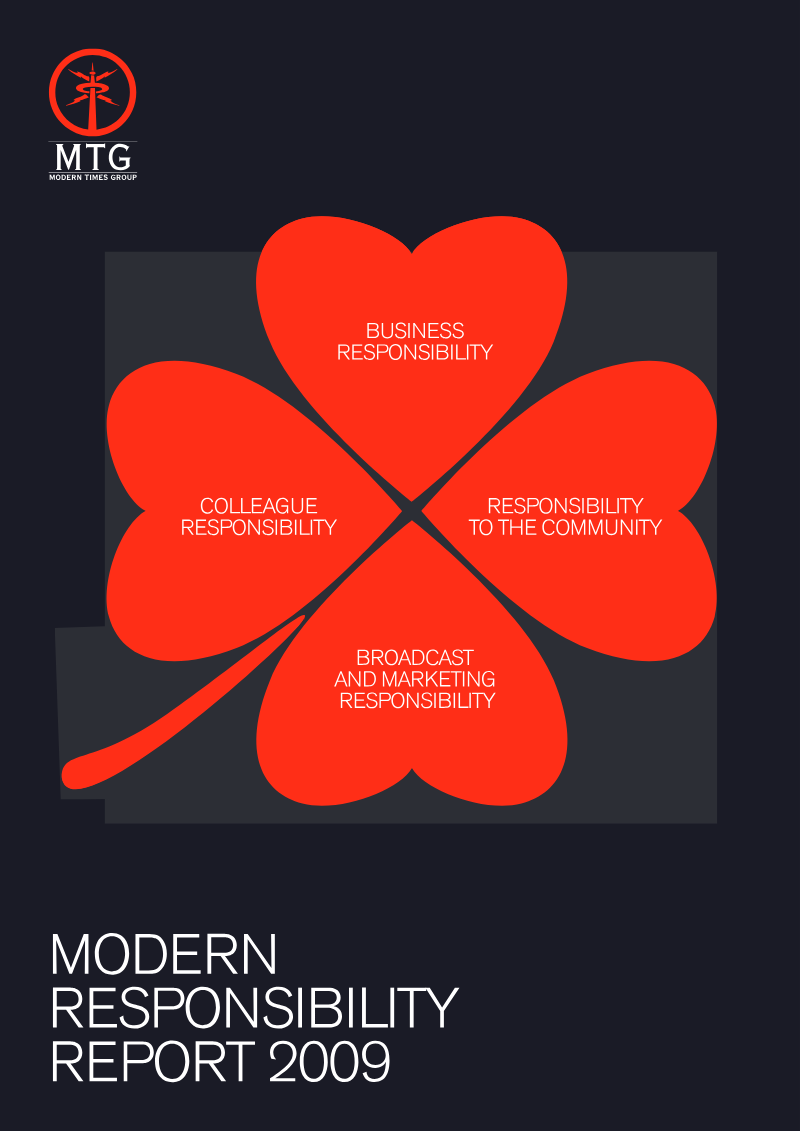
The 2009 Modern Responsibility Report presents Modern Times Group’s (MTG) effort to embed corporate responsibility across its broadcasting and media operations while navigating the aftermath of the 2008‑09 financial crisis. The report’s thesis is that a structured, multi‑pillar responsibility programme can coexist with commercial growth, even as the group expands its channel portfolio and geographic reach.
In 2009 MTG recorded net sales of SEK 14.2 billion and launched three new channels—TV3 Puls, Prima COOL and Viasat Hockey—while completing a major restructuring of its Bulgarian assets. Despite revenue growth, operating income fell to a loss of SEK 1.4 billion and basic earnings per share turned negative at ‑30.86 SEK. The responsibility framework, introduced in 2004, is now governed by the CEO, board directors, a central committee and local “Green Ambassadors,” with KPIs, internal audits and external consultancy guiding progress. Targets for 2010 include broader KPI coverage, reduced carbon emissions and enhanced stakeholder communication across business, broadcast‑marketing, colleague and community dimensions.
Employee engagement proved strong: 86 % of the 2,906 staff across 38 national markets completed the annual survey, 88 % expressed enthusiasm for their work and 90 % embraced the company’s three lead words. Gender balance approached parity overall (52 % male, 48 % female) though managerial levels remained skewed (63 % male, 37 % female). Internal recruitment accounted for 40 % of hires.
The carbon footprint for 2009 amounted to roughly 13 000 t CO₂e across 19 countries, split evenly between facilities and office‑supply material use, with an intensity of 4.2 t CO₂e per employee (0.9 t per MSEK turnover). ISO 14001 certification for the Swedish radio division and energy‑efficient headquarters illustrate concrete mitigation steps. Partnerships with WWF and Sweden’s BLICC, together with expanded carbon‑footprint audits, underscore MTG’s commitment to environmental stewardship within the