Key insights
6 slides
Market Context
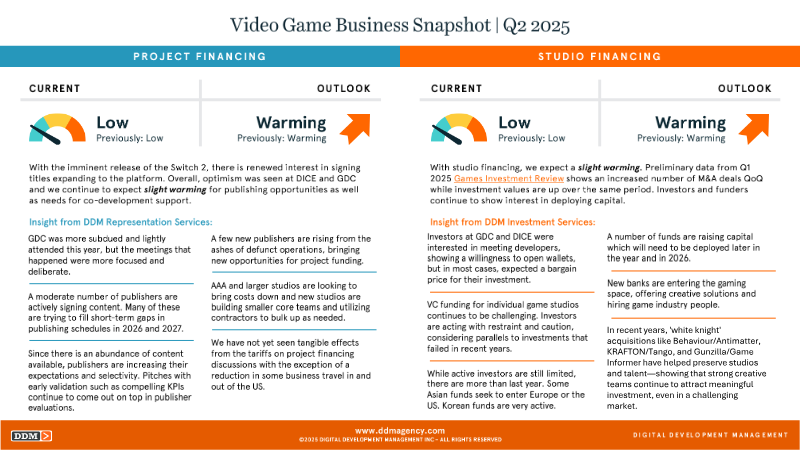
The global gaming industry transitioned to long-term growth and structural stabilization in 2024.
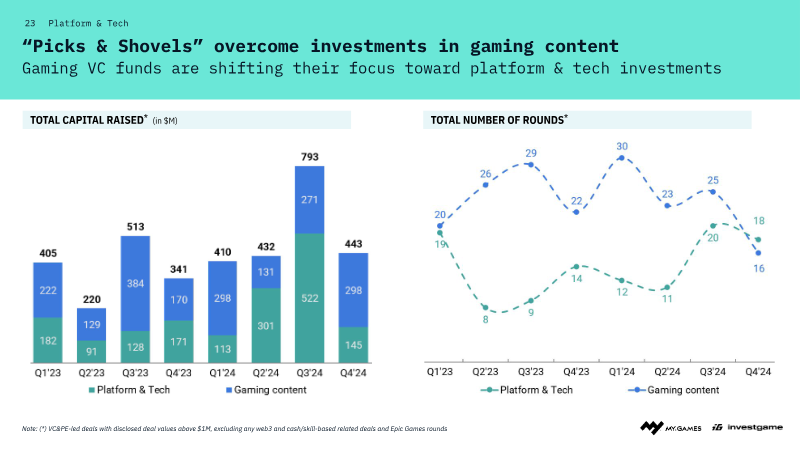
This shift reflects a broader recovery in late-stage venture capital and private equity. These investments increasingly prioritize platform-level technologies and infrastructure providers.
Investment Focus
Investment strategy has shifted from speculative studio acquisitions to platform-level technologies.
This new focus is on infrastructure providers that offer long-term scalability. Investors are moving away from speculative studio bets.
It's like investing in the tools to build houses rather than just buying individual houses.
Market Resilience
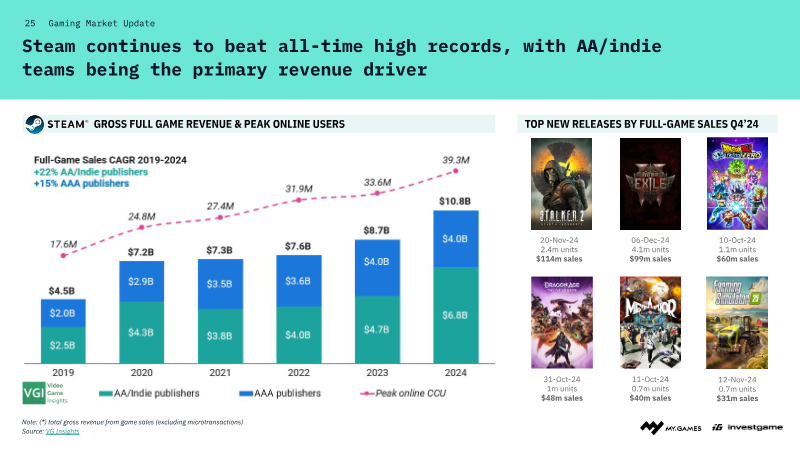
The 2024 market demonstrated resilience through steady performance in the consumer sector.
This was led by independent titles on Steam and mobile gaming initiatives from Asian developers.
Future Growth
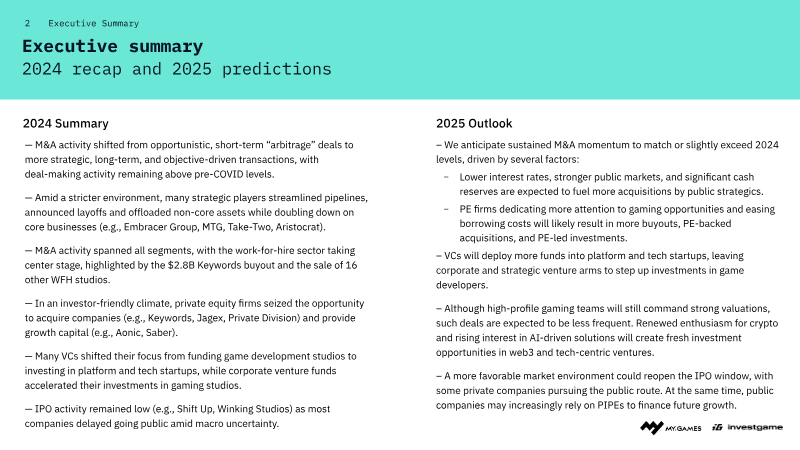
The 2025 outlook anticipates a resurgence in initial public offerings.
This is driven by expected macroeconomic improvements, including lower interest rates and stronger public market conditions. The industry is positioned for sustained momentum in mergers and acquisitions.
Innovation Focus
Capital allocation increasingly prioritizes high-utility innovation, specifically AI and web3 technologies.
Investors are seeking essential tools and frameworks for digital entertainment.
Investment Philosophy
The current industry trajectory emphasizes capital efficiency and sustainable growth models.
This follows the volatility of previous years. The focus is on the underlying infrastructure that supports the global gaming ecosystem.
1 / 6
Ask AI about this report