Key insights
6 slides
Market Performance
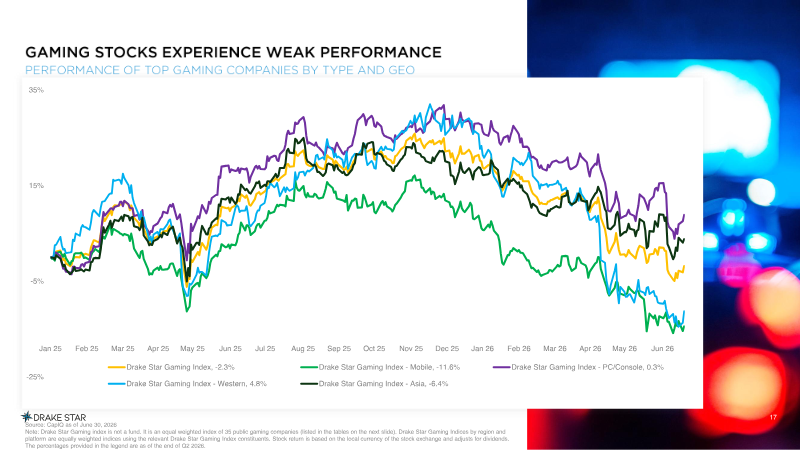
The Drake Star Gaming Index declined by 2.3% in Q2 2026.
This overall decline reflects broader equity market volatility impacting the gaming sector. The market experienced a period of financial divergence.
Overall Decline. The Drake Star Gaming Index recorded an overall decline of 2.3% during the quarter.
Sector Divergence
Western gaming stocks rose by 4.8%, while mobile gaming and Asian markets declined.
The gaming market showed significant divergence in Q2 2026. Western gaming stocks achieved gains, but other segments faced downturns.
Page 17 of the report4.8%
Gain in Western gaming stocks in Q2 2026.
- Decline in mobile gaming
- 11.6%
- Decline in Asian markets
- 6.4%
Private Financing
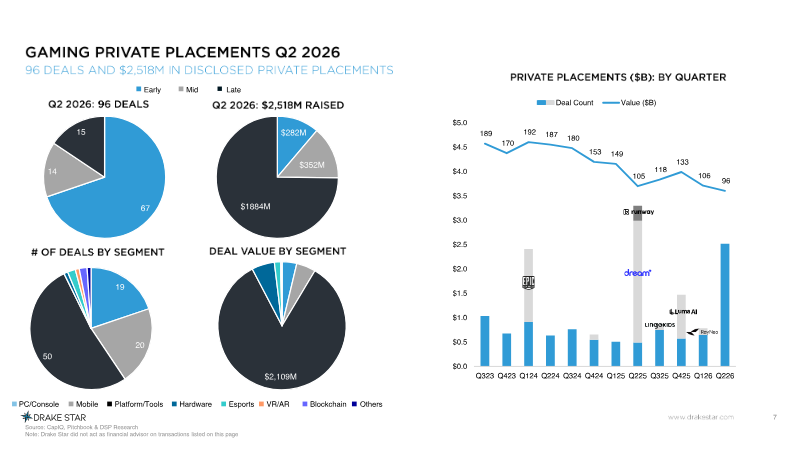
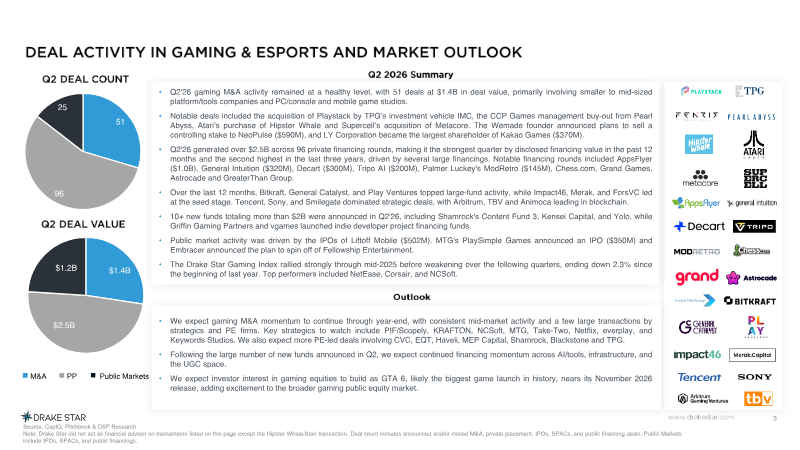
Private gaming financing reached a one-year high with over $2.5 billion in Q2 2026.
96 deals generated this capital, marking the highest level of private financing in the past year.
M&A Activity
M&A activity remained steady with 51 deals totaling $1.4 billion.
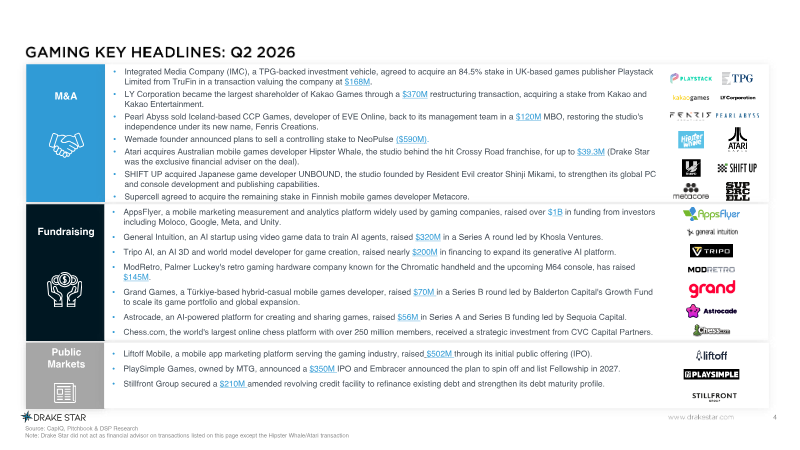
Strategic acquisitions by firms including TPG, Atari, and Supercell characterized this period.
Investment Focus
Investment is heavily concentrated in AI-driven infrastructure and tools.
Major funding rounds were secured by companies such as AppsFlyer, General Intuition, and Tripo AI.
Anticipated Catalyst
The late 2026 release of GTA 6 is expected to stabilize the market.
Analysts expect this release to act as a catalyst for market stabilization. It is also anticipated to drive continued momentum in M&A activity.
1 / 6
Ask AI about this report