Key insights
6 slides
M&A Activity
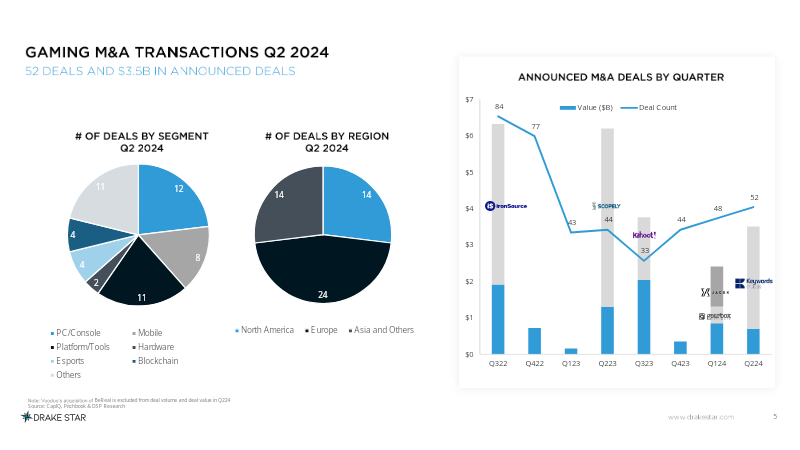
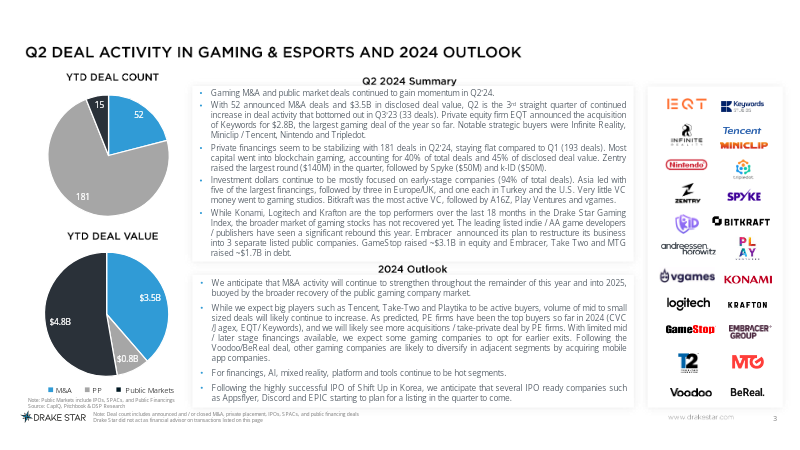
The gaming industry saw $3.5 billion in M&A activity across 52 deals in Q2 2024.
Strategic consolidation characterized the market.
Private Financing
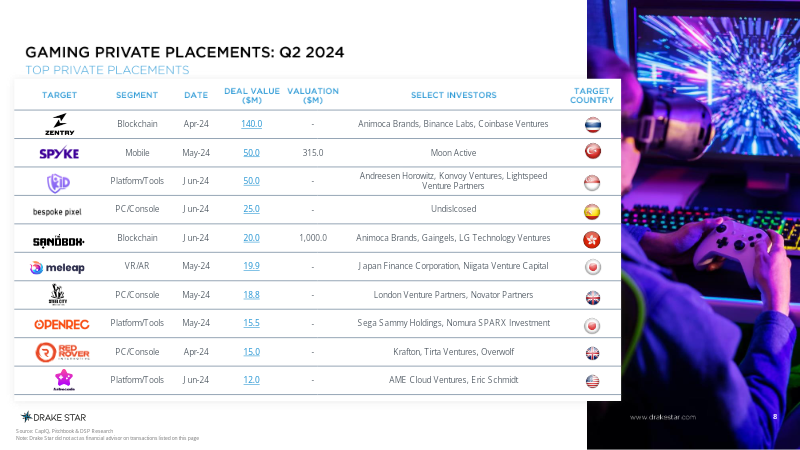
Private financing remained active with 181 transactions.
40% of these transactions were directed toward early-stage ventures and blockchain-integrated projects.
Bifurcated Performance
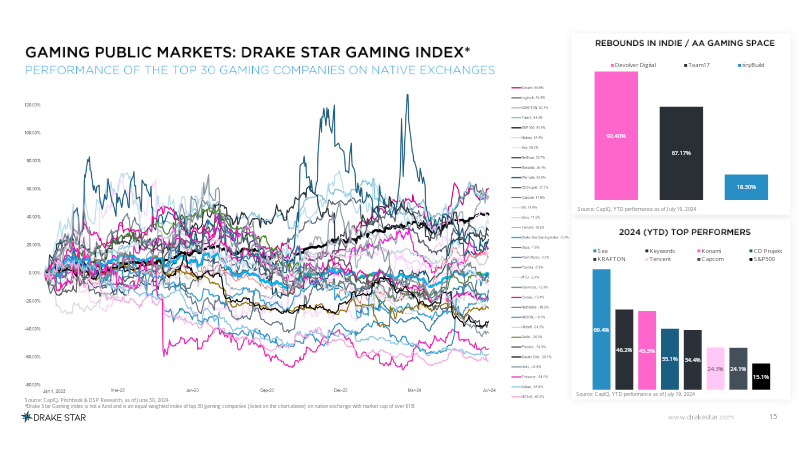
Market performance is bifurcated, with leaders achieving year-to-date gains exceeding 50%.
Major entities like Konami, Logitech, and KRAFTON saw significant gains. Many other firms, however, experienced double-digit valuation declines.
It's like a two-speed economy, where some companies are accelerating while others are slowing down.
Investor Priorities
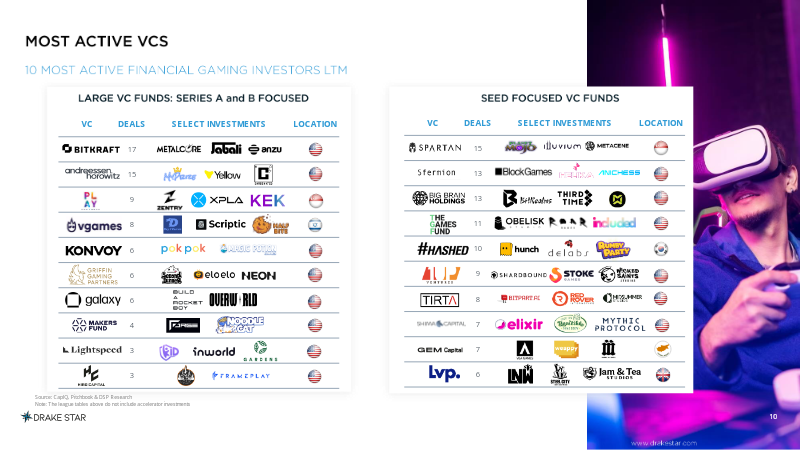
Investors are increasingly prioritizing developers with strong original intellectual property.
This allows select leaders to outperform the S&P 500.
Investor Focus. Investors are increasingly prioritizing developers with strong original intellectual property and proven operational resilience.
Future M&A
Continued M&A momentum is expected through 2025.
This will be driven by recovering public markets and increased private equity interest. The focus is on mobile, PC, and console sectors.
Consolidation Leaders
Strategic players like Tencent continue to lead market consolidation efforts.
Their focus remains on the long-term expansion of gaming ecosystems.
1 / 6
Ask AI about this report