Deconstructor of Fun
Media44 documents
Leading mobile gaming analysis publication by Michail Katkoff. Publishes weekly deep deconstructions of mobile games, market trends, and monetization analysis.
Documents
Article
Why the Best Founders Are Neither American nor European
The most effective founders in the gaming industry are those who synthesize American ambition with European operational grounding. While Silicon Valley culture emphasizes aggressive scaling and high-risk, high-reward financial projections, European business culture prioritizes technical craft, sustainable unit economics, and risk mitigation. Founders who successfully navigate both ecosystems—adopting the American "moonshot" mindset while maintaining European discipline—are uniquely positioned to build resilient, high-growth companies.
The gaming industry currently faces a significant gap between the adoption of AI tools and the realization of tangible financial returns. Many studios struggle because they treat AI as a top-down mandate rather than a workflow integration challenge. Successful implementation requires deep, granular knowledge of specific production pipelines rather than merely deploying generic AI wrappers. Contrary to common fears regarding workforce displacement, top-tier studios are primarily using AI to upskill existing teams and improve unit economics, rather than reducing headcount.
The analysis highlights that the most successful AI-driven studios are often incumbents who quietly build internal AI muscle, focusing on long-term workflow optimization rather than short-term hype. Because venture-backed companies are often pressured to prioritize rapid growth over sustainable fundamentals, founders who have experienced previous failures are better equipped to distinguish between productive speed and reckless expansion. Ultimately, the ability to balance the aggressive, growth-oriented expectations of American investors with the grounded, quality-focused approach typical of European engineering culture creates a competitive advantage that is difficult for rivals to replicate.
- Successful AI adoption in gaming studios requires deep integration into existing production workflows rather than simply purchasing tool licenses, as evidenced by top-grossing studios that invest weeks in workflow optimization rather than just buying software.
- The most effective AI founders combine American-style ambition—aiming for massive scale—with European-style grounding in unit economics and operational sustainability.
- Scenario, an AI content platform, has achieved profitability before a Series A round by maintaining near-zero customer churn and serving major studios including Scopely, Tripledot, Voodoo, Ubisoft, and InnoGames.
- The gaming industry faces a significant gap between AI tool investment and actual results, often because studios fail to rewire their internal production processes to accommodate new technology.
- AI models currently provide technical competence but lack the creative judgment required for art direction, meaning the role of the human creator remains essential for ensuring consistent creative vision.
+1
Deconstructor of Fun
Article
5 Numbers Hiding in Plain Sight: Sensor Tower's Ad Monetization Report
The analysis of Sensor Tower’s 2026 mobile gaming ad monetization report reveals that the industry’s $12 billion valuation for 2025 should be interpreted as a conservative floor rather than a total market size. By examining data across 19 countries and 2.4 trillion impressions, the findings suggest that ad revenue is a critical, often underestimated, pillar of the mobile economy. When restricted to the same 19 markets, advertising accounts for approximately 23% of net mobile game revenue, highlighting its role as a primary revenue engine rather than a secondary system.
A significant shift in the advertising landscape is the diversification of demand, as non-gaming advertisers now represent 30% to 50% of impressions across all genres. While these advertisers often pay lower CPMs than gaming-focused buyers, they provide essential incremental yield by clearing inventory that would otherwise remain unsold. Furthermore, the analysis challenges the traditional categorization of hybrid-monetization models. While IAP-first games currently generate higher revenue than IAA-first titles, the success of IAA-pure games—which rely almost exclusively on ad revenue—demonstrates that attention-based monetization remains a highly viable, high-scale business model.
The report emphasizes that studios often struggle when attempting to bolt store-based purchase economies onto ad-driven games, as these systems frequently cannibalize each other. The most effective strategy for future growth involves finding high-value conversion points that do not disrupt the existing ad loop. Ultimately, the data indicates that mobile game publishers should move away from rigid categorization and instead focus on optimizing their specific revenue mix, recognizing that ad monetization is a more robust and essential component of the global mobile gaming market than previously acknowledged.
- Mobile game ad revenue is significantly higher than public estimates suggest, with the $12 billion reported for 2025 serving as a conservative floor rather than a total market size.
- In-app advertising accounts for approximately 23% of net mobile game revenue within the measured markets, with ad revenue growing at 16% annually compared to 3% for in-app purchases.
- Non-gaming advertisers now represent 30% to 50% of ad impressions in mobile games, providing essential incremental yield by filling inventory that gaming competitors often ignore.
- IAP-first hybrid games currently generate roughly 4x the revenue of IAA-first hybrid games, though IAA-pure titles like Block Blast demonstrate that ad-only models can still achieve nine-figure annual revenues.
- The primary challenge for IAA-first hybrids is that store items often cannibalize rewarded video placements, as both frequently sell the same utility items like continues or boosters.
+2
Deconstructor of Fun
Article
How Toon Blast Became the Best Business in Puzzle
The mobile puzzle game Toon Blast has achieved a remarkable financial turnaround, demonstrating that mature titles can significantly increase revenue despite a shrinking user base. By shifting focus from user acquisition to monetization and live-ops optimization, the game successfully reversed a multi-year decline. Between 2023 and 2024, the title’s monthly revenue more than doubled, stabilizing above $35 million, while its ARPDAU (Average Revenue Per Daily Active User) surged from a historical range of $0.17–$0.38 to between $2 and $3.
The primary driver of this growth was the rapid integration of the "Super Light Ball" feature, a mechanic that doubles the effect of color-clearing items. By implementing this tool, the developers effectively increased difficulty headroom, leveraging loss aversion to encourage spending at critical gameplay moments. This technical adaptation was complemented by a comprehensive overhaul of the game’s live-ops calendar. The transition from short, isolated daily events to longer, overlapping, and compounding event structures created a more robust economy that incentivized sustained player engagement and recurring purchase opportunities.
The analysis highlights that Toon Blast’s success stems from its departure from traditional puzzle design. By stripping away complex meta-layers and prioritizing a high-luck, low-strategy core, the game functions more like a slot machine than a traditional puzzle, which facilitates higher monetization potential. The findings suggest that for established mobile games, the most effective path to growth is not through new user acquisition, but through the aggressive optimization of existing player value. This case study serves as a strategic model for studios managing legacy titles, proving that deep, data-driven live-ops can transform an aging asset into a high-performing business.
- Toon Blast achieved a massive turnaround by increasing its US ARPDAU from a range of $0.17–$0.38 to $2.00–$3.00, resulting in monthly revenue stabilizing above $35M in 2024 despite a 90% decline in downloads from its peak.
- The integration of the 'Super Light Ball' feature—a mechanic popularized by Royal Match that doubles the effect of special items—acted as a critical revenue driver by increasing difficulty headroom and leveraging loss aversion during out-of-moves prompts.
- The game’s live-ops strategy shifted from short, isolated daily events to longer, overlapping formats that compound player engagement and purchase opportunities, mirroring midcore progression systems.
- Toon Blast’s success demonstrates that legacy titles can be revitalized by treating an existing, committed install base as a primary asset rather than focusing solely on new user acquisition.
- The core design philosophy of Toon Blast succeeded by stripping away complex meta-layers and strategy, creating a 'slot-pull' experience that prioritizes gameplay simplicity and high-impact visual moments.
+4
Deconstructor of FunJul 2026
Article
The Most Honest AI Adoption Story in Gaming
The adoption of artificial intelligence at InnoGames serves as a pragmatic case study in operational efficiency rather than a narrative of creative transformation. The primary thesis posits that AI is most effectively deployed as a tool to manage the decline of plateaued titles, allowing studios to maintain profitability while reallocating human capital toward new projects with greater growth potential. By transitioning the maintenance of the game Sunrise Village from a 25-person team to a three-person operation, the studio successfully shifted the title from a loss-making position to profitability, while simultaneously redeploying 22 staff members to new development initiatives.
Key findings emphasize that successful AI integration requires identifying and automating unglamorous, repetitive data-shuffling tasks rather than focusing on creative output. The implementation relied on a stable, long-term use of established models like GPT-4o to ensure pipeline reliability, prioritizing consistency over the frequent adoption of newer, untested technologies. This approach highlights a critical trade-off: while AI enables significant cost and speed advantages, it introduces challenges such as increased cognitive fatigue for staff and the gradual erosion of specific technical skills.
The analysis concludes that the industry’s resistance to AI is largely a misunderstanding of the competitive landscape. Rather than a cultural conflict over authenticity, the adoption of AI represents a fundamental shift in the economics of game development. Studios that fail to integrate these tools risk being out-iterated by competitors who can produce content with greater speed and lower overhead. Ultimately, the most effective AI strategies are those that prioritize clear-eyed business decisions, such as extending the lifecycle of legacy products, over the pursuit of industry hype.
- InnoGames transitioned the live operations of Sunrise Village from a 25-person team to a 3-person team using AI, successfully shifting the title from a loss-making project to a profitable one.
- The AI implementation did not stop the game's revenue decline, but it significantly slowed the rate of decay while allowing 22 staff members to be reallocated to new development projects.
- The primary efficiency gain came from automating manual data-shuffling tasks, such as converting design definitions from Confluence to Excel and then to JSON for Unity, rather than from high-level creative AI generation.
- InnoGames maintained a stable, older model (GPT-4o) for over 18 months to ensure production pipeline reliability, prioritizing consistency over the latest model capabilities when running semi-autonomous workflows.
- Studios should prioritize observing internal team workflows to identify unglamorous bottlenecks before attempting to implement broad AI strategies or purchasing new tools.
+2
Deconstructor of FunJul 2026
Article
The Hidden Cost of Studio Engineering
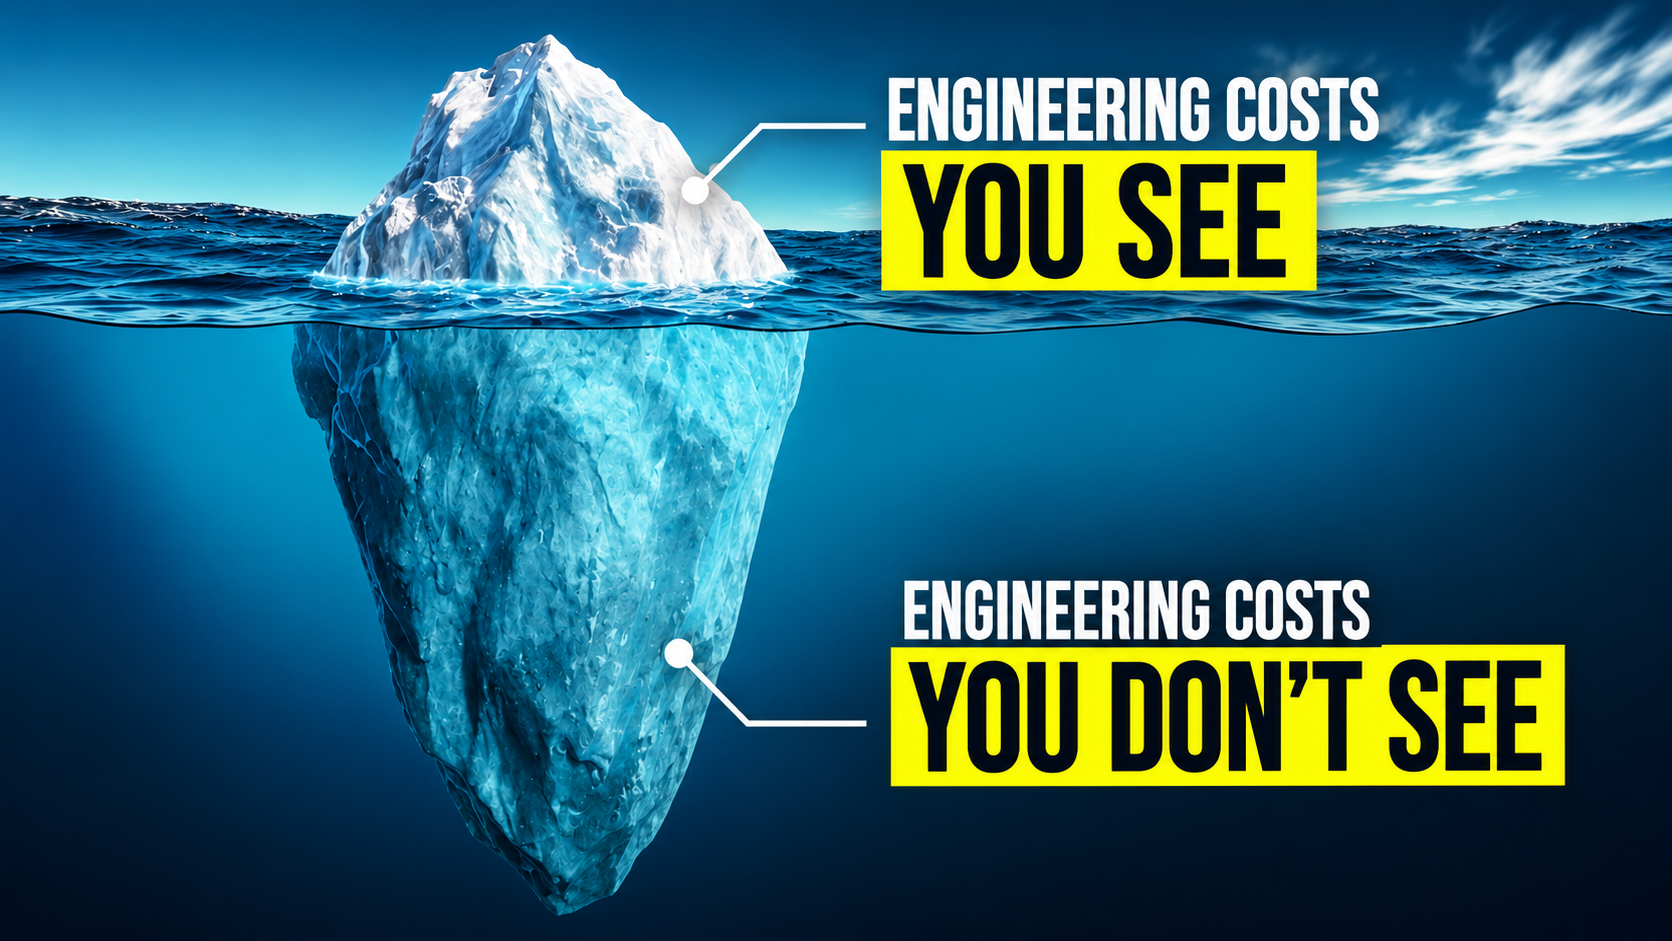
The gaming industry frequently miscalculates the financial implications of internal versus external software development, leading to a systemic bias toward building proprietary tools that ultimately prove more expensive than licensing third-party solutions. The core thesis posits that internal engineering projects are often perceived as "free" because their costs are absorbed into existing payroll and sprint cycles, masking the true total cost of ownership (TCO). This accounting illusion obscures the reality that internal builds require significant capital and human resources that could be better utilized on game-specific innovation.
A comprehensive TCO analysis must account for five critical components: initial build costs, ongoing maintenance, system evolution, knowledge retention, and opportunity cost. Industry data suggests that maintenance alone typically consumes 60 to 80 percent of a system’s total lifecycle cost, with annual upkeep requiring 15 to 25 percent of the initial investment. Furthermore, the opportunity cost—defined as the diversion of top engineering talent away from unique, game-differentiating features toward generic infrastructure like matchmaking or leaderboards—represents the most significant, yet often ignored, expense.
The analysis concludes that studios should reserve internal engineering capacity exclusively for proprietary problems that cannot be solved by commercially available, battle-tested tools. By failing to rigorously evaluate the full lifecycle costs of internal infrastructure, studios risk project delays, increased technical debt, and a loss of competitive focus. Adopting a disciplined build-versus-buy framework is essential for studios to optimize capital allocation and ensure that engineering talent remains focused on delivering the unique experiences that drive player engagement.
- The opportunity cost of diverting top engineering talent from game-differentiating features to generic infrastructure represents the most significant, yet frequently ignored, expense for gaming studios.
- Internal software maintenance consumes 60 to 80 percent of a system’s total lifecycle cost, with annual upkeep requiring an additional 15 to 25 percent of the initial investment.
- Studios often miscalculate the financial impact of internal development because payroll-absorbed costs mask the true total cost of ownership, creating an illusion that proprietary tools are 'free'.
- A comprehensive total cost of ownership analysis must account for five critical components: initial build costs, ongoing maintenance, system evolution, knowledge retention, and opportunity cost.
- Internal engineering capacity should be reserved exclusively for proprietary problems that cannot be solved by commercially available, battle-tested third-party solutions.
+1
Deconstructor of FunJul 2026
Article
The 30% Era Is Over: Google Play's Games GM Explains What Comes Next
The mobile gaming industry is undergoing a significant structural shift as Google Play decouples its service fees from its billing fees. This change, effective as of mid-2026 in the United States, United Kingdom, and European Economic Area, marks the end of the long-standing 30% platform fee model. Under the new framework, the standard service fee for new installs is reduced to 20%, with an additional 5% billing fee that can be bypassed entirely if developers implement their own payment systems. Notably, existing user cohorts remain subject to a 25% base fee, a policy intended to reflect historical platform investments in those specific player bases.
The transition is supported by the Level Up program, which incentivizes developers to meet technical benchmarks—such as high-performance graphics, cross-device compatibility, and robust engagement features—in exchange for favorable rate cards. While these requirements include mandatory integration of the Sidekick overlay, Google clarifies that this tool is designed to enhance player immersion rather than serve as an AI-driven coaching mechanism. Furthermore, the company maintains that the choice of billing system does not influence a game’s organic store ranking, discoverability, or eligibility for promotional featuring.
This policy evolution represents a move toward a more flexible, albeit complex, economic environment for developers. While the new structure lowers the barrier for user acquisition, it introduces operational challenges, requiring finance teams to manage revenue tracking across different cohorts and regions. Ultimately, the shift signals a transition where platform providers must increasingly justify their billing fees through product value and commerce infrastructure rather than relying on mandatory policy enforcement. The rollout is scheduled to expand globally through 2027, fundamentally altering the financial calculus for mobile game studios.
- Starting in mid-2026, Google Play will reduce its standard service fee for new installs to 20% in the US, UK, and EEA, effectively ending the 30% platform fee model.
- Developers can bypass an additional 5% billing fee by implementing their own payment systems, though existing user cohorts will remain subject to a 25% base fee.
- The policy rollout will expand globally throughout 2027, fundamentally altering the financial and operational requirements for mobile game studios.
- Google’s 'Level Up' program offers developers favorable rate cards in exchange for meeting technical benchmarks, including high-performance graphics, cross-device compatibility, and integration of the Sidekick overlay.
- Google maintains that the choice of billing system will not impact a game’s organic store ranking, discoverability, or eligibility for promotional featuring.
+2
Deconstructor of FunJul 2026
Article
Does Merge-2 Monetize Better Than Match-3?
The article examines why Merge‑2 titles such as Gossip Harbor and Travel Town have recently surpassed the long‑standing revenue leader Candy Crush Saga, questioning whether Merge‑2 monetizes more effectively than Match‑3 games. Using February 2026 revenue figures—Gossip Harbor at $77.7 million versus Candy Crush’s $71.7 million—the author notes a 172 % YoY quarterly growth for Merge‑2 compared to a 7 % decline for Match‑3. The analysis focuses on board mechanics, player psychology, and monetization strategies rather than raw numbers alone.
Key observations highlight that Match‑3 sells “solutions” to a finite puzzle, while Merge‑2 sells continuity of an ongoing economy. Energy in Merge‑2 is not merely a limiter; it becomes a tool for maintaining momentum, allowing players to keep progressing rather than facing a clean fail state. This design removes the natural selling ceiling present in Match‑3, where each level offers a limited number of purchase opportunities. The article also notes recent mechanical innovations—boosted generators that consume more energy per tap—and the role of Chinese publishers with large user‑acquisition budgets in accelerating Merge‑2’s growth.
The scope covers global mobile markets, focusing on 2025–2026 data across major Merge‑2 and Match‑3 titles. Methodology is qualitative, drawing on first‑person gameplay observations, revenue comparisons, and industry trend analysis. The conclusion is nuanced: Merge‑2 extracts higher per‑player revenue by sustaining player engagement, whereas Match‑3 still dominates total market size due to its broader audience and clearer gameplay loop. The piece argues that Merge‑2’s success stems from a different player relationship—one where nothing truly ends—rather than an inherently superior monetization mechanic.
- In February 2026, the Merge-2 game Gossip Harbor surpassed Candy Crush Saga in monthly revenue ($77.7 million vs. $71.7 million). By the end of Q1 2026, Gossip Harbor's quarterly revenue grew 172% year-over-year, while Candy Crush's fell 7%.
- The core difference between Merge-2 and Match-3 monetization lies in their board mechanics: Match-3 boards are temporary and reset each level, while Merge-2 boards are persistent, allowing players to manage an ongoing economy rather than solve discrete puzzles.
- Match-3 games monetize by selling solutions to failed levels, offering a 'clean break' for players. Merge-2 games monetize by selling continuity, using energy systems to pause progress and encourage spending to maintain momentum on an unfinished board.
- Merge-2 games, unlike Match-3, have no inherent spending ceiling; players can continuously refill energy and use boosted generators to progress faster, ensuring an endless selling opportunity.
- The current success of Merge-2 is attributed to the maturation of its core energy mechanic (e.g., boosted generators becoming standard around 2023) and significant user acquisition budgets from publishers like Microfun, who can compete with established Match-3 titles.
+2
Deconstructor of FunJun 2026
Article
The Runtime Gap: What 25 Years Inside Game Engines Taught Andrew Bowell About Where AI Actually Matters
The article examines the evolving role of artificial intelligence in video games, arguing that true innovation lies not in production tooling but in runtime player experience. It contrasts historical engine milestones—Havok’s physics focus and Unity’s mobile accessibility—with a forthcoming wave that leverages machine learning to create dynamic, responsive worlds. The author highlights Iconic’s ambition to embed conversational AI characters with memory and narrative coherence directly into game engines, positioning this as a design primitive rather than an add‑on.
A key economic insight is the cost of cloud‑based inference for large player bases; running a language model in the cloud becomes prohibitively expensive and raises privacy concerns. Iconic’s solution is on‑device inference, demonstrated in its title The Oversight Bureau, which eliminates ongoing token costs but is limited to high‑end hardware, prompting a hybrid approach as a bridge. The discussion notes that only about 30 % of Steam users possess GPUs capable of full AI stacks, underscoring the hardware reach challenge.
The piece also contextualizes Iconic’s strategy within the broader engine landscape, comparing it to middleware successes like Havok and cautioning against the high failure rate of new engine ventures. Iconic’s focus on a specialized AI runtime layer, rather than competing with Unity or Unreal on rendering and physics, mirrors middleware models. The article concludes that while the thesis is compelling, commercial validation hinges on player demand for AI‑native experiences and the scalability of on‑device inference before incumbents integrate similar capabilities.
- The significant AI paradigm shift in games is expected at runtime, enhancing player experience with dynamic, responsive game worlds, rather than merely improving production efficiency through asset generation or code assistance.
- On-device AI inference is crucial for the economic viability of AI-native games, as cloud-based inference for a million concurrent users results in existential token costs and latency issues.
- Iconic, led by Andrew Bowell (who spent 15 years at Havok and 10 years at Unity, where he built the product organization that captured 50%+ market share before their $13.7B IPO), is developing engine technology for AI-native interactive experiences.
- Iconic's first title, "The Oversight Bureau," runs its full AI stack on a Steam Deck, achieving zero ongoing inference costs per player, though this currently requires high-end GPUs (e.g., Nvidia 4080) only available to about 30% of Steam users.
- Iconic's strategy is to build a component layer (an AI runtime and authoring toolset) that sits on top of existing engines like Unity and Unreal, rather than competing as a full engine.
+1
Deconstructor of FunJun 2026
Article
My Wife Deleted Roblox
The article examines Roblox’s safety strategy after a parent’s wife removed the platform from family devices, citing media‑driven concerns. It argues that Roblox’s unique transparency about hosting children—36 % of age‑checked users are under 13, 38 % teens, and 26 % adults—forces the company to prioritize safety for its most vulnerable users. The piece details a suite of technical safeguards: a facial age‑estimation “Age Check” deployed globally in January 2025, a communication architecture that blocks image/video sharing and limits chat to same‑age peers, and an AI‑driven “Sentinel” model that flags grooming conversations. Roblox also moderates every user‑generated asset, applies real‑time multimodal moderation (RM3) to live gameplay, and monitors off‑platform contact attempts, escalating flagged cases to a law‑enforcement‑trained team. The article cites that in the first half of 2025, Sentinel generated roughly 1 200 reports to the National Center for Missing and Exploited Children, while daily text moderation processes over 4 billion messages. It links these investments to Roblox’s growth model, noting that trust—rather than advertising—drives installs and developer participation. The author contrasts Roblox’s proactive safety posture with competitors such as TikTok, YouTube, Instagram, and Discord, highlighting regulatory actions against those platforms for child‑privacy violations. The piece concludes that while no platform can eliminate risk, Roblox’s layered safeguards and age‑tiered accounts (Roblox Kids and Select) position it ahead of peers, encouraging parents to reinstall the service with confidence.
- Roblox’s user base is composed of 36% children under 13, 38% teens, and 26% adults, necessitating a safety-first operational model to maintain platform trust.
- The platform utilizes an AI-driven 'Sentinel' model that flagged approximately 1,200 cases for the National Center for Missing and Exploited Children in the first half of 2025.
- Roblox processes over 4 billion messages daily through automated text moderation systems to identify and mitigate grooming or harmful interactions.
- Technical safety measures include a global facial age-estimation 'Age Check' deployed in January 2025, real-time multimodal moderation (RM3) for live gameplay, and the restriction of image/video sharing.
- Roblox differentiates itself from competitors like TikTok, YouTube, Instagram, and Discord by implementing age-tiered accounts ('Roblox Kids' and 'Select') and proactive law-enforcement collaboration.
+1
Deconstructor of FunJun 2026
Article
Deep Dive into Grand Games’ Success with Batuhan Çelebi
Grand Games has accelerated from a zero‑budget studio to a $500 million annual run rate in just two years, achieving a fivefold revenue jump within the last twelve months. The company raised $103 million from prominent investors, including Balderton and Laton Ventures, with a Series A of $30 million completed in record time for Turkey and a subsequent Series B that doubled the valuation to $70 million without new investors, signaling strong founder conviction and product‑market fit. Grand’s growth strategy centers on five autonomous studios of roughly fifteen people each, a structure designed to preserve individual ownership and accelerate feature delivery; AI‑assisted development and shared codebases enable rapid porting of features across titles in three days. The studio deliberately rejects the volume model, instead employing a “sniper” approach that greenlights only games with clear pain‑point differentiation and a sizable total addressable market, as validated by Sensor Tower data. While the company excels at identifying underserved puzzle‑game audiences and delivering premium experiences, it acknowledges a current weakness in post‑launch live‑ops optimization, planning to separate launch and operations teams as it scales. Operating entirely within Istanbul, Grand leverages local talent and government subsidies that cover 50 % of marketing and app‑store costs during early growth, positioning itself as a regional champion that prioritizes acquisition over exit.
- Grand Games scaled from a zero-budget startup to a $500 million annual run rate in two years, achieving a fivefold revenue increase in the last twelve months.
- The studio raised $103 million in total funding, including a Series A of $30 million and a Series B that doubled the company valuation to $70 million without requiring new investors.
- The company utilizes a 'sniper' development strategy, rejecting high-volume models in favor of greenlighting only titles with clear pain-point differentiation and large addressable markets validated by Sensor Tower data.
- Operational efficiency is driven by five autonomous 15-person studios using AI-assisted development and shared codebases, which allow for feature porting across titles in three days.
- Grand Games leverages Istanbul’s local talent pool and government subsidies that cover 50% of marketing and app-store costs during the early growth phase.
+1
Deconstructor of FunJun 2026
Article
Where Asia’s $103 Billion Game Market Is Actually Growing
The analysis highlights that Asia’s gaming market is projected to grow from $88.9 billion in 2025 to $103.6 billion by 2030, a 3.1% CAGR, with player numbers approaching two billion. The region’s revenue is dominated by mature markets—China, Japan, and Korea—which together account for 88.6% of the regional share in 2030 but exhibit modest growth rates (China 2.9%, East Asia 2.5%). Emerging markets such as India, MENA‑3, and Southeast Asia drive the majority of growth, with India’s player base expanding by roughly 200 million while revenue rises from $1 billion to $1.8 billion, yielding an average spend of about $2 per player versus $371 in Korea.
A significant behavioral shift is observed: over 30% of players across the 13 markets now prefer to transact outside the app, a trend that has already increased out‑of‑app revenue shares in Southeast Asia from 21% to 38% between 2022 and 2024. This early adoption of direct‑to‑consumer models suggests that Western publishers should prioritize building such capabilities sooner rather than later.
Growth is also emerging in non‑mobile segments, notably PC and console markets in Japan (8% growth), mini‑games within super apps in China (nearly 20% of mobile spend), and Switch 2 sales. Genre shifts are evident, with India moving beyond battle royale into casual titles and China embracing dating sims, social deduction, realistic sports, and idle RPGs.
The player demographic is broadening: women now represent 42% of players, with rapid gains in India and MENA‑3, while raw player growth is strongest in India, Indonesia (projected 144 million players), and Vietnam (68 million).
Finally, generative AI is viewed more positively in Asia; studios report development efficiencies but caution against player‑facing applications that may provoke backlash. The overall takeaway is that while mature markets retain most revenue, emerging regions offer growth opportunities for studios willing to adapt to local preferences and leverage direct‑to‑consumer strategies.
- Asia’s gaming market is projected to grow from $88.9 billion in 2025 to $103.6 billion by 2030, driven primarily by emerging markets in India, Southeast Asia, and MENA-3.
- Mature markets (China, Japan, and Korea) will continue to dominate with 88.6% of total regional revenue by 2030, despite experiencing modest growth rates between 2.5% and 2.9%.
- Over 30% of players across 13 Asian markets now prefer out-of-app transactions, a trend that saw Southeast Asia’s direct-to-consumer revenue share jump from 21% to 38% between 2022 and 2024.
- India is a key volume driver with a projected 200 million new players, though average spend remains low at approximately $2 per player compared to $371 in Korea.
- Non-mobile segments are showing renewed strength, including 8% growth in Japan’s PC and console markets and mini-games accounting for nearly 20% of mobile spend in China.
+3
Deconstructor of FunJun 2026
Article
Nobody Told You This About Consulting
The article explains why a growing number of game‑industry veterans are turning to consulting, largely as a survival strategy after widespread layoffs. In 2022 and again in 2026, more than 45 000 workers were let go, with a U.S. study indicating that one‑third of industry employees were laid off in 2025. The piece follows John Wright, a former VP at Kwalee who began consulting in 2025, to illustrate the typical post‑layoff trajectory. After announcing his availability on LinkedIn, Wright received a surge of attention—tens of thousands of views and dozens of messages—but only about 33 % converted into contracts. The author notes that the initial wave of interest is often short‑lived, and a stable pipeline usually takes close to a year for most newcomers without an established network.
Key findings include the psychological impact of identity loss when shifting from a senior role to advisory work, and practical advice on structuring fees (day rates with volume incentives, goal‑based or equity arrangements). The article stresses the importance of early rejection handling, recognizing time‑wasting leads, and accounting for seasonality—especially when working with European clients. It also highlights the benefits of fractional engagements, which keep consultants’ skills sharp and provide longer‑term relationships.
The piece concludes that consulting is likely a phase for many, given the industry’s pivot toward AI and slower hiring. It advises newcomers to secure at least three months of financial runway before starting, to focus on fractional roles for skill retention, and to avoid comparison traps. Overall, the article offers a realistic, data‑driven overview of consulting economics and career strategy in the current gaming landscape.
- The gaming industry experienced massive workforce reductions in 2022 and 2026, with a 2025 U.S. study revealing that one-third of all industry employees were laid off.
- New consultants often face a significant conversion gap; for example, former Kwalee VP John Wright saw only 33% of his initial LinkedIn-generated leads convert into actual contracts.
- Building a stable consulting pipeline typically requires nearly a year of effort for those without a pre-existing professional network.
- Newcomers should secure at least three months of financial runway before transitioning to consulting to mitigate the risks of industry volatility and slow hiring.
- Effective fee structures for game industry consultants include a mix of day rates with volume incentives, goal-based milestones, or equity-based arrangements.
+1
Deconstructor of FunMay 2026