CyberAgent
Game Co.111 documents
Internet/media company, parent of Cygames (Granblue Fantasy, Uma Musume, Princess Connect). Game segment is major revenue driver.
Documents
Financial44 pages
3Q FY2025 Presentation Material
CyberAgent’s third-quarter results for fiscal year 2025 demonstrate a significant financial recovery and a strategic pivot toward a high-profit business model. Consolidated sales reached 210.7 billion yen, a 10.9% year-on-year increase, while operating profit surged by 138.3% to 19.6 billion yen. This performance was primarily catalyzed by the Gaming segment, which experienced a 30.4% rise in sales and a tripling of operating profit to 16.4 billion yen. The success of new titles and the expansion of existing intellectual properties, such as the global Steam release of Umamusume: Pretty Derby, underscore a successful transition toward a more diversified and globalized revenue stream.
The Media segment, centered on the ABEMA platform, has successfully moved from an intensive investment phase into a profitable one, with operating profit growing 7.8 times year-on-year. While the Internet Advertising business faced a 35.6% decline in profit due to rising human resource costs and client turnover, the overall corporate outlook remains highly optimistic. Consequently, the full-year operating profit forecast has been revised upward by 57.1% to 66 billion yen. This growth strategy relies on a robust pipeline of upcoming releases, including Shadowverse: Worlds Beyond and Hello Kitty Merch Match, which are slated for broad international distribution across 144 regions.
Looking ahead, the long-term objective involves establishing the Media and IP segments as primary profit drivers alongside traditional advertising and gaming. By integrating technological innovation with cross-media projects and anime production, the company aims to solidify ABEMA as a core component of social infrastructure while scaling its gaming IP globally. This multifaceted approach positions the organization to maintain momentum through the remainder of the fiscal year and beyond, leveraging a mix of established franchises and aggressive expansion into new markets.
- CyberAgent’s 3Q FY2025 operating profit surged 138.3% year-on-year to 19.6 billion yen, leading the company to raise its full-year operating profit forecast by 57.1% to 66 billion yen.
- The Gaming segment was the primary growth driver, achieving a 30.4% sales increase and tripling its operating profit to 16.4 billion yen behind the success of new titles and the global Steam release of Umamusume: Pretty Derby.
- The ABEMA media platform transitioned from an investment phase to profitability, recording a 7.8-fold year-on-year increase in operating profit.
- Consolidated sales for the third quarter reached 210.7 billion yen, representing a 10.9% increase compared to the previous year.
- The Internet Advertising business experienced a 35.6% decline in profit, attributed to rising human resource costs and client turnover.
+2
CyberAgentAug 2025
Financial10 pages
FY2025 Third Quarter Consolidated Financial Results [Japanese GAAP]
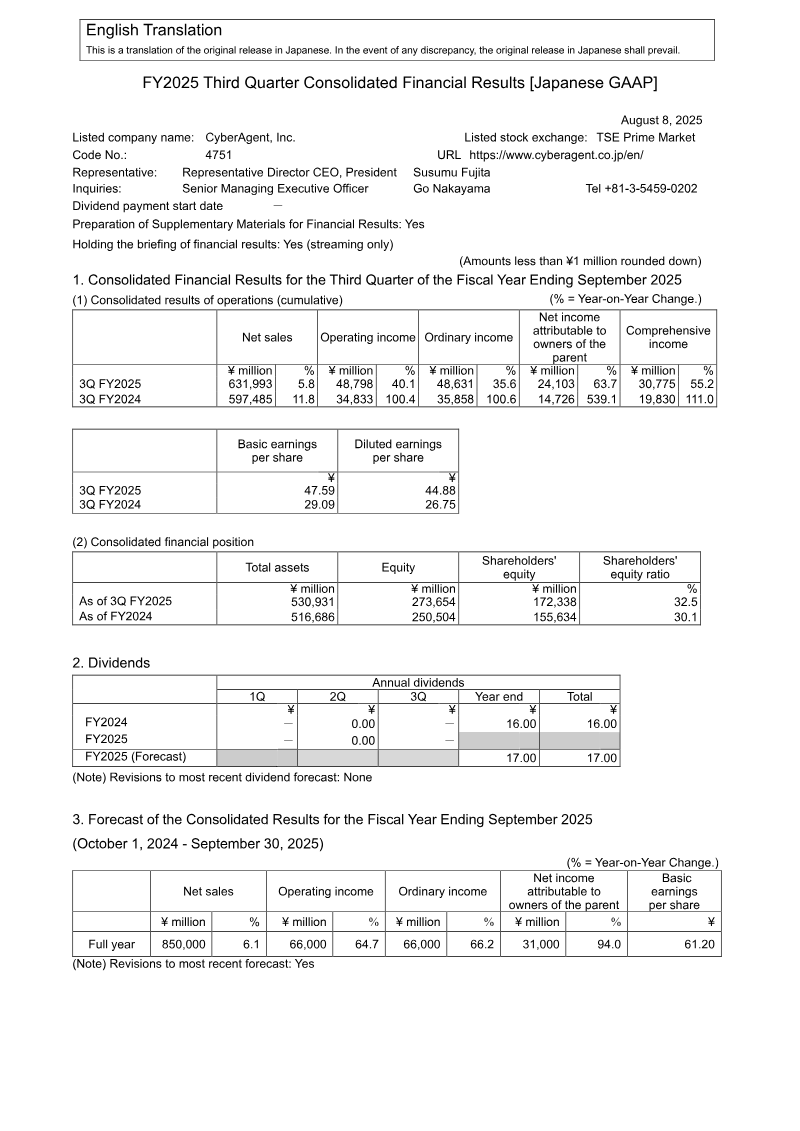
CyberAgent demonstrated robust financial growth through the third quarter of the fiscal year ending September 2025, characterized by a 5.8% year-on-year increase in net sales to ¥631,993 million and a substantial 40.1% surge in operating income to ¥48,798 million. This performance was primarily propelled by a successful turnaround in the Media and IP segment, specifically ABEMA, alongside a 31.0% rise in Game Business operating income. The gaming division remains the primary profit driver, contributing ¥35,162 million in income, which offset a ¥3,514 million impairment loss resulting from declining profitability in specific legacy services. Improved payment efficiencies and the success of major titles further bolstered these results, leading to an upward revision of the full-year forecast to ¥850,000 million in net sales.
The company’s financial position strengthened during this period, with total equity rising to ¥273,654 million and retained earnings growing to ¥138,698 million. Beyond immediate operational gains, there is a clear strategic focus on long-term expansion within the digital transformation and startup ecosystems. This is evidenced by the establishment of the CA Startups Internet Fund No. 4, a venture capital vehicle with a maximum investment of ¥5,000 million. Managed by CyberAgent Capital, this fund targets seed and early-stage startups both domestically and internationally. Due to the scale of this investment relative to the parent company’s capital stock, the fund is classified as a specified subsidiary, signaling a commitment to fostering innovation in the global digital sector as a core component of future growth.
- CyberAgent reported a 5.8% year-on-year increase in net sales to ¥631,993 million and a 40.1% surge in operating income to ¥48,798 million for the third quarter of FY2025.
- The Game Business remains the primary profit driver, contributing ¥35,162 million in operating income, representing a 31.0% increase that offset a ¥3,514 million impairment loss from legacy services.
- Driven by strong performance in the gaming division and the turnaround of the ABEMA media segment, the company has revised its full-year net sales forecast upward to ¥850,000 million.
- The company’s financial position improved during the period, with total equity reaching ¥273,654 million and retained earnings growing to ¥138,698 million.
- CyberAgent established the CA Startups Internet Fund No. 4, a venture capital vehicle with a maximum investment of ¥5,000 million, to target early-stage startups globally.
CyberAgentAug 2025
Financial43 pages
2Q FY2025 Presentation Material
CyberAgent achieved record-high consolidated sales of 217.3 billion yen in the second quarter of fiscal year 2025, representing a 1.2% year-on-year increase. This growth was primarily fueled by the Media and Internet Advertisement segments, which offset a 23.4% revenue decline in the Game business. Despite the year-on-year dip in gaming—attributed to a high-base comparison from a major release in the previous year—the segment demonstrated a significant 4.6x quarter-on-quarter profit recovery. Overall operating profit reached 20.8 billion yen, placing the company in a strong position to meet its annual targets, with current earnings already accounting for nearly 70% of the full-year forecast.
The strategic focus has shifted toward a high-profit business model that integrates Media and IP segments to create a global ecosystem for intellectual property production and monetization. To stabilize and grow the gaming division, the company is leveraging a pipeline of six upcoming titles, including high-profile projects like Shadowverse: Worlds Beyond, while expanding high-margin external payment methods. Furthermore, the aggressive implementation of artificial intelligence remains a core operational priority, evidenced by the launch of an internal AI agent platform designed to enhance advertising effectiveness and internal efficiency.
Corporate governance and long-term sustainability are addressed through the CyberAgent Way 2024 framework, which emphasizes succession planning and ESG initiatives. The company maintains a diverse and valuable portfolio of intellectual property, featuring major titles such as Umamusume: Pretty Derby and Jujutsu Kaisen Phantom Parade. While the current financial trajectory remains positive, future performance remains subject to market volatility and the inherent risks of the competitive digital entertainment and advertising landscapes. This balanced approach between established media services and new technological integration defines the current fiscal strategy.
- CyberAgent achieved record-high consolidated sales of 217.3 billion yen in 2Q FY2025, a 1.2% year-on-year increase driven by Media and Internet Advertisement segments.
- Operating profit reached 20.8 billion yen, putting the company on track to meet its annual targets with 70% of the full-year forecast already realized.
- The Game business experienced a 23.4% year-on-year revenue decline due to a high-base comparison from the previous year, though segment profit recovered 4.6x quarter-on-quarter.
- The company is prioritizing the stabilization of its gaming division through a pipeline of six upcoming titles, including 'Shadowverse: Worlds Beyond', and the expansion of high-margin external payment methods.
- Strategic growth is focused on integrating Media and IP segments to build a global monetization ecosystem, supported by established titles like 'Umamusume: Pretty Derby' and 'Jujutsu Kaisen Phantom Parade'.
+1
CyberAgentMay 2025
Financial20 pages
Partial Correction to FY2020 Consolidated Financial Results [Japanese GAAP]
CyberAgent, Inc. achieved significant financial growth during the fiscal year ended September 30, 2020, characterized by a 5.5% increase in net sales to ¥478,526 million and a 9.8% rise in operating income to ¥33,839 million. The most notable metric was the 287.5% surge in profit attributable to shareholders of the parent, which reached ¥6,567 million. This performance drove basic earnings per share from ¥13.45 in the previous year to ¥52.09, allowing for a year-end dividend of ¥34.00. The company’s financial position strengthened alongside these earnings, with net assets rising to ¥127,637 million and cash flow from operating activities increasing to ¥37,028 million.
The Group’s success was primarily anchored by the Game and Internet Advertisement segments, which generated incomes of ¥30,337 million and ¥21,030 million, respectively. While the Media Business experienced 22.6% sales growth, it recorded an operating loss of ¥18,267 million as a result of sustained strategic investments in the ABEMA streaming platform. Geographically, operations remain concentrated in the Japanese market, which accounts for over 90% of total sales and assets. To better align with current management strategies, the company also executed a structural transfer of specific businesses from the Internet Advertisement segment to the Media segment.
Looking ahead, the company forecasts continued expansion with a net sales target of ¥500 billion for fiscal year 2021. This outlook is supported by the strong performance of hit game titles and the broader expansion of the smartphone market. Despite ongoing impairment losses, which decreased to ¥4,589 million from the previous year’s ¥9,502 million, the Group maintains a robust liquidity position with a year-end cash balance exceeding ¥102,368 million. This capital provides the necessary foundation for continued investment in intangible assets and property to support its diverse reportable segments.
- CyberAgent achieved significant growth in FY2020, with net sales rising 5.5% to ¥478,526 million and operating income increasing 9.8% to ¥33,839 million.
- Profit attributable to shareholders surged 287.5% to ¥6,567 million, resulting in basic earnings per share of ¥52.09 and a year-end dividend of ¥34.00.
- The Game segment was the primary profit driver with ¥30,337 million in income, followed by the Internet Advertisement segment at ¥21,030 million.
- The Media Business recorded an operating loss of ¥18,267 million despite a 22.6% increase in sales, reflecting sustained strategic investment in the ABEMA streaming platform.
- The company maintains a strong liquidity position with a year-end cash balance of ¥102,368 million, supporting a FY2021 net sales target of ¥500 billion.
CyberAgentMay 2025
Financial20 pages
Partial Correction to FY2021 Consolidated Financial Results (Japanese GAAP)
CyberAgent, Inc. achieved exceptional financial growth during the 2021 fiscal year, characterized by a 39.2% increase in consolidated net sales to ¥666,149 million and a 207.5% surge in operating income to ¥104,070 million. This performance was underpinned by a significant rise in profit attributable to shareholders, which climbed from ¥6,567 million in the previous year to ¥41,242 million. The company’s liquidity position strengthened considerably, with cash and cash equivalents nearly doubling to ¥184,082 million, supported by robust operating cash flows of ¥109,609 million.
The Game Business served as the primary catalyst for this expansion, recording a 68.6% revenue increase to ¥262,751 million and a 217.9% jump in segment income to ¥96,445 million. This success was largely attributed to the performance of a major new title launch. Simultaneously, the Internet Advertisement Business reached record net sales of ¥321,001 million, while the Media Business grew by 45.1%, successfully narrowing its operating losses to ¥15,141 million. Other corporate developments included a four-for-one stock split implemented in April 2021, resulting in adjusted basic earnings per share of ¥81.68.
Despite the strong fiscal results, management has opted not to provide a formal forecast for the 2022 fiscal year. This decision stems from the inherent volatility of the game industry, where the timing of new title launches and the fluctuation of hit-driven revenue cycles create significant uncertainty. While the company maintains a diversified portfolio across media, advertising, and investment development, the high impact of the gaming segment on overall profitability necessitates a cautious approach to forward-looking guidance.
- CyberAgent achieved significant FY2021 growth with consolidated net sales rising 39.2% to ¥666,149 million and operating income surging 207.5% to ¥104,070 million.
- The Game Business was the primary driver of financial performance, delivering a 68.6% revenue increase to ¥262,751 million and a 217.9% rise in segment income to ¥96,445 million, largely due to a major new title launch.
- Profit attributable to shareholders increased significantly to ¥41,242 million, up from ¥6,567 million in the previous fiscal year.
- The Internet Advertisement Business reached record net sales of ¥321,001 million, while the Media Business grew 45.1% and reduced its operating losses to ¥15,141 million.
- Cash and cash equivalents nearly doubled to ¥184,082 million, supported by ¥109,609 million in operating cash flows.
CyberAgentMay 2025
Financial10 pages
Partial Correction to FY2022 Third Quarter Consolidated Financial Results [Japanese GAAP]
CyberAgent, Inc. issued this corrective filing on May 15, 2025, to amend its consolidated financial results for the third quarter of fiscal year 2022, originally disclosed in July 2022. The revisions stem from a broader initiative to correct past annual securities reports and financial statements for prior fiscal years. The scope of the data covers the nine-month period ending June 30, 2022, and includes comparative data from the same period in 2021, prepared in accordance with Japanese GAAP.
The corrected figures show that for the third quarter of FY2022, CyberAgent recorded net sales of ¥533,882 million, a 9.7% increase year-on-year. However, operating income fell 29.1% to ¥54,813 million, and profit attributable to shareholders of the parent dropped 39.8% to ¥19,779 million. The Media Business, driven by ABEMA’s pay-per-view growth, saw sales rise 36.2% to ¥81,926 million while narrowing its operating loss. The Internet Advertisement Business reached record high sales of ¥283,878 million. Conversely, the Game Business experienced a 6.9% decline in sales to ¥173,551 million and a 29.4% drop in operating income, attributed to the high baseline set by major events in the previous year.
Methodologically, the results reflect the application of the Accounting Standard for Revenue Recognition. This change specifically impacted the Game Business, where revenue from item charges is now recognized over an estimated user usage period rather than at the point of purchase. Despite these accounting adjustments and the numerical corrections, the company maintained its full-year earnings forecast and dividend projections as originally stated in April 2022. Total assets were reported at ¥373,421 million, a slight decrease from the end of the previous fiscal year due to corporate tax and dividend payments.
- CyberAgent issued a corrective filing for Q3 FY2022, reporting net sales of ¥533,882 million (up 9.7% YoY) but a significant 29.1% decline in operating income to ¥54,813 million.
- Profit attributable to shareholders of the parent dropped 39.8% to ¥19,779 million, despite the company maintaining its original full-year earnings and dividend forecasts.
- The Game Business saw a 6.9% decline in sales to ¥173,551 million and a 29.4% drop in operating income, largely due to a high baseline from the previous year's major events.
- Accounting changes under the Accounting Standard for Revenue Recognition now require game item charges to be recognized over the estimated user usage period rather than at the time of purchase.
- The Internet Advertisement Business achieved record-high sales of ¥283,878 million during the nine-month period ending June 30, 2022.
CyberAgentMay 2025
Financial19 pages
Partial Correction to FY2022 Consolidated Financial Results (Japanese GAAP)
CyberAgent’s financial performance for the fiscal year ended September 30, 2022, reflects a period of strategic transition characterized by record-breaking growth in media and advertising alongside a significant contraction in the gaming sector. Consolidated net sales reached ¥709.9 billion, a 6.6% year-over-year increase, yet operating income fell 35.1% to ¥67.5 billion. This decline in profitability was primarily driven by the Game Business, where sales dropped 13.1% to ¥228.4 billion and operating income plummeted 37.2% due to the natural slowdown of major titles. Despite these headwinds, the Internet Advertisement Business achieved record sales of ¥376 billion, and the Media Business grew 35.5% behind the expansion of the ABEMA platform.
The fiscal year also marked a shift in financial health and accounting methodology. Total equity rose substantially to ¥221.2 billion, yet net cash from operating activities decreased from ¥109.6 billion to ¥17.9 billion, largely due to increased income tax obligations. Furthermore, the adoption of new revenue recognition standards altered how game item charges are recorded, moving from the point of purchase to the estimated usage period. These changes, combined with the transition to a group tax sharing system, resulted in basic earnings per share falling from ¥81.68 to ¥45.29.
Looking forward, the company maintains a stable dividend policy of ¥14.00 per share and projects modest growth for FY2023 with a net sales forecast of ¥720 billion. While the gaming segment remains a core profit driver, the overall corporate strategy increasingly relies on the diversification of revenue through digital media and advertising to offset the inherent volatility of the mobile gaming market. This corrected financial outlook underscores a period of high investment and structural adjustment within the Japanese digital entertainment and advertising landscape.
- CyberAgent’s FY2022 operating income fell 35.1% to ¥67.5 billion, despite a 6.6% increase in consolidated net sales to ¥709.9 billion.
- The Game Business experienced a significant downturn, with sales dropping 13.1% to ¥228.4 billion and operating income plummeting 37.2% due to the natural lifecycle slowdown of major titles.
- The Internet Advertisement Business reached record sales of ¥376 billion, while the Media Business grew 35.5% driven by the expansion of the ABEMA platform.
- Basic earnings per share decreased significantly from ¥81.68 to ¥45.29, impacted by new revenue recognition standards for game items and increased tax obligations.
- Net cash from operating activities declined sharply from ¥109.6 billion to ¥17.9 billion, largely due to higher income tax payments.
CyberAgentMay 2025

Financial10 pages
Partial Correction to FY2023 Third Quarter Consolidated Financial Results [Japanese GAAP]
CyberAgent, Inc. issued this formal correction to its consolidated financial results for the third quarter of fiscal year 2023, covering the nine-month period ending June 30, 2023. The primary purpose of the document is to provide revised numerical data and financial statements following the submission of correction reports for past annual securities reports. The scope of the data includes the company’s major business segments: Media, Internet Advertisement, Games, Investment Development, and Other Businesses.
Key findings for the cumulative third quarter of FY2023 show net sales of ¥534,397 million, a marginal year-on-year increase of 0.1%. However, profitability metrics saw significant declines. Operating income fell 68.3% to ¥17,383 million, and net income attributable to owners of the parent dropped 88.3% to ¥2,304 million. These declines are attributed to heavy investments in the Media business—specifically the distribution of the FIFA World Cup Qatar 2022 on ABEMA—and a 21.2% revenue decrease in the Game Business following the slowdown of major titles like those from Cygames.
The consolidated financial position as of June 30, 2023, shows total assets of ¥461,683 million, an increase of ¥79,749 million from the end of the previous fiscal year. This growth was primarily driven by the issuance of convertible bonds and an increase in long-term bank loans, which also resulted in total liabilities rising to ¥235,349 million. The Internet Advertisement business remained a primary driver of volume, reaching record net sales of ¥300,672 million, though its operating income decreased by 30.2% due to upfront investments. The methodology follows Japanese GAAP standards, incorporating recent changes to accounting policies regarding fair value measurement and group tax sharing systems.
- CyberAgent's net income for the first nine months of FY2023 plummeted 88.3% year-on-year to ¥2,304 million, while operating income fell 68.3% to ¥17,383 million.
- The Game Business experienced a 21.2% revenue decline, driven by a slowdown in major titles from subsidiaries such as Cygames.
- The Internet Advertisement segment achieved record net sales of ¥300,672 million, though its operating income dropped 30.2% due to upfront investment costs.
- Total consolidated net sales remained nearly flat at ¥534,397 million, representing a marginal 0.1% year-on-year increase.
- Profitability was heavily impacted by strategic investments in the Media business, specifically the costs associated with broadcasting the FIFA World Cup Qatar 2022 on ABEMA.
+1
CyberAgentMay 2025
Financial18 pages
Partial Correction to FY2023 Consolidated Financial Results [Japanese GAAP]
CyberAgent’s consolidated financial results for the fiscal year ended September 30, 2023, reveal a period of transition characterized by modest top-line growth alongside a sharp contraction in profitability. While net sales rose 1.3% to ¥719,451 million, operating income plummeted 66.9% to ¥22,351 million. This decline was primarily driven by the Game Business, where operating income fell 62.5% to ¥22,708 million due to reduced revenue from high-margin titles. Consequently, net income attributable to owners of the parent dropped significantly from ¥22,901 million in the previous year to ¥3,540 million, resulting in a decrease in basic earnings per share from ¥45.29 to ¥6.99.
The Media Business, anchored by the streaming platform ABEMA, demonstrated strong revenue growth of 25.8%, bolstered by high-profile events such as the FIFA World Cup Qatar 2022. However, the segment continued to operate at a loss of ¥12,873 million. Simultaneously, the Internet Advertisement Business expanded its market share but experienced a 26.3% decrease in profit. Despite these earnings pressures, the company maintained a robust liquidity position, ending the period with ¥201,780 million in cash and cash equivalents, supported by financing activities including the issuance of convertible bonds.
Operations remain heavily concentrated in the Japanese domestic market, which accounts for over 90% of total sales and assets. Looking toward the 2024 fiscal year, projections suggest a recovery with a forecasted 34.2% increase in operating income. This anticipated growth is predicated on a pipeline of new game releases and a narrowing of deficits within the Media Business. The transition to a group tax sharing system further reflects the evolving corporate structure across its five primary reportable segments: Media, Internet Advertisement, Game, Investment Development, and Other Businesses.
- CyberAgent’s FY2023 operating income plummeted 66.9% to ¥22,351 million, driven largely by a 62.5% profit decline in the Game Business due to lower revenue from high-margin titles.
- Net income attributable to owners of the parent dropped significantly to ¥3,540 million from ¥22,901 million in the previous year, reducing basic earnings per share from ¥45.29 to ¥6.99.
- The Media Business, anchored by ABEMA, grew revenue by 25.8% behind events like the FIFA World Cup Qatar 2022 but remained unprofitable with a segment loss of ¥12,873 million.
- Despite earnings pressures, the company maintained a strong liquidity position with ¥201,780 million in cash and cash equivalents, bolstered by the issuance of convertible bonds.
- The Internet Advertisement Business expanded its market share during the period but suffered a 26.3% decrease in segment profit.
CyberAgentMay 2025

Financial9 pages
Partial Correction to FY2024 First Quarter Consolidated Financial Results [Japanese GAAP]
CyberAgent, Inc. issued this corrective filing on May 15, 2025, to amend its consolidated financial results for the first quarter of fiscal year 2024, originally disclosed in January 2024. The primary purpose of the document is to provide a comprehensive restatement of numerical data following a separate notice regarding the submission of correction reports for past annual securities reports and financial statements. The scope of the data covers the three-month period ending December 31, 2023, and includes comparative figures for the same period in 2022.
The revised data shows that for the first quarter of FY2024, net sales reached ¥192,655 million, a 15.1% year-on-year increase. Operating income significantly improved to ¥5,864 million, recovering from an operating loss of ¥1,738 million in the prior year. Despite this operational recovery, the company reported a net loss attributable to owners of the parent of ¥892 million, though this was a substantial improvement over the ¥5,391 million loss recorded in the first quarter of FY2023. A notable extraordinary loss of ¥3,376 million for the amortization of goodwill impacted the bottom line.
Segment analysis reveals that the Media Business, driven by the ABEMA platform, saw sales grow 27.7% to ¥42,784 million while narrowing its operating loss to ¥991 million. The Internet Advertisement Business remained the largest contributor with ¥104,900 million in sales and ¥5,246 million in operating income. The Game Business reported sales of ¥45,043 million, up 10.1%, though operating income in that segment fell 32.9% to ¥3,495 million. As of December 31, 2023, total assets were ¥464,799 million with a shareholders' equity ratio of 28.2%. The company maintained its full-year forecast for FY2024, projecting net sales of ¥750,000 million and operating income of ¥30,000 million.
- CyberAgent reported Q1 FY2024 net sales of ¥192,655 million, a 15.1% year-on-year increase, with operating income recovering to ¥5,864 million from a ¥1,738 million loss in the prior year.
- Despite operational improvements, the company recorded a net loss attributable to owners of the parent of ¥892 million, heavily impacted by an extraordinary goodwill amortization loss of ¥3,376 million.
- The Internet Advertisement Business remains the primary revenue driver, contributing ¥104,900 million in sales and ¥5,246 million in operating income.
- The Game Business saw a 10.1% increase in sales to ¥45,043 million, but segment operating income declined by 32.9% to ¥3,495 million.
- The Media Business, anchored by the ABEMA platform, grew sales by 27.7% to ¥42,784 million while successfully narrowing its operating loss to ¥991 million.
CyberAgentMay 2025

Financial12 pages
Partial Correction to FY2024 Third Quarter Consolidated Financial Results [Japanese GAAP]
CyberAgent, Inc. issued a partial correction to its consolidated financial results for the third quarter of fiscal year 2024, ending September 30, 2024. This amendment follows a broader review of past annual securities reports and financial statements. The scope of the data covers the company’s performance across its primary business segments—Media, Internet Advertisement, Game, and Investment Development—primarily within the Japanese market for the nine-month period ending June 30, 2024.
The revised data reveals significant year-on-year growth. Net sales reached ¥597,485 million, an 11.8% increase, while operating income doubled to ¥34,833 million. Net income attributable to the parent company saw a substantial rise of 539.1%, totaling ¥14,726 million. This performance was driven by record-high sales in the Internet Advertisement business and a 10.4% revenue increase in the Game segment, fueled by successful new titles. The Media segment, which includes the ABEMA streaming service, significantly narrowed its operating losses from ¥12,394 million in the previous year to ¥489 million.
The financial position as of June 30, 2024, shows total assets of ¥492,195 million, supported by increased cash and deposits. A notable subsequent event included in the report is the July 2024 acquisition of a 72.5% stake in Nitroplus Co., Ltd. for approximately ¥16,683 million. This strategic move aims to strengthen CyberAgent’s intellectual property and content production capabilities, aligning with its goal of global expansion through the integration of technology and creative entertainment. The methodology follows Japanese GAAP, with corrections applied to previously disclosed numerical values to ensure reporting accuracy.
- CyberAgent reported a 539.1% increase in net income to ¥14,726 million for the nine-month period ending June 30, 2024, alongside an 11.8% rise in net sales to ¥597,485 million.
- Operating income for the period doubled to ¥34,833 million, bolstered by record-high sales in the Internet Advertisement business and a 10.4% revenue increase in the Game segment.
- The Media segment, anchored by the ABEMA streaming service, significantly reduced operating losses from ¥12,394 million in the previous year to ¥489 million.
- In July 2024, CyberAgent acquired a 72.5% stake in Nitroplus Co., Ltd. for approximately ¥16,683 million to bolster its intellectual property and content production capabilities.
- As of June 30, 2024, the company reported total assets of ¥492,195 million, supported by an increase in cash and deposits.
+1
CyberAgentMay 2025
Financial19 pages
Partial Correction to FY2024 Consolidated Financial Results (Japanese GAAP)
CyberAgent’s fiscal year 2024 consolidated financial results reveal a period of robust recovery and operational efficiency, characterized by an 11.4% increase in net sales to ¥801,236 million. Operating income surged by 79.3% to reach ¥40,083 million, while net income attributable to owners of the parent experienced a dramatic 351.3% jump to ¥15,977 million. This financial turnaround was largely propelled by the Media Business, which successfully narrowed its operating loss from ¥12,873 million to just ¥1,927 million, and a high-performing Internet Advertisement Business that consistently outpaced broader market growth.
The Game Business remains a vital profit driver, generating ¥195,985 million in net sales and a 34.6% increase in operating income to ¥30,569 million. This growth was fueled by the successful launch of new titles alongside the steady performance of existing smartphone applications. Geographically, the company’s operations remain heavily concentrated in Japan, with over 90% of sales and assets originating within the domestic market. Enhanced cash flow management was also evident, as net cash from operating activities more than doubled to ¥53,231 million, supporting a total equity balance of ¥250,504 million by year-end.
Looking toward fiscal year 2025, projections indicate continued upward momentum with a net sales target of ¥820,000 million. A primary strategic milestone for the upcoming period is the anticipated transition of the Media Business into a profitable segment. Reflecting this positive outlook and strengthened earnings per share—which rose from ¥6.99 to ¥31.56—the annual dividend is expected to increase to ¥17.00 per share. These results underscore a successful stabilization of core business segments and a clear trajectory toward sustained profitability across the entire portfolio.
- CyberAgent reported a strong fiscal 2024 with net sales rising 11.4% to ¥801,236 million and operating income surging 79.3% to ¥40,083 million.
- The Game Business remains a primary profit engine, contributing ¥195,985 million in net sales and achieving a 34.6% increase in operating income to ¥30,569 million.
- The Media Business significantly narrowed its operating loss from ¥12,873 million in the previous year to ¥1,927 million, with a strategic goal to reach profitability in fiscal 2025.
- Net income attributable to owners of the parent grew 351.3% to ¥15,977 million, while earnings per share increased from ¥6.99 to ¥31.56.
- The company’s operations are heavily concentrated in Japan, with over 90% of total sales and assets derived from the domestic market.
CyberAgentMay 2025