CyberAgent
Game Co.111 documents
Internet/media company, parent of Cygames (Granblue Fantasy, Uma Musume, Princess Connect). Game segment is major revenue driver.
Documents
Report37 pages
1Q FY2025 Presentation Material
The presentation outlines CyberAgent’s FY 2025 financial outlook, operational highlights, and strategic priorities across its Media & IP, Internet Advertising, and Game divisions. FY 2025 revenue is projected at ¥820 billion with operating profit of ¥42 billion, representing 24.9 % and 19.8 % of the year‑to‑date targets, respectively. First‑quarter results show a 5.6 % YoY sales increase to ¥203.8 billion and a 32.1 % rise in operating profit to ¥8.3 billion, driven largely by a 10.5 % lift in Media & IP sales (¥55.6 billion) and an 11.8 % growth in Internet Advertising sales (¥117.7 billion). The Game segment, however, posted a 15.1 % YoY decline to ¥38.2 billion and a 4.1 % drop in operating profit, attributed to slower releases despite strong performance of new titles.
Operating margins improved from 3.3 % in FY 2024 to 4.1 % in FY 2025, supported by a 32 % increase in operating income. SG&A expenses rose 4.4 % YoY to ¥45.7 billion, while cash deposits increased 11.3 % YoY to ¥205.6 billion, reflecting liquidity strengthening.
Strategically, the company is shifting from a Media‑only model to an integrated Media & IP business, aiming to generate global IPs through ABEMA and new production units such as CA Soa Inc. The medium‑to‑long‑term plan emphasizes investment in high‑profit IP content, game development, and advertising technology leveraging AI to enhance ad effectiveness. The presentation also lists a pipeline of over six new games for FY 2025, including international releases, and outlines organizational changes to support the expanded IP focus.
- CyberAgent reported a 5.6% YoY revenue increase to ¥203.8 billion and a 32.1% rise in operating profit to ¥8.3 billion for 1Q FY2025.
- The Game segment underperformed, recording a 15.1% YoY revenue decline to ¥38.2 billion and a 4.1% drop in operating profit due to a slower release cadence.
- Growth was primarily driven by the Media & IP segment, which saw a 10.5% sales increase to ¥55.6 billion, and the Internet Advertising segment, which grew 11.8% to ¥117.7 billion.
- The company is pivoting to an integrated Media & IP strategy, utilizing ABEMA and new production units like CA Soa Inc. to develop global intellectual property.
- CyberAgent plans to bolster its gaming portfolio with a pipeline of over six new titles in FY2025, including several international releases.
+1
CyberAgent
Financial10 pages
FY2025 Third Quarter Consolidated Financial Results: Japan
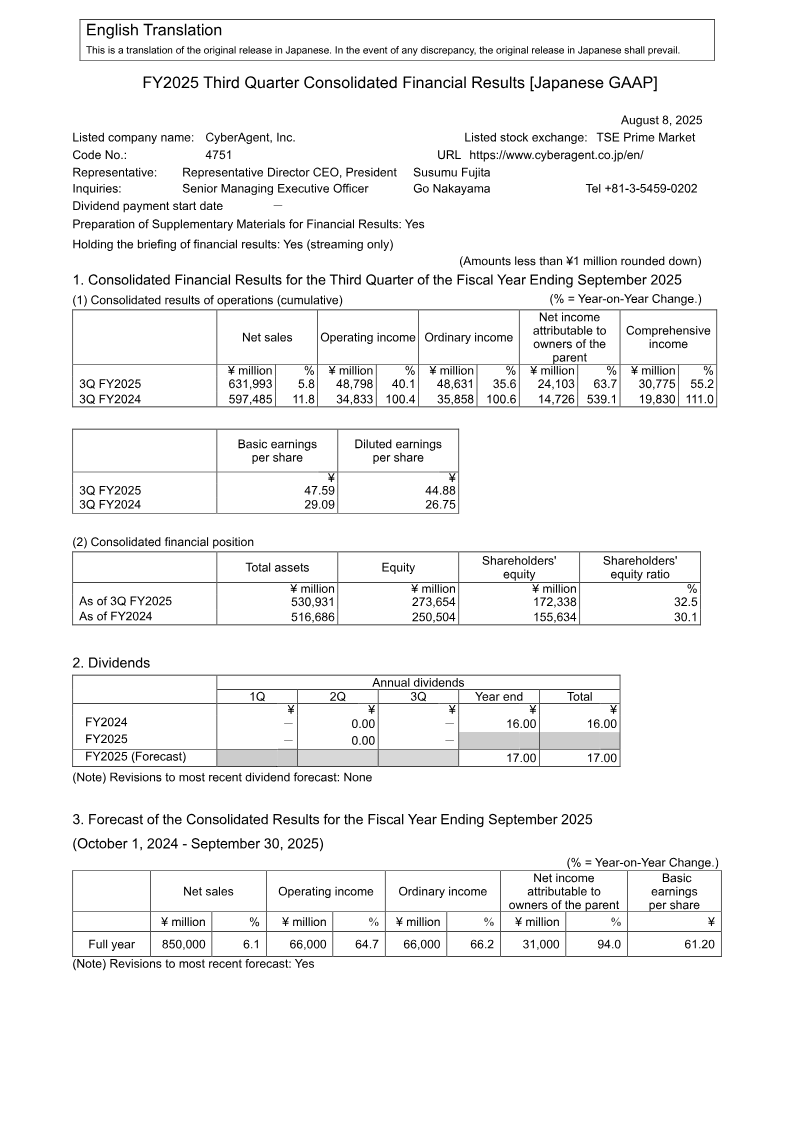
CyberAgent, Inc. reported consolidated financial results for the third quarter of fiscal year 2025 (ending September 30, 2025) under Japanese GAAP. Net sales rose 5.8 % YoY to ¥631,993 million, driven by a 14.1 % increase in the Media & IP Business and a 7.1 % rise in Internet Advertisement sales, while Game Business sales fell 7.1 %. Operating income increased 40.1 % to ¥48,798 million; ordinary income grew 35.6 % to ¥48,631 million, and net income attributable to owners of the parent surged 63.7 % to ¥24,103 million. Basic earnings per share reached ¥47.59 (diluted ¥44.88). Total assets climbed to ¥530,931 million, equity rose to ¥273,654 million, and the equity ratio improved to 32.5 %. The company forecast full‑year FY2025 net income of ¥850,000 million (up 6.1 %) and operating income of ¥66,000 million (up 64.7 %). Dividend policy remains unchanged with a forecast of ¥17.00 million per share for FY2025.
Segment analysis shows Media & IP as the largest contributor, with operating income of ¥7,008 million; Internet Advertisement posted a 4.6 % YoY decline in operating income due to higher personnel costs; Game Business achieved a 31.0 % YoY rise in operating income after a successful console title launch; Investment Development recorded a modest operating loss. Impairment losses totaled ¥3,892 million across segments, primarily in Internet Advertisement and Game. The company’s cash position remained stable at ¥209 billion, while short‑term debt increased to ¥5.6 billion following the elimination of convertible bond current portions. No significant changes in accounting policies or segment structure were noted beyond the reclassification of “Other Businesses” into Media & IP. The report also announced the establishment of a new venture‑capital fund, CA Startups Internet Fund No. 4, which will become a specified subsidiary once fully funded.
- CyberAgent reported a 40.1% increase in operating income to ¥48,798 million and a 63.7% surge in net income to ¥24,103 million for the third quarter of FY2025.
- Consolidated net sales grew 5.8% year-over-year to ¥631,993 million, fueled by a 14.1% rise in Media & IP and a 7.1% increase in Internet Advertisement, despite a 7.1% decline in Game Business sales.
- The Game Business segment achieved a 31.0% year-over-year rise in operating income, attributed to the successful launch of a console title, even as the company recorded ¥3,892 million in total impairment losses across segments.
- Full-year FY2025 forecasts project net sales of ¥850,000 million (up 6.1%) and operating income of ¥66,000 million (up 64.7%).
- The Internet Advertisement segment experienced a 4.6% year-over-year decline in operating income, primarily due to rising personnel costs.
+1
CyberAgent
Financial19 pages
FY2025 Consolidated Financial Results: Japan
FY2025 Consolidated Financial Results [Japanese GAAP] Listed company name: CyberAgent, Inc.(herein referred as the "Company") Listed stock exchange: TSE Prime Market Code No.: 4751 URL https://www.cyberagent.co.jp/ en/ Representative: Representative Director CEO, President Susumu Fujita Inquiries: Senior Managing Executive Officer ...
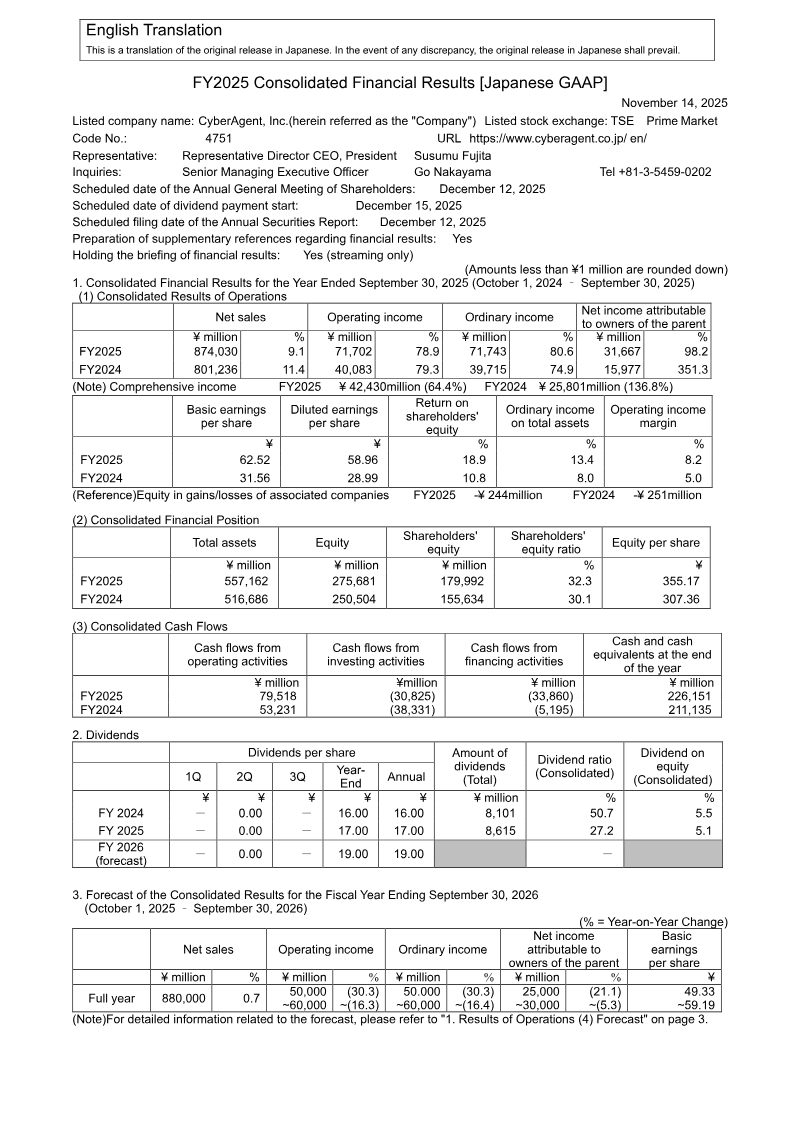
- CyberAgent, Inc. reported strong FY2025 consolidated financial results (October 1, 2024 – September 30, 2025), with net sales increasing 9.1% year-on-year to ¥874,030 million, marking 28 consecutive periods of revenue growth.
- Operating income surged 78.9% to ¥71,702 million, driven by the Media & IP business returning to profitability after 10 years and significant profit increases in the Game business.
- Net income attributable to owners of the parent nearly doubled, increasing 98.2% to ¥31,667 million in FY2025.
- The company forecasts a slowdown in growth for FY2026 (October 1, 2025 – September 30, 2026), projecting net sales to increase by only 0.7% to ¥880,000 million, and operating income to decrease by 30.3% to 50,000-60,000 million yen.
- Cash and cash equivalents increased by ¥15,016 million to ¥226,151 million by the end of FY2025, primarily due to strong operating cash flow of ¥79,518 million.
+1
CyberAgent
Report1 pages
Quarterly Transition by Business Segment: Japan
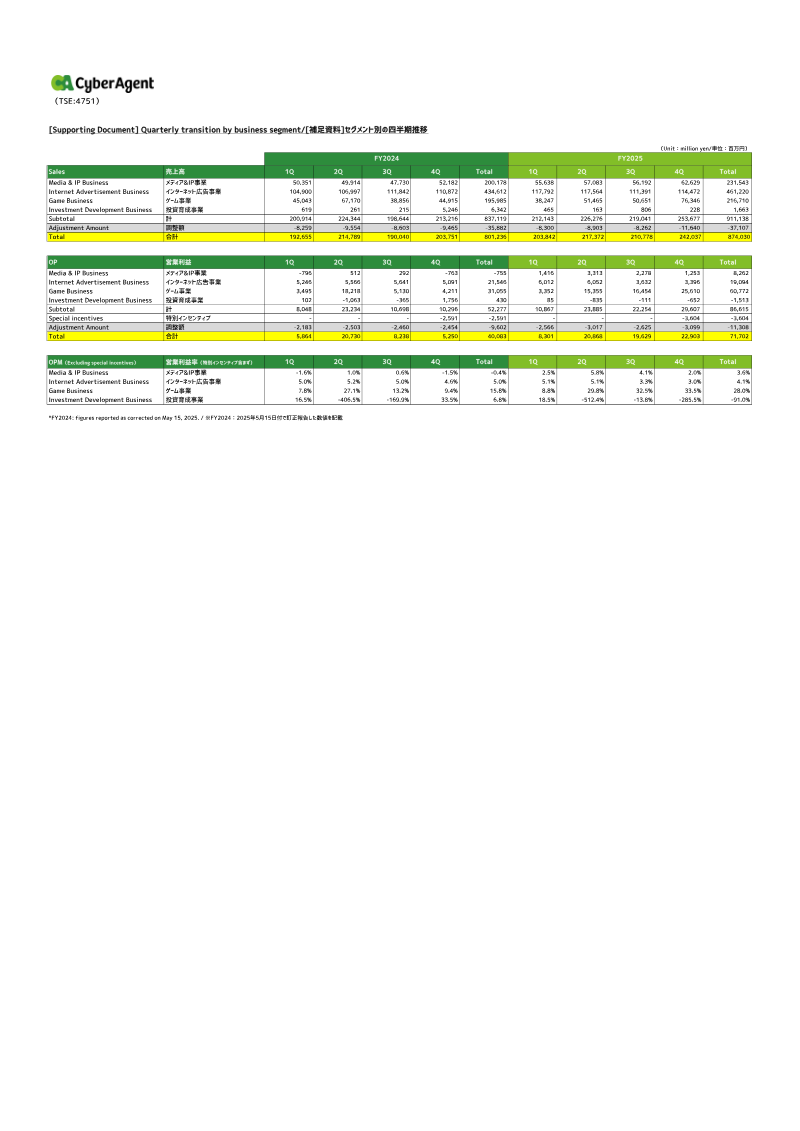
The quarterly transition analysis for Japan’s business segments presents detailed financial performance for FY2024 and FY2025, focusing on Media & IP, Internet Advertisement, Game, and Investment Development divisions. Sales figures reveal that the Internet Advertisement Business consistently leads with a FY2024 total of ¥434,612 million and a FY2025 total of ¥461,220 million. The Game Business shows the most volatility, peaking in Q2 FY2024 at ¥67,170 million before declining to ¥38,856 million in Q3. Media & IP sales remain relatively stable around ¥50–52 billion per quarter, while Investment Development remains a minor contributor with totals under ¥7 billion.
Operating profit (OP) highlights divergent profitability across segments. The Game Business delivers the highest OP, reaching ¥31,055 million in Q1 FY2024 and sustaining strong quarterly results thereafter. Internet Advertisement maintains steady OP around ¥5–6 billion each quarter, whereas Media & IP oscillates between losses and modest gains, culminating in a FY2024 total OP of ¥8,262 million. Investment Development experiences significant swings, with a notable loss in Q2 FY2024 but a recovery to ¥1,756 million in Q4.
Operating profit margins (OPM) excluding special incentives illustrate segment efficiency. Game Business achieves the highest margin, peaking at 33.5% in Q3 FY2024 and maintaining a FY2025 average of 28%. Internet Advertisement sustains margins around 5%, while Media & IP remains near break‑even, fluctuating between –1.6% and 5.8%. Investment Development shows extreme volatility, with a negative margin of –406.5% in Q2 FY2024 and a positive 33.5% in Q4, resulting in an overall FY2024 margin of 3.6%.
The data cover the Japanese market over two fiscal years, with quarterly granularity and corrections applied as of May 15 2025. The analysis relies on internal financial statements, presenting a comprehensive view of segment performance and profitability trends.
- The Game Business is the company's most profitable segment, maintaining a FY2025 average operating profit margin of 28% and peaking at 33.5% in Q3 FY2024.
- Internet Advertisement is the largest revenue generator, growing from ¥434,612 million in FY2024 to ¥461,220 million in FY2025, though it operates on thin margins of approximately 5%.
- Game Business revenue is highly volatile, experiencing a sharp decline from a peak of ¥67,170 million in Q2 FY2024 to ¥38,856 million in Q3 FY2024.
- Media & IP remains a stable but low-margin segment, with quarterly sales consistently between ¥50 billion and ¥52 billion and operating profit margins fluctuating between –1.6% and 5.8%.
- Investment Development is a minor contributor with annual revenue under ¥7 billion and extreme performance volatility, ranging from a –406.5% margin in Q2 FY2024 to a 33.5% margin in Q4 FY2024.
+1
CyberAgent
Financial9 pages
FY2026 First Quarter Consolidated Financial Results: Japan
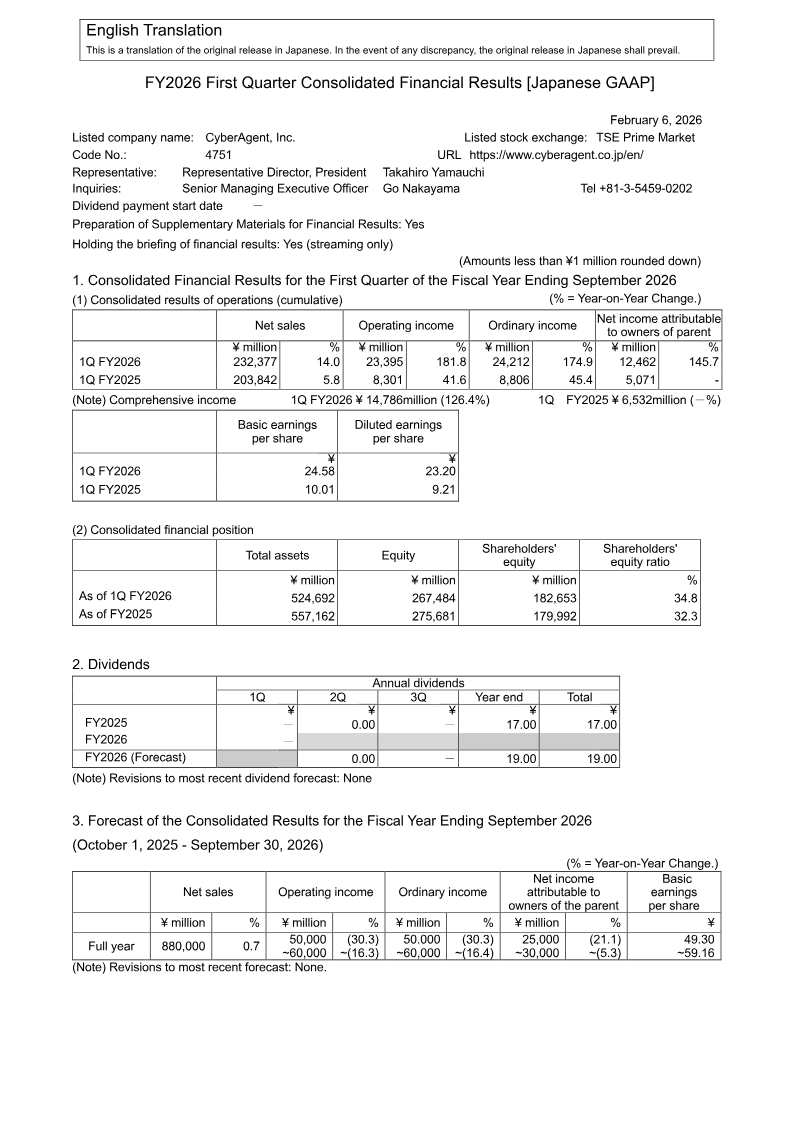
CyberAgent, Inc. reported a strong first‑quarter performance for FY2026, with net sales rising 14 % YoY to ¥232.4 billion and operating income surging 182 % to ¥23.4 billion, driven by significant gains in its Media & IP and Game segments. The Media & IP business generated ¥62.6 billion in sales, up 12.5 %, and operating income of ¥4.9 billion, largely thanks to the profitable quarterly results of AbemaTV Inc., a key subsidiary. The Game segment posted net sales of ¥64.7 billion, up 69 % YoY, and operating income of ¥17.7 billion, a 427 % increase, reflecting strong performance of existing titles and overseas expansion. In contrast, the Internet Advertisement business saw a 2.7 % sales decline to ¥114.6 billion, with operating income falling 27 %. The Investment Development segment recorded a net loss of ¥552 million after a prior year profit.
Total assets decreased to ¥524.7 billion, mainly due to cash outflows for taxes and dividends, while equity fell to ¥267.5 billion, reflecting reduced non‑controlling interests from subsidiary dividends. Net income attributable to owners of parent reached ¥12.5 billion, a 146 % increase, and basic earnings per share climbed to ¥24.58.
The FY2026 full‑year forecast remains unchanged, projecting net sales of ¥880 billion and operating income of ¥50 billion (a 30 % decline YoY). The company’s guidance acknowledges potential risks that could materially affect actual results.
- CyberAgent reported a strong Q1 FY2026 with net sales rising 14% YoY to ¥232.4 billion and operating income surging 182% to ¥23.4 billion.
- The Game segment was the primary growth driver, with net sales increasing 69% to ¥64.7 billion and operating income jumping 427% to ¥17.7 billion due to successful existing titles and overseas expansion.
- The Media & IP segment contributed ¥62.6 billion in sales (up 12.5%) and ¥4.9 billion in operating income, bolstered by the profitability of subsidiary AbemaTV Inc.
- The Internet Advertisement business underperformed, with sales declining 2.7% to ¥114.6 billion and operating income falling 27%.
- Net income attributable to owners of the parent reached ¥12.5 billion, a 146% increase, resulting in basic earnings per share of ¥24.58.
+1
CyberAgent
Report41 pages
Presentation Material: Q1 FY2026
The future information, such as earnings forecast, written in this document is based on our expectations and assumptions as of the date the forecast was made. Our actual results could differ materially from those described in this forecast because of various risks and uncertainties. 1. Summary (October - December 2025) 4. Internet Advertisement Business 6.
- For Q1 FY2026, overall sales increased by 14.0% year-over-year to 232.3 billion yen, and operating profit surged 2.8x year-over-year to 23.3 billion yen, marking a strong start to the fiscal year.
- The Game business was a primary driver of growth, with sales up 69.2% year-over-year to 64.7 billion yen and operating profit increasing 5.3x year-over-year to 17.6 billion yen, fueled by existing titles and global expansion.
- The Media & IP business also contributed significantly, achieving a 12.5% year-over-year increase in sales to 62.6 billion yen and a 3.5x year-over-year increase in operating profit to 4.9 billion yen.
- Net income for Q1 FY2026 rose 2.5 times year-over-year to 12.4 billion yen.
- Ad Sales experienced a slight decrease of 2.7% year-over-year to 114.6 billion yen due to the loss of a large client, though the trend is showing gradual improvement.
+2
CyberAgent
Financial1 pages
Quarterly Transition by Business Segment
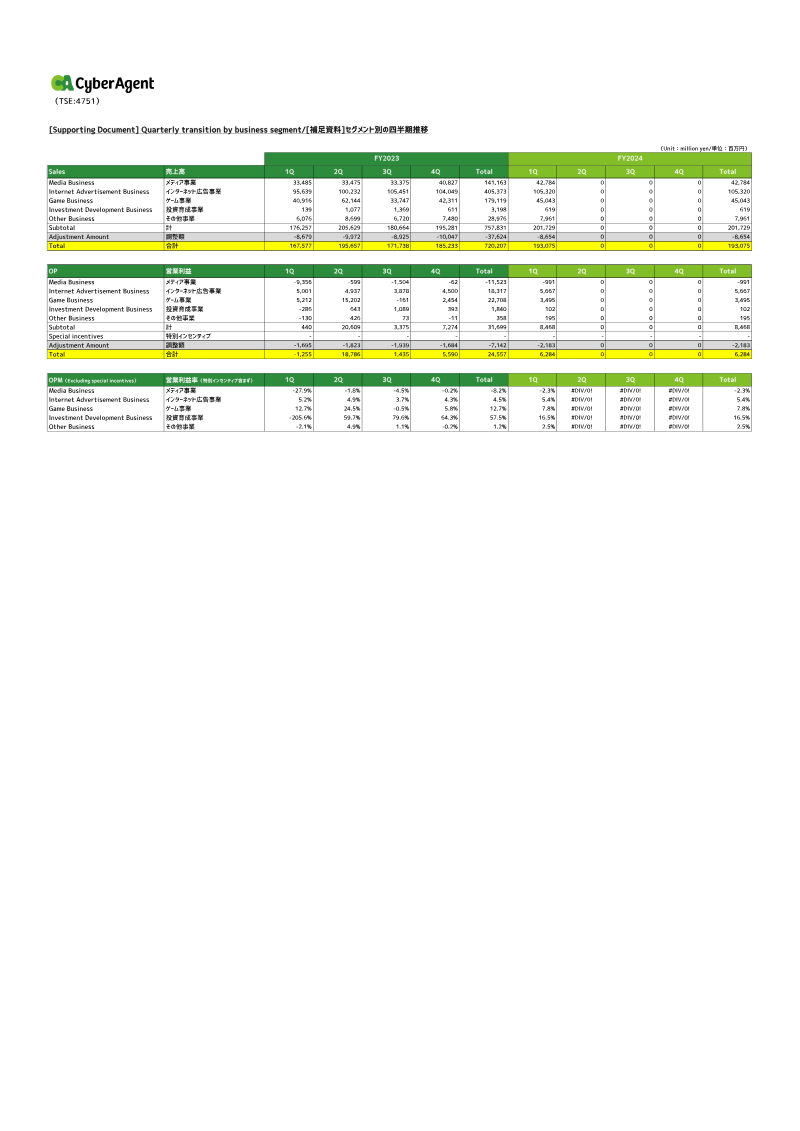
CyberAgent’s financial performance for the first quarter of fiscal year 2024 demonstrates a significant recovery in profitability compared to the same period in the previous year. Total net sales reached 193.07 billion yen, representing a year-over-year increase from the 167.57 billion yen recorded in the first quarter of 2023. Most notably, the consolidated operating income swung from a loss of 1.25 billion yen in the prior year’s first quarter to a profit of 6.28 billion yen, signaling a stabilized financial trajectory across the company’s diverse business segments.
The Internet Advertisement Business remains the primary revenue driver, contributing 105.32 billion yen in sales and 5.66 billion yen in operating profit during the first quarter. While the Media Business continues to operate at a loss, its performance has improved substantially; the segment reduced its operating loss from 9.35 billion yen in the first quarter of 2023 to just 991 million yen in the current period. This improvement is reflected in the operating profit margin for the Media segment, which narrowed from negative 27.9 percent to negative 2.3 percent.
The Game Business experienced a moderate increase in revenue, posting 45.04 billion yen for the quarter compared to 40.91 billion yen a year earlier. However, the segment's operating profit of 3.49 billion yen and margin of 7.8 percent represent a decline from the 5.21 billion yen and 12.7 percent margin seen in the first quarter of 2023. Despite this contraction in game-related margins, the overall corporate performance was bolstered by the Investment Development and Other Business segments, both of which remained profitable. The data covers the Japanese market and reflects the transition from the full fiscal year 2023 through the initial quarter of 2024.
- CyberAgent achieved a significant financial turnaround in Q1 2024, swinging from a 1.25 billion yen operating loss in Q1 2023 to a 6.28 billion yen profit on total net sales of 193.07 billion yen.
- The Internet Advertisement Business remains the company's primary revenue engine, generating 105.32 billion yen in sales and 5.66 billion yen in operating profit.
- The Media Business significantly narrowed its losses, reducing its operating deficit from 9.35 billion yen in Q1 2023 to 991 million yen, improving the segment margin from -27.9% to -2.3%.
- The Game Business saw revenue grow to 45.04 billion yen from 40.91 billion yen year-over-year, yet operating profit declined to 3.49 billion yen with a margin contraction from 12.7% to 7.8%.
- Overall corporate profitability in Q1 2024 was supported by the Investment Development and Other Business segments, both of which maintained positive operating results.
+1
CyberAgentFeb 2026
Financial3 pages
FY2024 Full Year Earnings Release Q&A
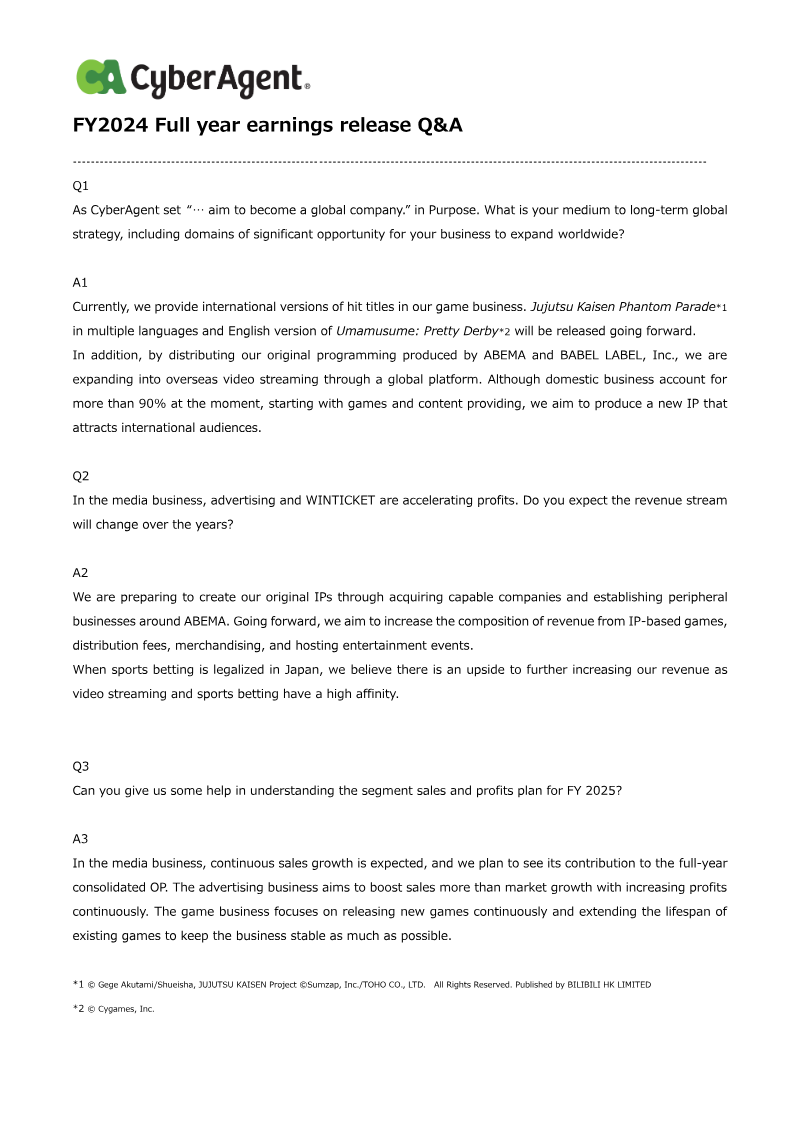
CyberAgent is prioritizing a transition toward global expansion and diversified revenue streams as it enters the 2025 fiscal year. While domestic operations currently account for over 90% of total business, the strategic focus is shifting toward internationalizing core intellectual properties. This expansion is led by the game business, specifically through the multi-language release of Jujutsu Kaisen Phantom Parade and the upcoming English version of Umamusume: Pretty Derby. By leveraging original programming from ABEMA and BABEL LABEL, the company intends to distribute content via global platforms to cultivate a worldwide audience and establish new, internationally recognized IPs.
The media segment is evolving beyond its current reliance on advertising and the WINTICKET platform. Future growth is expected to stem from a broader ecosystem including distribution fees, merchandising, and live entertainment events. There is also significant long-term potential in the synergy between video streaming and sports betting, with the company positioning itself to capitalize on any future legalization of sports betting in Japan. This diversification strategy aims to stabilize the media business and ensure it contributes consistently to consolidated operating profit.
For the 2025 fiscal year, the financial outlook remains focused on steady growth across three primary segments. The advertising business is projected to outperform general market growth while maintaining profitability. In the game business, the strategy centers on a dual approach of launching new titles while extending the operational lifespan of existing hits to ensure stability. Overall, the company is moving toward a model where IP-based revenue and peripheral businesses around the ABEMA platform drive long-term value alongside traditional advertising and gaming operations.
- CyberAgent is shifting its strategic focus toward international expansion, as domestic operations currently account for over 90% of total business.
- The game segment is driving global growth through the multi-language release of Jujutsu Kaisen Phantom Parade and the upcoming English version of Umamusume: Pretty Derby.
- The media segment is diversifying revenue beyond advertising and the WINTICKET platform by expanding into distribution fees, merchandising, and live entertainment.
- CyberAgent is positioning its ABEMA platform to capitalize on the potential future legalization of sports betting in Japan to create long-term synergy with video streaming.
- The company’s 2025 fiscal year strategy for the game business relies on a dual approach of launching new titles while extending the operational lifespan of existing hits.
+1
CyberAgentFeb 2026
Financial41 pages
Q1 FY2026 Presentation Material
CyberAgent achieved record-high consolidated sales of 232.3 billion yen and a nearly threefold increase in operating profit during the first quarter of fiscal year 2026. This performance was primarily catalyzed by the Game and Media & IP segments, which offset a minor decline in internet advertising revenue resulting from the loss of a major client. By reaching nearly 47% of its annual operating profit target within the first three months, the organization has established a robust financial trajectory for the remainder of the fiscal year.
The Game business served as the primary engine for growth, recording a 69.2% year-over-year increase in sales and a fivefold surge in operating profit. This success was largely driven by the global performance of high-profile titles such as Jujutsu Kaisen Phantom Parade. Looking forward, the strategic focus remains on international expansion and the development of a diverse pipeline, including the North American launch of Umamusume: Pretty Derby and upcoming releases like hololive Dreams and Shadowverse: Worlds Beyond. These efforts are supported by extensive collaborative partnerships with major industry entities such as Shueisha, KADOKAWA, and Bandai Namco Entertainment.
Simultaneously, the Media & IP segment reached a significant milestone as AbemaTV achieved independent profitability. The company is increasingly integrating animation studios and leveraging generative artificial intelligence to automate video advertisement production and optimize for emerging search technologies. This synergy between intellectual property development and technological innovation underscores a broader strategy to diversify revenue streams and solidify a global presence across the digital entertainment landscape.
- CyberAgent achieved record-high consolidated sales of 232.3 billion yen in Q1 FY2026, reaching nearly 47% of its annual operating profit target in the first three months.
- The Game segment drove performance with a 69.2% year-over-year sales increase and a fivefold surge in operating profit, largely fueled by the global success of Jujutsu Kaisen Phantom Parade.
- AbemaTV reached a key milestone by achieving independent profitability within the Media & IP segment.
- Future growth strategy focuses on international expansion, including the North American launch of Umamusume: Pretty Derby and the upcoming releases of hololive Dreams and Shadowverse: Worlds Beyond.
- The company is leveraging partnerships with major entities like Shueisha, KADOKAWA, and Bandai Namco Entertainment to support its game development pipeline.
+1
CyberAgentFeb 2026
Financial9 pages
FY2026 First Quarter Consolidated Financial Results [Japanese GAAP]
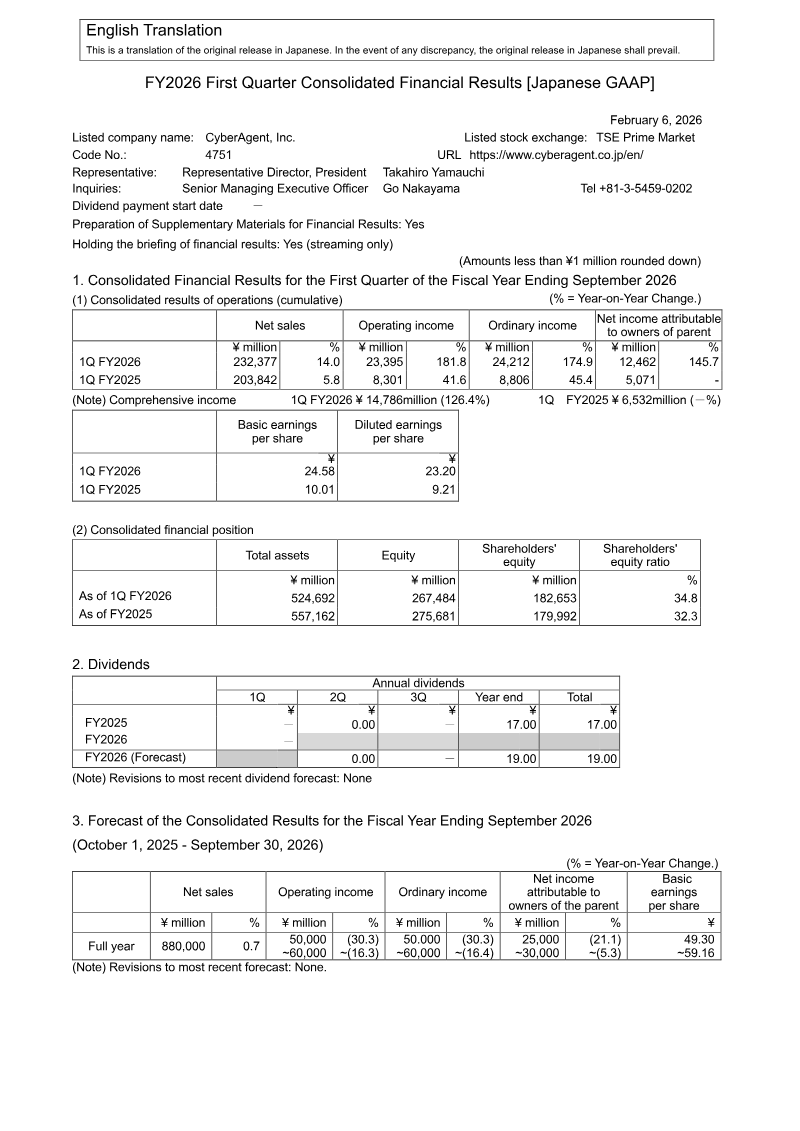
CyberAgent’s consolidated financial results for the first quarter of fiscal year 2026, covering the period from October 1, 2025, to December 31, 2025, demonstrate significant growth in revenue and profitability. Net sales rose 14.0% year-on-year to ¥232.3 billion, while operating income surged 181.8% to ¥23.3 billion. This performance was primarily driven by record-high results in the Media & IP and Game segments. Notably, the subsidiary AbemaTV Inc. achieved its first quarterly operating profit since its 2015 inception, contributing to a 246.1% increase in Media & IP segment income.
The Game Business served as a major growth engine, with net sales increasing 69.2% to ¥64.7 billion and operating income rising 427.2% to ¥17.6 billion, fueled by strong existing titles and international expansion. Conversely, the Internet Advertisement Business saw a 2.7% decline in sales and a 27.2% drop in operating income following the loss of a major client. The Investment Development Business also underperformed, reporting an operating loss of ¥552 million.
Geographically focused on the Japanese market with expanding global IP interests, the report utilizes Japanese GAAP to detail the company's financial position. Total assets decreased to ¥524.6 billion, largely due to tax and dividend payments. Despite the strong first-quarter start, the full-year forecast remains unchanged, projecting net sales of ¥880 billion. The outlook suggests a potential year-on-year decline in annual operating income, ranging from 16.3% to 30.3%, as the company balances proactive content investment with fluctuating segment performances.
- CyberAgent achieved a 14.0% year-on-year increase in net sales to ¥232.3 billion and a 181.8% surge in operating income to ¥23.3 billion for Q1 FY2026.
- The Game Business segment acted as a primary growth driver, with net sales rising 69.2% to ¥64.7 billion and operating income jumping 427.2% to ¥17.6 billion.
- AbemaTV Inc. reached a milestone by recording its first quarterly operating profit since its 2015 inception, helping drive a 246.1% increase in Media & IP segment income.
- The Internet Advertisement Business experienced a downturn, with sales declining 2.7% and operating income falling 27.2% due to the loss of a major client.
- Despite a strong first quarter, CyberAgent maintained its full-year net sales forecast of ¥880 billion while projecting a potential annual operating income decline of 16.3% to 30.3%.
CyberAgentFeb 2026
Financial53 pages
FY2025 Presentation Material
CyberAgent achieved record consolidated net sales of 874 billion yen for the 2025 fiscal year, marking nearly three decades of uninterrupted growth. This performance was characterized by a significant recovery in profitability, as operating income surged nearly 79% to 71.7 billion yen. The primary catalyst for this expansion was the gaming segment, which saw operating income nearly double due to the success of several new hit titles and a six-fold increase in overseas sales following aggressive global expansion. Furthermore, the Media and IP segment reached a major milestone by achieving profitability for the first time since the launch of the ABEMA streaming service, which saw record viewership and a doubling of active users for its original programming.
While the gaming and media sectors flourished, the advertising division experienced a 14% decline in operating profit. This contraction resulted from heavy internal investments in artificial intelligence intended to drive long-term structural changes. Despite these costs, overall group sales grew by over 6%, supported by the establishment of new animation studios and expanded global distribution partnerships. The company’s strategic focus remains on diversifying its IP portfolio and leveraging external payment methods to improve margins within its digital storefronts.
Looking toward the 2026 fiscal year, the outlook remains stable with projected sales of 880 billion yen, though operating income is expected to moderate to between 50 and 60 billion yen. This conservative forecast accounts for the inherent volatility of the gaming market and the high performance bar set by recent hits. Additionally, the organization is preparing for a significant leadership transition scheduled for late 2025, during which founder Susumu Fujita will transition to Chairman, and Takahiro Yamauchi will assume the role of President to lead the next phase of the company's evolution.
- CyberAgent achieved record consolidated net sales of 874 billion yen in FY2025, with operating income surging 79% to 71.7 billion yen.
- The gaming segment served as the primary growth driver, nearly doubling its operating income behind new hit titles and a six-fold increase in overseas sales.
- The Media and IP segment reached profitability for the first time since the launch of the ABEMA streaming service, which saw record viewership and a doubling of active users for original programming.
- The advertising division experienced a 14% decline in operating profit due to heavy internal investments in artificial intelligence to drive long-term structural changes.
- CyberAgent projects FY2026 sales of 880 billion yen, with operating income expected to moderate to between 50 and 60 billion yen due to gaming market volatility.
+1
CyberAgentNov 2025
Financial19 pages
FY2025 Consolidated Financial Results [Japanese GAAP]
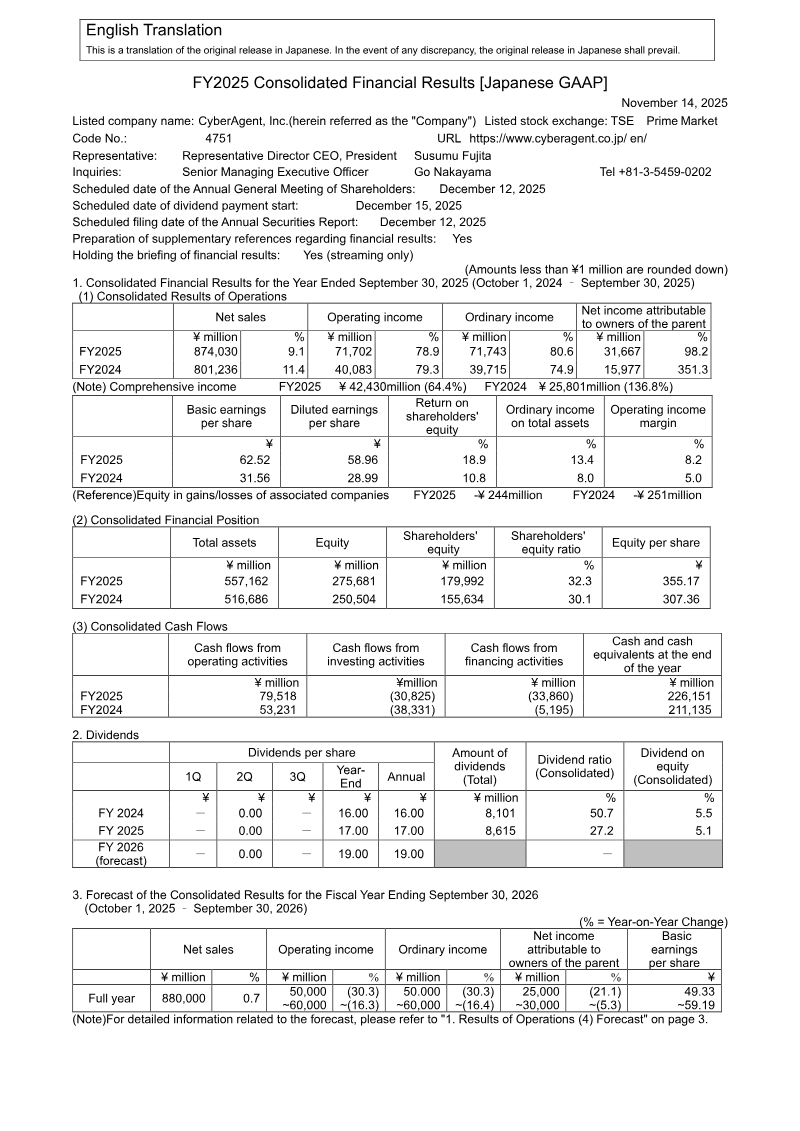
CyberAgent achieved a significant financial recovery during the 2025 fiscal year, characterized by a 9.1% increase in net sales to ¥874,030 million and a 78.9% surge in operating income to ¥71,702 million. This performance was underpinned by the Media & IP segment returning to profitability for the first time in a decade, generating ¥7.29 billion in operating income. The Game Business served as the primary engine for growth, with its operating income nearly doubling to ¥60.06 billion. This success in the gaming sector was attributed to aggressive overseas expansion and the adoption of high-margin external payment methods, which more than offset a ¥727 million extraordinary loss related to a patent infringement settlement between subsidiary Cygames and Konami Digital Entertainment.
The company’s financial position strengthened considerably over the period, with net income attributable to the parent doubling to ¥31.67 billion and cash flows from operating activities rising to ¥79,518 million. Strategic capital management included a ¥20,000 million redemption of convertible bonds and the acquisition of subsidiary shares. To better leverage synergies surrounding the ABEMA platform, the corporate structure was reorganized to integrate secondary operations into the newly designated Media & IP Business segment.
Looking toward the 2026 fiscal year, the outlook remains cautious despite the recent momentum. While consolidated net sales are projected to grow modestly to ¥880,000 million, operating income is expected to contract to a range between ¥50,000 and ¥60,000 million. This forecast suggests a period of reinvestment or market stabilization following the exceptional gains realized in the gaming and media sectors during the previous year. The results reflect a consolidated Japanese market focus with increasing international contributions from the gaming portfolio.
- CyberAgent's operating income surged 78.9% to ¥71,702 million in FY2025, driven primarily by the Game Business, which nearly doubled its operating income to ¥60,06 billion.
- The Media & IP segment achieved its first annual profit in a decade, contributing ¥7.29 billion in operating income following a corporate reorganization to integrate ABEMA-related operations.
- Consolidated net sales grew 9.1% to ¥874,030 million, while net income attributable to the parent doubled to ¥31.67 billion.
- Growth in the gaming sector was fueled by aggressive overseas expansion and the adoption of high-margin external payment methods, successfully offsetting a ¥727 million patent infringement settlement between Cygames and Konami Digital Entertainment.
- The company strengthened its financial position by generating ¥79,518 million in operating cash flow and executing a ¥20,000 million redemption of convertible bonds.
CyberAgentNov 2025