CyberAgent
Game Co.111 documents
Internet/media company, parent of Cygames (Granblue Fantasy, Uma Musume, Princess Connect). Game segment is major revenue driver.
Documents
Report34 pages
1Q FY2024 Presentation Material
The presentation outlines CyberAgent’s fiscal‑year 2024 first‑quarter performance, emphasizing a robust rebound across its three core businesses—Internet advertising, media (ABEMA), and game development. Consolidated sales reached ¥193 billion, up 15.2 % year‑over‑year, while operating profit climbed to ¥6.28 billion, a 7.5‑point increase from the prior year’s loss. The advertising arm delivered ¥105.3 billion in revenue, up 10.1 % YoY, and an operating profit of ¥5.6 billion, reflecting a 13.3 % YoY gain and sustained improvement in operating‑margin efficiency (OPM). Media operations posted ¥42.7 billion, a 27.8 % YoY rise, though operating loss narrowed to ¥0.9 billion, driven by reduced losses in ABEMA‑related activities. Game sales hit ¥45.0 billion, up 10.1 % YoY and 6.5 % QoQ; operating loss fell to ¥3.4 billion, a 32.9 % YoY decline and 42.4 % QoQ improvement, thanks to a new hit title.
Financial statements show total assets of ¥468.7 billion and shareholders’ equity of ¥129.0 billion, with cash deposits at ¥184.8 billion. SG&A expenses rose 8.1 % YoY to ¥43.7 billion, while headcount increased to 7,336 employees.
Strategically, the company targets a “growth phase” with new digital ad platforms (e.g., ANA Moment Ads), continued investment in ABEMA, and a pipeline of high‑quality games such as “Jujutsu Kaisen Phantom Parade.” Forecasts indicate that FY2024 operating profit will reach ¥30 billion, with sales projected at ¥750 billion. The presentation stresses a commitment to enhancing monetization, AI‑driven advertising efficiency, and extending game lifecycles to secure long‑term profitability.
- CyberAgent returned to profitability in 1Q FY2024 with ¥6.28 billion in operating profit, a significant recovery from the prior year's loss, on consolidated sales of ¥193 billion.
- The company projects full-year FY2024 performance to reach ¥750 billion in sales and ¥30 billion in operating profit.
- The game development segment saw sales rise 10.1% YoY to ¥45.0 billion, with operating losses narrowing by 32.9% YoY to ¥3.4 billion, largely driven by the success of the new title 'Jujutsu Kaisen Phantom Parade.'
- The internet advertising business remains the primary revenue driver, contributing ¥105.3 billion in revenue—a 10.1% YoY increase—and ¥5.6 billion in operating profit.
- Media operations, anchored by ABEMA, grew revenue by 27.8% YoY to ¥42.7 billion, successfully narrowing the segment's operating loss to ¥0.9 billion.
+2
CyberAgent

Financial11 pages
Partial Correction to FY2024 Second Quarter Consolidated Financial Results: Japan
CyberAgent, Inc. issued a partial correction to its FY2024 second‑quarter consolidated financial results under Japanese GAAP, released on May 15 2025. The correction adjusts several numerical figures from the original April 24, 2024 filing but does not alter the overall financial position or key performance trends. Net sales for the cumulative second quarter rose 12.3 % year‑on‑year to ¥407,444 million, while operating income increased 61.4 % to ¥26,595 million and ordinary income grew 60.6 % to ¥27,028 million. Net income attributable to owners of the parent surged 346.5 % to ¥9,105 million, reflecting a significant improvement over the ¥2,039 million reported for 2Q FY2023. Basic earnings per share climbed from ¥4.03 to ¥17.98, and diluted EPS rose from ¥3.65 to ¥16.54.
Total assets reached ¥495,553 million, up ¥20,330 million from the prior year, driven mainly by increases in trade receivables and contract assets. Equity expanded to ¥235,219 million, a rise of ¥6,769 million, largely due to retained earnings. Cash and cash equivalents increased by ¥3,795 million to ¥205,575 million, supported by stronger operating cash flow of ¥23,008 million versus ¥14,080 million in 2Q FY2023. Financing cash flow turned negative with an outflow of ¥8,429 million, largely from dividend payments.
Segment analysis shows continued growth in the Internet advertisement and game businesses, with media operations improving from an operating loss of ¥10,605 million to a smaller loss of ¥829 million. The investment development segment recorded an operating loss of ¥960 million, a reversal from prior profitability. Forecasts for FY2024 remain unchanged, with net income projected at ¥750,000 million and operating income at ¥30,000 million. The company emphasizes that the correction does not affect its overall financial health or strategic outlook, and it will disclose any future revisions promptly.
- CyberAgent reported strong growth for 2Q FY2024, with net sales rising 12.3% to ¥407,444 million and operating income increasing 61.4% to ¥26,595 million.
- Net income attributable to owners of the parent surged 346.5% year-on-year to ¥9,105 million, resulting in basic earnings per share rising from ¥4.03 to ¥17.98.
- The media operations segment significantly reduced its operating loss from ¥10,605 million in 2Q FY2023 to ¥829 million in 2Q FY2024.
- Operating cash flow improved to ¥23,008 million compared to ¥14,080 million in the prior year, while cash and cash equivalents reached ¥205,575 million.
- The company maintained its FY2024 full-year forecast, projecting net sales of ¥750,000 million and operating income of ¥30,000 million.
CyberAgent
Financial9 pages
FY2024 Second Quarter Consolidated Financial Results: Japan
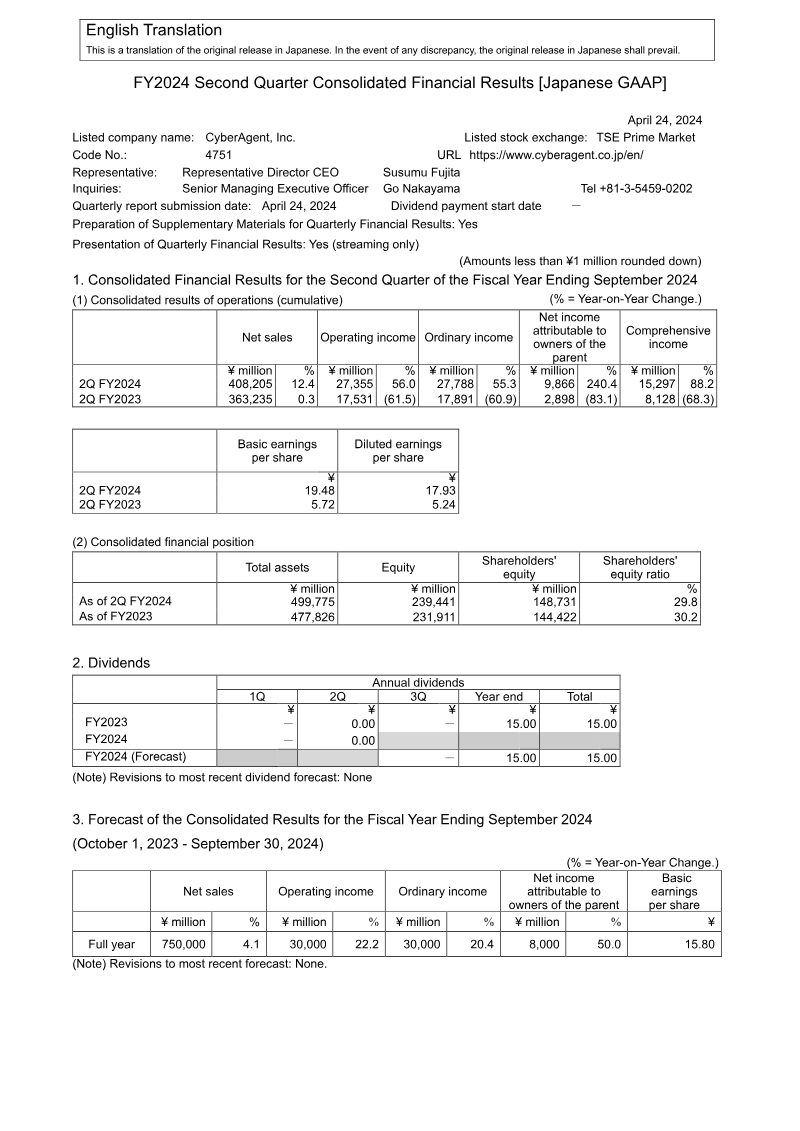
CyberAgent’s FY2024 second‑quarter results show a robust 12.4 % rise in net sales to ¥408,205 million, driven by growth across its media, internet advertising, and game segments. Operating income surged 56 % to ¥27,355 million, while ordinary income climbed 55 % to ¥27,788 million. Net income attributable to the parent ballooned 240 % to ¥9,866 million, with earnings per share rising from ¥5.72 (basic) to ¥19.48 in the quarter.
Segment performance highlights include a 26.8 % increase in ABEMA‑related media sales to ¥84,880 million, an 8.6 % rise in internet advertising revenue to ¥212,658 million, and an 8.9 % rise in game sales to ¥112,213 million. The investment development segment recorded a 27.6 % decline in sales to ¥880 million, reflecting a shift away from venture activities.
Total assets grew by ¥21.9 billion to ¥499,775 million, with current assets expanding due to higher receivables and contract assets. Total liabilities increased by ¥14.4 billion, mainly from higher accounts payable and tax payables, while equity rose by ¥7.5 billion to ¥239,441 million. Cash and cash equivalents increased by ¥3.8 billion to ¥205,575 million.
Cash flow from operations improved markedly, providing ¥23,008 million in net inflow versus ¥14,080 million the prior year. Investing cash outflows were lower than in 2023, and financing activities shifted from a net inflow to a net outflow due largely to dividend payments.
The company maintains its FY2024 full‑year forecast of ¥750 billion in net sales and ¥30 billion in operating income, unchanged from the November 2023 guidance. No revisions to accounting policies or significant subsidiary changes were reported, and the forecast remains subject to market uncertainties.
- CyberAgent reported a significant surge in profitability for FY2024 Q2, with operating income rising 56% to ¥27,355 million and net income attributable to the parent jumping 240% to ¥9,866 million.
- Net sales for the quarter increased by 12.4% to ¥408,205 million, supported by growth across all primary segments including media, internet advertising, and games.
- The media segment, driven by ABEMA, saw the strongest growth with a 26.8% increase in sales to ¥84,880 million, while game sales rose 8.9% to ¥112,213 million and internet advertising grew 8.6% to ¥212,658 million.
- Cash flow from operations improved significantly to a net inflow of ¥23,008 million, compared to ¥14,080 million in the same period of the prior year.
- The company maintained its full-year FY2024 guidance, projecting ¥750 billion in net sales and ¥30 billion in operating income.
+1
CyberAgent
Report37 pages
FY2024 Presentation Material: January to March 2024
The presentation outlines CyberAgent’s FY2024 performance, emphasizing record sales and operating profit growth across its three core businesses—Internet Advertising, Media (ABEMA), and Game. Consolidated sales reached ¥215.1 billion in Q2, up 10.0% YoY, while operating profit rose to ¥21.0 billion, a 12.2% increase and the first time surpassing ¥20 billion in eight quarters. Internet Advertising sales climbed 7.1% YoY to ¥107.3 billion, with operating profit up 19.6%. The Media segment achieved a new high of ¥42.0 billion in sales, up 25.8% YoY, and turned profitable for the first time since Q2 2023; operating profit increased 0.7 billion yen. Game sales grew 8.1% YoY to ¥67.1 billion, driven by the launch of “Granblue Fantasy: Relink,” which sold one million units within eleven days, and by anniversary events for major titles; operating profit surged 19.8% YoY.
Financially, SG&A expenses increased modestly by 2.9%, while cash deposits and fixed assets grew significantly, reflecting investment in technology and talent. Net income attributable to shareholders rose 30.8% YoY to ¥10.3 billion, offset by a temporary extraordinary loss.
The company’s strategy focuses on leveraging generative AI and large‑language models (CyberAgentLM) to enhance ad creative, expand ABEMA’s sports content through partnerships with DAZN and WOWSPO, and sustain game revenue by launching new titles such as “Granblue Fantasy Versus” and “Umamusume Pretty Derby.” The overarching goal is to increase sales and profits, with FY2023 operating profit as a low point, and to position CyberAgent as a global digital media and technology leader.
- CyberAgent achieved consolidated Q2 FY2024 sales of ¥215.1 billion (up 10.0% YoY) and an operating profit of ¥21.0 billion, marking the first time profit has exceeded ¥20 billion in eight quarters.
- The Game segment grew 8.1% YoY to ¥67.1 billion in sales, bolstered by the launch of 'Granblue Fantasy: Relink'—which reached one million units sold in eleven days—and various anniversary events.
- The Media segment (ABEMA) reached a record ¥42.0 billion in sales, a 25.8% YoY increase, and achieved profitability for the first time since Q2 2023 with an operating profit of ¥0.7 billion.
- Internet Advertising sales rose 7.1% YoY to ¥107.3 billion, with operating profit significantly outpacing revenue growth at a 19.6% increase.
- Net income attributable to shareholders grew 30.8% YoY to ¥10.3 billion, despite being partially offset by a temporary extraordinary loss.
+2
CyberAgent

Financial11 pages
Partial Correction to FY2025 First Quarter Consolidated Financial Results: Japan
CyberAgent, Inc. issued a partial correction to its FY2025 first‑quarter consolidated financial results under Japanese GAAP, released on May 15 2025. The correction adjusts several numerical values in the original January 29 announcement, with revised figures presented in full. Net sales for the quarter rose 5.8% year‑on‑year to ¥203,842 million, while operating income increased 41.6% to ¥8,301 million and ordinary income grew 45.4% to ¥8,806 million. Net income attributable to owners of the parent swung from a loss of ¥892 million in 1Q FY2024 to a profit of ¥5,071 million in 1Q FY2025. Basic earnings per share improved from a negative ¥1.76 to ¥10.01, with diluted EPS at ¥9.21.
Total assets climbed to ¥521,241 million, equity fell slightly to ¥248,271 million (equity ratio 29.3%), and liabilities rose to ¥272,969 million. The company’s dividend policy remained unchanged; the FY2025 forecast predicts net income of ¥820,000 million and net sales of ¥42,000 million for the full fiscal year. Segment analysis shows strong growth in Media & IP (net sales ¥55,638 million, operating income ¥1,416 million) and Internet Advertisement (¥117,792 million sales, ¥6,012 million operating income), while Game and Investment Development segments experienced declines. The correction does not alter the company’s forecast or strategic outlook, which continues to emphasize expansion around its flagship “ABEMA” platform and IP development.
- CyberAgent reported a significant turnaround in 1Q FY2025, swinging to a net profit of ¥5,071 million from a ¥892 million loss in the same period last year.
- Consolidated net sales for the quarter reached ¥203,842 million, marking a 5.8% year-on-year increase.
- Operating income grew by 41.6% to ¥8,301 million, while ordinary income rose 45.4% to ¥8,806 million.
- The Internet Advertisement segment remains the primary revenue driver with ¥117,792 million in sales and ¥6,012 million in operating income.
- The Media & IP segment showed strong growth with ¥55,638 million in sales and ¥1,416 million in operating income, while the Game and Investment Development segments saw declines.
CyberAgent
Financial10 pages
FY2024 Third Quarter Consolidated Financial Results: Japan
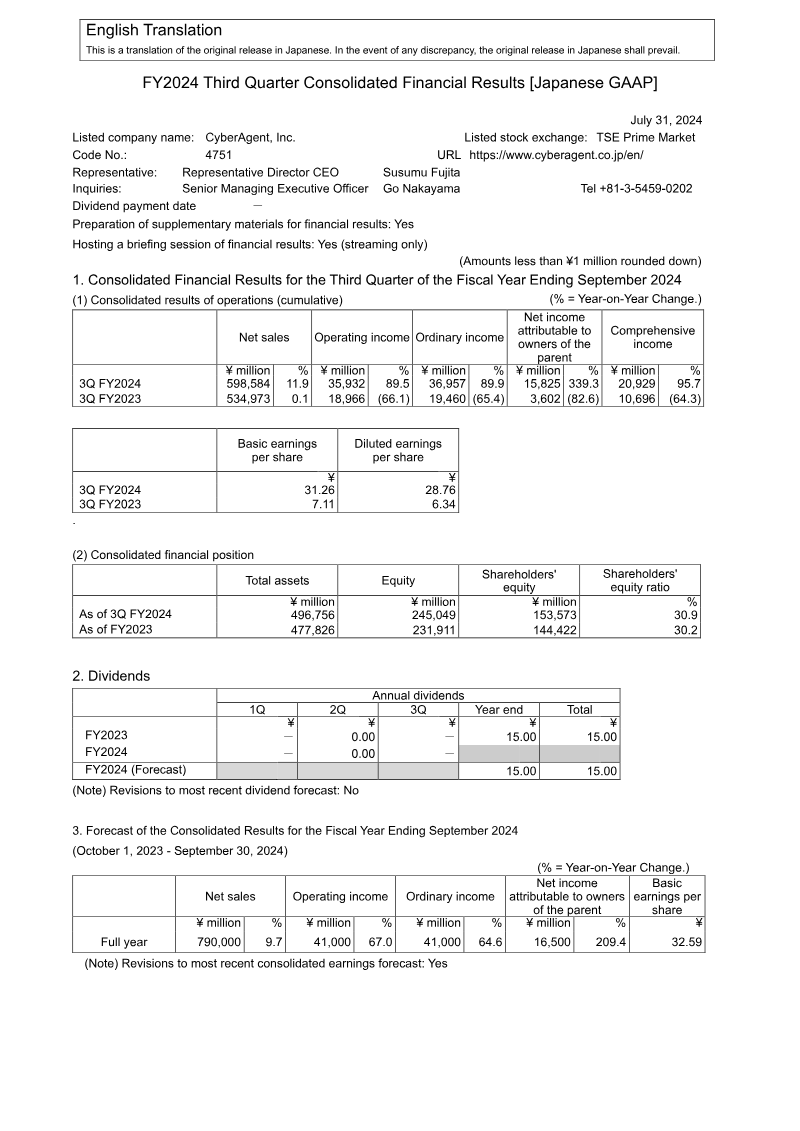
CyberAgent, Inc. reported a strong third‑quarter performance for FY2024, with net sales rising 11.9% year‑on‑year to ¥598 584 million and operating income increasing 89.5% to ¥35 932 million. Ordinary income attributable to owners surged 339.3% to ¥15 825 million, driven by record growth in the Internet Advertisement and Game segments. Net income attributable to owners rose 339% from ¥3 602 million in the same period of FY2023 to ¥15 825 million, while diluted earnings per share climbed from ¥6.34 to ¥28.76.
Segment analysis shows the Media Business, anchored by ABEMA, generated ¥125 885 million in sales with a reduced operating loss of ¥489 million. The Internet Advertisement segment achieved ¥324 839 million in sales, operating income of ¥17 553 million. The Game Business contributed ¥151 070 million in sales and ¥26 844 million in operating income. Investment Development and Other segments posted modest sales but contributed to overall profitability.
Total assets increased to ¥496 756 million, driven mainly by cash and deposits, while total liabilities rose modestly to ¥251 706 million. Equity stood at ¥245 049 million, with an equity ratio of 30.9%. The company maintained a stable share count of approximately 506 million shares outstanding.
CyberAgent revised its FY2024 earnings forecast upward, projecting net income of ¥790 000 million and operating income of ¥41 000 million. The company also announced the acquisition of Nitroplus Co., Ltd., a content‑creation firm, to enhance its IP and media mix capabilities. The acquisition is expected to strengthen CyberAgent’s position in global entertainment markets, aligning with its strategy of integrating technology and creativity across digital platforms.
- CyberAgent reported strong FY2024 Q3 growth with net sales rising 11.9% to ¥598,584 million and operating income surging 89.5% to ¥35,932 million.
- Net income attributable to owners increased 339% year-on-year to ¥15,825 million, with diluted earnings per share rising from ¥6.34 to ¥28.76.
- The Game Business and Internet Advertisement segments were primary growth drivers, contributing ¥151,070 million and ¥324,839 million in sales respectively.
- CyberAgent revised its FY2024 earnings forecast upward, now projecting ¥41,000 million in operating income.
- The Media Business, anchored by ABEMA, significantly narrowed its operating loss to ¥489 million on sales of ¥125,885 million.
+2
CyberAgent
Report54 pages
FY2024 Presentation Material: October 2023 to September 2024
October 2023 to September 2024 The future information, such as earnings forecast, written in this document is based on our expectations and assumptions as of the date the forecast was made. Our actual results could differ materially from those described in this forecast because of various risks and uncertainties. 1. FY2024 Full Year Results (October 2023 -September 2024) 2. FY2025 Forecast (October 2024 -September 2025) 3. Internet Advertisement Business 6. Medium to Long-Term Strategy 7.
- Consolidated sales for FY2024 reached 802.9 billion yen, an 11.5% increase year-over-year, marking the 27th consecutive year of sales growth driven by strong performance in three key businesses.
- The company's full-year sales were 436.3 billion yen, up 7.6% year-over-year, indicating market share growth by outpacing overall market expansion.
- The dividend forecast has been raised to 16 yen from 15 yen, with a Dividend on Equity (DOE) guidance of 5%, and the company's ROE, dividend payout ratio, and DOE all exceed the TSE average.
- Operating loss significantly improved year-over-year, with FY2024 showing a 9.5 billion yen increase in operating income compared to the previous year.
- Sales from ABEMA and related businesses grew by 22.4% year-over-year to 107.5 billion yen in FY2024, primarily driven by ABEMA-related businesses and advertising.
+1
CyberAgent
Financial18 pages
FY2024 Consolidated Financial Results: Japan
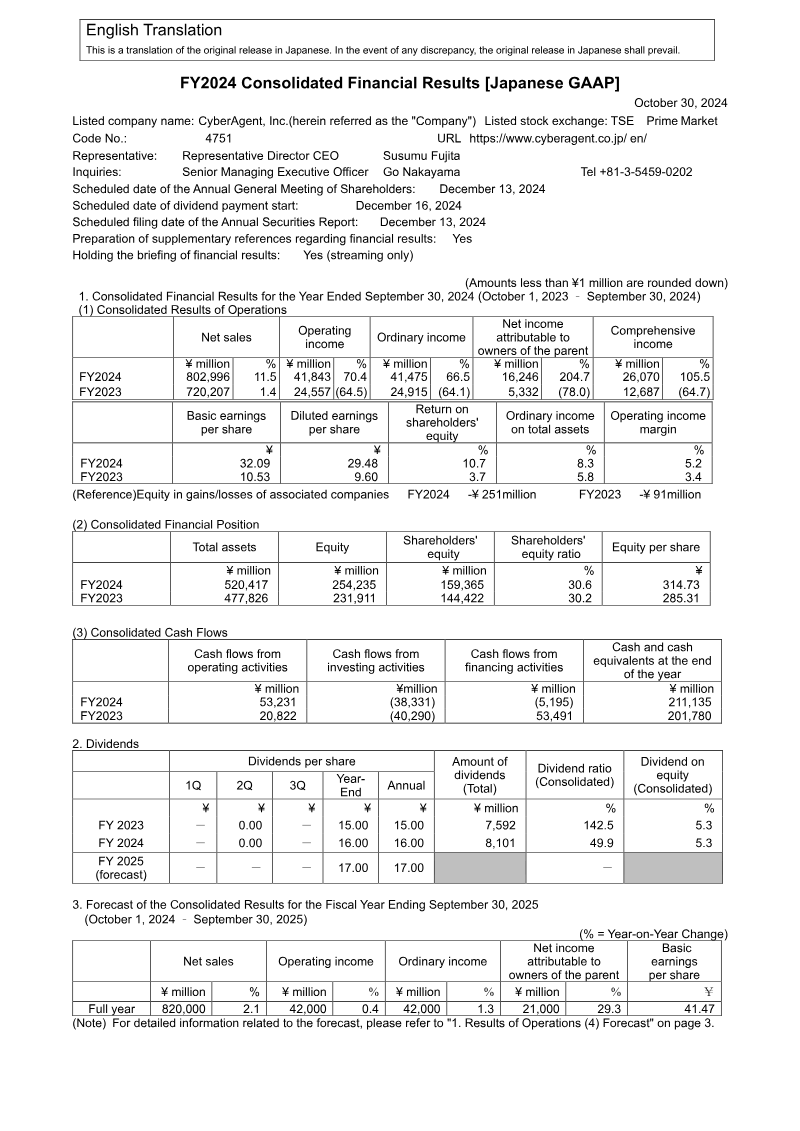
FY2024 Consolidated Financial Results [Japanese GAAP] Listed company name: CyberAgent, Inc.(herein referred as the "Company") Listed stock exchange: TSE Prime Market Code No.: 4751 URL https://www.cyberagent.co.jp/ en/ Representative: Representative Director CEO Susumu Fujita Inquiries: Senior Managing Executive Officer Go Nakaya...
- CyberAgent, Inc. reported a significant increase in net income attributable to owners of the parent, rising 204.7% to ¥16,246 million in FY2024, compared to ¥5,332 million in FY2023.
- Overall net sales for FY2024 increased by 11.5% to ¥802,996 million from ¥720,207 million in FY2023, with operating income also seeing a substantial 70.4% rise to ¥41,843 million.
- The Game Business segment experienced a 10.3% year-on-year increase in net sales to ¥197,015 million in FY2024, but its operating income decreased by 13.9% to ¥19,540 million.
- The Internet Advertisement Business remains the largest segment by revenue, with net sales of ¥401,313 million in FY2024 (up 5.3% year-on-year) and operating income of ¥20,534 million (up 12.1% year-on-year).
- Total assets increased by ¥42,590 million to ¥520,417 million at the end of FY2024, primarily due to an increase in cash and deposits.
+1
CyberAgent
Financial19 pages
Partial Correction to FY2024 Consolidated Financial Results: Japan
Representative Director, CEO, and President (Corrections / Corrections of Numerical Data) Partial Correction to FY2024 Consolidated Financial CyberAgent, Inc. today announced a correction to part of the "FY2024 Consolidated Financial Results [Japanese GAAP]," which was disclosed on October 30, 2024. The details of the correction are as follows.
- CyberAgent, Inc. issued a partial correction to its FY2024 Consolidated Financial Results, originally disclosed on October 30, 2024, with the corrected data provided on May 15, 2025.
- For FY2024, the Game Business saw significant growth, with net sales increasing by 9.4% year-on-year to ¥195,985 million and operating income rising by 34.6% year-on-year to ¥30,569 million, driven by new and existing titles.
- The Internet Advertisement Business also performed strongly in FY2024, with net sales up 7.4% year-on-year to ¥434,612 million and operating income increasing by 17.2% year-on-year to ¥20,457 million, outpacing the overall internet advertising market growth of 5.9%.
- The Media Business experienced a 20.9% year-on-year increase in net sales, reaching ¥170,849 million in FY2024, while significantly reducing its operating loss from ¥12,873 million in FY2023 to ¥1,927 million.
- CyberAgent forecasts consolidated sales of ¥820 billion for FY2025 (up 2.3% from FY2024) and consolidated operating income of ¥42 billion (up 4.8%), with the Media Business expected to become profitable.
CyberAgent
Financial10 pages
FY2025 First Half Consolidated Financial Results: Japan
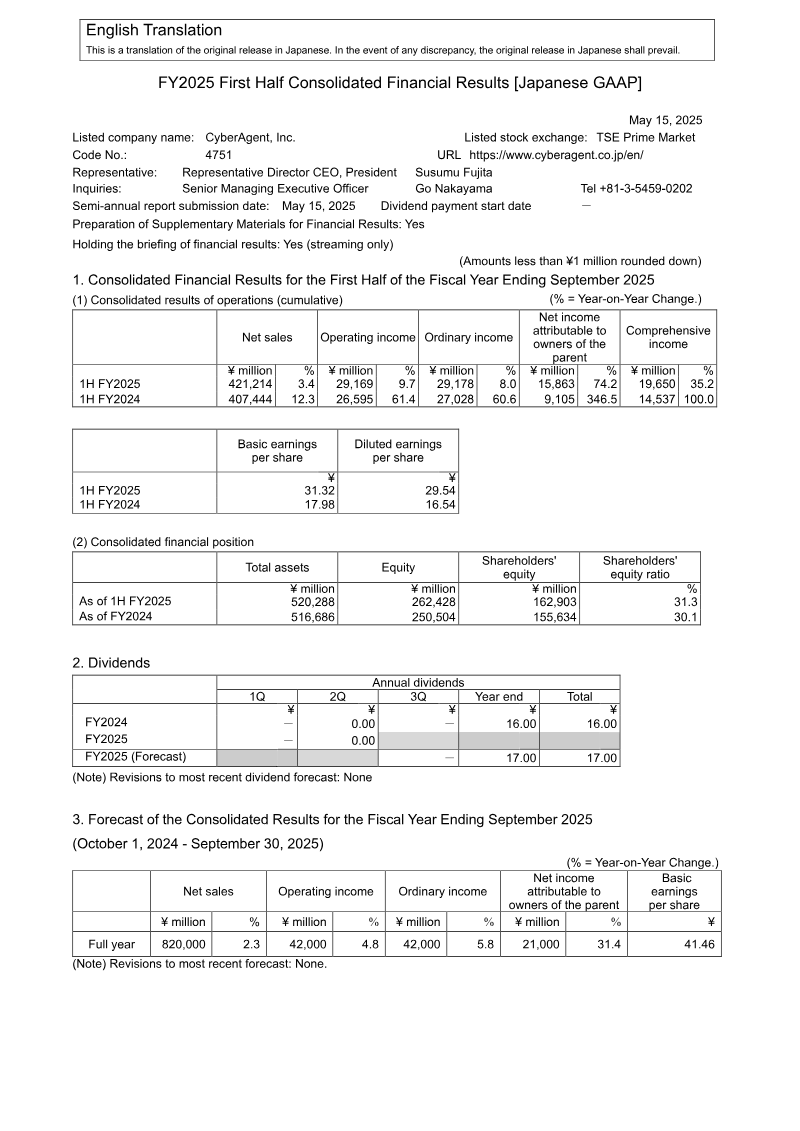
CyberAgent, Inc. reported first‑half FY2025 consolidated results under Japanese GAAP, showing a 3.4 % rise in net sales to ¥421,214 million and operating income up 9.7 % to ¥29,169 million. Ordinary income attributable to owners increased 8.0 % to ¥29,178 million, while net income attributable to the parent surged 74.2 % to ¥15,863 million, driven by a strong performance in the newly defined Media & IP Business and Internet Advertisement segments. The Media & IP segment recorded ¥112,721 million in sales (12.4 % YoY) and a shift from an operating loss to a profit of ¥4,729 million. Internet Advertisement sales rose 11.1 % to ¥235,356 million with operating income up 11.6 %. Game Business sales fell 20.1 % to ¥89,713 million, though operating income decreased only 13.9 %. Investment Development sales declined 28.6 % to ¥628 million, with an operating loss of ¥749 million.
Total assets increased to ¥520,288 million, equity rose to ¥262,428 million, and the equity ratio improved to 31.3 %. Cash and cash equivalents fell by ¥10,734 million to ¥200,400 million, largely due to operating cash inflows offset by investing and financing outflows, including a ¥20,000 million redemption of convertible bonds. Net income for the full year is forecast at ¥820,000 million, up 2.3 % YoY, with operating income projected at ¥42,000 million (4.8 %) and ordinary income at ¥42,000 million (5.8 %). The company maintains its dividend policy with a forecast of ¥17 million per share for FY2025, unchanged from prior guidance.
- CyberAgent reported a 74.2% surge in net income attributable to the parent to ¥15,863 million for the first half of FY2025, alongside a 3.4% increase in net sales to ¥421,214 million.
- The Media & IP Business segment achieved a significant turnaround, recording ¥112,721 million in sales (up 12.4% YoY) and shifting from an operating loss to a profit of ¥4,729 million.
- The Internet Advertisement segment remains a primary growth driver, with sales rising 11.1% to ¥235,356 million and operating income increasing 11.6%.
- The Game Business segment experienced a contraction, with sales falling 20.1% to ¥89,713 million and operating income declining 13.9%.
- The company's financial position strengthened with an improved equity ratio of 31.3% and total assets reaching ¥520,288 million.
+1
CyberAgent
Report43 pages
2Q FY2025 Financial Presentation Material
2Q FY2025 Presentation Material We corrected past annual securities reports and others due to the discovery of an inappropriate accounting treatment at the consolidated subsidiary. Please refer to the “Notice on Submission of Correction Reports of Past Annual Securities Reports and Amendments of Financial Statements for Past Fiscal Years” released on May 15, 2025, for details.
- The company achieved record-high sales of 217.3 billion yen in FY2025 Q2, up 1.2% YoY, with operating profit increasing by 0.7% YoY to 20.8 billion yen, primarily driven by Media & IP and Ad businesses.
- An inappropriate accounting treatment at a consolidated subsidiary led to corrections of past annual securities reports and amendments of financial statements, with details released on May 15, 2025.
- The Media & IP business saw significant growth, with sales up 14.4% YoY to 57.0 billion yen and operating profit increasing 6.5x YoY to 3.3 billion yen, through building a multi-layered revenue stream and investing in anime production.
- The Ad business maintained a high sales increase rate, up 9.9% YoY to 117.5 billion yen, and operating profit increased by 8.7% YoY to 6.0 billion yen, with an operating profit margin of 5.1%.
- Sales and profit in the game console game sector declined 23.4% YoY to 51.4 billion yen and 15.7% YoY to 15.3 billion yen respectively, despite a significant QoQ increase (34.6% in sales, 4.6x in OP) due to a game release in February 2024.
+2
CyberAgent
Financial10 pages
FY2025 First Quarter Consolidated Financial Results: Japan GAAP
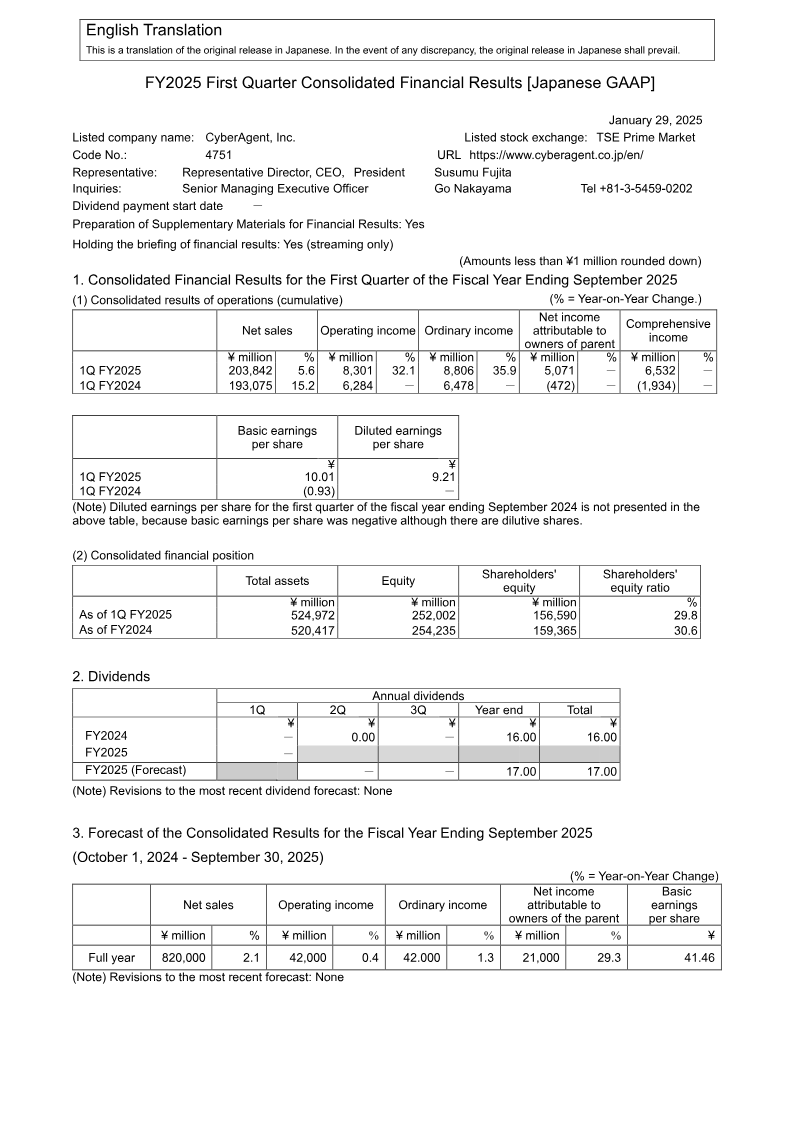
CyberAgent, Inc. reported a first‑quarter fiscal 2025 performance that marked a turnaround from the prior year’s loss. Net sales rose 5.6 % to ¥203,842 million, driven by a 10.5 % increase in the Media & IP Business (¥55,638 million) and an 11.8 % rise in Internet Advertisement sales (¥117,792 million). Operating income surged 32.1 % to ¥8,301 million, converting the prior‑year operating loss of ¥796 million into a profit. Ordinary income climbed 35.9 % to ¥8,806 million, and net income attributable to the parent rose from a loss of ¥472 million to a profit of ¥5,071 million. Earnings per share improved from a negative ¥0.93 to ¥10.01 basic and ¥9.21 diluted.
Total assets increased modestly to ¥524,972 million, while equity fell slightly to ¥252,002 million due mainly to dividend payouts. The company’s forecast for FY2025 remains unchanged: net sales of ¥820,000 million (2.1 % growth) and operating income of ¥42,000 million (0.4 % growth). Dividend policy is unchanged, with a forecast annual dividend of ¥17.00 per share.
The report covers Japan GAAP operations across four segments—Media & IP, Internet Advertisement, Game, and Investment Development—within the Japanese market for FY2025. No significant accounting policy changes or restatements were noted, and the company confirmed its going‑concern assumption. The financial statements are based on a consolidated basis, with 506 million shares outstanding and no material changes in the scope of consolidation.
- CyberAgent returned to profitability in Q1 FY2025, reporting an operating income of ¥8,301 million compared to a ¥796 million loss in the same period last year.
- Net sales grew 5.6% year-over-year to ¥203,842 million, supported by double-digit growth in both the Media & IP Business and Internet Advertisement segments.
- The Internet Advertisement segment remains the primary revenue driver, contributing ¥117,792 million in sales, an 11.8% increase over the previous year.
- The Media & IP Business segment saw a 10.5% revenue increase, reaching ¥55,638 million for the quarter.
- Net income attributable to the parent company reached ¥5,071 million, a significant recovery from the ¥472 million loss recorded in Q1 FY2024.
+2
CyberAgent