Report40 pages
Mobile Ad Creative Index
The mobile advertising landscape in 2023 is defined by a strategic shift toward high-performing creative formats as advertisers navigate macroeconomic pressures and evolving privacy regulations. Despite these challenges, mobile ad revenue continues to grow, driven by the efficiency of specific ad types tailored to distinct industry verticals. Native ads emerge as the most cost-effective format overall, boasting a $1.01 cost-per-install and delivering a leading 18% Day 7 return on ad spend within the gaming sector. Meanwhile, playable ads have established themselves as the premier tool for driving gaming installs, while banner ads remain the dominant force in e-commerce due to their low cost-per-action and high conversion rates.
Performance metrics across finance, entertainment, and social applications further underscore the importance of format selection. Native and banner ads provide the lowest entry costs for social and dating apps, yet interstitial and video formats yield significantly higher short-term returns, reaching up to 44% Day 7 return on ad spend. Creative strategies are increasingly moving away from lifestyle imagery in favor of clean, user-interface-focused designs. Implementing multi-page ad experiences has proven particularly effective, resulting in a 20% increase in installs per mille.
Optimization now relies on a sophisticated blend of interactivity and narrative depth. Interactive playable ads serve a dual purpose by engaging users and gathering valuable audience data, while longer video segments of 31 to 60 seconds drive 50% higher conversions by showcasing complex mechanics and storytelling. Furthermore, the integration of authentic user-generated content that focuses on problem-solving builds necessary trust with modern consumers. By aligning creative content with specific psychological motivations—such as competition or exploration—advertisers can maximize engagement and emotional connection across global mobile markets.
- Native ads are the most cost-effective format for gaming, achieving a $1.01 cost-per-install and an 18% Day 7 return on ad spend.
- Interstitial and video formats drive superior short-term performance for social and dating apps, yielding up to 44% Day 7 return on ad spend.
- Video ad segments ranging from 31 to 60 seconds drive 50% higher conversions compared to shorter formats by effectively showcasing complex mechanics.
- Multi-page ad experiences increase installs per mille by 20% compared to single-page designs.
- Playable ads are the primary driver for gaming installs, while banner ads remain the most efficient format for e-commerce due to low cost-per-action.
+1
LiftoffJan 2023
Report42 pages
Q1 2023: Store Intelligence Data Digest
The global mobile app ecosystem experienced a slight contraction in early 2023, with total downloads falling 2.6% year-over-year to 35 billion. Despite this overall decline, the market remained bifurcated between Google Play’s 26.9 billion installs and the App Store’s 8.1 billion. While established giants like Meta and Google maintained their status as leading publishers, TikTok secured its eleventh consecutive quarter as the world’s top app. The gaming sector showed stability through the continued popularity of titles such as Subway Surfers and Roblox, even as broader consumer behavior shifted toward emerging technologies and new retail platforms.
The most significant growth occurred within the artificial intelligence and marketplace sectors. AI-powered productivity tools saw an explosive 378% increase in downloads and a nearly 400% surge in revenue, reaching $20 million in quarterly earnings driven primarily by U.S. demand. Simultaneously, the North American retail landscape underwent a major disruption as the Chinese shopping app Temu captured a 50% market share. Following a high-profile Super Bowl campaign, Temu surpassed Amazon in average monthly user engagement, clocking 64 minutes per user. This shift coincided with a general downturn in traditional social networking and messaging installs, though privacy-centric platforms like Telegram and short-video leaders continued to grow.
Comprehensive market intelligence across these sectors reveals a digital economy in transition, where established social media dominance is being challenged by specialized AI utilities and aggressive new e-commerce entrants. By tracking performance across major platforms including TikTok, YouTube, and Instagram, data indicates that while total volume may be cooling, high-value engagement is concentrating in specific, high-growth niches. These trends reflect a broader evolution in consumer priorities toward utility-driven AI and highly competitive, gamified shopping experiences.
- AI-powered productivity tools experienced explosive growth in Q1 2023, with a 378% increase in downloads and a nearly 400% surge in revenue to $20 million.
- Temu captured a 50% market share in North American retail and surpassed Amazon in user engagement, averaging 64 minutes per user following its Super Bowl campaign.
- Global mobile app downloads contracted by 2.6% year-over-year to 35 billion, with 26.9 billion installs on Google Play and 8.1 billion on the App Store.
- TikTok maintained its position as the world's top app for the eleventh consecutive quarter, even as traditional social networking and messaging installs saw a general downturn.
- The gaming sector remained stable during early 2023, supported by the continued popularity of established titles like Subway Surfers and Roblox.
+1
Sensor TowerJan 2023
Report42 pages
How Different Generations Engage with Video Games Today
Gaming has evolved into the primary entertainment medium for younger generations, with 94% of Gen Alpha identifying as game enthusiasts. This shift signifies a transition from gaming as a solitary hobby to a multi-dimensional "way of life" that encompasses playing, viewing, and socializing. While mobile gaming maintains universal appeal across all age groups, younger cohorts like Gen Alpha and Gen Z are significantly more likely to engage across multiple platforms and participate in virtual social environments. These younger players demonstrate high spending conversion rates, with approximately 60% investing in games, often driven by a desire for social immersion and diverse genres such as Adventure and Battle Royale.
In contrast, older generations like Gen X and Baby Boomers exhibit more utilitarian engagement patterns. These cohorts primarily favor casual puzzle-solving titles and are motivated by achievement, mastery, and time-saving mechanics. While 70% of younger players are "player-viewers" who consume gaming video content for entertainment and social connection, older players use video content more informationally, such as for reviews or tutorials. This generational divide extends to brand discovery; younger players are increasingly open to discovering new brands within game worlds, making the medium a vital marketing tool for reaching modern consumers.
The global gaming landscape is characterized by both universal franchises and distinct regional preferences. Major titles like Call of Duty, Fortnite, and Genshin Impact maintain a massive international presence, yet markets such as China, Japan, and South Korea continue to support region-specific hits like Honor of Kings and Lineage. Across these diverse geographies, the 2023 data highlights that gaming has become a central pillar of social interaction and brand engagement, particularly as younger generations integrate virtual experiences into their daily identities and consumption habits.
- Gaming has become the primary entertainment medium for younger generations, with 94% of Gen Alpha identifying as game enthusiasts.
- Approximately 60% of younger players invest in games, driven by a preference for social immersion and genres like Adventure and Battle Royale.
- 70% of younger players are 'player-viewers' who consume gaming content for social connection, whereas older generations use such content primarily for information like reviews and tutorials.
- Younger cohorts engage across multiple platforms and virtual social environments, while Gen X and Baby Boomers favor casual puzzle titles focused on mastery and time-saving mechanics.
- Younger players are increasingly receptive to brand discovery within game worlds, positioning gaming as a critical marketing channel for modern consumer engagement.
+1
NewzooJan 2023
Presentation17 pages
Aktualizacja Strategii Nowe Otwarcie 2023
The strategy overview presents PCF Group S.A. as a leading Polish producer of AAA‑level shooter games built on Unreal Engine, emphasizing its extensive experience, proprietary technology, and international development network. It positions the company as a high‑profile creator of original and co‑produced titles that have repeatedly appeared on the cover of the prestigious “Game Informer” magazine, citing notable releases such as Gears of War series, Bulletstorm, and collaborations with Epic Games on Fortnite.
Financial highlights indicate that cumulative revenue reached 608 million złoty between 2018 and 2022, representing a 4.9‑fold increase and a 2.4‑fold rise in EBITDA to 185 million złoty. The firm projects a similar revenue multiplier for 2023‑2027, driven primarily by a self‑publishing model and the launch of four core AAA projects and three supplementary titles, including two VR offerings slated for 2025‑2026. Shareholder structure after the IPO shows a diversified ownership with significant ESOP participation, and the capital plan anticipates issuing up to 5.85 million new shares.
Operationally, the group employs more than 600 specialists across two continents, organized into matrix‑based centers of excellence that support simultaneous development of multiple projects. The PCF Framework, an Unreal Engine add‑on, accelerates production pipelines and standardizes agile practices across seven development studios located in Warsaw, Newcastle, Montreal, Katowice, Rzeszów, New York, and Kraków. Recent acquisitions have expanded the portfolio with new IPs such as Gemini, Dagger, Bifrost, and Victoria, now in pre‑production.
Strategic goals focus on scaling the self‑publishing business, introducing “games‑as‑a‑service” monetization with micro‑transactions and seasonal passes, and strengthening the company’s position as an independent AAA publisher. The plan anticipates a workforce of over 1 200 employees by 2027, supported by incentive programs for shareholders and a robust cash flow structure designed to fund continued growth without external dilution.
- PCF Group targets a revenue multiplier for 2023–2027 comparable to the 4.9-fold growth seen between 2018 and 2022, when cumulative revenue reached 608 million złoty.
- The company is shifting to a self-publishing model to support the launch of four core AAA projects and three supplementary titles, including two VR games scheduled for 2025–2026.
- Strategic monetization will pivot toward a 'games-as-a-service' model, incorporating micro-transactions and seasonal passes to scale independent AAA publishing.
- The firm plans to double its workforce to over 1,200 employees by 2027, supported by a matrix-based operational structure across seven international studios.
- Development efficiency is driven by the proprietary 'PCF Framework' add-on for Unreal Engine, which standardizes production pipelines across studios in locations including Warsaw, Montreal, and New York.
+1
PCF GroupJan 2023
Report23 pages
Peak Play: Trends in East Asian Videogame Streaming H1 2023
The East Asian videogame livestreaming market is a mature and culturally distinct ecosystem where competitive esports serve as the primary engine for audience engagement. During the first half of 2023, MOBA and Battle Royale titles accounted for over half of the region's most-watched content. While established franchises like League of Legends maintain a dominant presence, the market is increasingly shaped by the influence of Key Opinion Leaders and VTubers. These creators contribute up to 15% of total viewership for major titles and have demonstrated the power to revitalize older games such as Minecraft and Escape from Tarkov.
Regional preferences reveal a bifurcated landscape where specific titles command massive scale. In China, Honor of Kings remains the undisputed leader with 5.67 billion views, while VALORANT and Apex Legends dominate the Japanese and Korean markets, each surpassing 100 million hours watched. The barrier to entry for new releases is high, as only high-profile 2023 titles like Diablo IV, Honkai: Star Rail, and Street Fighter 6 managed to break into regional top-ten rankings. The rapid ascent of Honkai: Star Rail in China notably came at the expense of Genshin Impact, which saw a 31% decline in viewership as audiences shifted toward the newer release.
The integration of granular streaming analytics and market intelligence is essential for navigating this complex environment. By tracking metrics across platforms such as Twitch, YouTube, and AfreecaTV, stakeholders can monitor audience retention and demographic shifts. This data-driven approach highlights the volatility of the market, evidenced by the 68.5% decline in Splatoon 3 viewership following its launch period. Understanding these dynamics—ranging from the professional esports circuit to the rising prominence of virtual avatars—is critical for identifying growth opportunities and executing successful market entry strategies across Asia.
- Competitive esports, specifically MOBA and Battle Royale titles, drive over 50% of total viewership in the East Asian streaming market.
- Honor of Kings remains the dominant force in China with 5.67 billion views, while VALORANT and Apex Legends lead in Japan and Korea with over 100 million hours watched each.
- Key Opinion Leaders and VTubers are significant market drivers, contributing up to 15% of total viewership for major titles and successfully revitalizing older games.
- New title launches face high barriers to entry, with only Diablo IV, Honkai: Star Rail, and Street Fighter 6 breaking into regional top-ten rankings during H1 2023.
- Audience cannibalization is a measurable risk, as evidenced by Honkai: Star Rail’s growth contributing to a 31% decline in Genshin Impact viewership.
+1
Niko PartnersJan 2023
Report19 pages
European Key Facts 2023
This analysis provides a comprehensive overview of the European video game sector in 2023, detailing market health, player demographics, and regulatory priorities. The industry demonstrated resilience with annual revenues reaching €25.7 billion, representing a 5% year-on-year increase. Employment also saw significant growth, with the workforce expanding by nearly 7% to reach approximately 115,000 people across Europe.
The data reveals that video games are a mainstream cultural fixture, with 53% of the European population aged 6–64 identifying as players. Contrary to youth-centric stereotypes, the average player age is 31.4 years, and 75% of the gaming population are adults. Women represent 43.5% of the total player base, averaging 6.7 hours of play per week. While smartphones remain the most popular platform (68%), consoles (56%) and PCs (46%) maintain significant engagement. Despite the rise of digital media, average weekly playtime has remained stable for over a decade at approximately 8.9 hours.
A central thesis of the findings is the industry’s commitment to social responsibility and self-regulation. The Pan European Game Information (PEGI) system celebrated 20 years of operation, with 79% of parents aware of its ratings and 62% actively using parental tools to manage gameplay. Furthermore, the industry is increasingly focused on sustainability and diversity, noting that 44% of new hires in regions like Sweden are women and highlighting energy-saving agreements that have saved 54 TWh of electricity over the lifetime of major consoles.
The geographic scope covers the European Union and broader European markets, utilizing data from Ipsos, GameTrack, and Games Sales Data (GSD). Methodology includes online polling of 60,000 individuals across major markets, calibrated by nationally representative face-to-face surveys. Looking forward, the industry advocates for EU policy that recognizes video games as unique creative works, supports a robust talent pipeline through STEAM education, and maintains a fair regulatory framework that avoids distorting the single market.
- The European video game sector generated €25.7 billion in 2023, marking a 5% year-on-year revenue increase.
- Industry employment grew by nearly 7% in 2023, reaching a total workforce of approximately 115,000 people across Europe.
- Video games are a mainstream fixture with 53% of the population aged 6–64 identifying as players, maintaining a stable average of 8.9 hours of gameplay per week.
- The player base is mature and diverse, with an average age of 31.4 years, 75% adult representation, and 43.5% female participation.
- Smartphones are the leading platform at 68% usage, followed by consoles at 56% and PCs at 46%.
+1
Video Games EuropeJan 2023
Report40 pages
State of the Market 2023
The global mobile application market underwent a period of stabilization in 2023, characterized by a slight year-over-year decline of 3.6% in downloads and 1% in total revenue. Despite these minor contractions, the industry remains a massive economic force, with a distinct divide between platform utility and monetization. Android continues to dominate the global market share by volume, facilitating 84% of all installs, while iOS remains the primary engine for monetization, accounting for 67% of total consumer spending. Geographically, while emerging markets like India and Brazil are driving significant download growth, global revenue remains highly concentrated, with the United States, China, and Japan collectively generating 58% of all spending.
Gaming persists as the most influential vertical, particularly within the Casual and RPG subgenres, though performance metrics across most categories have trended downward. A significant disparity exists between the apps that consumers download most frequently and those that generate the highest revenue. While Meta-owned platforms and utility services lead in global installs, high-engagement entertainment and social platforms like TikTok and Tinder drive the highest financial returns. Notably, Duolingo has established a unique position as a leader in both volume and monetization within the education sector, signaling the potential for specialized platforms to achieve cross-metric dominance.
The mobile advertising landscape is currently adapting to increased privacy restrictions and tracking challenges by pivoting toward AI-driven video and hybrid formats. Although the total number of advertisers and publishers decreased in 2023, the volume of creative content surged, reflecting a highly competitive environment where over half of all ads are cycled out within three days. Gaming advertisers remain the most active participants, representing 53% of all advertisers and nearly 79% of App Store traffic. Current strategic trends favor user-generated content and gamified video over traditional or misleading creatives, emphasizing high-quality, targeted engagement to maintain visibility in an increasingly saturated digital ecosystem.
- The global mobile market saw minor 2023 contractions, with a 3.6% decline in downloads and a 1% decrease in total revenue.
- Market share is bifurcated by platform: Android accounts for 84% of global installs, while iOS generates 67% of total consumer spending.
- Revenue is highly concentrated, with the United States, China, and Japan collectively accounting for 58% of all global mobile spending.
- Gaming remains the dominant vertical, with gaming advertisers representing 53% of all advertisers and 79% of App Store traffic.
- While Meta and utility apps lead in download volume, high-engagement platforms like TikTok and Tinder drive the highest financial returns.
+1
AppticaJan 2023
Report14 pages
Australian Game Development Survey FY 2023
The Australian Game Development Survey FY2023 reveals a maturing industry experiencing significant growth in both revenue and employment. Total income generated by local studios reached $345.5 million, a 21% increase over the previous year, while the workforce expanded by 17% to 2,458 full-time equivalent employees. This growth is largely attributed to increased federal and state government support, including the Digital Games Tax Offset (DGTO), which has bolstered developer confidence and attracted international interest.
The sector is heavily export-oriented, with 87% of revenue derived from markets outside of Australia. While the industry is diversifying, it remains concentrated in the eastern states, with Victoria housing 29% of studios and 41% of the workforce. The ecosystem is characterized by a mix of established and emerging entities; 32% of studios have operated for over a decade, yet 45% are five years old or less, and 29% are currently developing their first title. Small businesses dominate the landscape, with 79% of respondents employing fewer than 20 people.
Despite this upward trajectory, the industry faces notable headwinds. The primary challenges identified include difficulty hiring staff with specialized technical skills, attracting early-stage development funding, and securing international publishing deals amidst tightening global economic conditions. Nevertheless, 63% of studios intend to hire more staff in the coming year, and 68% predict continued income growth.
The findings are based on a survey of 111 Australian game development studios conducted by Bond University on behalf of the Interactive Games & Entertainment Association (IGEA). The data covers the financial year from July 1, 2022, to June 30, 2023, and includes metrics on gender diversity, which showed an increase in the representation of women and gender-diverse individuals within the workforce.
- The Australian game development industry generated $345.5 million in revenue during FY2023, marking a 21% year-over-year increase.
- Total industry employment grew by 17% to 2,458 full-time equivalent employees, with 63% of studios planning further hiring in the coming year.
- The sector is highly export-focused, with 87% of total revenue derived from international markets.
- Government support, specifically the Digital Games Tax Offset (DGTO), is a primary driver of developer confidence and international investment.
- The industry is geographically concentrated in Victoria, which accounts for 29% of studios and 41% of the total workforce.
+1
Interactive Games & Entertainment AssociationJan 2023
Report27 pages
Hyper to Hybrid: Mobile Gaming Market Trends 2023
The mobile gaming landscape is undergoing a fundamental shift as developers transition from hyper-casual to hybrid-casual business models. This evolution is driven by a significant downward trend in ad revenue profitability, influenced by Apple’s App Tracking Transparency framework, shifting post-pandemic user behaviors, and increased selectivity from major publishers. To maintain sustainability, developers are increasingly adopting self-publishing strategies and integrating sophisticated meta-gameplay components alongside in-app purchases to diversify revenue streams beyond traditional advertising.
Data from the 2022 calendar year reveals a cooling market for ad-centric models, characterized by declining ad impressions and effective cost per mille (eCPM) across both Android and iOS platforms. Conversely, the volume of in-app purchases grew on both operating systems, signaling a successful pivot toward hybrid monetization. Geographically, India emerged as the leader for Android installs, while the United States maintained its position as the primary market for both ad revenue and in-app purchase value across all devices.
The competitive landscape for ad networks and monetization channels shows distinct platform preferences. Apple Search Ads dominates iOS rankings for installs, retention, and lifetime value, while AppLovin and ironSource lead the Android market. AppLovin currently stands as the top monetization channel by total ad revenue on both platforms. These findings are based on anonymized data from the full 2022 period, utilizing a weighted average methodology for performance metrics and focusing on networks and regions that exceeded a threshold of 25 million installs. The analysis underscores a broader industry movement toward deeper player engagement and more complex economic structures in mobile gaming.
- Mobile developers are shifting from hyper-casual to hybrid-casual models to counter declining ad revenue profitability caused by Apple’s App Tracking Transparency and post-pandemic behavioral shifts.
- In-app purchase volume grew across both Android and iOS in 2022, signaling a successful industry-wide pivot toward diversified revenue streams beyond traditional advertising.
- Ad-centric monetization models faced a cooling market in 2022, characterized by a downward trend in both ad impressions and effective cost per mille (eCPM) on all platforms.
- Apple Search Ads is the top-performing channel for iOS installs, retention, and lifetime value, while AppLovin and ironSource lead the Android market.
- AppLovin currently serves as the leading monetization channel by total ad revenue across both Android and iOS platforms.
+3
TenjinJan 2023
Report19 pages
The Games We Watched: Lurkit’s Top 500 Global Stream Report
The global gaming industry experienced a period of significant contrast in 2023, characterized by record-breaking streaming engagement despite internal industry volatility such as widespread layoffs. Analysis of 170,000 games and 12 million channels reveals that the top 500 titles alone generated nearly 15 billion hours of viewership on Twitch. This engagement is heavily concentrated at the top of the market, with only 11 titles accounting for half of the total viewership among the top 500. Grand Theft Auto V maintained its position as the most-watched title with 1.3 billion hours, while Fortnite demonstrated the broadest creator appeal, engaging 2.8 million unique streaming channels.
The performance of mid-tier and newly released titles illustrates a diverse landscape where evergreen sandbox games compete with high-impact narrative launches. While established hits like Stardew Valley maintained steady viewership, 2023 releases such as Alan Wake II and Armored Core VI achieved high average viewership densities, signaling strong concentrated interest during their launch windows. Even at the lower end of the top 500 rankings, titles like PICO PARK maintained substantial footprints, recording nearly 1.8 million hours watched. This indicates a deep tail of engagement where hundreds of games sustain millions of hours of annual viewership.
Methodologically, these findings focus exclusively on digital video game software, omitting non-gaming categories such as "Just Chatting" and tabletop games to provide a precise view of the interactive entertainment market. The data accounts for active engagement by excluding streams with zero concurrent viewers, a factor that impacts total hours watched by less than 1%. Ultimately, the 2023 streaming data confirms that while a small number of blockbuster titles dominate the majority of audience attention, the ecosystem remains robust enough to support hundreds of titles with significant, multi-million-hour viewership totals.
- The top 500 games generated nearly 15 billion hours of viewership on Twitch in 2023, despite broader industry volatility.
- Market engagement is highly concentrated, with just 11 titles accounting for 50% of the total viewership among the top 500 games.
- Grand Theft Auto V was the most-watched title of 2023, accumulating 1.3 billion hours of viewership.
- Fortnite achieved the highest creator appeal, with 2.8 million unique streaming channels broadcasting the game throughout the year.
- New 2023 releases like Alan Wake II and Armored Core VI demonstrated high average viewership density during their launch windows, proving the viability of high-impact narrative launches.
LurkitJan 2023
Report66 pages
How UGC, AI, & Cloud Are Transforming Gaming
The gaming industry is currently undergoing a fundamental transformation driven by the social behaviors of Gen Alpha and Gen Z, over 90% of whom utilize gaming as their primary interactive outlet. This demographic shift has catalyzed the rise of User-Generated Content (UGC), artificial intelligence, and cloud infrastructure, collectively democratizing development and allowing indie titles to compete with AAA productions. The cloud gaming market is expanding rapidly, reaching nearly 400 million users within four years, while the integration of AI in gaming is projected to achieve a $4.2 billion valuation by 2029.
UGC has emerged as a critical driver of retention, with dominant platforms like Roblox, Minecraft, and Fortnite accounting for 19% of total global playtime and distributing over $1.3 billion to creators in 2023. To overcome the technical and legal hurdles of content creation, the industry is increasingly turning to generative AI, a sector expected to reach $1.8 billion by 2025. These tools automate complex processes such as texture upscaling and level generation, lowering the barrier to entry for creators across diverse genres.
While cloud technology offers the potential for real-time updates and massive concurrency, infrastructure limitations remain a significant bottleneck. Approximately 76% of players identify latency as a primary concern, suggesting that while 5G will eventually facilitate mass consumer adoption, the immediate utility of the cloud lies in B2B applications like secure playtesting and instant discoverability. The convergence of these technologies is ultimately moving the industry toward a live-service ecosystem of "endless games," where the boundaries between traditional media and interactive community-driven platforms continue to blur.
- User-generated content (UGC) is a primary driver of player retention, with Roblox, Minecraft, and Fortnite accounting for 19% of global playtime and distributing $1.3 billion to creators in 2023.
- The integration of AI in gaming is projected to reach a $4.2 billion valuation by 2029, while the generative AI sector specifically is expected to hit $1.8 billion by 2025.
- Cloud gaming has scaled to nearly 400 million users in four years, though 76% of players cite latency as a primary barrier to mass adoption.
- Generative AI is lowering development barriers by automating complex technical tasks like texture upscaling and level generation, enabling indie titles to compete with AAA productions.
- Over 90% of Gen Alpha and Gen Z now utilize gaming as their primary interactive outlet, forcing a shift toward live-service ecosystems and community-driven platforms.
+2
NewzooJan 2023
Report15 pages
In-Game Spending: Parents' Supervision of In-Game Spending 2023
The research investigates how parents supervise and manage their children’s in‑game purchases, tracking trends across five European markets—United Kingdom, France, Germany, Spain and Italy—over four survey waves (2018, 2019, 2020 and 2023). Each wave surveyed adult parents or guardians of children who play video games, with sample sizes ranging from 962 in 2018 to 2,808 in 2023, providing a broad cross‑section of the region’s gaming households.
Findings show that three‑quarters of parents consistently report that their children do not spend on in‑game extras, a proportion that has remained stable since 2020. Among the minority who do spend, the average monthly outlay rose from €33 in 2020 to €39 in 2023, reflecting a €6 increase that aligns with inflation. Most spending (64 %) falls within the €1‑20 range, with the most popular items being gameplay‑impacting content (34 %) and decorative or cosmetic items (just under one third). Loot boxes and other unknown‑reward items remain relatively unpopular.
Parental oversight is high: nine‑in‑ten parents of spending children have some form of agreement, half of which are explicit—either seeking permission (38 %) or setting limits (23 %). Preferred monitoring tools include credit‑card bill checks, parental‑control settings, and two‑factor authentication, though 44 % of parents who avoid controls deem them unnecessary and 32 % find them difficult to activate. Awareness of in‑game currency and loot boxes among all players (ages 11‑64) is also limited, with only 9 % having purchased in‑game currency and 4 % having bought loot boxes. The study’s methodology relies on standardized questionnaires administered to representative adult panels in each country, ensuring comparability within each survey year while noting that cross‑year comparisons are constrained by methodological changes.
- Three-quarters of children do not engage in in-game spending, a figure that has remained stable since 2020.
- Average monthly in-game spending among children who do spend increased from €33 in 2020 to €39 in 2023, a rise consistent with inflation.
- The majority of in-game spending (64%) is concentrated in the €1–20 monthly range, with gameplay-impacting content (34%) and cosmetic items (33%) being the most popular purchases.
- Parental oversight is high, with 90% of parents of spending children maintaining some form of agreement, including explicit permission requirements (38%) or spending limits (23%).
- While 44% of parents who do not use parental controls consider them unnecessary, 32% report that they find these tools difficult to activate.
+1
Video Games EuropeJan 2023
Report1 pages
Video Games in Romania 2023
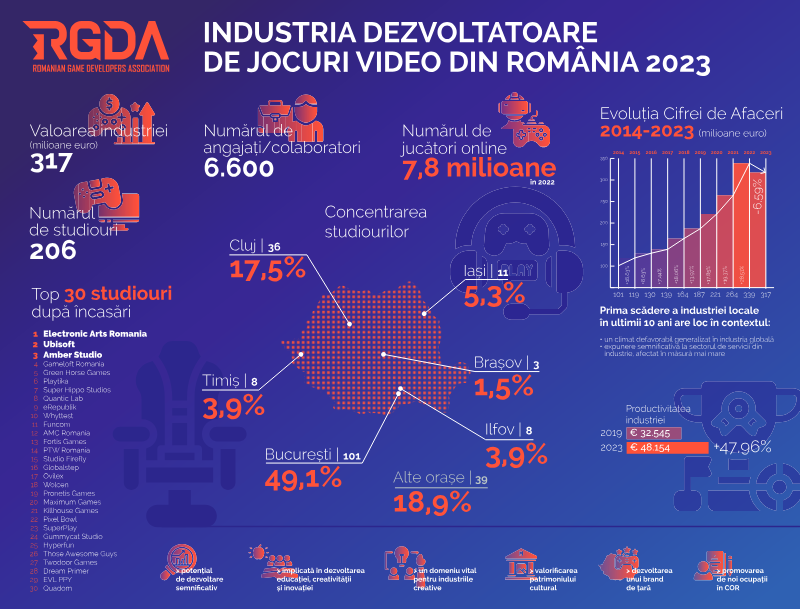
The 2023 analysis of Romania’s video‑game sector presents a comprehensive overview of its economic evolution, workforce expansion, and market concentration over the past decade. It establishes that the industry’s turnover has risen sharply, reaching approximately €6.6 billion in 2023, while the number of active studios grew to 350 and employment climbed to roughly 6 600 people. Online player participation also expanded, with an estimated 7.8 million gamers engaging with Romanian titles or services.
Growth trends are detailed year by year from 2014 to 2023, highlighting an overall upward trajectory in revenue and studio count, yet noting a first‑time contraction in 2022 of about 6.6 percent, attributed to a broadly unfavorable global climate and heightened exposure to the service‑sector dynamics that affect the industry more acutely than other creative fields. Geographic distribution shows a pronounced clustering in key urban hubs: Cluj hosts the largest concentration with 36 studios, followed by Iași, which accounts for 17.5 percent of the total, and other significant presences in Bucharest, Timișoara, and Brașov.
The report identifies the top thirty studios, which together generate roughly 5 percent of total industry revenue, and lists leading companies such as Electronic Arts Romania, Ubisoft, Amber Studio Brașov, and Playtika, among others. Their individual growth rates vary, with some recording double‑digit percentage increases, underscoring a heterogeneous performance landscape within the sector. The analysis concludes that despite recent headwinds, the Romanian video‑game ecosystem remains a vital and expanding creative economy, but it calls for reinforced educational initiatives, stronger promotion, and strategic support to sustain momentum and mitigate external risks.
- The Romanian video game industry reached a turnover of approximately €6.6 billion in 2023, supported by 350 active studios and a workforce of 6,600 employees.
- The sector experienced a 6.6% contraction in 2022, marking the first decline in a decade due to an unfavorable global economic climate and service-sector volatility.
- Industry activity is highly concentrated in key urban hubs, led by Cluj with 36 studios and Iași, which accounts for 17.5% of the total studio count.
- The top 30 studios, including major players like Electronic Arts Romania, Ubisoft, Amber Studio Brașov, and Playtika, generate roughly 5% of the industry's total revenue.
- The Romanian gaming ecosystem serves an estimated 7.8 million players through its titles and services.
+1
RGDA – Romanian Game Developers AssociationJan 2023
Report60 pages
Digital Games' Impact in Denmark
The study evaluates how digital games shape everyday life in Denmark, measuring participation rates, motivations, and social outcomes among a representative sample of gamers. By linking behavioural data with self‑reported wellbeing, it argues that games have become a mainstream cultural activity that delivers measurable, though modest, emotional benefits while also fostering relational ties when played socially.
Among 1,172 respondents, 79 % reported playing a digital game within the past year, with weekly engagement ranging from 62 % of those aged 55‑79 to 74 % of 16‑24‑year‑olds. This high penetration underscores games as a routine leisure pursuit across age groups. Players rate gaming as an “active, rewarding break,” assigning an average relaxation score of 3.9 on a five‑point scale and an immersion rating of roughly 3.6, indicating that the activity is perceived as both soothing and engaging.
The majority of gaming occurs in solitary settings—91 % of participants play at home—and puzzle titles dominate preferences, attracting 65 % of respondents and achieving the highest relaxation scores. Nevertheless, social play, whether with friends, online strangers (12 % of gamers) or one’s own children (11 % of gamers), markedly elevates relational and community metrics; relational scores rise from an overall average of 2.1 to 2.9 for those who game with children, and empathy levels increase especially among action‑ and adventure‑game players. These findings suggest that shared gaming experiences amplify social connection, empathy, and cross‑generational bonding.
Overall, digital games in Denmark generate modest emotional gains while serving as a versatile tool for personal relaxation and, when played together, for strengthening social ties. The results highlight the dual role of games as both an individual stress‑relief mechanism and a catalyst for community cohesion within the Danish cultural context.
- Digital gaming is a mainstream activity in Denmark, with 79% of the population having played a game in the past year.
- Engagement is high across all age groups, ranging from 62% of those aged 55–79 to 74% of those aged 16–24 playing on a weekly basis.
- Puzzle games are the most popular genre, preferred by 65% of respondents and yielding the highest relaxation scores among all game types.
- Gaming is primarily a solitary, home-based activity, with 91% of participants playing at home.
- Social gaming significantly boosts relational metrics, with scores rising from an overall average of 2.1 to 2.9 when parents play with their children.
+2
NIMBI – Danish Institute for Game DevelopmentJan 2023
Report33 pages
White Paper Catalan Video Game Industry 2023
The 2023 white paper on Catalonia’s video‑game industry presents a detailed assessment of the sector’s economic performance and labour dynamics for the year 2022. It establishes that the regional market generated €709 million in revenue, reflecting a 7.5 percent decline compared with the previous year, while employment rose to 4 619 workers, an increase of 8.7 percent. This juxtaposition of falling turnover and rising headcount suggests a shift toward more labour‑intensive activities, such as development and ancillary services, even as overall sales pressures persist.
The analysis situates the sector within Catalonia’s broader creative economy, emphasizing its continued relevance as a source of high‑skill jobs and its capacity to attract talent despite modest revenue contraction. The data underline the resilience of the local ecosystem, which appears to be sustaining employment growth through diversification and possibly increased public or private investment in development capacities.
Overall, the findings portray a video‑game industry that, while facing short‑term market headwinds, maintains a solid employment base and remains a pivotal component of Catalonia’s digital and cultural output. The report implies that strategic support and continued innovation could reverse the revenue dip and further strengthen the region’s position in the European gaming landscape.
- Catalonia’s video game industry generated €709 million in revenue during 2022, representing a 7.5 percent decline from the previous year.
- Total employment in the sector grew by 8.7 percent in 2022, reaching a workforce of 4,619 people.
- The simultaneous decrease in revenue and increase in headcount indicates a strategic shift toward more labor-intensive development and ancillary service activities.
- The regional gaming ecosystem demonstrates resilience by sustaining job growth despite broader market headwinds and revenue contraction.
- The industry remains a critical component of the Catalan creative economy, serving as a primary driver for high-skill employment and digital innovation.
+3
DEVJan 2023
Report42 pages
Estudio sobre el Consumo de Videojuegos entre la Población Adulta Española y en Familia
The study investigates how video‑games are consumed in Spain, focusing on family interaction, the adoption of parental‑control tools, and the impact of streaming personalities on player behaviour. It draws on data collected in 2022 and compares it with earlier figures from 2015 to illustrate recent trends.
A striking finding is that nearly eight in ten Spanish parents reported playing video games together with their children in 2022, up from just over a third in 2015, indicating a rapid cultural shift toward shared digital entertainment within households. Despite this increase in joint play, only about thirty‑nine percent of gamers employ any form of parental control—seventeen point five percent do so regularly and twenty‑two percent occasionally—while more than forty percent never use such measures and almost twenty percent claim ignorance of them. This gap suggests limited awareness and uptake of safety mechanisms despite heightened parental involvement.
The research also highlights the growing relevance of streamers, noting that many families monitor the content creators their children follow, which further shapes consumption patterns and expectations. Overall, the findings point to a need for broader education on parental‑control options and for policies that address the influence of streaming platforms, as the Spanish gaming market continues to expand across all age groups.
- Shared family gaming in Spain has surged significantly, with nearly 80% of parents playing with their children in 2022 compared to just over 33% in 2015.
- Parental control adoption remains low, as only 39% of gamers use these tools, with 17.5% using them regularly and 22% occasionally.
- A significant portion of the gaming population is disengaged from safety measures, with over 40% of users never employing parental controls and nearly 20% reporting they are unaware of their existence.
- Streaming personalities have become a primary influence on gaming consumption, leading many Spanish families to actively monitor the specific content creators their children follow.
- The rapid cultural shift toward household digital entertainment creates a critical need for increased public education regarding available parental control mechanisms and safety policies.
+1
AEVIJan 2023
Report12 pages
Informe Mundial 2023: Comportamientos e Intereses de los Videojugadores
The 2023 Power of Play survey set out to map the motivations, social impacts and perceived wellbeing benefits of video gaming across a broad international sample. By combining responses from 12,847 active gamers who play at least once a week with findings from ten recent peer‑reviewed studies, the analysis argues that games deliver measurable social, emotional and cognitive value that extends far beyond pure entertainment.
Respondents from twelve markets—Australia, Brazil, Canada, France, Germany, Italy, Japan, Poland, South Korea, Spain, the United Kingdom and the United States—identified “having fun” as the top driver (69 % overall), followed by “entertainment” and “stress relief”. More than half of participants reported regular online play, while a third also engaged in face‑to‑face sessions. Nearly 45 % said they had met a close friend, partner or spouse through gaming, and 67 % believed games help them forge new relationships. Across the sample, 71 % felt games reduce stress, anxiety and isolation, 64 % described gaming as a healthy escape from daily problems, and 83 % reported increased happiness when playing.
Cognitive and creative gains were also prominent: 69 % linked gaming to improved problem‑solving, 65 % to greater adaptability, 60 % to enhanced communication, and 57 % to better linguistic skills. The report cites academic work that documents superior cognitive performance among gamers, reduced depressive symptoms during the COVID‑19 pandemic, and potential protective effects against age‑related memory decline and dementia. Studies of exergames and therapeutic titles further suggest benefits for pain management, motor coordination and social inclusion in clinical populations.
Methodologically, the survey employed an online, quota‑controlled panel designed to reflect each country’s demographic composition, with screening to ensure weekly gaming activity. Data were collected by AudienceNet, a market‑research firm accredited by the Market Research Society and compliant with GDPR standards. The integration of large‑scale consumer data with scholarly evidence provides a comprehensive picture of gaming’s evolving role in mental health, social connectivity and skill development worldwide.
- Gaming serves as a primary tool for emotional regulation, with 83% of players reporting increased happiness and 71% stating that games reduce stress, anxiety, and isolation.
- Social connectivity is a core outcome of gaming, as 67% of players believe games help them forge new relationships, and 45% have met a close friend, partner, or spouse through the medium.
- Players identify 'having fun' as the primary motivation for gaming (69%), followed by entertainment and stress relief as the leading drivers for engagement.
- Gaming is perceived as a driver of cognitive and professional skill development, with 69% of respondents citing improved problem-solving and 65% noting greater adaptability.
- Peer-reviewed academic research supports the survey findings, suggesting that gaming can provide protective effects against age-related memory decline and help manage depressive symptoms.
+1
AEVIJan 2023
Report38 pages
Videojuegos en el Aula: Qué se está haciendo en España
¡Hola! 👋
Veo que has compartido el título del documento y los resúmenes de las tres primeras secciones, pero aún no me indicas qué necesitas exactamente. Aquí tienes algunas ideas de lo que podría hacer por ti:
| Posible tarea | Qué incluye | |---------------|-------------| | Resumen ejecutivo | Un texto breve (≈ 200 palabras) que capture los hallazgos clave del manual y sus implicaciones para docentes y responsables de política educativa. | | Esquema estructurado | Un índice detallado con títulos y subtítulos de todas las secciones y subsecciones, listo para usar como base de un informe o presentación. | | Tabla comparativa | Consolidar la información de los juegos mencionados (título, desarrollador, plataforma, objetivo pedagógico, nivel educativo, financiación, etc.) en una tabla única y fácil de consultar. | | Recomendaciones prácticas | Propuestas de cómo integrar los juegos citados en diferentes áreas curriculares, con ejemplos de actividades y recursos de formación docente. | | Análisis de tendencias | Identificar los patrones más relevantes (p.ej., enfoque en inclusión, sostenibilidad, realidad virtual) y sugerir líneas de futuro desarrollo en España. | | Traducción / adaptación | Convertir el contenido a otro idioma o adaptar el lenguaje a un público específico (directores de centro, padres, estudiantes). | | Otro | Cualquier otra necesidad que tengas (presentación PowerPoint, infografía, guion para taller, etc.). |
¿Qué te gustaría que hiciera?
1. Selecciona una de las opciones de la tabla anterior (o combina varias). 2. Indica el nivel de detalle que prefieres (p.ej., resumen muy breve vs. informe completo). 3. Añade cualquier requisito adicional (formato, longitud, estilo, fecha límite, etc.).
Con esa información podré entregarte exactamente lo que necesitas. ¡Quedo a la espera!
- The provided document does not contain substantive data, statistics, or findings regarding the state of video games in Spanish classrooms. The content is limited to a meta-discussion about potential ways to summarize a report rather than the report itself. Consequently, no factual insights regarding the integration of video games in education can be extracted from the provided text.
+1
AEVIJan 2023
Report166 pages
Pesquisa Nacional da Indústria de Games 2023
The 2023 national survey of Brazil’s game‑development ecosystem maps the sector as it stood in 2022, revealing a vibrant but highly fragmented industry dominated by micro‑ and small studios. With 1,042 active studios and a representative sample of 309 developers, 214 freelancers and 80 support organisations, the market expanded despite a 5.1 % contraction in the global games market, delivering a 3 % domestic growth that lifted the industry to US $182.9 bn in 2022 and projecting US $206.4 bn by 2025. Brazil ranks fifth worldwide in online population, hosting roughly 103 million gamers; revenue generation is led by mobile (49 %), followed by PC (26 %) and consoles (25 %), while gender parity approaches equality with women accounting for 46.2 % of players.
Export orientation is emerging, as 76 % of developers target the domestic market but substantial shares also aim at the United States (58 %), Latin America (57 %) and Western Europe (55 %). Prospects for the next three years show Canada and Latin America each featuring in 47 % of sales roadmaps, with China appearing in 44 % of plans, indicating a gradual diversification of export destinations. The sector is supported by 17 regional industry associations and coordinated nationally by Abragames, Brazil Games and ApexBrasil, which provide market representation, business‑matching missions and participation in overseas fairs.
Artificial intelligence dominates technology priorities, cited by more than half of respondents as a short‑ and long‑term focus, while XR/VR/AR follows closely, driven by 5G and new engines such as Unreal Engine 5. Interest in blockchain and
- Brazil’s game industry grew 3% in 2022 despite a 5.1% global market contraction, reaching a valuation of US$182.9 billion with projections to hit US$206.4 billion by 2025.
- The Brazilian market is highly fragmented, consisting of 1,042 active studios that are primarily micro or small in size.
- Mobile gaming leads revenue generation at 49%, followed by PC at 26% and consoles at 25%, supported by a massive domestic player base of approximately 103 million people.
- Developers are increasingly export-oriented, with 58% targeting the U.S., 57% targeting Latin America, and 55% targeting Western Europe, while future roadmaps show growing interest in China (44%).
- Artificial intelligence is the primary technology priority for over 50% of developers, followed by XR/VR/AR applications enabled by 5G and Unreal Engine 5.
+1
AbragamesJan 2023
Report15 pages
Annual Report 2023: Canada
The 2023 annual review underscores a year of extraordinary expansion for Canada’s video‑game industry, positioning the nation as a pre‑eminent global hub for development talent and creative output. Canadian studios not only captured a record share of international awards and critical praise, but also deepened export revenues, reinforcing the sector’s contribution to the broader digital economy. Concurrently, the industry association intensified its advocacy agenda, securing more favourable regulatory frameworks and advancing diversity, equity and inclusion initiatives that aim to broaden participation across the workforce.
Financial analysis reveals that the Canadian Entertainment Software Association (ALD) concluded the fiscal year with a substantial surplus, reflecting both robust membership growth and effective cost management. The surplus enabled the organization to maintain flat membership fees for existing constituents while expanding its full‑time staff, thereby enhancing service delivery and policy‑making capacity. This fiscal stability signals confidence among stakeholders and provides a solid foundation for future strategic investments.
Geographically, the findings pertain to the Canadian market, encompassing all provinces and territories, and cover the calendar year 2023. The scope spans development studios, publishing entities, and ancillary service providers within the interactive entertainment ecosystem, as well as the association’s governance and advocacy functions.
Overall, the data illustrate a thriving, financially sound industry that is both internationally competitive and increasingly inclusive, supported by an association that leverages its surplus to reinforce member value and influence public policy.
- Canada’s video game industry experienced extraordinary expansion in 2023, solidifying its status as a global hub for development talent and creative output.
- Canadian studios achieved record-breaking international award recognition and critical acclaim throughout the 2023 calendar year.
- The sector deepened its export revenues in 2023, significantly increasing its contribution to the national digital economy.
- The Canadian Entertainment Software Association (ALD) ended the 2023 fiscal year with a substantial financial surplus resulting from robust membership growth and cost management.
- The ALD utilized its fiscal surplus to increase full-time staffing and enhance policy-making capacity while maintaining flat membership fees for existing constituents.
+1
ESAC – Entertainment Software Association of CanadaJan 2023