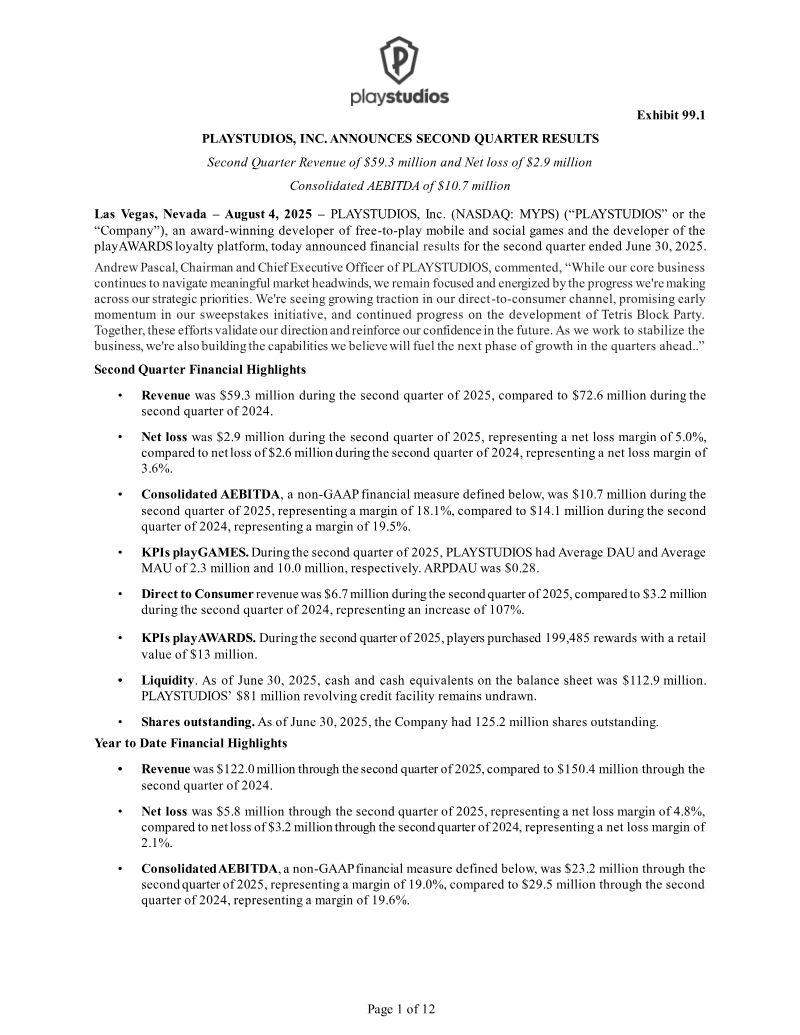
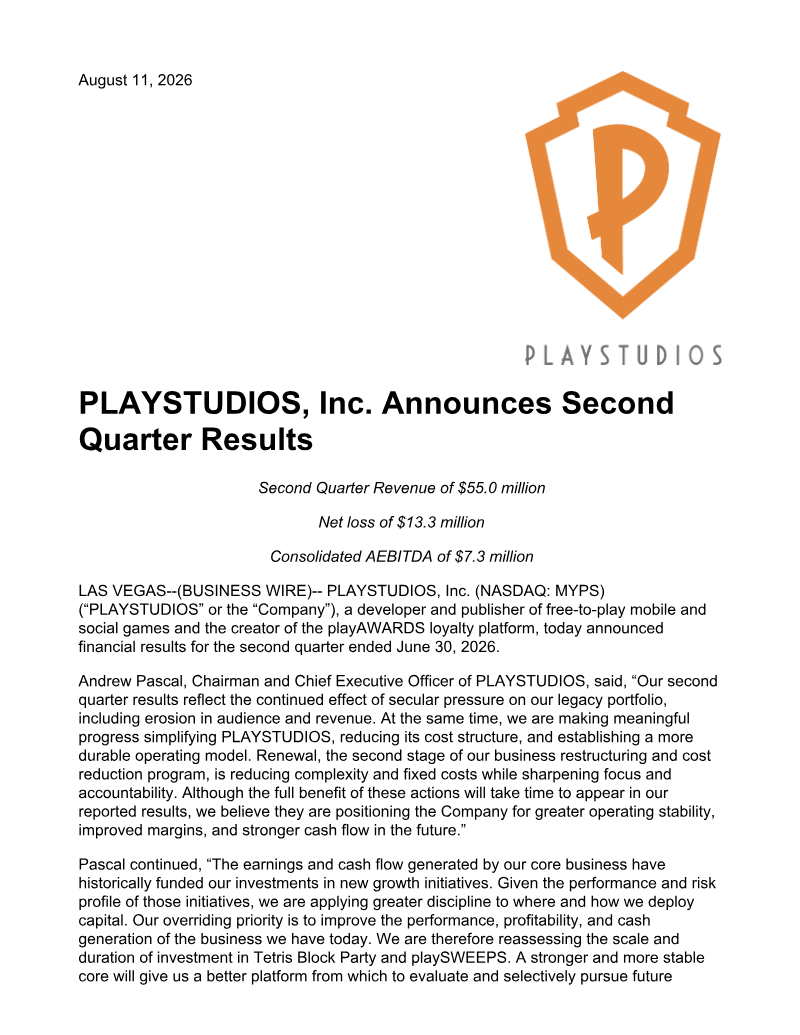
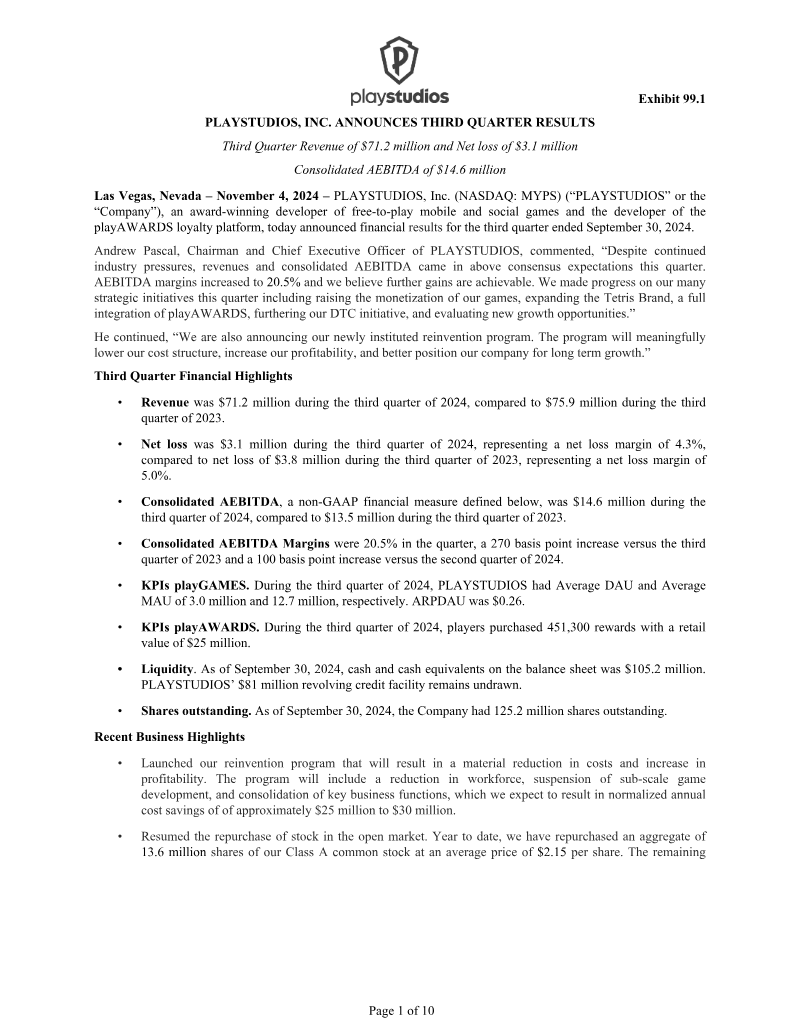
Playstudios experienced a challenging first quarter in 2026, characterized by a net loss of $10.7 million on $58.4 million in revenue. This performance represents a decline from the same period in 2025, where revenue reached $62.7 million with a smaller net loss of $2.9 million. The primary drivers of this downturn include a 7.5 percent decrease in the playGAMES segment and a significant 20.4 percent drop in average daily active users. While the company achieved a 19.2 percent increase in average revenue per daily active user, this growth was insufficient to offset rising user acquisition costs and the financial impact of a major corporate restructuring.
To address these headwinds, the company initiated a reorganization plan involving a 27 percent reduction in its global workforce and the consolidation of leased facilities. These efforts incurred $2.88 million in restructuring charges during the quarter and contributed to a 71.4 percent decline in consolidated AEBITDA to $3.6 million. Despite these operational pressures, the company maintains a stable liquidity position with $103.7 million in cash and equivalents and no outstanding balances on its $81 million revolving credit facility. Management asserts that these resources are sufficient to sustain operations for the next twelve months.
The company continues to navigate a complex legal and regulatory landscape, including ongoing class-action lawsuits and allegations concerning state gambling statutes, for which it has accrued $3.2 million in potential settlement costs. Furthermore, the business remains heavily reliant on major platform operators such as Apple, Google, Xsolla, and AppLovin. Moving forward, the strategic focus remains on leveraging the proprietary playAWARDS and myVIP loyalty programs to bolster player engagement, while the company continues to utilize its $40 million authorized stock repurchase program to manage capital allocation amidst these industry-wide pressures.