1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial report Playtika
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial reportPlaytika
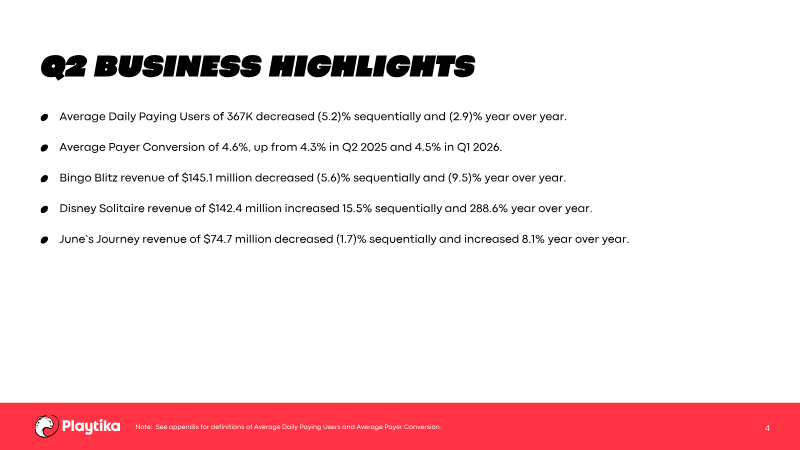
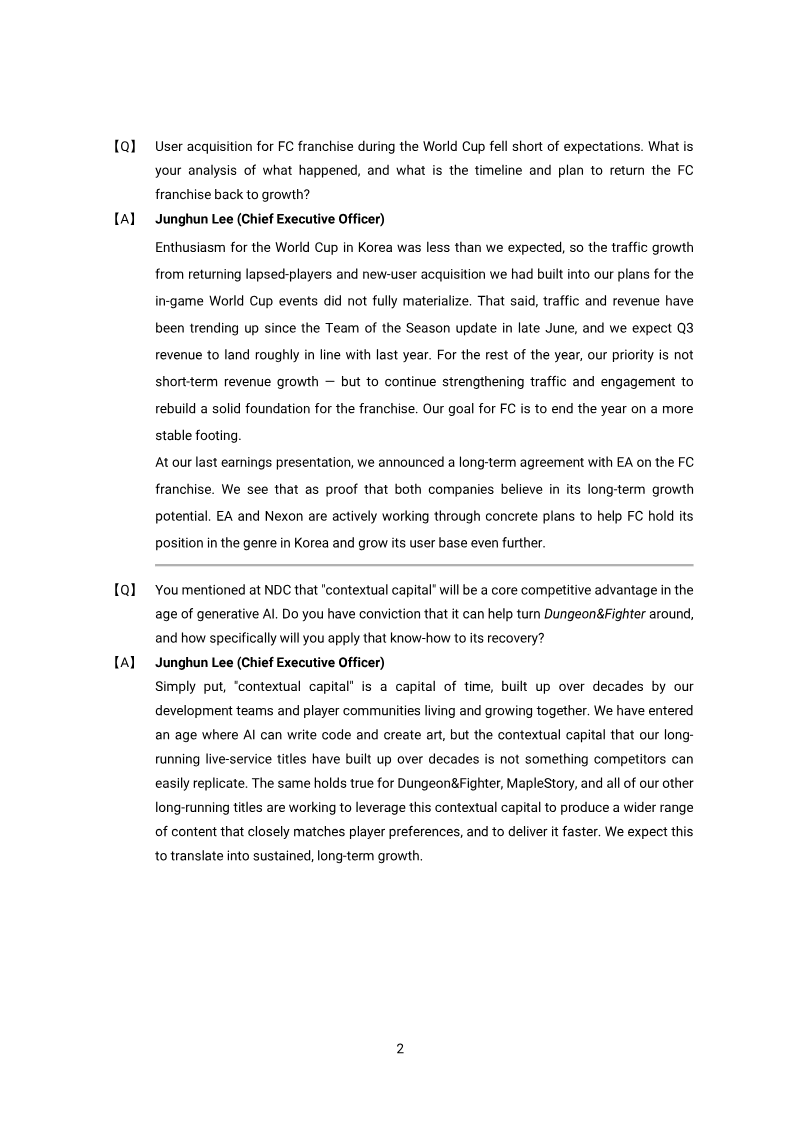
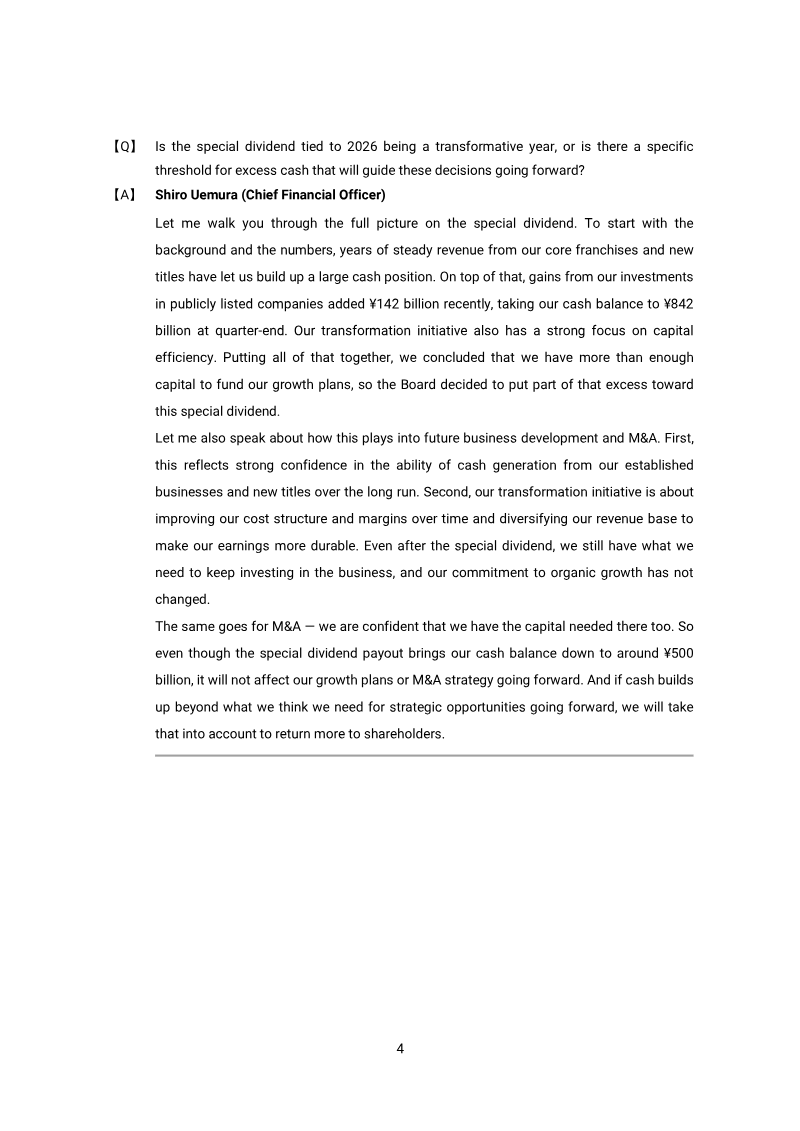
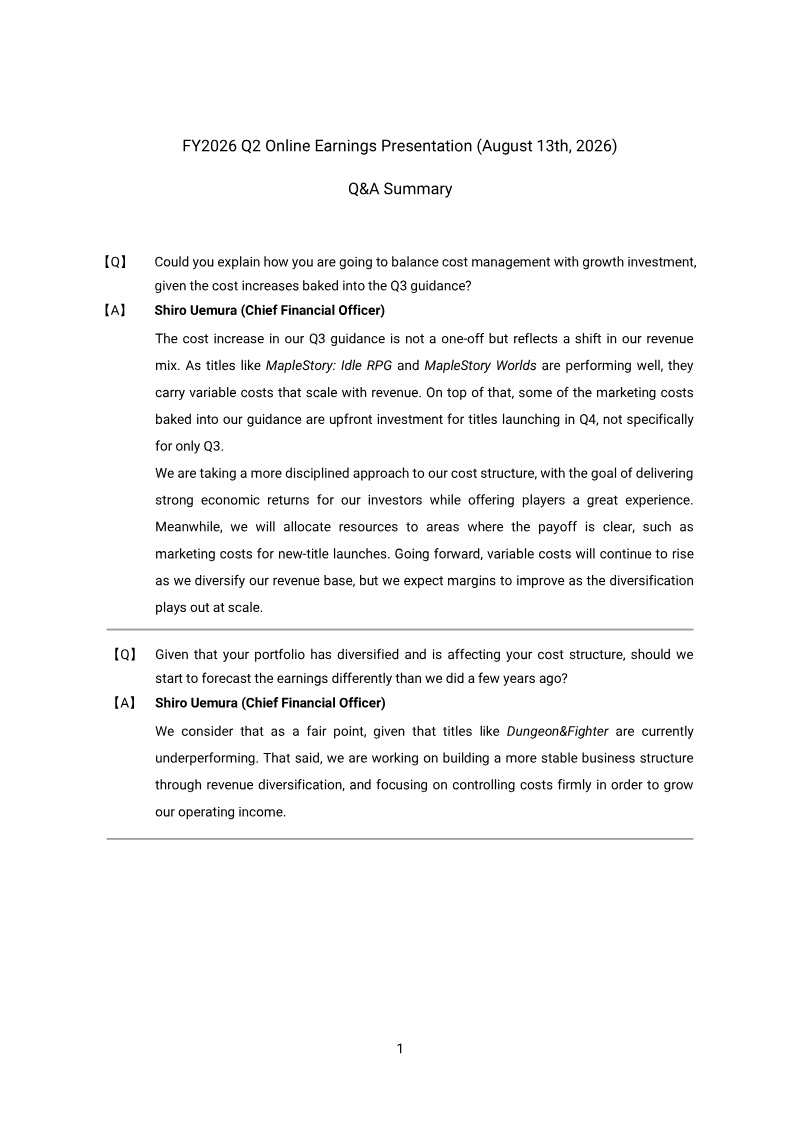
Playtika Holding Corp. reports second-quarter 2025 results, highlighting a revenue of $696 million that fell 1.4% sequentially but rose 11.0% year-over-year, driven by a mix of direct-to-consumer (DTC) and third-party platform sales. GAAP net income reached $33.2 million, an 8.5% sequential increase yet a 61.7% decline YoY, reflecting higher operating costs and lower profitability in key titles such as Slotomania. Adjusted net income contracted sharply, falling 82% sequentially and 91.4% YoY to $6.5 million, while adjusted EBITDA slipped 0.2% sequentially and 12.6% YoY to $167 million, with margins tightening from 24.0% to 23.7%. Cash and short-term investments totaled $592 million, with no near-term debt maturities and an extended revolving credit facility to September 2027.
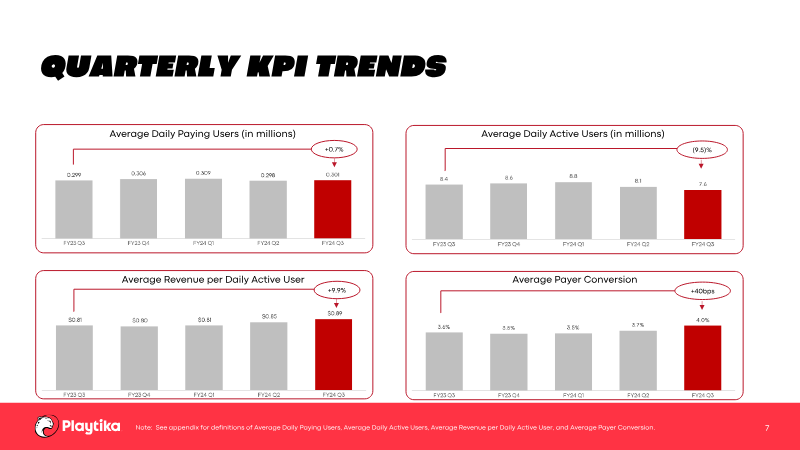
Key performance indicators show average daily paying users at 378 k, down 3.1% sequentially but up 26.8% YoY, and a payer conversion rate of 4.3%, matching Q1 levels. Game-specific revenue trends reveal Bingo Blitz maintaining near-stable sales, Slotomania declining 22.7% sequentially and 35.4% YoY, and June’s Journey slightly up sequentially but down 7.4% YoY. The company plans a global launch of the new slot game Jackpot Tour in Q4 2025.
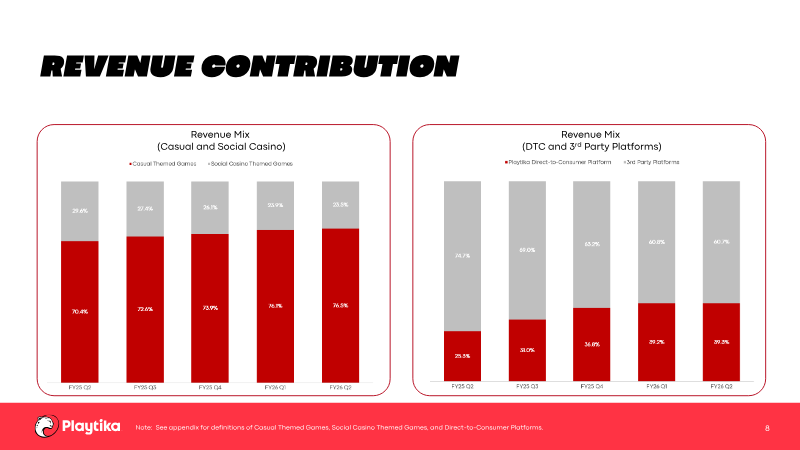
Geographically, Playtika’s revenue mix remains heavily weighted toward casual and social casino titles across DTC and third-party platforms, with no explicit regional breakdown provided. The report emphasizes reliance on a limited portfolio of games and a small user subset for revenue generation, underscoring exposure to platform policy changes and competitive pressures. Methodologically, figures are presented in GAAP terms with reconciliations to non-GAAP adjusted metrics, and the company discloses detailed definitions of key KPIs in an appendix.
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2025
Playtika