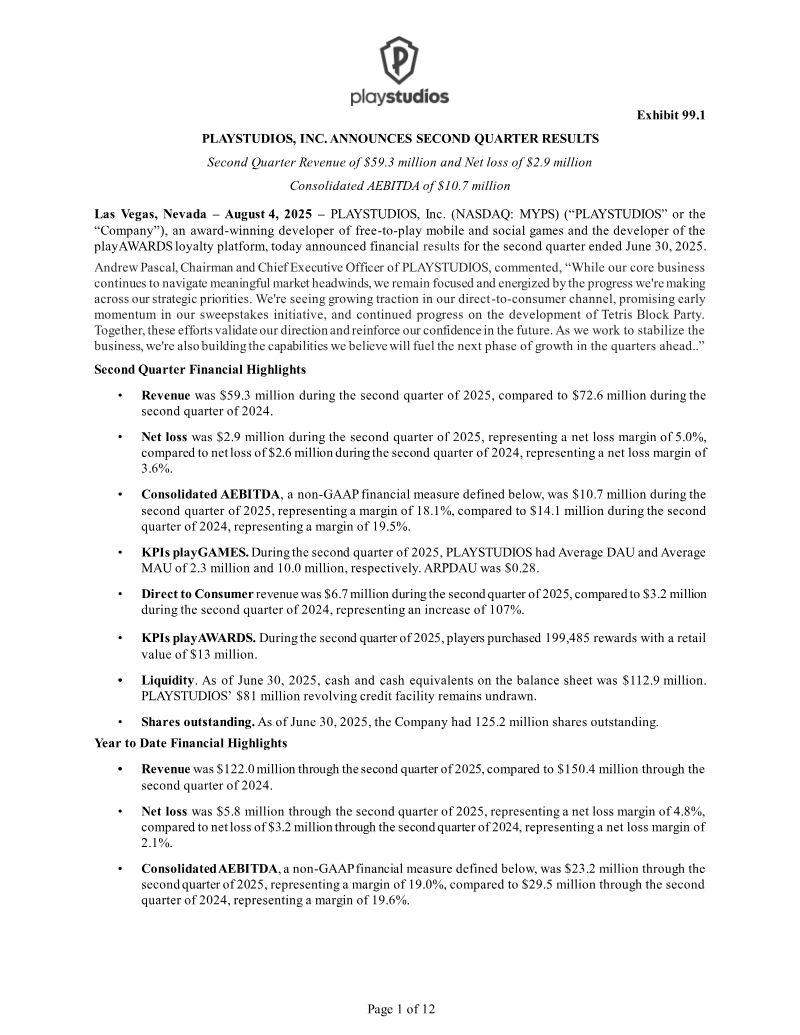
PLAYSTUDIOS, Inc. demonstrated improved bottom-line performance during the first quarter of 2024, narrowing its net loss to $0.6 million from $2.6 million in the same period of 2023. Despite this progress, the company experienced a 2.9% year-over-year decline in net revenue, which totaled $77.8 million. This revenue contraction was primarily attributed to a $4.1 million decrease in virtual currency sales, though this was partially mitigated by growth in in-game advertising revenue. Consolidated Adjusted EBITDA also saw a decline, falling to $15.3 million from $17.8 million, influenced by rising employee costs associated with the company’s loyalty and rewards programs.
The company maintains a strong liquidity position, holding $127.0 million in cash and cash equivalents as of March 31, 2024, with no outstanding debt under its $75 million credit facility. This financial stability supports ongoing operational requirements and a continued share repurchase program, through which 1.1 million shares were acquired for $2.8 million during the quarter. Management retains $47.2 million in authorized capacity for future repurchases and asserts that current liquidity is sufficient to fund operations for at least the next twelve months.
Operational risks remain a significant factor, particularly regarding the company’s heavy reliance on major platform operators, with Apple and Google accounting for 65.9% of total receivables. Furthermore, the company is actively defending against multiple class-action lawsuits and arbitration demands alleging that its gaming products constitute illegal gambling. While management maintains that these claims are meritless and has made no financial accruals, these legal challenges represent a persistent area of focus. The company continues to operate as an emerging growth company, balancing its two primary segments, playGAMES and playAWARDS, while navigating a complex regulatory and competitive landscape.