This analysis explores the structural shift toward recurrent revenue models in the global video game industry, positioning 2021 as a pivotal year for business model innovation. The central thesis posits that as gaming becomes a mainstream entertainment pillar, the industry is moving away from volatile, hit-driven product sales toward stable, subscription-based ecosystems. This transition mirrors the evolution of the film and music industries, where platforms like Netflix and Spotify have fundamentally altered consumer behavior and valuation metrics.
Key findings highlight the economic advantages of subscriptions for both platform holders and content creators. For platforms, a $10 monthly subscription generates approximately $120 in annual revenue per user, significantly outperforming the traditional $19–$32 annual margin earned from physical or digital unit sales. Microsoft’s Game Pass, with approximately 20 million subscribers at the time of writing, serves as the industry benchmark, while Sony’s PlayStation Now trails at 2.2 million. The analysis suggests that subscriptions reduce consumer "gamble" on $60 titles and solve the issue of used game sales for publishers.
The scope of the analysis covers global market trends, specifically focusing on major incumbents like Microsoft, Sony, and Nintendo, alongside emerging cloud competitors Google and Amazon. It also examines how legacy publishers like Electronic Arts and Ubisoft are adapting. A critical observation is the impact on corporate valuation: service-based firms trade at revenue multiples of 10-20x, compared to 2-5x for product-based firms. This access to cheaper capital is deemed essential for future competition over talent and intellectual property.
The methodology relies on market data from firms like Antenna, financial reports from major gaming entities, and comparative analysis of media industry trends. It concludes that publishers are evolving into "TV networks" that target specific demographics, using subscriptions to build long-term loyalty and predictable cash flow in an increasingly fragmented hardware landscape.
Success in the modern interactive entertainment industry requires a shift from competitive isolation toward collaborative partnership. The core thesis posits that sustainable entrepreneurship is built on accountability and relationship-building rather than "cult-like" corporate insularity. Within the venture capital ecosystem, the most effective founders view their peers as allies solving adjacent problems in digital creativity, transforming traditional financing into a model of friendly capital.
The analysis covers global industry trends during the 2020-2021 period, focusing on the transition to digital-first business models. Key data points highlight the resilience of tabletop gaming, with Games Workshop reporting a 26% revenue increase to $256 million despite physical store closures, driven by an 87% surge in online sales. In the mobile sector, Playtika’s $10 billion IPO valuation is supported by $1.8 billion in annual revenue and a 2.5% conversion rate of its 11.4 million daily active users. Geographically, the United Kingdom saw gaming expenditures reach $5.2 billion in 2020, with digital sales accounting for $4.9 billion of that total.
Regulatory and structural shifts are also identified as critical industry drivers. The Federal Trade Commission has signaled increased scrutiny of platform gatekeepers like Apple and Google regarding developer relations and data protection. Furthermore, major acquisitions and partnerships—such as Nvidia’s $40 billion bid for Arm and Sony’s $250 million investment in Epic Games—illustrate a strategic move toward vertical integration and the expansion of game engines into broader entertainment sectors like virtual concerts. The findings suggest that while market volatility affects firms like CD Projekt Red and GameStop, long-term success depends on maintaining transparency and fostering genuine business partnerships.
This analysis explores the strategic evolution of the video game industry as it transitions from a product-based model to a media-centric "flywheel" ecosystem. The central thesis posits that 2021 marks a turning point where novel business strategies and revenue models—rather than just hardware cycles—become the primary catalysts for growth and competitive advantage. By leveraging intellectual property across multiple engagement layers, game companies can sustain momentum even as the global pandemic's immediate impact on consumer behavior begins to stabilize.
Key findings include a projected 21% year-over-year growth for the global games market, reaching an estimated $202 billion in 2021. This valuation is supported by strong performance across mobile ($96 billion), PC ($41 billion), and console software ($25.6 billion), alongside emerging segments like live streaming and mixed reality. The industry is characterized by a "frothy" market with record-breaking early-stage venture capital deals and high-premium acquisitions, such as Microsoft’s $7.5 billion purchase of ZeniMax and EA’s $1.2 billion acquisition of Codemasters.
The scope of this outlook is global, with specific focus on major Western and Asian publishers and the impact of "Big Tech" entrants like Amazon and Google. The methodology relies on market estimation, historical financial data, and qualitative analysis of industry trends. Four emerging revenue pillars are identified as critical to the future "flywheel": subscriptions for predictable cash flow, advertising to reach younger demographics, user-generated content to strengthen network effects, and cryptocurrency to facilitate digital asset ownership.
Ultimately, the industry is moving toward a bifurcation of audiences, where high-tech consumers invest in premium hardware while others gravitate toward ad-supported or subscription-based "content buffets." Success in this new era requires firms to move beyond unit sales, focusing instead on how games can be watched, modified, and socially integrated into the daily lives of a projected three billion global gamers.
This analysis provides a retrospective on the video game industry in 2020, a year characterized by significant market growth and shifting business models amid global volatility. The central thesis posits that while the pandemic accelerated existing trends, the industry’s long-term trajectory is being shaped by the rise of user-generated content, the emergence of the metaverse as a core concept, and the ongoing struggle of Big Tech to successfully integrate into the gaming landscape.
Key findings highlight the divergent strategies of major console manufacturers: Nintendo exceeded expectations through hardware sales, Sony focused on high-quality exclusive content, and Microsoft transitioned toward a future-proofed, service-oriented business model. The year was also marked by high-profile corporate conflicts and market volatility, specifically the legal battle between Epic Games and Apple over platform economics and the troubled launch of Cyberpunk 2077. The latter resulted in CD Projekt Red disclosing specific sell-through data to stabilize investor confidence as analysts lowered sales expectations by 25% due to technical failures.
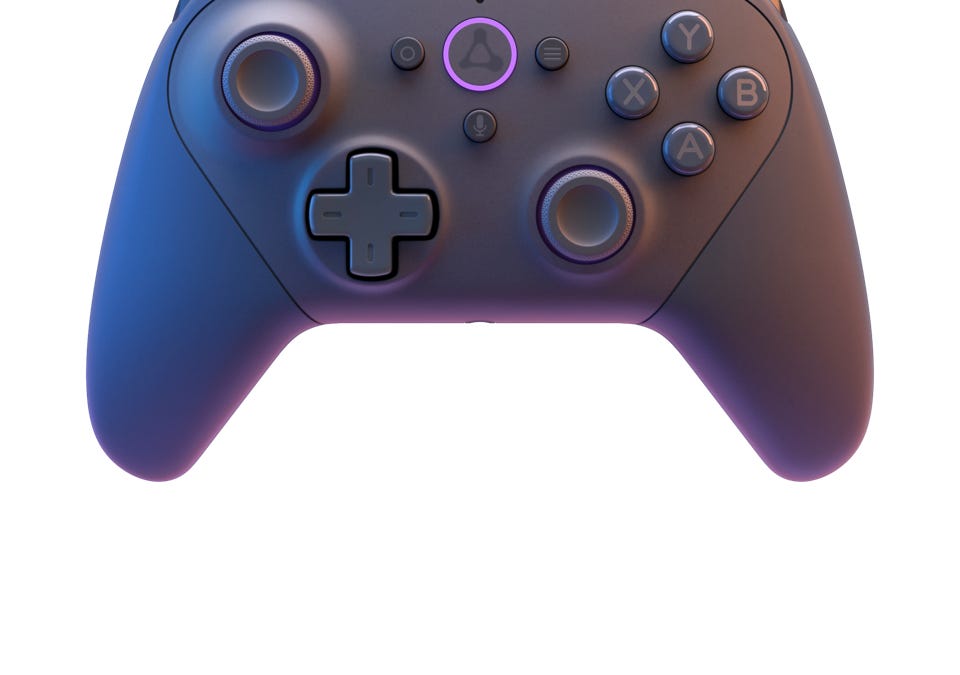
The scope of the analysis covers global industry segments including cloud gaming, mobile platforms, and social infrastructure. Data points emphasize a surge in investment and consolidation, such as Discord’s $7 billion valuation and Tencent’s $1.5 billion acquisition of Leyou. Regarding emerging technology, cloud gaming services like Google Stadia and Amazon Luna are identified as functional but currently limited by a lack of cloud-first software and ergonomic hardware solutions. The methodology relies on a synthesis of market performance data, corporate financial reports, and expert commentary on the evolving relationship between players, creators, and platform holders.
This analysis explores the volatile state of the video game industry in late 2020, centered on the controversial launch of Cyberpunk 2077. The primary thesis suggests that the game’s rocky release—characterized by technical failures, broken "no-crunch" promises, and a 33% drop in CD Projekt Red’s market value—reflects a systemic shift toward unsustainable labor practices and corporate negligence. Despite these internal failures, the game remained immediately profitable, leading to concerns that the industry may be moving toward a future where consumer trust is secondary to hype-driven capital.
The scope of the commentary extends beyond a single title to cover broader industry trends, including major mergers and acquisitions, cloud technology, and market performance. Key data points highlight a period of massive financial growth: Sony’s PS5 and Microsoft’s Xbox Series X/S launched successfully with 1.1 million and 796,000 units sold in November respectively, while the Nintendo Switch led the market with 1.3 million units. Total hardware spending rose 58% year-over-year to $1.4 billion, and mobile spending reached $112 billion, a 25% increase.
The analysis also identifies a strategic "arms race" for intellectual property and technological innovation. This is evidenced by Electronic Arts’ $1.2 billion acquisition of Codemasters to bolster its sports portfolio and Sony’s $1.2 billion purchase of Crunchyroll to consolidate its entertainment empire. Furthermore, the emergence of "native cloud games" like Rival Peak is noted as a significant evolution from traditional streaming, moving toward Massive Interactive Live Events (MILEs) that allow for true audience agency. Ultimately, the industry is depicted as being at a crossroads between institutionalizing ethical labor standards and accepting a high-growth, high-pressure corporate model.
This analysis explores the transition of blockchain gaming from a speculative "crypto-craze" to a legitimate decentralized publishing model. It frames the emergence of blockchain as the third major macro-shift in game economics, following the industry’s move from physical products to digital services and "permanent beta" models. While traditional models rely on centralized authority, the decentralized model optimizes for long-term use value and shared ownership, granting players the autonomy to alter a game’s governing rules and economy.
The findings highlight a significant investment surge, with over $1.2 billion in venture capital funding flowing into the sector over a 24-hour period, resulting in at least six "unicorn" startups valued at $1 billion or more. Despite this capital influx, the market remains top-heavy and fragmented. PC is the primary platform, hosting two-thirds of top titles, while mobile remains a critical but underdeveloped frontier due to strict platform governance. Data indicates a "winner-takes-most" dynamic, where the top-ranked game can have nearly 60 times the user base of the 15th-ranked title.
Key growth drivers include play-to-earn mechanics—particularly popular in Southeast Asia—unique digital asset minting, and the creation of secondary markets via smart contracts. However, the sector faces substantial headwinds, including a lack of high-quality content, regulatory scrutiny in the U.S. and China, and environmental concerns regarding energy consumption. Furthermore, the user base is currently skewed toward young, affluent demographics, suggesting that mainstream adoption requires improved accessibility and a move away from "clumsy" onboarding processes. The analysis concludes that while the potential for disruption is high, talent shortages and technical bottlenecks remain significant hurdles for the industry’s nascent leaders.
The 2022 South by Southwest (SXSW) conference signaled a significant shift in the cultural positioning of the gaming industry, as the sector moved to the event’s opening weekend to align with major tech and advertising brands. This transition drew a massive influx of attendees from outside the traditional interactive entertainment space, highlighting two dominant and pervasive themes: the metaverse and blockchain technology. While the metaverse is often framed as a novel solution to societal issues, its development actually spans fifteen years, and current iterations face criticism for a lack of diversity among its primary architects. Similarly, the blockchain and NFT sectors, fueled by significant capital from crypto foundations, have become central to the industry's current economic expansion, mirroring the atmosphere of the dot-com boom.
Beyond the conference, the broader industry is seeing a rapid digitization of intellectual property. Major entities like Warner Bros. are partnering with traditional toy and card makers to launch hybrid physical-digital collectibles, capitalizing on a market that has more than doubled to $5.1 billion since 2016. Simultaneously, global investment patterns are shifting. The Saudi Arabia Public Investment Fund (PIF) has aggressively expanded its influence, amassing $8.6 billion in video game shares across North America and Asia, including significant stakes in NCSoft, Nexon, and Electronic Arts. This capital infusion reflects the emergence of the Middle East and North Africa as a high-growth gaming powerhouse, with a combined audience of 65 million people in key markets.
Despite this commercial success, a growing disconnect exists between celebrated creative talent and their audiences. Some prominent designers are criticized for adopting a "mansplaining" or "pretentious" design philosophy that underestimates the digital literacy of modern players. By treating users as "giant babies" through intrusive tutorials and restrictive mechanics, these creators risk losing the human connection that defined their earlier work. As the industry matures, there is a call for developers to evolve alongside their audience, trusting in the player's intelligence rather than relying on regressive design or intoxicating futurism.
This analysis examines the intersection of technology, politics, and market economics within the global video game industry. The primary focus is Elon Musk’s announcement that xAI will launch a game studio to counter perceived ideological capture and corporate consolidation. The author challenges this premise, arguing that the industry’s true challenge is not publisher concentration but the immense power of platform gatekeepers. In 2023, eight of the ten largest gaming companies were platform holders, such as Apple, rather than content creators.
The scope of the analysis is global, covering market shifts in the United States, China, and Australia. Key data points include Sony’s confirmation of 160 million lifetime sales for the PlayStation 2 and the current reach of the PlayStation 5 at 65 million units. The text also highlights the cooling of the Web3 gaming market, noting that despite hundreds of millions in venture capital, titles like Off the Grid have failed to achieve cultural relevance. Furthermore, it addresses the potential impact of proposed U.S. tariffs on hardware and the increasing shift toward digital distribution, which may insulate software from trade barriers as physical media becomes a niche collector's market.
Methodologically, the analysis draws on corporate financial reports, market sales data, and social media announcements to contextualize current trends. It concludes that while new entrants like Musk face a difficult landscape characterized by high user-acquisition costs and softening consumer demand, strategic moves into gaming may serve as a hedge against tightening social media regulations for younger demographics.
This analysis examines the volatile intersection of blockchain technology and traditional gaming, focusing on the rapid rise of Axie Infinity and the broader strategic shifts among major tech platforms. The central thesis suggests that while play-to-earn models and NFT-integrated games have achieved significant momentum, current investor exuberance often lacks historical context. Success in the gaming industry requires more than novel monetization; it necessitates the creation of accessible, hit-driven ecosystems that can withstand inevitable competition and market corrections.
Key findings highlight the cyclical nature of gaming "sensations." While Axie Infinity has successfully leveraged its Ronin side-chain to create income opportunities in regions like the Philippines, it faces long-term pressure from emerging competitors like Illuvium, which offer more sophisticated financial structures such as double-sided staking. The analysis compares the current crypto-gaming hype to previous industry shifts, noting that while titles like World of Warcraft and Fortnite expanded the market by popularizing new genres, other "disruptors" like Rovio eventually struggled to maintain valuations comparable to established media giants like Disney.
The scope of the discussion extends to global hardware and platform trends in 2021. Valve’s Steam Deck is identified as a significant threat to the $11 billion gaming laptop market, while Netflix’s entry into gaming is viewed with skepticism based on the failed "five-step disaster" strategy previously employed by Google and Amazon. Geographically, the analysis notes a "lying flat" social trend in China and Southeast Asia, where a disenchanted younger generation is shifting time away from traditional labor toward digital consumption, potentially driving massive demand for interactive media despite government opposition.
Methodologically, the findings rely on market capitalization data, historical industry parallels, and recent corporate developments. The conclusion emphasizes that while Web3 and the Metaverse represent transformative shifts, the industry remains grounded in creative execution and the difficult task of maintaining long-term player engagement.
The collapse of Quibi serves as a primary case study for the failure of top-down, high-capital media ventures that prioritize corporate interests over user-centric innovation. Despite $1.8 billion in funding, the service failed to achieve product-market fit because it attempted to impose a rigid, "walled garden" consumption model on an audience that increasingly values organic, decentralized, and interactive media experiences. This failure highlights a broader industry thesis: technology gains life through the unintended and clever ways humans use it, rather than through expensive, closed-door development by legacy executives.
The analysis extends to several key segments of the interactive entertainment industry during late 2020. In the hardware and retail space, the strategic partnership between Microsoft and GameStop is viewed as a lopsided arrangement. While it provides GameStop with immediate capital and a share of digital revenues, it ultimately risks cannibalizing physical foot traffic by incentivizing the transition to digital subscriptions like Xbox Game Pass. In the streaming sector, the merger of Huya and DouYu under Tencent creates a dominant entity with 334 million monthly active users and a 67.5% voting share, effectively consolidating the Chinese esports and marketing landscape.
Methodologically, the findings rely on market data, financial reports, and industry deal tracking, such as the 437 gaming deals recorded in the first three quarters of 2020. The scope is global, covering North American retail trends, Chinese streaming consolidation, and the rise of "Chinese AAA" titles like Genshin Impact, which earned $100 million in its first two weeks. Ultimately, the industry is shifting toward a model where accessibility and meaningful human exchange outweigh the sheer scale of investment, as evidenced by the success of lower-tech or indie titles like Among Us and Hades compared to over-capitalized failures.
The emergence of cloud gaming services, specifically Amazon’s Luna, represents a potential disruption to the traditional video game industry model. The primary thesis suggests that while the "Netflix of gaming" concept is intoxicating, it may ultimately act as a scourge by prioritizing corporate financial stability over creative innovation. By shifting toward subscription-based recurrent revenue, tech giants aim to mitigate the financial risks inherent in a hit-driven industry, potentially leading to a "buffet of mediocrity" if these platforms fail to deliver high-quality, original content.
The analysis highlights a significant trend toward industry consolidation, exemplified by Microsoft’s $7.5 billion acquisition of ZeniMax Media and Sony’s aggressive pursuit of high-end intellectual property. While Amazon and Google possess the market capitalization to acquire major publishers—noting that Amazon’s three-day market cap growth of $35 billion could theoretically fund the purchase of Electronic Arts—they have yet to demonstrate the commitment to content necessary to compete with established gaming ecosystems. This lack of original "hit" software remains a primary barrier for tech-first newcomers.
Geographically, the scope covers global market movements in late 2020, including Alibaba’s expansion into gaming in Asia and Europe, and the $8 billion valuation of the American platform Roblox. Additional data points indicate that gaming accounts for 10% of teen wallet share, with 63% of that demographic planning to purchase next-generation consoles. The methodology relies on market analysis, financial reporting, and industry news to conclude that the success of cloud gaming will depend on whether providers prioritize consumer needs and quality IP over mere rent-seeking and financial engineering.
The global video game industry has transitioned from a niche hobby into a dominant mainstream entertainment medium by aligning creative game design with innovative business strategies. Success in this sector is not merely the result of technical prowess or artistic vision but stems from a company’s ability to apply the same level of ingenuity to its commercial operations as it does to its software development. This evolution is characterized by a shift from the sale of physical goods to digital downloads and the rise of the games-as-a-service model, which allows titles to maintain long-term cultural and financial relevance.
The analysis draws upon three decades of empirical data covering over 200 game companies, including major industry stakeholders such as Tencent, Sony, Microsoft, and Epic Games. By examining the strategic decisions of these platform holders and publishers, the research identifies how firms navigate competition and capture the cultural zeitgeist. Key case studies of massive commercial successes like Fortnite and Pokémon GO illustrate how modern gaming companies leverage data and strategic intelligence to manage global audiences and sustain profitability in a rapidly changing landscape.
The scope of this study is global and cross-segment, encompassing mobile gaming, console ecosystems, and PC distribution platforms. It dispels common industry myths by synthesizing academic research with primary financial data and executive insights. Ultimately, the findings suggest that the most successful entities in the digital era are those that embrace transparency, adapt to shifting distribution methods, and treat business strategy as a creative discipline essential for survival in the most dynamic sector of the entertainment industry.