Report4 pages
Top Game Creators Academy: 入学式/懇親会を開催しました
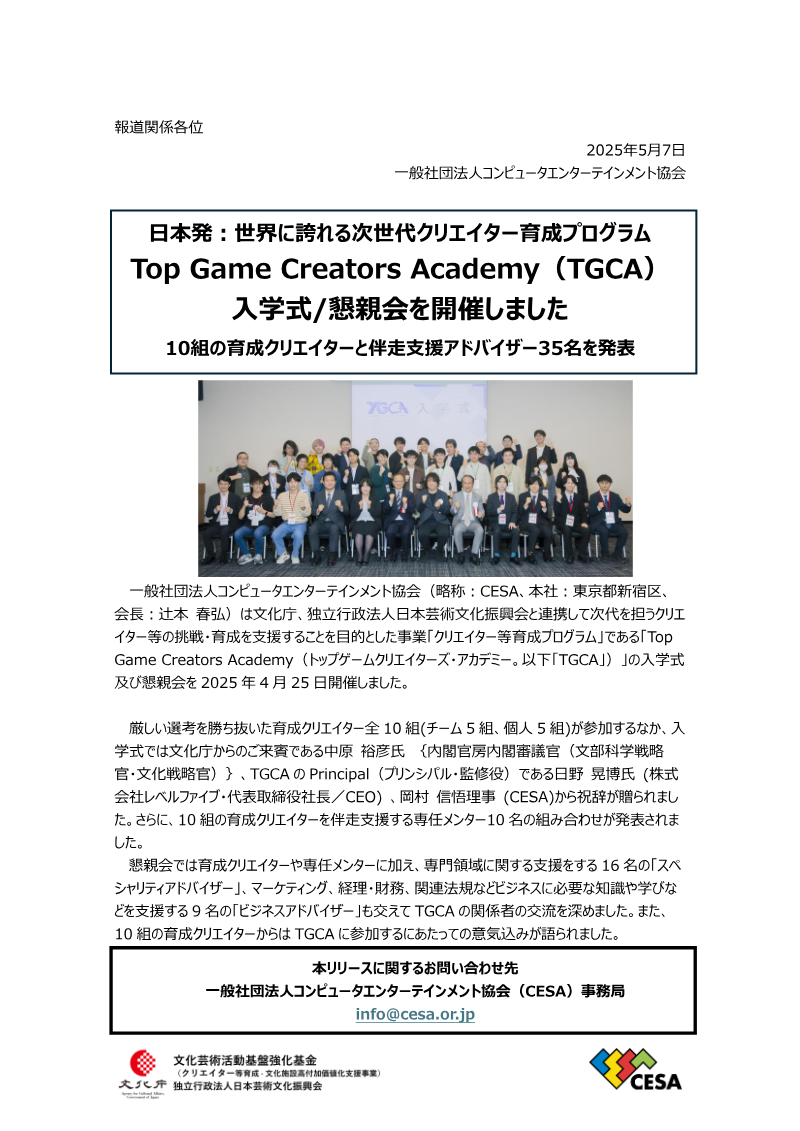
The Top Game Creators Academy (TGCA) was inaugurated on 25 April 2025 as a joint initiative of the Cultural Agency, the Japan Arts and Culture Promotion Agency, and the Computer Entertainment Association (CESA) to cultivate next‑generation game creators capable of delivering original IP that can compete globally. Ten selected teams—five groups and five individual creators—were formally admitted, accompanied by thirty‑five advisors who will provide ongoing mentorship, specialty guidance, and business support throughout a two‑year development cycle.
The program draws on the Cultural Arts Activity Strengthening Fund, allocating public resources to enable intensive, mentor‑driven training. Each creator cohort is paired with a dedicated mentor from leading studios such as Bandai Namco, Capcom, and Square Enix, while sixteen specialty advisors cover visual art, engineering, design, sound, and project management, and nine business advisors address marketing, finance, and legal matters. Progress meetings occur monthly, fostering collaborative feedback within multi‑person groups rather than one‑on‑one pairings.
Participants will showcase their work at major industry events, beginning with an online appearance at CEDEC in July 2025, a debut at Tokyo Game Show in September 2025, and subsequent exhibitions at the Taipei Game Show in January 2026, with potential expansion to international venues such as Gamescom in 2026. The cohort aims to graduate by March 2027, having refined both creative and commercial competencies to launch globally competitive titles.
- The Top Game Creators Academy (TGCA) launched on 25 April 2025 to develop globally competitive original IP through a two-year intensive mentorship program.
- The cohort consists of 10 teams—5 groups and 5 individuals—supported by a network of 35 advisors, including 16 specialty experts and 9 business consultants.
- Mentorship is provided by industry leaders from major studios, specifically Bandai Namco, Capcom, and Square Enix.
- The program is funded by the Cultural Arts Activity Strengthening Fund, a joint initiative involving the Cultural Agency, the Japan Arts and Culture Promotion Agency, and CESA.
- Participants will debut their projects at CEDEC in July 2025 and Tokyo Game Show in September 2025, followed by Taipei Game Show in January 2026.
+2
CESA – Computer Entertainment Supplier's AssociationMay 2025
Report67 pages
Studie Vlaams Gamebeleid: Eindrapport
The Flemish game industry stands at a critical juncture, requiring a strategic pivot from project-based support toward comprehensive business scaling and economic consolidation. While the sector has seen a rise in the number of studios between 2020 and 2024, growth remains heavily concentrated among a few major players, creating a fragile ecosystem characterized by a lack of mid-sized companies. To ensure long-term viability and competitiveness within the global market—which is currently valued at approximately 187.7 billion dollars—Flemish policy must evolve to address the "missing middle" by facilitating access to private capital and fostering entrepreneurial maturity.
Current support mechanisms, including the VAF/Gamefonds and the Tax Shelter, have been instrumental in initial development but are increasingly viewed as insufficient for the demands of international scaling. Global competition, driven by aggressive fiscal incentives in regions like Canada and France, necessitates a more robust and integrated financial instrumentarium. Stakeholders emphasize that while talent development remains a strength, the sector suffers from a lack of commercial focus, high production costs, and difficulties in retaining intellectual property. Consequently, there is a clear mandate to shift policy priorities toward attracting foreign investment, enhancing international promotion, and streamlining governance through a centralized strategic body.
Ultimately, the objective for the 2026–2030 period is to transition the Flemish games sector into a more stable, economically diverse industry. This requires a dual approach: optimizing existing public funding to better support commercial growth and implementing new, flexible economic tools that bridge the gap between early-stage prototyping and market-ready maturity. By aligning educational outputs with industry needs, fostering cross-sectoral collaboration, and prioritizing business development over isolated project subsidies, the region can mitigate the risks of brain drain and build a resilient, internationally recognized gaming hub.
- The Flemish game industry lacks a 'missing middle' of mid-sized companies, with growth concentrated among a few major players despite an increase in total studio numbers between 2020 and 2024.
- To compete in the $187.7 billion global market, Flemish policy must shift from project-based subsidies toward business scaling and private capital access for the 2026–2030 period.
- Existing support mechanisms like the VAF/Gamefonds and the Tax Shelter are currently insufficient to match the aggressive fiscal incentives offered by international competitors such as Canada and France.
- The sector faces structural challenges including high production costs, difficulties in retaining intellectual property, and a lack of commercial focus despite strong local talent development.
- Strategic priorities for the next five years include attracting foreign investment, enhancing international promotion, and establishing a centralized governance body to oversee industry development.
+1
Departement CultuurMay 2025
Report60 pages
The Game Development Renaissance
The global game development industry is undergoing a fundamental transition toward a more sustainable and efficient operational model, moving away from volatile hiring cycles in favor of long-term stability. With the market projected to reach $190 billion by 2025, industry leaders express significant optimism, as 77% of developers anticipate continued growth and a marked reduction in workforce instability. This evolution is characterized by a strategic shift toward leaner production cycles where studios prioritize creative intellectual property over the maintenance of internal technical infrastructure.
Central to this transformation is the widespread adoption of externalized technology and third-party backend services. While only 6% of developers intend to rely on internal builds in 2025, nearly half plan to integrate specialized third-party tools to manage complex requirements such as cross-platform synchronization and unified player inventories. By outsourcing non-core technical burdens, studios can accelerate time-to-market and mitigate the financial risks associated with building bespoke systems. This shift enables a deeper focus on LiveOps and "forever game" models, which are increasingly viewed as the primary drivers of player lifetime value and long-term revenue.
Furthermore, the industry is diversifying its financial and distributional strategies to bypass traditional gatekeepers. Developers are increasingly leveraging alternative funding sources, such as crowdfunding, and utilizing direct-to-consumer webshops to avoid high app store fees. As studios embrace sophisticated metagames and personalized engagement strategies, the integration of cross-platform capabilities and web-based distribution is becoming a strategic necessity. This new paradigm emphasizes technical agility and creative innovation, positioning the industry for a period of disciplined, technology-driven expansion.
- The global game development market is projected to reach $190 billion by 2025, with 77% of developers anticipating continued industry growth and reduced workforce instability.
- Studios are shifting toward leaner production models by outsourcing non-core technical infrastructure, with only 6% of developers planning to rely on internal builds by 2025.
- Nearly 50% of developers plan to integrate specialized third-party tools to manage complex requirements like cross-platform synchronization and unified player inventories.
- The industry is prioritizing 'forever game' models and LiveOps as the primary drivers for increasing player lifetime value and long-term revenue.
- Developers are increasingly bypassing traditional gatekeepers by utilizing alternative funding sources like crowdfunding and direct-to-consumer webshops to avoid high app store fees.
+1
MetaplayJan 2025
Report74 pages
Games Industry Employment Survey: Europe 2025
The European games industry is currently navigating a period of profound instability, characterized by widespread layoffs and a significant exodus of talent. Over the past year, 26% of professionals have faced involuntary unemployment, with junior-level staff suffering a disproportionate 39% exit rate. This volatility is driven by a transition from rapid market expansion to a focus on operational optimization, further complicated by the rapid integration of artificial intelligence. While 63% to 69% of the workforce now utilizes AI for core tasks, this shift has fostered deep-seated skepticism among creative and quality assurance roles regarding long-term job security and the potential devaluation of human expertise.
Financial dissatisfaction has become a defining feature of the current landscape, exacerbated by salary freezes, reduced bonuses, and a persistent gender pay gap. With over a third of companies eliminating financial bonuses entirely, salary has emerged as the primary motivator for 87% of employees. This economic pressure, combined with a lack of structured support—such as the absence of dedicated diversity and inclusion specialists in 67% of firms—has contributed to a sharp decline in employee engagement. Burnout, affecting up to 63% of the workforce, and ineffective management are now the leading drivers for professionals considering career changes or leaving the industry altogether.
Despite these challenges, the workforce remains committed to hybrid work models, though a growing disconnect exists between employee preferences for flexibility and actual workplace mandates. Relocation trends have shifted toward a pragmatic focus on cost-of-living stability rather than traditional geographic mobility. As the industry matures, the data underscores a critical need for improved management practices and better alignment between organizational goals and employee well-being to mitigate the ongoing loss of talent and restore professional morale across the European sector.
- The European games industry is experiencing significant volatility, with 26% of professionals facing involuntary unemployment and a 39% exit rate among junior-level staff.
- Financial dissatisfaction is widespread, as 87% of employees now prioritize salary above all else following salary freezes and the elimination of bonuses at over one-third of firms.
- Burnout affects up to 63% of the workforce, serving as a primary driver for professionals considering leaving the industry alongside ineffective management practices.
- While 63% to 69% of employees now utilize AI for core tasks, the integration has triggered deep skepticism regarding job security and the devaluation of human expertise.
- Organizational support structures are lacking, evidenced by the absence of dedicated diversity and inclusion specialists in 67% of European gaming companies.
+2
InGameJobJan 2025
Report37 pages
2025 GDC Trends Report
The global video game industry is undergoing a strategic pivot toward operational sustainability and niche market penetration as of 2025. Developers are increasingly moving away from high-risk, large-scale AAA live service projects in favor of smaller, cost-effective titles that prioritize player retention over aggressive acquisition. This shift is mirrored in the mobile sector, where hybrid-casual models and data-driven advertising are gaining prominence, alongside a notable resurgence in HTML5 gaming as a platform for broader accessibility.
Technological integration remains a primary driver of industry evolution, particularly regarding generative AI and extended reality. While AI tools are being rapidly adopted to accelerate prototyping and enhance non-player character complexity, their implementation is tempered by significant concerns surrounding copyright, ethics, and long-term job security. Simultaneously, the VR, AR, and MR sectors are transitioning toward mass-market accessibility, with a focus on affordable hardware and the development of immersive multiplayer experiences. These trends are underscored by the success of titles like Balatro, which exemplify the growing market appetite for innovative, independent-minded gameplay.
The industry is also experiencing a fundamental change in its social and structural foundations. The formalization of labor organization, exemplified by the debut of the United Videogame Workers, reflects a growing commitment to addressing developer burnout and workplace equity. Furthermore, the industry is standardizing accessibility through initiatives like the ESA’s Accessible Games program, recognizing that inclusive design is essential for long-term growth. As funding becomes more selective, developers are increasingly relying on robust community building as a primary mechanism to secure investment and ensure the viability of their projects in a competitive global landscape.
- Developers are shifting away from high-risk AAA live service projects to prioritize smaller, cost-effective titles that focus on long-term player retention.
- Generative AI is being widely adopted to accelerate prototyping and increase NPC complexity, though its use remains constrained by ongoing ethical, copyright, and job security concerns.
- The mobile gaming sector is pivoting toward hybrid-casual models and data-driven advertising, while HTML5 gaming is seeing a resurgence as a tool for broader accessibility.
- The VR, AR, and MR sectors are moving toward mass-market adoption by prioritizing affordable hardware and immersive multiplayer experiences.
- Labor organization is becoming formalized, with groups like the United Videogame Workers emerging to address industry-wide issues of developer burnout and workplace equity.
+1
Game Developers ConferenceJan 2025
Report25 pages
The Big Game Engine Report: 2025
The game engine landscape is undergoing a significant transition as developers increasingly move away from proprietary, in-house solutions in favor of established third-party platforms. This shift is driven by the need for immediate development readiness, access to advanced graphical features like Nanite and Lumen, and the ability to leverage a broader, pre-trained talent pool. While custom engines historically dominated the industry, their market share has declined sharply over the last decade, falling to approximately 13% of new releases by 2024.
Unreal Engine has emerged as the primary beneficiary of this trend, particularly among large-scale AAA studios. By 2024, Unreal Engine and custom engines collectively accounted for the majority of unit sales on Steam, with Unreal Engine 5 becoming the industry standard for high-fidelity projects. Conversely, Unity maintains a dominant position in terms of the sheer volume of games released, particularly within the indie and smaller-scale development sectors. However, Unity faces intensifying competition from smaller, specialized engines like Godot and GameMaker, which have captured a growing segment of the indie market.
The analysis, which covers over 13,000 games released on Steam, utilizes proprietary tagging and estimation methodologies to track engine adoption trends. Data indicates that engine preference is heavily influenced by game scale and genre; high-graphics, large-budget titles skew heavily toward Unreal Engine, while strategy and simulation games remain strongholds for Unity. Looking toward 2030, the industry is expected to see continued consolidation as more studios abandon legacy in-house tools to mitigate the high costs of engine maintenance, further cementing the market dominance of third-party public engines.
- Proprietary in-house engines have seen their market share of new game releases decline to approximately 13% by 2024.
- Unreal Engine 5 has established itself as the industry standard for high-fidelity, large-scale AAA projects.
- Unity maintains market dominance by volume, particularly within the indie and smaller-scale development sectors.
- Engine selection is highly correlated with project type, as high-graphics titles favor Unreal Engine while strategy and simulation games remain concentrated in Unity.
- Specialized engines like Godot and GameMaker are successfully capturing an increasing share of the indie market, intensifying competition for Unity.
+3
VG InsightsJan 2025
Report25 pages
The Big Game Engine Report: End of the Era of In-House Engines
The game engine landscape is undergoing a significant structural shift, characterized by the decline of proprietary in-house technology in favor of established third-party platforms. While custom engines historically dominated the industry, their market share has eroded substantially over the last decade, falling to approximately 13 percent of new releases by 2024. This transition is driven by the increasing complexity of modern development, which makes the maintenance of internal engines cost-prohibitive and less efficient compared to the immediate, high-fidelity capabilities offered by public alternatives.
Unreal Engine has emerged as the primary beneficiary of this trend, particularly within the AAA segment. Following the release of Unreal Engine 5, the platform has successfully reclaimed market share lost during the pandemic, becoming the preferred choice for large-scale, high-budget productions. Conversely, Unity maintains a dominant position in terms of total volume of games released, particularly among indie and smaller developers, though it faces increasing competition from smaller engines like Godot, which has seen notable growth since 2020. Despite Unity’s high release volume, Unreal Engine and custom AAA engines continue to command a larger portion of total units sold, underscoring their prevalence in high-performing commercial titles.
The analysis relies on data from over 13,000 games released on Steam, utilizing proprietary estimation algorithms and tagging methodologies to categorize engine usage by game size, genre, and unit sales. The findings indicate that while the choice of engine is often dictated by project scale—with smaller titles favoring Unity and larger, graphics-intensive projects gravitating toward Unreal Engine—the industry is moving toward a standardized ecosystem. As studios weigh the benefits of third-party support, talent accessibility, and advanced graphical features against the loss of proprietary control, the reliance on external engines is expected to continue its upward trajectory through 2030.
- Proprietary in-house engine usage has declined significantly, accounting for only 13 percent of new game releases by 2024.
- Unreal Engine has become the industry standard for high-budget AAA productions, particularly following the release of Unreal Engine 5.
- Unity maintains the highest total volume of game releases, primarily driven by adoption among indie and smaller-scale developers.
- While Unity leads in release volume, Unreal Engine and custom AAA engines command a larger share of total units sold in the commercial market.
- The open-source Godot engine has experienced notable growth since 2020, emerging as a competitive alternative to established platforms.
+3
Video Game InsightsJan 2025
Report139 pages
The Game Industry of Poland: 2025
Collective work under the direction of dr Jakub Marszałkowski dr Jakub Marszałkowski, Indie Games Poland, Poznan University of Technology (chapters 3, 5, 8, 9) Eryk Rutkowski, Polish Agency for Enterprise Development (chapters 2, 4, 6) Wojciech Trusz, Creative Industries Institute (chapters 1) Piotr Milewski, Sirius Game Studio, Gdynia Maritime University (chapters 7) Game Industry Conference team: Olga Matej, Agnieszka Wołoszyn, Kacper Żubryk, Hanna Marszałkowska, Dominik Latos Extra data minin...
- The provided report content contains only the title and author credits, lacking the body text, statistical data, or specific industry findings required to generate factual insights.
- Due to the absence of substantive data in the provided source, it is impossible to extract growth rates, company performance metrics, or industry trends for the Polish game industry in 2025.
- The source material consists exclusively of administrative metadata regarding the report's contributors and institutional affiliations.
- No concrete takeaways regarding market size, employment figures, or economic impact can be derived from the provided text.
- The input provided is insufficient to fulfill the request for a data-driven summary of the Polish game industry.
+3
Polish Agency for Enterprise DevelopmentJan 2025
Report29 pages
Game Developer Survey 2025
The 2025 Game Developer Survey captures the technology preferences and strategic shifts of game studios worldwide, focusing on platform targets, engine adoption, 3D creation tools, backend services, analytics, user‑acquisition solutions, and generative‑AI usage. By segmenting respondents across six studio‑size categories—from solo developers to enterprises with over 100 employees—the survey reveals how development priorities evolve as companies scale and as pricing models change.
Unity remains the most widely used engine, yet studios of all sizes report a notable decline in planned future use, driven by Unity’s revised pricing that introduced a 25 % increase for enterprise licenses and an $2,200 per‑seat fee for pro users. Open‑source alternatives such as Godot and Defold are gaining traction, while Unity’s ProBuilder and SideFX’s Houdini emerge as the fastest‑growing 3D modeling and level‑design tools, especially among studios under 100 employees focused on PC and web titles. Conversely, Adobe’s suite and Autodesk products experience the steepest drop‑offs, with declines ranging from 4 % to 10 % in anticipated usage.
Backend infrastructure shows a shift away from Photon, whose hybrid‑plus offering has sparked a modest decline, toward Edgegap, which leverages bare‑metal and cloud resources to deliver cost‑effective matchmaking. Xsolla’s recent rollout of loyalty programs, regional tiering, and cloud‑gaming integration underscores a broader move toward web‑based delivery and progressive‑web‑app capabilities, particularly in the MENA region. Analytics remain dominated by Google, but Mixpanel records a 120 % surge in interest, buoyed by a new startup‑focused pricing tier that promises over $150 k in value for qualifying studios.
User‑acquisition trends indicate a universal retreat from Apple Search Ads after its shift to a cost‑per‑tap model, while privacy‑centric platforms such as Tenjin and Branch experience rapid adoption, leveraging OpenAI‑enabled features and enhanced compliance tools. Generative AI is employed across a spectrum of development stages—from storyboarding to performance optimization—but studios report a consistent decline in its use for content creation, with smaller teams showing a 7 % drop and larger teams a 5 % reduction.
Overall, the survey highlights a diversification of technology stacks, a cautious response to pricing reforms, and an accelerating embrace of open‑source, cloud‑native, and AI‑augmented solutions as the industry navigates
- Unity remains the dominant engine, but studios are increasingly planning to move away from the platform following a 25% enterprise license price hike and the introduction of a $2,200 per-seat fee for pro users.
- Open-source engines like Godot and Defold are gaining significant traction as alternatives to traditional engines, while ProBuilder and Houdini have become the fastest-growing 3D modeling tools for studios with fewer than 100 employees.
- Mixpanel has seen a 120% surge in interest among developers, driven by a new startup-focused pricing tier that offers over $150,000 in value.
- User-acquisition strategies are shifting away from Apple Search Ads due to its move to a cost-per-tap model, favoring privacy-centric platforms like Tenjin and Branch that integrate OpenAI features.
- Studios are reporting a decline in the use of generative AI for content creation, with usage dropping by 7% among smaller teams and 5% among larger teams.
+2
KonvoyJan 2025
Report15 pages
El Seguro en el Ámbito de los Videojuegos
This industry guide, developed by the Spanish Video Game Association (AEVI) in collaboration with legal experts from Pérez-Llorca, serves as a strategic framework for managing risk within the video game development and publishing sectors. The primary thesis emphasizes that insurance is an essential mechanism for ensuring the financial viability of projects, acting as an indirect prevention tool against the inherent complexities of game production, such as tight delivery schedules, technical bugs, and intellectual property disputes.
The analysis identifies several critical risk categories specific to the gaming industry, including breach of delivery deadlines, transmission of computer viruses, and unauthorized data intrusions. Key findings highlight that Professional Civil Liability (RCP) and Errors and Omissions (E&O) insurance are the most vital protections for developers, covering involuntary contractual breaches and negligence. Furthermore, the guide underscores the rising importance of cybersecurity insurance to mitigate operational costs and reputational damage resulting from hacking, ransomware, and data leaks, which can trigger significant sanctions from regulatory bodies like the Spanish Data Protection Agency.
The scope of the guidance focuses on the Spanish market, referencing local legal standards and regulatory bodies, while covering the entire industry lifecycle from independent developers and freelancers to large publishers. It details specific coverage areas such as intellectual property infringement—protecting against claims regarding music, characters, and concept art—and liability for defamation or the unauthorized use of public images. Methodologically, the guide provides a practical checklist for insurance procurement, advising firms to utilize insurance brokerages for periodic contract reviews and to ensure all operational risks are disclosed to maintain policy validity.
- Professional Civil Liability (RCP) and Errors and Omissions (E&O) insurance are the primary mechanisms for protecting developers against involuntary contractual breaches and professional negligence.
- Cybersecurity insurance is essential for mitigating the operational costs and reputational damage associated with ransomware, data leaks, and hacking incidents.
- Insurance policies must specifically cover intellectual property infringement, including claims related to unauthorized use of music, character designs, and concept art.
- The Spanish Video Game Association (AEVI) and Pérez-Llorca identify breach of delivery deadlines, computer virus transmission, and unauthorized data intrusions as the most critical operational risks for game studios.
- Regulatory compliance, particularly regarding data protection standards enforced by the Spanish Data Protection Agency, is a major driver for adopting comprehensive insurance coverage.
+1
AEVIJan 2025
Report14 pages
Employment Issues in Video Game Development: Spain
The guideaims to help video‑game publishers, developers and related staff in Spain navigate employment legislation while fostering safe, productive workplaces. It stresses that compliance with the Workers’ Statute, the 2022 labour reform and the Remote‑Working Law is essential to avoid costly legal sanctions and to protect staff from the health‑risk phenomenon known as “crunch.”
Key findings highlight the danger of false self‑employment, where workers appear independent but are actually subject to employer control. Spanish courts identify dependency, subordination and fixed remuneration as hallmarks; violations can trigger Social‑Security fines of €3,750‑€12,000 per worker, plus surcharges up to 150 % of unpaid contributions. The guide confirms that indefinite contracts are the default; fixed‑term contracts are permissible only for production‑related needs or to replace absent employees, with a maximum six‑month duration for the former and 90 days per calendar year for the latter. Misusing temporary contracts converts the relationship to permanent status and incurs fines of €751‑€7,500 per affected employee.
Remote work must be voluntarily agreed, cover at least 30 % of a worker’s time, and include employer‑funded equipment costing roughly €25‑€35 per month; non‑compliance also attracts fines of €751‑€7,500. Occupational‑risk prevention is mandated under Law 31/1995, with penalties ranging from €45 to €983,736 depending on severity, and requires systematic risk analyses to curb physical and psychosocial harms linked to crunch periods. Additionally, firms must maintain objective daily time‑recording systems, respect the irregular distribution of hours (up to a 10 % pool, notified five days in advance), and implement digital‑disconnection protocols, equality plans for organisations with over 50 employees, and whistle‑blowing channels.
Overall, the guide provides a practical checklist for Spanish video‑game companies: verify contract types, assess self‑employment arrangements, formalise remote‑work agreements, enforce occupational‑risk measures, and ensure accurate time‑keeping and compliance with broader digital‑and‑equality obligations, thereby reducing legal exposure and promoting healthier work environments.
- Misclassifying employees as independent contractors can result in Social Security fines of €3,750–€12,000 per worker, plus potential surcharges of up to 150% of unpaid contributions.
- Indefinite contracts are the legal default in Spain, with fixed-term contracts strictly limited to production needs (six-month maximum) or employee replacement (90 days per year); misuse of these terms triggers fines of €751–€7,500 per employee.
- Occupational risk prevention, specifically regarding 'crunch' and psychosocial health, is mandated under Law 31/1995, with non-compliance penalties ranging from €45 up to €983,736 for severe violations.
- Remote work agreements must be voluntary, cover at least 30% of working hours, and include employer-funded equipment costs of approximately €25–€35 per month to avoid fines of €751–€7,500.
- Companies are legally required to implement objective daily time-recording systems and adhere to digital-disconnection protocols, while organizations with over 50 employees must also maintain formal equality plans and whistle-blowing channels.
+1
AEVIJan 2025
Report15 pages
Insurance in the Video Game Sector: Spain
The guide explains that insurance is a critical safeguard for video‑game development in Spain, where tight schedules, complex technical workflows and the involvement of multiple parties create a range of legal and financial exposures. Its central thesis is that appropriate coverage not only mitigates the impact of unforeseen events but also functions as an indirect prevention tool, protecting both small studios and independent creators from liabilities that could jeopardise a project’s completion and commercial success.
Key risks identified include failure to meet delivery deadlines, software bugs, transmission of computer viruses, cyber‑attacks, data‑protection breaches, intellectual‑property infringements, defamation, and malicious acts by employees. Each risk is linked to potential legal consequences such as contractual liability, third‑party compensation claims, regulatory penalties from the Spanish Data Protection Agency, and reputational damage. The guide matches these exposures to specific insurance solutions: Professional Liability Insurance (PLI) and Errors & Omissions (E&O) for contractual and professional errors; Cybersecurity Insurance for hacking, ransomware and data‑loss incidents; Multi‑Risk and General Civil Liability policies for broader operational hazards; and specialised coverage for intellectual‑property disputes, defamation and employee misconduct.
The scope is national, focusing on the Spanish video‑game sector and addressing developers of all sizes, from freelancers to larger studios. While the guide does not present original empirical research, it draws on prevailing market offerings and legal frameworks to construct a practical risk‑assessment matrix. Recommendations emphasize engaging insurance brokers to conduct tailored assessments, compare policy terms, and periodically review coverage, with clear procedural steps for application, policy issuance, amendment periods and premium payment.
Overall, the guide provides a comprehensive checklist for selecting and maintaining insurance that aligns with the specific vulnerabilities of video‑game projects, underscoring the importance of proactive risk management in a highly competitive and technically demanding industry.
- Spanish video game developers face critical financial and legal exposures from project delays, software bugs, cyber-attacks, and intellectual property infringements.
- Professional Liability Insurance (PLI) and Errors & Omissions (E&O) policies are essential to mitigate risks related to contractual failures and professional errors.
- Cybersecurity insurance is required to address specific threats including ransomware, data-protection breaches, and the transmission of computer viruses.
- General Civil Liability and Multi-Risk policies provide necessary coverage for broader operational hazards and physical or malicious acts by employees.
- Developers should engage insurance brokers to conduct tailored risk assessments and perform periodic reviews of policy terms to ensure coverage aligns with evolving project vulnerabilities.
+1
AEVIJan 2025
Report8 pages
Strategies for Creating Global Hit Formats: Exporting and Localizing K-Broadcast Formats
The interview with Jin‑Woo Hwang, CEO and executive producer of Something Special, outlines a strategic framework for turning Korean broadcast formats into globally successful products. Central to the thesis is that formats must be conceived with a “global‑oriented concept” and then deliberately exported and localized, rather than relying on passive inbound interest. Hwang identifies six core attributes—simplicity, flexibility, scalability, authenticity, compelling storytelling, and play‑along participation—that distinguish formats capable of crossing cultural boundaries, and he emphasizes the “Korean Twist,” a hybrid, genre‑blending approach that reflects Korea’s dynamic audience preferences.
The discussion situates these ideas within a practical scope that spans Asia, Europe, and North America. Something Special’s recent LEAP project with Taiwan’s Creative Content Agency, alongside new co‑development deals with major French and Spanish media firms, illustrates active outbound collaboration. Past successes such as “Grandpas Over Flowers” and “I Can See Your Voice” are cited as case studies where market insight, differentiation articulation, and extensive pitching were essential. Hwang stresses that legal risk management—registering formats with FRAPA’s Format Registration System, maintaining detailed e‑trail documentation, and constructing a “format bible” for localization—are critical to protecting intellectual property and enhancing commercial value.
Technology is addressed as both an opportunity and a challenge; AI and VR can enrich format expression, yet integrating these tools abroad requires careful cost‑benefit analysis and protection of core technologies. Hwang warns that entering the U.S. market without experience in intermediate territories often demands significant sacrifice, underscoring the need for a stepwise, experience‑based expansion strategy. Ultimately, the interview calls for Korean producers to choose active global expansion, invest in long‑term partnerships, and view format export as a dual process of contract negotiation and sustained localization, positioning Something Special as a hub for Korea’s future format IP ecosystem.
- Successful global format export requires a proactive strategy of deliberate localization rather than relying on passive inbound interest.
- Core attributes for cross-cultural success include simplicity, flexibility, scalability, authenticity, compelling storytelling, and play-along participation, often enhanced by a 'Korean Twist' of genre-blending.
- Protecting intellectual property is essential and should be managed through the FRAPA Format Registration System, detailed e-trail documentation, and the creation of a comprehensive 'format bible'.
- A stepwise expansion strategy is recommended, as entering the U.S. market without prior experience in intermediate territories often requires significant commercial sacrifice.
- Active international collaboration is demonstrated by Something Special’s LEAP project with Taiwan’s Creative Content Agency and new co-development partnerships with French and Spanish media firms.
+1
KOCCA – Korea Creative Content AgencyJan 2025
Report7 pages
Interview with Keunkyo Kim, Head of Global Business at NC AI
The interview articulates NC AI’s transformation from a game‑focused research lab into a national industrial‑AI hub, positioning Korea as a global center for “K‑AI.” It outlines the company’s ambition to leverage fourteen years of game‑AI expertise to drive cross‑industry innovation, emphasizing that AI has moved from a supporting role to a core driver of gameplay, content creation, and broader economic competitiveness.
NC AI, a subsidiary of NCSoft, has built a proprietary large‑language model called VARCO and the VARCO 3D engine, which can generate near‑realistic, physics‑based 3D environments from text or images. The firm was selected as one of five leaders in Korea’s Independent Foundation Model project and became the first Korean entity to deploy its LLM on AWS. An open‑source release of VARCO Vision 2.0 attracted over 10 000 downloads within ten days, reflecting a strategic push for global adoption and a vibrant developer ecosystem.
The company’s real‑time processing and reinforcement‑learning capabilities, honed in massive MMORPG settings, are now applied to digital twins for manufacturing, robotics, smart‑city, and defense sectors. NC AI pursues a dual‑track model—developing a 200‑billion‑parameter LLM while simultaneously creating lightweight, edge‑optimized multimodal diffusion models—to balance scale with field efficiency. Its proprietary safety filter, Safeguard, has been integrated into NCSoft’s NCER chatbot, underscoring a commitment to AI trustworthiness and standards collaboration.
Looking ahead, NC AI leads a consortium of 54 organizations to produce industry‑specific AI that validates in real‑world environments, aiming for Korean AI sovereignty and global leadership. By enabling user‑generated content through VARCO 3D, Voice, and animation tools, the firm promotes a “everyone can be a creator” ethos, encouraging young talent to contribute to a vertically integrated AI ecosystem that links industry, government, and academia and positions Korea as a powerhouse in the international AI landscape.
- NC AI is leveraging 14 years of MMORPG-based reinforcement learning and real-time processing expertise to expand from gaming into industrial sectors, including manufacturing, robotics, smart cities, and defense.
- The company is developing a dual-track AI strategy that balances a 200-billion-parameter large language model with lightweight, edge-optimized multimodal diffusion models for field efficiency.
- NC AI’s proprietary VARCO 3D engine enables the generation of physics-based 3D environments from text or images, while the open-source VARCO Vision 2.0 achieved over 10,000 downloads within ten days of release.
- As a leader in Korea’s Independent Foundation Model project, NC AI is the first Korean entity to deploy its proprietary LLM on AWS and currently heads a 54-organization consortium to drive industry-specific AI adoption.
- The firm is prioritizing AI safety and trustworthiness through its proprietary 'Safeguard' filter, which is already integrated into the NCER chatbot.
+1
KOCCA – Korea Creative Content AgencyJan 2025
Report32 pages
Association of Swedish Game Developers: 2024 Report
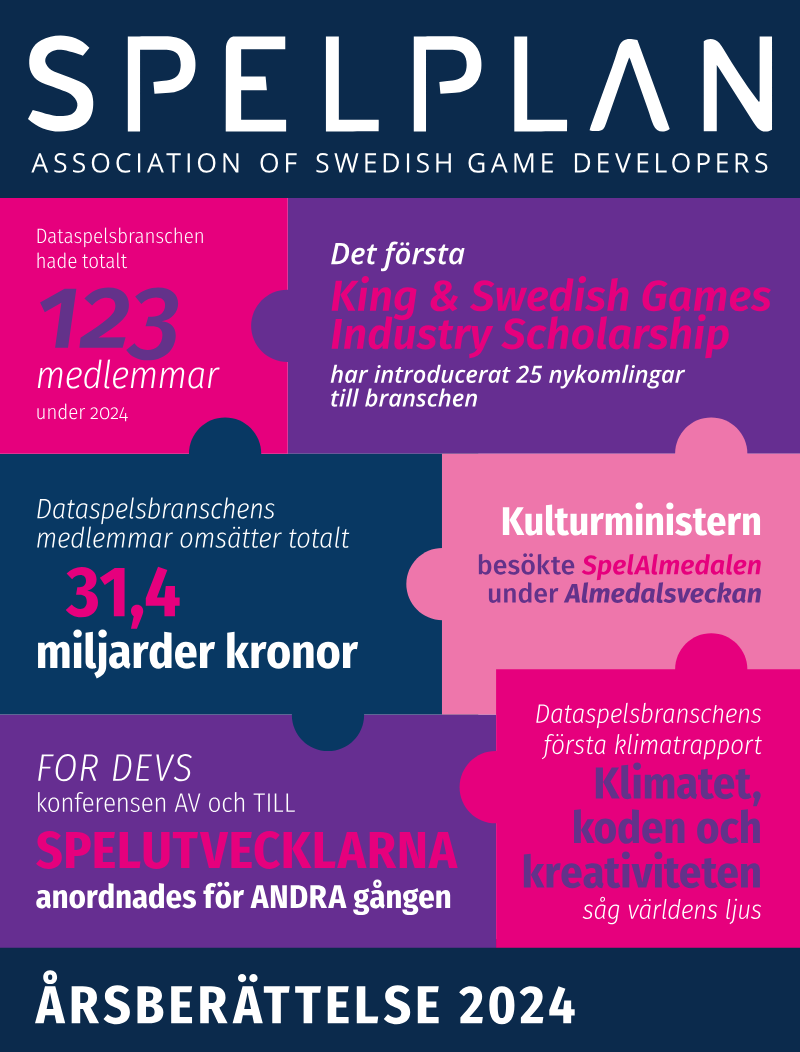
The 2024 overview of Sweden’s games industry presents a comprehensive assessment of the sector’s performance, challenges, and forward‑looking dynamics within the Swedish market. It argues that, despite a noticeable wave of studio closures, the industry remains resilient and is entering a phase of regeneration driven by regional clusters, targeted investment schemes, and internationally successful titles.
Analysis of the year shows that development activity is increasingly concentrated in hubs such as Skövde, where new studios have emerged and produced world‑hit games like Satisfactory, a title that secured both D.I.C.E. and Golden Joystick awards. This creative output underscores Sweden’s capacity to generate globally competitive products even as legacy firms exit the market. Growth is attributed largely to coordinated programmes—including Redeye Gaming Day, Invest in Games, and the EU‑funded CDG‑Booster mentoring cohort—that channel capital, mentorship, and market access to emerging developers.
The findings highlight a sector that, while contending with consolidation pressures, is expanding its export footprint and sustaining employment through the formation of new companies and the scaling of award‑winning projects. Investment in talent development and cluster formation emerges as a decisive factor in maintaining Sweden’s reputation as a leading European game‑development hub.
Overall, the 2024 snapshot confirms that Sweden’s games industry, spanning development, publishing, and ancillary services, continues to generate significant economic value and cultural impact, positioning itself for sustained growth in the coming years.
- Sweden’s games industry is undergoing a structural shift characterized by legacy studio closures offset by the emergence of new, high-performing development hubs.
- Regional clusters like Skövde have become primary drivers of industry output, exemplified by the commercial and critical success of the title Satisfactory.
- Industry resilience is supported by targeted support initiatives, including Redeye Gaming Day, Invest in Games, and the EU-funded CDG-Booster mentoring program.
- The sector is maintaining its international export footprint and employment levels by successfully scaling new companies and award-winning projects.
- Strategic investment in talent development and cluster-based infrastructure is identified as the core factor sustaining Sweden’s position as a leading European game-development hub.
+1
Spelplan-ASGDJan 2025
Report68 pages
Spelutvecklarindex: Sweden 2025
The analysis maps Sweden’s game‑development landscape, arguing that the sector’s rapid expansion has positioned the country as a leading European hub while simultaneously exposing new regulatory and societal challenges. Over the past twenty years the industry has multiplied from 71 firms with SEK 0.5 billion in revenue to more than 1 100 companies generating roughly SEK 37 billion—an increase of about 7 500 %—and employing 9 130 staff domestically, complemented by an additional 11 000 workers abroad. This growth underscores the sector’s escalating economic weight and its contribution to national employment.
Geographically, the ecosystem spans all Swedish counties, comprising over 300 development studios. The highest concentrations are found in Stockholm and its surrounding regions, notably Uppsala, Värmland and Örebro, where studio density exceeds twelve entries per county. Domestically, Swedish‑produced titles commanded the majority share of the Steam market in 2024, reflecting strong consumer preference for locally created content and reinforcing the sector’s market relevance.
Artificial intelligence has become a dual‑purpose tool within the industry: it is employed to generate novel game assets and to identify players exhibiting signs of radicalisation or harassment. The analysis stresses that radicalisation often migrates from in‑game interactions to external, unmoderated forums, distinguishing it from broader online hate. Consequently, it calls for coordinated, cross‑border interventions that involve regulators, academic researchers and game companies to mitigate these risks while preserving the sector’s innovative momentum.
- Sweden’s game industry has grown to over 1,100 companies generating SEK 37 billion in annual revenue, a 7,500% increase from the SEK 0.5 billion recorded twenty years ago.
- The sector currently employs 9,130 staff domestically and an additional 11,000 workers abroad.
- Swedish-produced titles held the majority market share on Steam in 2024, demonstrating strong consumer demand for local content.
- The industry ecosystem is comprised of over 300 development studios distributed across all Swedish counties, with the highest density concentrated in Stockholm, Uppsala, Värmland, and Örebro.
- Artificial intelligence is being utilized as a dual-purpose tool for both generating game assets and monitoring player behavior for signs of radicalization and harassment.
+1
DataspelsbranschenJan 2025
Report4 pages
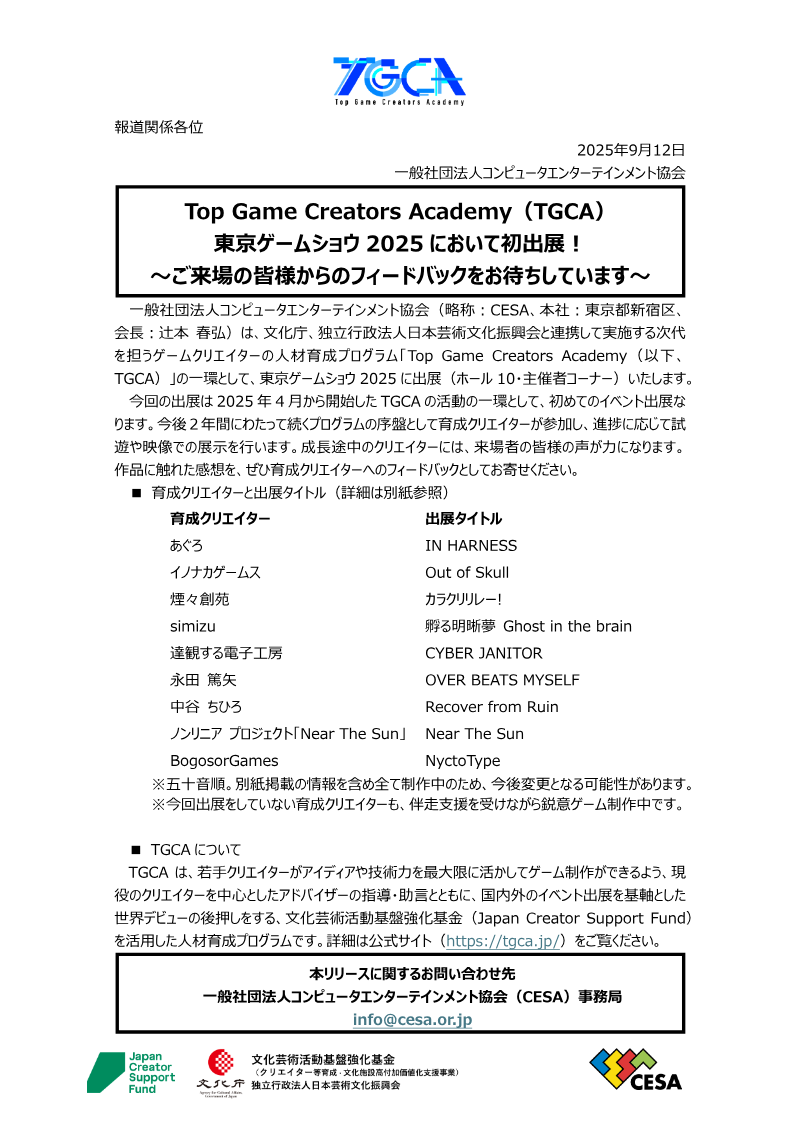
Top Game Creators Academy: Tokyo Game Show 2025 Exhibition
Top Game Creators Academy (TGCA) is being introduced to the public for the first time at the Tokyo Game Show 2025, where it will occupy Hall 10’s organizer’s corner. The initiative, run by the Computer Entertainment Association in partnership with the Agency for Cultural Affairs and the Japan Arts & Culture Promotion Agency, aims to accelerate the development of next‑generation game creators by pairing them with active industry advisors and providing exposure through domestic and international events. The exhibition showcases ten emerging developers, each presenting a work‑in‑progress title ranging from an online cooperative 3D jump‑action (IN HARNESS) to a 2D puzzle platformer (Out of Skull), a collaborative “game‑making relay” (カラクリリレー!), a first‑person horror action (Ghost in the brain), a formula‑driven shooter (CYBER JANITOR), a rhythm‑action experience (OVER BEATS MYSELF), an exploratory RPG (Recover from Ruin), a 2D stealth‑action novel (Near The Sun), and a competitive typing‑board hybrid (NyctoType). All projects remain under development and may evolve before final release.
The program, launched in April 2025, is structured as a two‑year pipeline in which creators receive ongoing mentorship and are encouraged to gather visitor impressions as direct feedback for iterative improvement. Although no quantitative metrics are provided, the breadth of genres and innovative mechanics underscores TGCA’s commitment to diversifying Japan’s game development talent pool and facilitating global market entry. The announcement concludes with a call for attendees to submit their reactions, positioning audience interaction as a core component of the creators’ growth trajectory.
- The Computer Entertainment Association, in partnership with the Agency for Cultural Affairs and the Japan Arts & Culture Promotion Agency, launched the Top Game Creators Academy (TGCA) in April 2025 to accelerate the development of next-generation talent.
- The TGCA program utilizes a two-year pipeline structure that pairs emerging developers with active industry advisors to facilitate professional growth and global market entry.
- Ten emerging developers are debuting work-in-progress titles at the Tokyo Game Show 2025 in Hall 10, representing diverse genres including 3D action, 2D puzzle platformers, horror, and rhythm-action.
- Audience interaction is a core component of the program, with creators actively soliciting visitor feedback at the Tokyo Game Show to drive iterative improvements for their projects.
- The initiative aims to diversify Japan’s game development talent pool by providing creators with exposure through both domestic and international industry events.
+3
CESA – Computer Entertainment Supplier's AssociationJan 2025
Report29 pages
The State of Games QA
This analysis explores the current state and future trajectory of quality assurance (QA) within the video game industry, specifically focusing on the integration of artificial intelligence and automation. The central thesis posits that modern game development—characterized by the complexity of games-as-a-service and accelerated release cycles—has outpaced traditional manual QA capabilities. Consequently, there is a critical need for AI-driven solutions to bridge the gap between increasing content volume and stagnant testing budgets.
The findings are based on a September 2024 survey of 303 US-based game development professionals across various disciplines, including QA, production, and design, supplemented by interviews with industry experts from companies such as Netflix and Indium Play. Data indicates a significant strain on current resources: 77% of developers admit to conducting less QA than necessary for their most recent releases, and 50% believe budgets are failing to keep pace with game complexity. While 94% of studios use some form of non-AI automation, there is a near-unanimous consensus (94%) that AI will be essential for the future of the field.
Key statistics highlight a strong industry appetite for AI adoption, with 88% of respondents viewing AI as equal to or better than traditional methods for bug detection. Developers identify faster bug detection, automated reporting, and 24/7 testing as the primary advantages of the technology. However, a significant implementation gap exists; while 87% of studios feel "somewhat ready" for AI, only 18% feel fully prepared. Primary barriers to adoption include setup complexity, high initial costs, and a lack of skilled staff. The analysis concludes that while AI is vital for scalability and stress testing, it serves as a complement to—rather than a replacement for—human intuition and creative exploratory testing.
- 77% of game developers report conducting insufficient QA for their recent releases, highlighting a critical gap between traditional manual testing and the demands of modern, complex game development.
- While 94% of studios currently utilize non-AI automation, there is a near-unanimous consensus (94%) that AI integration is essential for the future of quality assurance.
- 88% of industry professionals believe AI-driven testing is equal to or superior to traditional methods, specifically citing faster bug detection, automated reporting, and 24/7 testing as key advantages.
- Despite high interest, only 18% of studios feel fully prepared to implement AI, with setup complexity, high initial costs, and a lack of skilled staff serving as the primary barriers to adoption.
- Half of all surveyed developers report that current QA budgets are failing to keep pace with the increasing complexity of games-as-a-service models and accelerated release cycles.
+1
modl.aiJan 2025
Report19 pages
How Developers Are Using Generative AI to Create a New Generation of Games
This research, conducted by Google Cloud and The Harris Poll in mid-2025, examines the transformative role of generative AI within the global games industry. Based on a survey of 615 developers across the United States, South Korea, Norway, Finland, and Sweden, the study finds that 97% of professionals believe generative AI is actively reshaping the sector. The primary thesis suggests that while the industry faces rising development costs and market saturation, AI serves as a critical tool for innovation, democratization, and operational efficiency.
Key findings indicate that 90% of developers have already integrated AI into their workflows, primarily to automate repetitive tasks and accelerate playtesting, localization, and coding. A significant trend is the rise of AI agents—autonomous systems capable of reasoning and planning—which 44% of respondents use for content optimization and 34% for advanced NPC behavior. These technologies are shifting player expectations, with 89% of developers noting that gamers now demand more lifelike, responsive, and personalized experiences. Furthermore, 94% of developers anticipate that AI will lead to long-term reductions in development costs over the next three years.
Despite this optimism, the industry faces notable hurdles regarding legal and ethical standards. Approximately 63% of developers expressed concerns over data ownership and intellectual property, while 35% cited worries regarding player data privacy. To navigate these challenges, the study recommends that studios start with small-scale pilots, align AI use with their core creative visions, and invest in staff upskilling. Ultimately, the data portrays AI not just as a productivity booster, but as a fundamental shift in game design that enables smaller studios to compete more effectively while fostering new levels of player immersion.
- 97% of game developers believe generative AI is actively reshaping the industry, with 90% already integrating the technology into their workflows to automate tasks like coding, localization, and playtesting.
- 94% of developers anticipate that the adoption of generative AI will lead to long-term reductions in game development costs over the next three years.
- AI agents are increasingly used for advanced game mechanics, with 44% of developers utilizing them for content optimization and 34% for creating more responsive NPC behaviors.
- 89% of developers report that player expectations have shifted, with gamers now demanding higher levels of personalization and lifelike interactivity in their experiences.
- Legal and ethical concerns remain a primary barrier to adoption, as 63% of developers cite worries regarding intellectual property and data ownership, while 35% express concerns over player data privacy.
+1
Google CloudJan 2025
Report76 pages
Spelutvecklarindex 2024: Sweden
Sweden’s video‑game sector continued to expand in 2023 despite a constrained credit environment, with domestic turnover rising 6.4 % to 34.6 billion SEK and reaching 90.4 billion SEK when foreign subsidiaries are included. The number of development firms hit a record 1,010, an 8 % increase, while employment grew to 9,089 staff in the country, also an 8 % rise, although the overseas workforce fell 4 % to 15,792. Female representation improved to 23.7 % (2,150 women), yet overall profitability declined.
In 2024 the industry marked several high‑profile milestones. The Microsoft‑Activision Blizzard acquisition, valued at roughly 620 billion SEK, concluded in October 2023, and King celebrated the ten‑year anniversaries of Farm Heroes Saga and Candy Crush Soda Saga while relocating to a larger Malmö office. Mergers and acquisitions accelerated, exemplified by Embracer’s €4.9 billion sale of Gearbox to Take‑Two, Red Rover’s €212 million financing round led by Behold Ventures and Krafton, and EQT’s €28.7 billion purchase of Keywords Studios.
Inclusion efforts gained momentum, with programmes such as WINGS, Game Dev Force and King’s nine‑month mentorship supporting 27 women and non‑binary participants, and 52 studios adopting formal diversity policies. Over 300 Swedish studios were catalogued, reflecting a broadening ecosystem. The government’s 2023 cultural‑canon initiative prompted the selection of fifteen landmark digital games spanning six decades, underscoring the sector’s cultural significance.
Higher‑education institutions expanded game‑development curricula, launching new bachelor, master and specialist programmes, thereby strengthening the talent pipeline. Concurrently, research highlighted the limited relevance of traditional screen‑time guidelines for games and emphasized positive outcomes of play. Emerging risks identified include radicalisation, the legal and creative challenges posed by generative AI
- Sweden's video-game sector grew domestic turnover by 6.4% to 34.6 billion SEK in 2023, with total turnover reaching 90.4 billion SEK when including foreign subsidiaries.
- The industry reached a record 1,010 development firms, an 8% increase, while domestic employment grew by 8% to 9,089 staff despite a 4% decline in the overseas workforce.
- High-profile M&A activity remained significant, highlighted by Embracer’s €4.9 billion sale of Gearbox to Take-Two and EQT’s €28.7 billion acquisition of Keywords Studios.
- Profitability across the sector declined in 2023, even as the industry navigated a constrained credit environment.
- Diversity and inclusion initiatives gained traction, with 52 studios adopting formal policies and specific mentorship programs supporting 27 women and non-binary participants.
+1
DataspelsbranschenNov 2024