Report231 pages
The State of Video Gaming in 2026
The global video game industry is currently navigating a period of significant contraction and structural realignment following a decade of rapid expansion between 2011 and 2021. Real-term spending on game content has declined by approximately 12% since 2021, as the market shifts from a growth-oriented environment to a capital-constrained, zero-sum landscape. This downturn is marked by record-high layoffs, widespread studio closures, and a sharp reduction in venture capital funding. The industry is increasingly dominated by a small cohort of entrenched live-service titles that act as "black holes," consuming the vast majority of player time and financial resources, which makes the launch of new, independent titles increasingly difficult.
Market dynamics are further complicated by extreme resource inflation, with AAA production budgets frequently ballooning to between $200 million and $500 million. While mobile gaming remains the primary driver of global revenue, it faces its own challenges, including declining download volumes and rising user acquisition costs. Meanwhile, the console sector shows signs of stagnation, with current-generation hardware trailing its predecessors in total unit sales. As traditional growth models stall, the industry is pivoting toward new strategies, including the integration of programmatic advertising, the adoption of generative AI to improve production efficiency, and a push toward cross-platform accessibility to maximize player retention.
Geographically, the center of gravity is shifting toward Asian markets, where local developers are increasingly challenging Western incumbents with high-performing, globally resonant titles. Concurrently, the rise of user-generated content platforms like Roblox and the maturation of PC-based modding ecosystems are redefining how players engage with digital worlds. Looking forward, the industry is pinning its recovery on technological advancements in cloud computing and AI-driven development, alongside regulatory shifts that may allow developers to capture a larger share of revenue through alternative distribution channels. Success in this new era requires moving beyond traditional gameplay loops toward interconnected, persistent ecosystems that prioritize social infrastructure and long-term engagement.
- The video game industry is in a period of contraction, with real-term spending on content declining by approximately 12% since 2021.
- AAA production budgets have ballooned to between $200 million and $500 million, contributing to a capital-constrained environment marked by record-high layoffs and studio closures.
- A small cohort of entrenched live-service titles now dominates the market, acting as 'black holes' that consume the majority of player time and spending, making new independent launches increasingly difficult.
- The industry is pivoting toward generative AI to combat production cost inflation and integrating programmatic advertising to offset stalling growth in traditional console and mobile sectors.
- The global center of gravity is shifting toward Asian markets, where local developers are increasingly challenging Western incumbents with high-performing, globally resonant titles.
+2
EpyllionMay 2025
Report37 pages
2025 GDC Trends Report: Connecting the World Through Games
The global game industry in 2025 is defined by a strategic pivot toward practical generative AI implementation and sustainable monetization models in response to market saturation and rising development costs. Approximately one-third of developers now utilize AI tools to streamline prototyping and NPC creation, focusing on "human-in-the-loop" workflows to enhance personalization. However, this technological shift is met with significant friction regarding ethical sourcing, copyright concerns, and the potential displacement of narrative designers. To combat AAA stagnation, studios are increasingly adopting "niche" live service models and "hybrid-casual" mobile strategies, leveraging telemetry for personalized monetization and prioritizing player re-acquisition over expensive new user acquisition.
Financial sustainability has become a primary concern, with 56% of studios now relying on personal funding as the publishing landscape becomes more selective. This has led to a surge in self-publishing and the adoption of HTML5 and WebGPU technologies for more efficient cross-platform distribution. The mobile sector reflects this shift, with narrative-driven advertising propelling the in-game ad market to $100 billion in 2024, officially surpassing in-app purchase revenue. Simultaneously, the industry is embracing social responsibility through the Accessible Games Initiative, which introduces standardized storefront tags to assist the 16% of the global population living with disabilities.
The labor market is undergoing a historic transformation, marked by a 17% layoff rate that has catalyzed the formation of the United Videogame Workers union. Despite these workforce challenges, technical innovation continues across hardware and software, evidenced by the rise of affordable mixed-reality devices and the debut of high-performance handheld platforms like the Snapdragon G3 Gen 3. Creative excellence remains a central pillar of the industry, as demonstrated by the indie title Balatro winning Game of the Year at the 2025 Game Developers Choice Awards, signaling that innovative, community-focused projects can still achieve massive success in a highly competitive global market.
- The mobile in-game advertising market reached $100 billion in 2024, officially surpassing revenue generated from in-app purchases.
- Financial instability has forced 56% of studios to rely on personal funding as the publishing landscape becomes increasingly selective.
- The industry is experiencing a 17% layoff rate, which has served as a primary catalyst for the formation of the United Videogame Workers union.
- Approximately one-third of developers are now integrating generative AI into workflows for prototyping and NPC creation, despite ongoing ethical and copyright concerns.
- Studios are shifting focus from expensive new user acquisition to player re-acquisition, utilizing telemetry to drive personalized monetization in niche live service and hybrid-casual models.
+1
Game Developers ConferenceMay 2025
Report19 pages
Global Gaming Report: Q1 2025
The global gaming industry experienced a significant resurgence in financial activity during the first quarter of 2025, marked by a substantial rebound in mergers, acquisitions, and private placements. Total deal value for the quarter reached $4.4 billion across 48 announced transactions, representing the highest quarterly valuation in nearly two years. This momentum was primarily driven by large-scale strategic consolidations, such as the $3.5 billion acquisition of Niantic’s games division by Scopely and AppLovin’s $900 million studio spin-off. Simultaneously, private investment surged to $3.5 billion across 149 deals, anchored by a landmark $3 billion investment into Infinite Reality at a $12.25 billion valuation.
Investment trends during this period shifted toward AI-driven entertainment and mobile user acquisition technologies. Strategic players like Savvy Games Group and Tencent maintained leadership roles in capital deployment, while venture capital firms such as BITKRAFT and Andreessen Horowitz remained the most prolific investors by volume. Geographically, the Asian developer market demonstrated steady stability with a median revenue growth of 9%, while the hardware and tools sector outperformed broader segments with a 20% average revenue increase. This growth was heavily influenced by the dominance of NVIDIA, which saw a 114% year-over-year revenue surge, positioning it as a cornerstone of the industry’s infrastructure with a $2.6 trillion market capitalization.
Despite the overall recovery reflected in the 16.37% return of the Drake Star Gaming Index, the market exhibited extreme volatility among individual public companies. While Sea Limited experienced a dramatic 223% increase, established entities like Unity and Ubisoft faced significant downturns, with valuations falling by over 50%. This divergence highlights a period of intense transition where hardware providers and AI-integrated platforms are capturing the majority of market gains, while traditional software developers and engine providers navigate a more challenging and fragmented economic landscape.
- The gaming industry saw a major financial rebound in Q1 2025, with $4.4 billion in M&A deal value across 48 transactions and $3.5 billion in private investment.
- NVIDIA has become a critical industry infrastructure pillar, achieving a 114% year-over-year revenue surge and a $2.6 trillion market capitalization.
- Private investment was anchored by a $3 billion funding round for Infinite Reality, which reached a $12.25 billion valuation.
- Market performance is highly polarized: while the Drake Star Gaming Index rose 16.37%, companies like Sea Limited grew 223% while Unity and Ubisoft saw valuations drop by over 50%.
- Strategic consolidation was led by major deals including Scopely’s $3.5 billion acquisition of Niantic’s games division and AppLovin’s $900 million studio spin-off.
+1
Drake Star PartnersApr 2025
Report24 pages
Live Streaming Trend Report: Q2 2025
Live‑streaming activity in the second quarter of 2025 expanded by five percent year‑over‑year, pushing total consumption past the nine‑billion‑hour mark for the first time since late 2021. The surge was led by YouTube Gaming, which recorded a historic 2.2 billion hours watched, while Kick’s creator‑incentive scheme lifted its viewership share by 5.5 percent. In contrast, Twitch’s share slipped 4.6 percent, dropping below five billion hours for the first time in nearly five years. These dynamics illustrate a reshaping of platform dominance, with emerging services gaining traction at the expense of long‑standing incumbents.
Esports consumption followed a parallel upward trajectory, rising six percent to a record 729 million hours despite a 37 percent contraction in the number of tournaments held. The sector’s growth was driven by a pivot toward mobile titles, co‑streaming formats, and creator‑led events, exemplified by the Rainbow Six Siege Invitational 2025. This shift underscores a broader trend in which audience engagement is increasingly tied to personalities and flexible production models rather than traditional tournament structures.
Content analysis highlights the ascendancy of hybrid formats that blend gaming with established intellectual properties, such as “Den Ring Nightreign” and “Survival Games with Dune.” VTuber Usada Pekora emerged as the most‑subscribed creator, confirming the expanding influence of virtual personalities. Collectively, cross‑genre collaborations, VTuber‑centric audiences, and creator‑driven esports are identified as the primary engines propelling live‑streaming growth throughout 2025, signaling a continued evolution toward integrated, personality‑focused entertainment across the global market.
- Live-streaming consumption reached over nine billion hours in Q2 2025, a five percent year-over-year increase driven by YouTube Gaming's record 2.2 billion hours watched.
- Twitch’s market share declined by 4.6 percent, causing its quarterly viewership to drop below five billion hours for the first time in nearly five years.
- Kick grew its viewership share by 5.5 percent during Q2 2025, bolstered by the platform's active creator-incentive programs.
- Esports viewership rose six percent to a record 729 million hours, even as the total number of tournaments contracted by 37 percent.
- Audience engagement in esports is shifting away from traditional tournament structures toward mobile titles, co-streaming, and creator-led event formats.
Stream HatchetApr 2025
Report50 pages
State of Mobile Gaming 2025
The global mobile gaming market entered a period of mature recovery in 2024, characterized by a strategic pivot toward live services and high-value player retention. While total downloads declined by 6.6%, global in-app purchase revenue grew by 4% to reach $82 billion. This growth was primarily driven by North America and the Middle East, offsetting spending declines in Asia. The industry has transitioned into a "live operations" era, where 84% of all revenue is generated by games utilizing continuous updates and seasonal events. This shift is further evidenced by a 50% decrease in new game releases since 2020, as publishers prioritize high-quality core titles over volume.
Genre performance highlights a market dominated by Strategy and RPG titles, which collectively generated over $34 billion in 2024. Action games emerged as the fastest-growing category with a 46% revenue increase, fueled by breakout hits like Last War: Survival. Despite the dominance of established franchises, a record 11 games surpassed $1 billion in annual consumer spend, including MONOPOLY GO!, which secured the top global position. The market is also seeing a demographic shift, particularly in the United States, where the 18-24 age group now represents 18% of the player base, up from 13% in 2022.
Marketing strategies have evolved to combat rising user acquisition costs, with a significant move toward high-intent creative content and short-form video platforms. TikTok experienced a 67% year-over-year growth in social ad share, while mid-core developers nearly doubled their impression share on social networks. To maintain profitability, publishers are increasingly leveraging external web stores, celebrity partnerships, and localized cultural influencers, such as virtual YouTubers in the Japanese market. These trends underscore a broader industry movement toward sophisticated monetization models and IP-driven growth in an increasingly concentrated competitive landscape.
- Global mobile gaming revenue grew 4% to $82 billion in 2024 despite a 6.6% decline in total downloads, signaling a shift toward high-value player retention.
- The industry has entered a 'live operations' era, with 84% of total revenue now generated by games utilizing continuous updates and seasonal events.
- Publishers have reduced new game releases by 50% since 2020, focusing resources on high-quality core titles rather than volume.
- Strategy and RPG titles remain the market leaders with over $34 billion in combined revenue, while Action games emerged as the fastest-growing category with a 46% revenue increase.
- A record 11 games surpassed $1 billion in annual consumer spend in 2024, with MONOPOLY GO! securing the top global position.
+1
Sensor TowerMar 2025
Report17 pages
Games Investment Review: Q1 2025 Executive Summary Report
The Q1 2025 Games Investment Review provides a comprehensive analysis of global financial activity within the video game industry, covering investments, mergers and acquisitions (M&A), and initial public offerings (IPOs). The report identifies a significant recovery in market activity, noting that the combined value of investments and M&As reached $7.8 billion across 245 transactions. This represents the largest quarterly total since late 2023 and the second consecutive quarter of growth, signaling a stabilizing investment landscape.
Key findings highlight a massive surge in investment value, which rose 370% quarter-over-quarter to $4.4 billion. This growth was primarily driven by a $3.0 billion mid-to-late-stage investment in Infinite Reality. While M&A volume hit a two-year high with 55 transactions, the total reported value fell to $3.3 billion, largely because 80% of these deals did not disclose financial terms. The exit market showed strength through Asmodee’s $2.2 billion IPO and several billion-dollar acquisitions, such as Miniclip’s purchase of Easybrain. Additionally, new fund announcements reached a three-year peak of $21.8 billion, with 65% of that capital concentrated in five major funds.
The scope of the research encompasses diverse industry segments, including Console/PC, Mobile, Tech/Other, eSports, and Web3/Blockchain. Geographically, activity was led by Asia and Europe, while North America contributed high transaction volume with lower disclosed values. Methodology relies on a proprietary database tracking officially closed deals rather than mere announcements, ensuring data reflects actual capital deployed. The analysis emphasizes that artificial intelligence and blockchain remain primary areas of investor enthusiasm, with AI-related game investments totaling $3.1 billion during the quarter.
- Global gaming investment and M&A activity reached $7.8 billion across 245 transactions in Q1 2025, marking the highest quarterly total since late 2023.
- Investment value surged 370% quarter-over-quarter to $4.4 billion, largely driven by a single $3.0 billion mid-to-late-stage investment in Infinite Reality.
- New fund announcements hit a three-year peak of $21.8 billion, with 65% of that capital concentrated within just five major funds.
- Artificial intelligence remains a primary investment driver, accounting for $3.1 billion in game-related funding during the quarter.
- M&A volume reached a two-year high of 55 transactions, though total disclosed value was limited to $3.3 billion because 80% of deals did not report financial terms.
+1
Digital Development ManagementMar 2025
Report42 pages
Mobile App Trends: 2025 Edition
The mobile app economy is entering a significant scaling phase, with global consumer spending projected to reach $626 billion by 2030. This growth is underpinned by a 2024 surge in app installs and a notable rise in App Tracking Transparency opt-in rates to 35%, suggesting that privacy-centric measurement is successfully rebuilding user trust. As the industry moves into 2025, the integration of artificial intelligence and machine learning has transitioned from a conceptual trend to an operational necessity, particularly for predictive analytics and campaign optimization across diverse platforms like Connected TV and in-app advertising.
Mobile commerce currently serves as the primary driver of the digital landscape, accounting for 73% of global e-commerce sales with anticipated 2025 revenues of $2.5 trillion. While e-commerce app installs grew by 17% in 2024, the sector must navigate rising acquisition costs, which have reached an average of $3.44 per install. This financial pressure is particularly acute in emerging markets such as MENA and LATAM, where reliance on paid media is increasing. Simultaneously, the mobile gaming sector remains the most popular category, expected to reach $126.1 billion in 2025. Although gaming faces retention challenges in North America and Europe, strategy games have seen an 83% growth in installs, and global session lengths have extended to over 30 minutes.
The financial services vertical is also experiencing a period of robust expansion, especially within the APAC and LATAM regions. Global session lengths for finance apps have risen to 6.66 minutes, while average revenue per monthly active user has climbed significantly to $4.10. Across all sectors, the 2025 outlook emphasizes a shift toward omnichannel strategies and a rebound in mobile-first holiday shopping. Success in this evolving market requires developers to balance aggressive growth in high-potential regions with sophisticated, privacy-compliant data strategies to maintain long-term user engagement.
- Global mobile consumer spending is projected to reach $626 billion by 2030, supported by a 2024 surge in app installs and a 35% App Tracking Transparency opt-in rate.
- Mobile commerce accounts for 73% of global e-commerce sales, with 2025 revenues expected to hit $2.5 trillion despite rising acquisition costs averaging $3.44 per install.
- The mobile gaming sector is projected to reach $126.1 billion in 2025, with strategy games experiencing an 83% growth in installs and global session lengths exceeding 30 minutes.
- Financial services apps are seeing robust expansion in APAC and LATAM, with average revenue per monthly active user reaching $4.10 and session lengths increasing to 6.66 minutes.
- Artificial intelligence and machine learning have become operational necessities for predictive analytics and campaign optimization across Connected TV and in-app advertising.
+1
AdjustMar 2025
Report5 pages
Newzoo’s Games Market Reports & Forecasts Q1 2025 Update
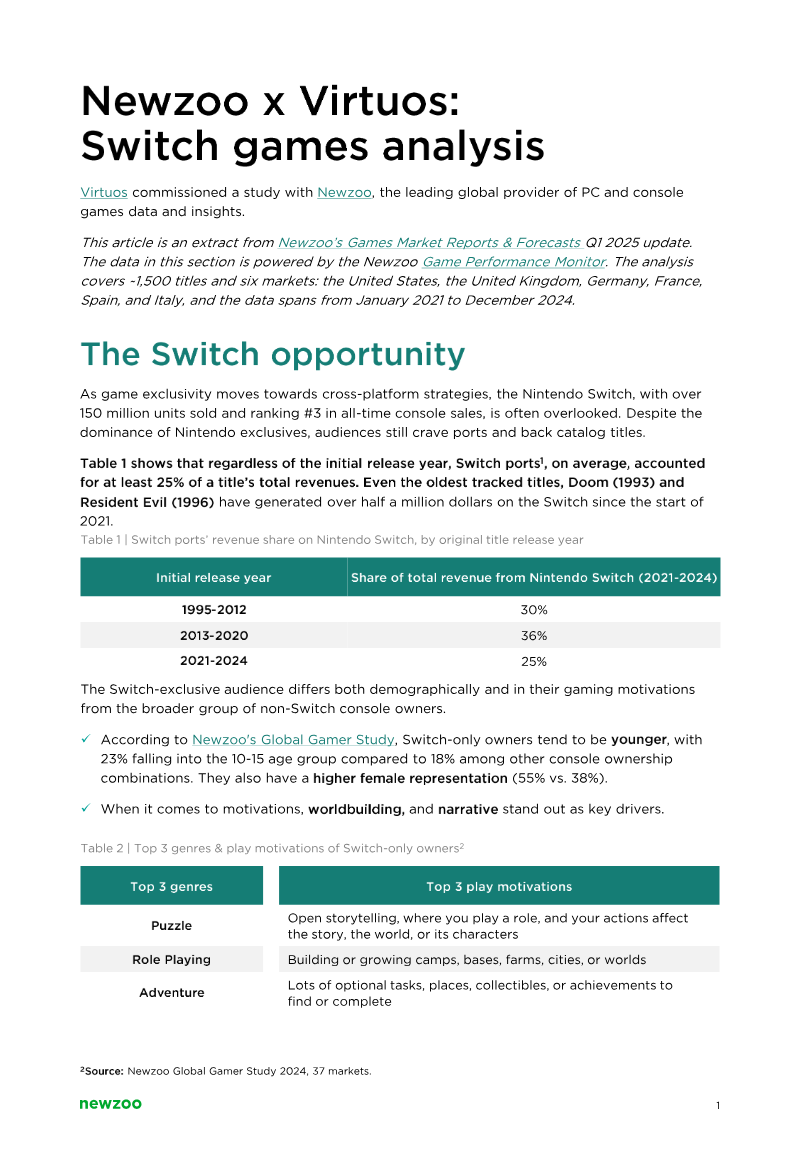
This analysis examines the Nintendo Switch market landscape from January 2021 to December 2024, focusing on the performance of third-party ports across the United States, United Kingdom, Germany, France, Spain, and Italy. Utilizing data from approximately 1,500 titles, the study highlights that while Nintendo-published exclusives dominate the platform, third-party ports represent a significant and growing revenue stream. By 2024, ports accounted for over a third of the console's revenue, a trend accelerating as the industry anticipates the transition to the next generation of hardware.
The findings reveal a distinct demographic and motivational profile for Switch-only owners. This audience is younger than the broader console market—with 23% aged 10-15—and features a higher concentration of female players at 55%. Their primary gaming motivations include immersive storytelling, world-building, and completionism. Consequently, genres such as Role-Playing, Simulation, and Platformers consistently outperform others. Role-Playing titles are particularly successful, with over one-third of ported RPGs generating more than $1 million in revenue.
The data distinguishes between simultaneous and staggered releases, noting that staggered ports often achieve higher average revenue per title due to major hits like Hogwarts Legacy, while simultaneous releases capture a higher percentage of total cross-platform revenue share. Fighting games also emerge as high performers when tied to strong intellectual properties. Ultimately, the analysis concludes that while the Switch offers substantial long-tail revenue opportunities, success depends on navigating technical hardware limitations and aligning game design with the specific preferences of the handheld audience.
- Third-party ports have grown to account for over one-third of total Nintendo Switch revenue as of 2024.
- The Switch audience is distinct from the broader console market, with 23% of users aged 10–15 and 55% identifying as female.
- Role-Playing, Simulation, and Platformer genres consistently outperform others, with over one-third of ported RPGs generating more than $1 million in revenue.
- Staggered releases often achieve higher average revenue per title, exemplified by high-performing ports like Hogwarts Legacy, while simultaneous releases capture a larger share of total cross-platform revenue.
- Fighting games demonstrate strong commercial performance on the platform when paired with established intellectual properties.
+1
NewzooMar 2025
Report20 pages
Live Streaming Trend Report: Q1 2025
I’m ready to synthesize the full report, but I only have the beginning of the first section. Could you please provide the remaining section summaries so I can create a complete, cohesive summary?
- Live streaming viewership increased by 8.9% year-over-year in Q1 2025, primarily driven by competitor platforms, as Twitch's viewership decreased by 6.9% from Q1 2024.
- Non-gaming content is the most popular streaming category, growing 25.6% year-over-year, with Kick, Chzzk, and SOOP Korea showing roughly 94% year-over-year increases in non-gaming content.
- Twitch remains the largest platform with 59% of the market share, while Kick experienced strong growth with a 112% year-over-year increase in hours watched, securing an 8.6% share of total viewership.
- YouTube Gaming's market share grew in Q2 2024 following Twitch's shutdown in South Korea, with new Korean platforms like SOOP (AfreecaTV's new platform) and Chzzk seeing streamers prosper after departing Twitch.
- Counter-Strike boasted the highest growth in Q1 2025, increasing its viewership by 55%, driven by high-profile esports events, while League of Legends, despite remaining #1, saw a 3% quarterly viewership decline.
+1
Stream HatchetMar 2025
Report32 pages
Mobile Games Industry Trends Survey: Winter 2024/25
The mobile games industry entered a period of significant recalibration during the winter of 2024/25, characterized by a transition from rapid expansion to a focus on long-term sustainability. While the market is returning to growth, it is currently defined by a "reality check" phase where 56.7% of professionals identify widespread layoffs as the year’s most impactful trend. High user acquisition costs and evolving privacy regulations have created a consolidated landscape favoring established organizations, as evidenced by the fact that nearly 39% of companies have operated for over a decade while the presence of new startups has notably diminished.
Strategic priorities have shifted toward maintaining existing portfolios through live operations and hybrid-casual models rather than launching new intellectual property. Over 40% of organizations released no new titles in the past year, choosing instead to prioritize top-line revenue and retention as their primary performance indicators. In-app purchases and video advertisements remain the foundational business models, though rising acquisition costs are cited by 64.2% of respondents as the greatest threat to continued profitability. Despite these headwinds, the industry maintains a cautiously optimistic outlook for 2025, with 44.1% of professionals expressing confidence in the coming year.
Growth opportunities are increasingly sought in emerging markets, particularly the MENA region, and through strategic networking at global industry summits. Professional events remain vital for the ecosystem, with nearly 90% of participants attending for networking and over 31% seeking investment or publishing partnerships. As the industry moves forward, the reliance on proven development tools like Unity and a data-driven approach to player retention will be essential for navigating a market that increasingly rewards operational efficiency and established brand presence over speculative new ventures.
- Rising user acquisition costs are the primary threat to profitability, cited by 64.2% of industry professionals as the greatest challenge to the sector.
- The industry is in a period of consolidation, with 56.7% of professionals identifying widespread layoffs as the most impactful trend of the 2024/25 period.
- Strategic focus has shifted away from new IP, as evidenced by over 40% of organizations releasing zero new titles in the past year to prioritize existing live operations.
- The market landscape is increasingly dominated by established players, with nearly 39% of companies operating for over a decade while startup formation has notably declined.
- Despite current headwinds, 44.1% of industry professionals maintain a cautiously optimistic outlook for growth in 2025.
PocketGamer.bizMar 2025
Report60 pages
The Game Development Renaissance
The global game development industry is undergoing a fundamental transition toward a more sustainable and efficient operational model, moving away from volatile hiring cycles in favor of long-term stability. With the market projected to reach $190 billion by 2025, industry leaders express significant optimism, as 77% of developers anticipate continued growth and a marked reduction in workforce instability. This evolution is characterized by a strategic shift toward leaner production cycles where studios prioritize creative intellectual property over the maintenance of internal technical infrastructure.
Central to this transformation is the widespread adoption of externalized technology and third-party backend services. While only 6% of developers intend to rely on internal builds in 2025, nearly half plan to integrate specialized third-party tools to manage complex requirements such as cross-platform synchronization and unified player inventories. By outsourcing non-core technical burdens, studios can accelerate time-to-market and mitigate the financial risks associated with building bespoke systems. This shift enables a deeper focus on LiveOps and "forever game" models, which are increasingly viewed as the primary drivers of player lifetime value and long-term revenue.
Furthermore, the industry is diversifying its financial and distributional strategies to bypass traditional gatekeepers. Developers are increasingly leveraging alternative funding sources, such as crowdfunding, and utilizing direct-to-consumer webshops to avoid high app store fees. As studios embrace sophisticated metagames and personalized engagement strategies, the integration of cross-platform capabilities and web-based distribution is becoming a strategic necessity. This new paradigm emphasizes technical agility and creative innovation, positioning the industry for a period of disciplined, technology-driven expansion.
- The global game development market is projected to reach $190 billion by 2025, with 77% of developers anticipating continued industry growth and reduced workforce instability.
- Studios are shifting toward leaner production models by outsourcing non-core technical infrastructure, with only 6% of developers planning to rely on internal builds by 2025.
- Nearly 50% of developers plan to integrate specialized third-party tools to manage complex requirements like cross-platform synchronization and unified player inventories.
- The industry is prioritizing 'forever game' models and LiveOps as the primary drivers for increasing player lifetime value and long-term revenue.
- Developers are increasingly bypassing traditional gatekeepers by utilizing alternative funding sources like crowdfunding and direct-to-consumer webshops to avoid high app store fees.
+1
MetaplayJan 2025
Report56 pages
Mobile Gaming 2022-2024
The analysis tracks mobile‑gaming dynamics from 2022 through 2024, arguing that the sector’s financial expansion now exceeds its ability to attract new users. Revenue on Google Play rose roughly 10 % year‑on‑year in 2023‑24 while download volumes stagnated or slipped slightly, and iOS revenue grew about 12 % against an 8 % rise in downloads. Despite this divergence, the concentration of earnings among the top ten publishers has held steady, indicating that market power remains entrenched even as overall spend accelerates.
Consumer‑device preferences reveal a near‑universal reliance on smartphones, with 97 % of Brazilian gamers using mobile phones in 2024 and personal PCs ranking as the only other significant platform; console usage is negligible. Across the United States and Brazil, the primary incentives for trying a new title are free‑to‑play pricing, recognizable brands or characters, and easy access through subscription services. Gender nuances appear modest: men place greater value on non‑pay‑to‑win structures and strong single‑player experiences, whereas women are drawn to customizable avatars and peer recommendations.
Behavioral data show a pronounced tendency toward deep engagement with a single game. Approximately half of respondents in Brazil, Germany, Japan and the United States report completing one title before moving to the next, suggesting that the market favors sustained, title‑centric play rather than rapid turnover. The findings collectively underscore a maturing mobile‑gaming ecosystem where revenue growth is driven by monetisation depth and brand loyalty rather than sheer user acquisition.
- Mobile gaming revenue growth is decoupling from user acquisition, with Google Play revenue rising 10% and iOS revenue growing 12% in 2023–2024 despite stagnant or slowing download volumes.
- Market power remains highly concentrated, as the top ten publishers continue to capture the vast majority of earnings despite the overall acceleration in consumer spending.
- The mobile ecosystem is shifting toward a maturity model where revenue increases are driven by monetization depth and brand loyalty rather than the expansion of the total user base.
- Approximately 50% of gamers in major markets like the U.S., Germany, Japan, and Brazil prefer deep, sustained engagement with a single title rather than rapid game turnover.
- Consumer acquisition is primarily driven by free-to-play pricing, recognizable IP, and accessibility through subscription services.
+1
Mariusz Gasiewski (Google)Jan 2025
Report17 pages
Rewarded Returns
Rewarded Returns explores the evolution of reward-based user acquisition (UA) from its origins as a controversial incentivized traffic tactic to a sophisticated, data-driven pillar of modern mobile game marketing. The primary thesis is that technological advancements and deeper reward structures have effectively addressed legacy concerns regarding fraud and user quality, positioning rewarded UA as a high-performance alternative to traditional channels in an increasingly challenging privacy-centric landscape.
The findings are based on a late 2024 survey of 502 mobile game developers in the United States and United Kingdom, primarily representing mid-sized companies with 50 to 100 employees. While 64% of respondents characterize the current UA environment as challenging due to privacy rules and high costs, 77% have already integrated reward-based campaigns into their strategies. Among these adopters, 82% report that rewarded campaigns outperform traditional UA, and 95% believe these strategies provide a distinct competitive advantage. Furthermore, 79% of developers observe stronger long-term retention from rewarded users compared to non-rewarded sources.
The study identifies a significant shift in perception, noting that fraud concerns for rewarded UA (47%) are now nearly identical to those for traditional channels (46%). Despite these lingering concerns, 59% of current users plan to expand their rewarded UA budgets in 2025. Among non-adopters, 62% express concern about falling behind competitors, and 43% intend to adopt the strategy in the coming year.
Looking ahead, the scope of the industry is expected to expand, with 90% of experienced developers predicting that reward-based mechanisms will move beyond mobile and web into console gaming. The conclusion emphasizes that as the industry moves toward 2025, real-world rewards—particularly cash and gift cards—are becoming a fundamental discovery and engagement mechanism rather than a mere experimental tactic.
- 82% of developers using reward-based user acquisition report that these campaigns outperform traditional channels, with 79% noting stronger long-term retention from rewarded users.
- 77% of mid-sized mobile game developers in the US and UK have integrated reward-based campaigns into their strategies, with 59% planning to increase these budgets in 2025.
- Fraud concerns for rewarded user acquisition have stabilized, with 47% of developers citing risks compared to 46% for traditional UA channels.
- 95% of developers currently using rewarded strategies believe they provide a distinct competitive advantage in an environment where 64% find standard UA increasingly challenging due to privacy rules and costs.
- 43% of developers not currently using rewarded UA intend to adopt the strategy in 2025, driven by a 62% concern among non-adopters about falling behind competitors.
+1
AlmediaJan 2025
Report95 pages
State of Mobile 2025
The global mobile economy reached a significant milestone in 2024, with consumer spend hitting $150 billion. This growth was primarily propelled by a 25% surge in non-gaming app revenue, particularly within the entertainment, productivity, and generative AI sectors. While total app downloads declined for the fourth consecutive year, indicating a maturing market, user engagement reached a record 4.2 trillion hours. The rise of generative AI served as a primary catalyst for this engagement, with AI chatbot downloads increasing by 635 million and the subgenre generating nearly $1.3 billion in revenue.
The mobile gaming sector demonstrated a robust recovery in 2024, reaching $80.9 billion in internal purchase revenue. Although total game downloads fell by 6%, the market shifted toward high-quality, core genres. Strategy and RPG titles dominated monetization, while the "hybrid-casual" model—combining simple mechanics with midcore progression—emerged as a vital growth driver. Established franchises continue to exert dominance, with titles older than two years accounting for over 80% of revenue. Notably, the industry saw a record eleven games surpass $1 billion in annual revenue, signaling a concentration of wealth among top-tier performers.
Beyond gaming, the landscape was defined by the continued dominance of social media, which accounted for 2.4 trillion hours of global usage. TikTok became the first non-game app to reach $15 billion in lifetime spend, reflecting a broader trend of social platforms diversifying revenue through in-app purchases and subscriptions. In the retail sector, Chinese e-tailers like Temu and SHEIN expanded their global footprint, while the finance sector saw a resurgence driven by cryptocurrency and digital wallets. Despite signs of "digital fatigue" in traditional streaming, the mobile ecosystem remains resilient, characterized by strategic shifts toward ad-supported tiers, meaningful AI integration, and incentivized health and fitness platforms.
- The global mobile economy reached $150 billion in consumer spend in 2024, driven by a 25% surge in non-gaming revenue despite a four-year decline in total app downloads.
- Mobile gaming revenue recovered to $80.9 billion, with 80% of earnings generated by titles older than two years and a record eleven games surpassing $1 billion in annual revenue.
- Generative AI became a primary engagement catalyst, with chatbot downloads increasing by 635 million and generating nearly $1.3 billion in revenue.
- Total mobile user engagement hit a record 4.2 trillion hours, with social media platforms accounting for 2.4 trillion of those hours.
- The 'hybrid-casual' gaming model has emerged as a critical growth driver, while strategy and RPG titles continue to dominate monetization.
+1
Sensor TowerJan 2025
Report13 pages
Gaming CEO Survey: 2024 in Review
Industry leadership maintains a cautiously optimistic outlook for 2025, with 98% of executives expecting consumer spending to either increase or remain stable. Growth expectations are strongest in the mobile sector, where 41% of leaders anticipate expansion in in-app purchases and 31% expect growth in advertising revenue. While the PC segment remains relatively healthy with a 33% growth projection, the console market appears more stagnant, as 70% of respondents forecast stable performance and only 15% predict growth. This outlook is tempered by concerns regarding content saturation and a challenging user acquisition environment, which are cited as the primary hurdles facing the industry.
Operational strategies for the coming year signal a shift toward expansion and increased investment. A majority of companies plan to initiate more game development projects in 2025 compared to the previous year, supported by higher or stable budgets and increased marketing spend. Talent acquisition remains a priority, particularly in game development and engineering roles. Furthermore, the mergers and acquisitions landscape is expected to intensify, with 71% of executives anticipating more opportunities in 2025 and none predicting a decrease in activity.
Artificial intelligence has reached a significant level of penetration within the sector, with 84% of companies reporting either limited implementation or advanced integration across multiple functions. Executives identify art, game design, and engineering as the areas where AI will provide the most significant value. These findings, compiled by a leading global investment bank specializing in gaming, reflect a sector transitioning from a period of consolidation toward a renewed focus on production, technological integration, and strategic deal-making.
- Industry leadership is optimistic for 2025, with 98% of executives expecting consumer spending to increase or remain stable.
- AI adoption is widespread, with 84% of companies already implementing the technology across functions like art, game design, and engineering.
- The M&A landscape is expected to intensify, as 71% of executives anticipate more deal-making opportunities in 2025 compared to the previous year.
- Mobile gaming is the primary growth driver, with 41% of leaders expecting increased in-app purchases and 31% projecting growth in advertising revenue.
- The console market is largely stagnant, with 70% of respondents forecasting stable performance and only 15% predicting growth.
+1
Aream & CoJan 2025
Report60 pages
Global LiveOps Trends 2025
The global mobile gaming landscape in 2025 is characterized by a notable deceleration in overall market growth, with revenue increases stalling at 0.7% and download growth slowing to 4.1%. In response to this stagnation, developers are intensifying LiveOps strategies to sustain engagement and monetization. The average number of monthly events per game has risen to 89, shifting away from traditional holiday-centric scheduling toward persistent, competitive mechanics such as Win Streaks, Leaderboards, and various collection-based systems. This strategic pivot reflects a broader industry effort to maximize the lifetime value of existing player bases, particularly within the Midcore and Hybridcasual segments.
Genre performance is undergoing a significant realignment, as Puzzle and Strategy titles experience growth while RPG and Shooter categories face substantial declines. Midcore titles remain the primary drivers of revenue, relying on cooperative events and targeted monetization of high-spending players to maintain stability. Simultaneously, the Hybridcasual sector has emerged as a high-growth area, recording a 75% year-over-year revenue increase despite stagnant download figures. This success is largely attributed to the integration of Casual-style mechanics, such as Digging and Expedition events, which effectively boost session length and ad-based monetization.
The industry is currently defined by a move toward greater mechanical complexity and event density. By adopting diverse features like Stamp-based systems and Core Duplicates, developers are successfully diversifying their monetization strategies across different player archetypes. While Midcore games continue to prioritize whale-focused cooperative events, Hybridcasual titles are increasingly leveraging competitive, short-term engagement loops to drive performance. Ultimately, the 2025 market environment demonstrates that sustained success is no longer dependent on rapid user acquisition, but rather on the sophisticated, data-driven application of LiveOps to deepen engagement within established gaming ecosystems.
- The global mobile gaming market has stagnated, with revenue growth slowing to 0.7% and download growth to 4.1%, forcing a shift toward maximizing the lifetime value of existing players.
- Hybridcasual games have emerged as a high-growth sector, recording a 75% year-over-year revenue increase despite flat download numbers.
- LiveOps strategy has shifted toward high-frequency engagement, with the average number of monthly events per game rising to 89.
- Developers are moving away from holiday-centric calendars in favor of persistent, competitive mechanics like Win Streaks, Leaderboards, and collection-based systems.
- Genre performance is realigning, with Puzzle and Strategy titles showing growth while RPG and Shooter categories face substantial declines.
+3
AppMagicJan 2025
Report133 pages
Vorhaus Digital Strategy Study: All Findings
The 2025 digital landscape is defined by a fundamental transition in entertainment consumption, as smartphones and connected TVs have officially supplanted traditional television as the primary mediums for American audiences. This shift is accompanied by a broader decline in legacy pay TV services, with nearly a quarter of consumers signaling an intent to cancel subscriptions within the next year. While the streaming market remains highly competitive, with the average consumer maintaining 3.5 paid subscriptions, cost-sensitivity has emerged as the primary driver for churn. Simultaneously, digital engagement is deepening across gaming and social platforms, with 80% of the population now participating in gaming activities, reflecting a 4% increase since 2024.
Gaming has evolved into a central pillar of digital life, characterized by rising in-game spending and a growing preference for mobile platforms across all age groups, including those over 55. Discovery mechanisms are also shifting, as traditional advertising loses efficacy in favor of video-based gameplay content, which has become a critical influence for younger demographics. While interest in emerging technologies like the Metaverse, virtual reality, and augmented reality remains concentrated among the 18–34 cohort, adoption is tempered by broader consumer apprehension regarding data privacy and security. Furthermore, while the creator economy is expanding in terms of participation, monetization remains a significant hurdle, with many creators facing declining average earnings despite the rise of user-generated content platforms.
The demographic profile of this digital ecosystem is largely composed of educated, established homeowners, though self-identification varies sharply by age. Younger users increasingly embrace niche digital identities, whereas older cohorts lean toward mainstream engagement. Looking ahead, the integration of virtual goods and blockchain-based tracking presents a potential avenue for increased revenue, as a significant portion of gamers express a willingness to spend more if ownership and transferability of digital assets are secured. Despite this, cryptocurrency adoption remains limited, suggesting that while consumers are increasingly comfortable with digital transactions, they remain cautious regarding speculative financial technologies.
- Gaming participation has reached 80% of the U.S. population, marking a 4% increase since 2024 and establishing gaming as a primary pillar of digital engagement.
- Traditional pay TV is in decline, with nearly 25% of consumers planning to cancel their subscriptions within the next year as smartphones and connected TVs become the dominant media platforms.
- Cost-sensitivity is the primary driver of churn in the streaming market, where the average consumer currently maintains 3.5 paid subscriptions.
- Mobile gaming is the preferred platform across all age groups, including users over 55, while video-based gameplay content has replaced traditional advertising as the most effective discovery mechanism for younger demographics.
- While interest in the Metaverse, VR, and AR is concentrated in the 18–34 age demographic, widespread adoption is currently hindered by consumer concerns regarding data privacy and security.
+4
Vorhaus AdvisorsJan 2025
Report23 pages
PC & Console Year in Review: 2025
The 2025 PC and Console Year in Review provides a comprehensive analysis of the global gaming landscape, focusing on market performance, consumer behavior, and development trends. The primary thesis highlights that while pre-launch marketing and wishlist campaigns remain foundational for success, post-release player reception and the integration of social, co-op elements are the primary drivers of long-term revenue and sustainability. The analysis covers the period from January 1, 2025, through late 2025, utilizing proprietary data estimates to track sales, player engagement, and platform distribution across global markets.
Key findings indicate that the premium game market remains dominant, accounting for 78% of Steam’s $16.8 billion revenue. Indie developers continue to capture significant market share, contributing over 25% of Steam’s total revenue, with "Triple-I" titles demonstrating exceptional return on investment. Geographically, China has solidified its position as a critical market, serving as the top region for Steam and a major driver for both Western and Eastern-developed titles. Furthermore, the data reveals a shift in marketing efficacy; while wishlist counts are rising, conversion rates are declining, forcing studios to experiment with in-game incentives and community-driven engagement strategies.
Genre trends show that action, adventure, and RPG titles continue to lead in player interest, though "cute" and atmospheric games experienced significant year-over-year growth in revenue. Co-op mechanics have emerged as a vital pillar for commercial success, with 11 of the top 20 highest-grossing titles featuring cooperative elements. From a technical perspective, Unreal Engine maintains its status as the market leader for AA and AAA development, while many studios continue to leverage proprietary engines for large-scale projects. The report concludes that while pre-launch hype is a useful tool for visibility, the post-release sales trajectory is ultimately dictated by player sentiment and the ability of a title to foster sustained social interaction.
- Premium games dominate the market, accounting for 78% of Steam’s $16.8 billion total revenue in 2025.
- Cooperative gameplay is a primary driver of commercial success, with 11 of the top 20 highest-grossing titles featuring co-op mechanics.
- Indie developers contribute over 25% of Steam’s total revenue, with 'Triple-I' titles delivering exceptional return on investment.
- China has become the top global region for Steam, serving as a critical market for both Western and Eastern-developed titles.
- Marketing efficacy is shifting as wishlist counts rise while conversion rates decline, necessitating a move toward in-game incentives and community-driven engagement.
+3
Alinea AnalyticsJan 2025
Whitepaper26 pages
Maximize Your ROAS: Cutting-Edge Attribution Strategies in Mobile Gaming
Mobile gaming marketers currently face a critical measurement crisis driven by tightening privacy regulations, increased media fragmentation, and the inherent inaccuracies of traditional Last-Touch Attribution. These factors have rendered legacy models insufficient for capturing the true impact of marketing spend, as they frequently over-index on bottom-of-funnel touchpoints while ignoring the incremental value generated by upper-funnel awareness campaigns. To maintain competitive advantage and optimize Return on Ad Spend, the industry is transitioning toward sophisticated Marketing Mix Modeling, which leverages aggregated, privacy-compliant data to provide a more comprehensive view of channel performance.
The most effective strategy for modern publishers involves a dual-measurement framework that integrates tactical, real-time insights from Last-Touch Attribution with the strategic, long-term perspective offered by Marketing Mix Modeling. This hybrid approach is particularly vital for organizations managing substantial monthly budgets across diverse media channels, provided they possess at least one year of historical data to ensure model accuracy. By identifying the true incrementality of various platforms, developers can move beyond attribution blind spots and allocate resources with greater precision.
This analytical shift is essential for navigating the complexities of the global mobile gaming landscape. Platforms such as Kochava’s Always-On Incremental Measurement, often utilized in tandem with partners like TikTok for Business, represent the current standard for advertisers seeking to reconcile privacy-first data requirements with the need for actionable growth insights. Adopting these advanced modeling techniques allows publishers to move past fragmented measurement silos, ensuring that marketing investments are directed toward the channels that provide the most significant, measurable impact on long-term user acquisition and revenue growth.
- Mobile gaming marketers must transition from legacy Last-Touch Attribution to Marketing Mix Modeling (MMM) to overcome privacy regulations and media fragmentation that render bottom-of-funnel-focused models inaccurate.
- A dual-measurement framework combining real-time Last-Touch Attribution with long-term Marketing Mix Modeling is the most effective strategy for optimizing Return on Ad Spend.
- Marketing Mix Modeling requires a minimum of one year of historical data to ensure the accuracy necessary for identifying true channel incrementality.
- The hybrid measurement approach is specifically recommended for organizations managing substantial monthly budgets across diverse media channels.
- Platforms such as Kochava’s Always-On Incremental Measurement, used alongside partners like TikTok for Business, are currently the industry standard for reconciling privacy-compliant data with actionable growth insights.
+2
KochavaJan 2025
Report26 pages
Video Gaming Report 2025: How Platforms Are Colliding and Why This Will Spark the Next Era of Growth
The global video game industry is currently emerging from a three-year period of stagnation, transitioning toward a future defined by platform convergence and hardware-agnostic ecosystems. The traditional era of console-centric competition is being replaced by a multiplatform landscape where success is increasingly dictated by community engagement, user-generated content, and discoverability. This structural shift is underpinned by the integration of generative AI, the expansion of cloud gaming, and the diversification of distribution channels, which collectively aim to move the industry beyond the limitations of legacy hardware.
Cloud gaming is projected to reach $18.3 billion in revenue by 2030, serving as a primary catalyst for this growth. However, this transition introduces significant challenges, most notably the risk of market saturation caused by an influx of low-quality, AI-generated content. To maintain profitability and relevance, developers are pivoting toward direct-to-consumer monetization strategies, including tiered pricing models, windowing, and the integration of in-game advertising. These tactics are designed to capture value from a increasingly price-conscious global player base while navigating a shifting regulatory environment.
The dominance of incumbent app stores is simultaneously being challenged by the rise of developer-owned webstores and alternative distribution platforms. While these new channels offer the potential for improved margins and deeper player relationships, their long-term viability depends on the industry’s ability to address consumer concerns regarding security and platform convenience. Ultimately, the next era of growth will be defined by the ability of stakeholders to balance technological innovation with the necessity of fostering sustainable creator economies, ensuring that discoverability remains the central pillar of the modern gaming experience.
- Cloud gaming is projected to reach $18.3 billion in revenue by 2030, acting as a primary driver for industry growth as the market moves toward hardware-agnostic ecosystems.
- The industry is shifting from console-centric competition to a multiplatform model where success depends on user-generated content, community engagement, and discoverability.
- Developers are adopting direct-to-consumer monetization strategies—including tiered pricing, windowing, and in-game advertising—to address a price-conscious global player base.
- The rise of developer-owned webstores and alternative distribution platforms is challenging the dominance of incumbent app stores to improve margins and deepen player relationships.
- Market saturation caused by an influx of low-quality, AI-generated content poses a significant risk to profitability and requires a focus on sustainable creator economies.
+3
Boston Consulting GroupJan 2025