Key insights
6 slides
Key number
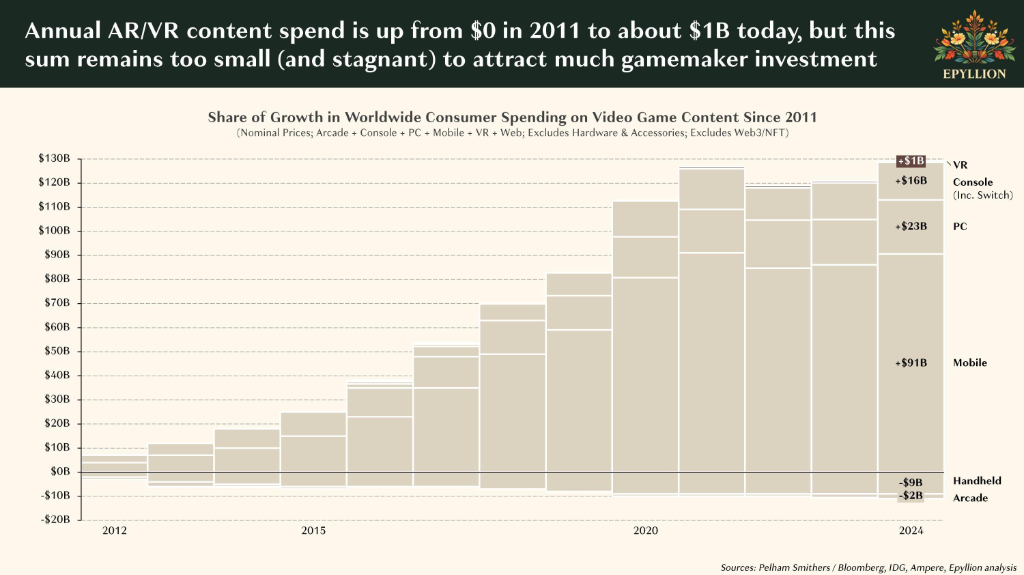
Global gaming spend reached $200 billion in 2025.
This represents a 150% increase since 2011. However, real-term growth has stalled and profit margins have compressed to single digits.
Rising costs
AAA development costs now exceed $600 million.
This cost pressure contributes to record layoffs and shrinking publisher share prices. Venture capital funding has also contracted sharply.
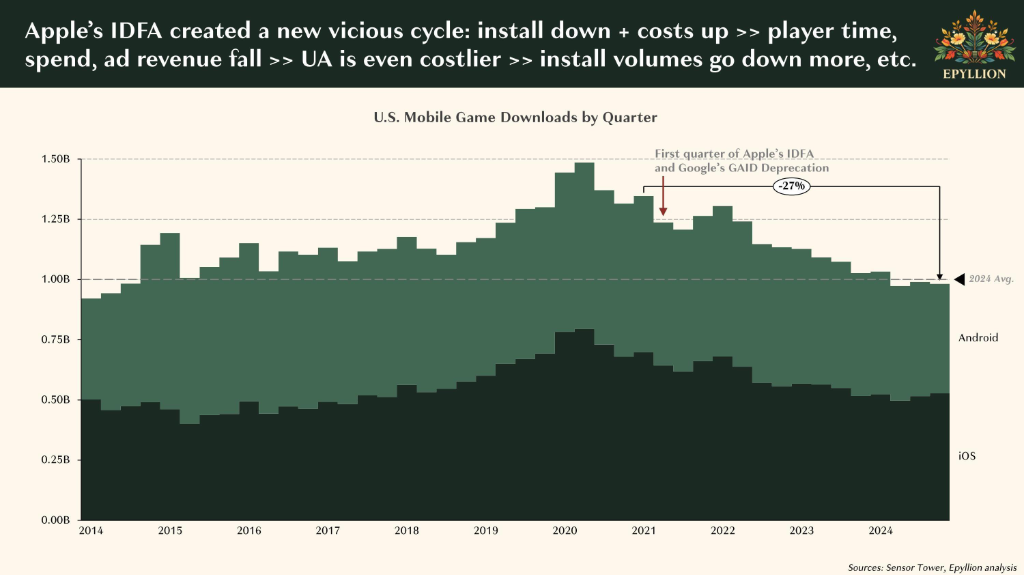
Mobile decline
Mobile gaming revenue fell 23% in Q1 2024.
Spend is now increasingly concentrated among a small number of high-margin titles.
Regional growth
China and India account for 30% of projected spend.
Together, these markets represent approximately 30% of the projected $300 billion total market spend. China is the largest single market.
Page 134 of the report30%
Share of projected $300B spend from China and India
- China market size
- $50–65 B
Engagement gap
Steam user engagement per capita remains low.
This is despite a 250% increase in the user base and a 300% rise in total game releases. PC and Steam continue to dominate full-game purchases.
Page 100 of the report20186.1
20194.3
20205
20214.6
20223.7
20233.6
20243.9
Console plateau
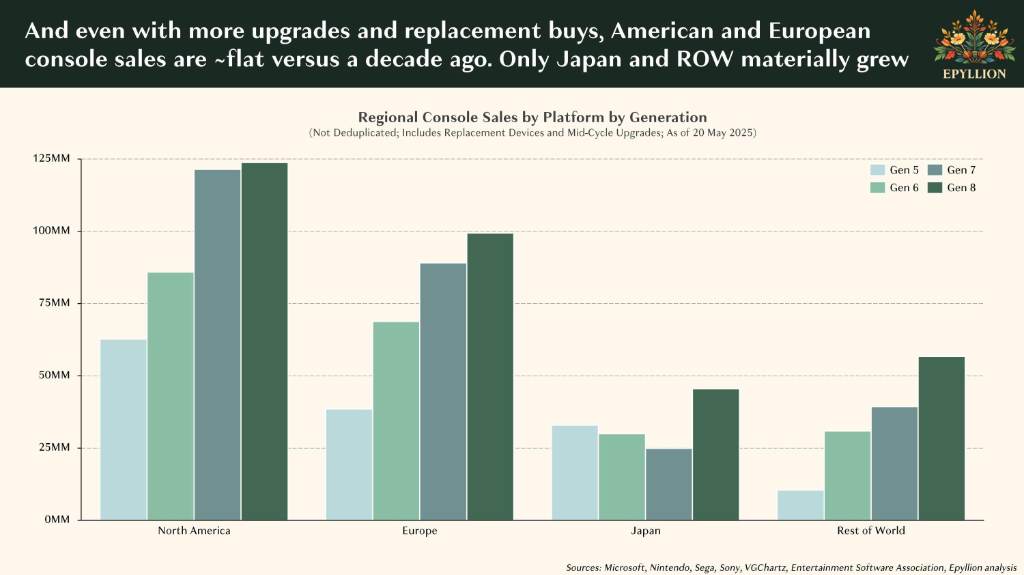
Console sales have plateaued over the last decade.
PlayStation and Xbox see flat or declining sales outside of Japan. AR/VR shipments continue to underperform against forecasts.
1 / 6
Ask AI about this report