FinancialPlaytika
Playtika Holding Corp. Second Quarter 2024 Results
7 Aug 202412 pages~14 min full read
Distilling the key insights…
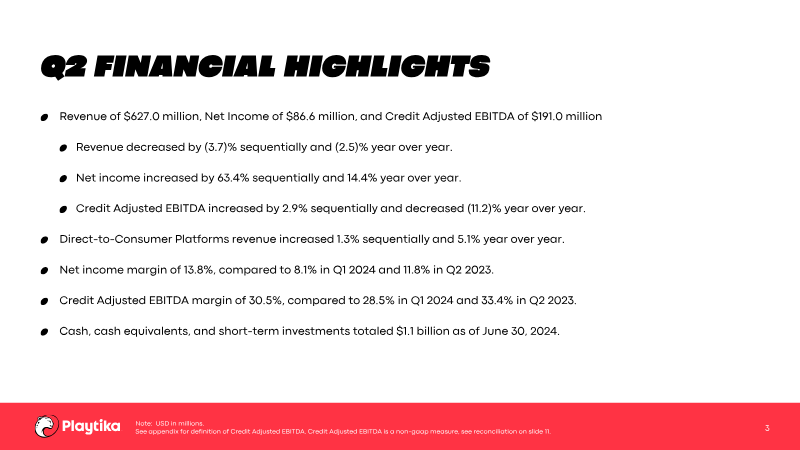
Playtika Holding Corp.’s second quarter 2024 results reflect a period of mixed financial performance characterized by a focus on operational efficiency and direct-to-consumer growth amidst a challenging macroeconomic and geopolitical environment. The company reported quarterly revenue of $627.0 million, representing a 3.7% sequential decline and a 2.5% decrease year over year. Despite the revenue contraction, net income showed significant improvement, rising 63.4% sequentially and 14.4% year over year to $86.6 million. Credit Adjusted EBITDA reached $191.0 million, a 2.9% sequential increase, though this figure reflects an 11.2% decline compared to the same period in the prior year.
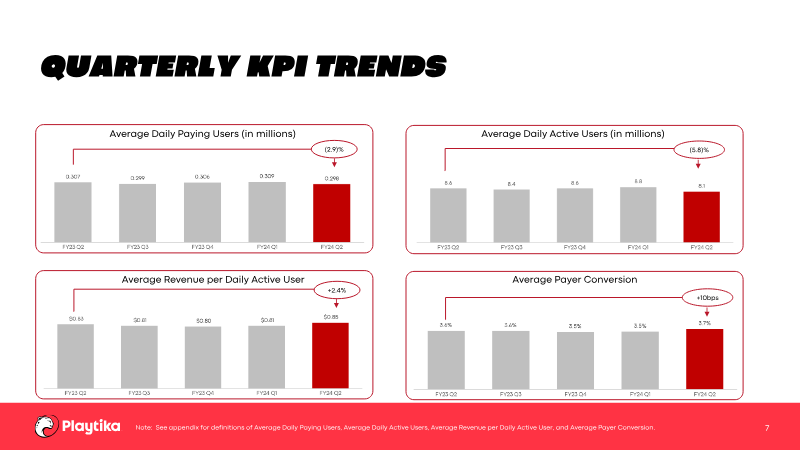
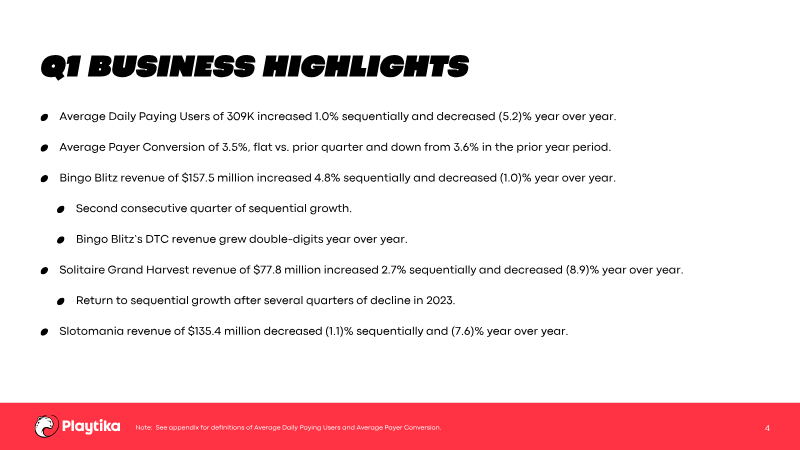
Operational metrics indicate a slight softening in user engagement, with average daily paying users falling 3.6% sequentially to 298,000. However, the company successfully improved its average payer conversion rate to 3.7%, up from 3.5% in the first quarter of 2024. Revenue performance across key titles remained varied, with flagship games such as Bingo Blitz and Slotomania experiencing slight sequential declines. A notable bright spot was the performance of direct-to-consumer platforms, which saw a 5.1% year-over-year revenue increase, highlighting the strategic importance of these channels in mitigating high third-party platform fees.
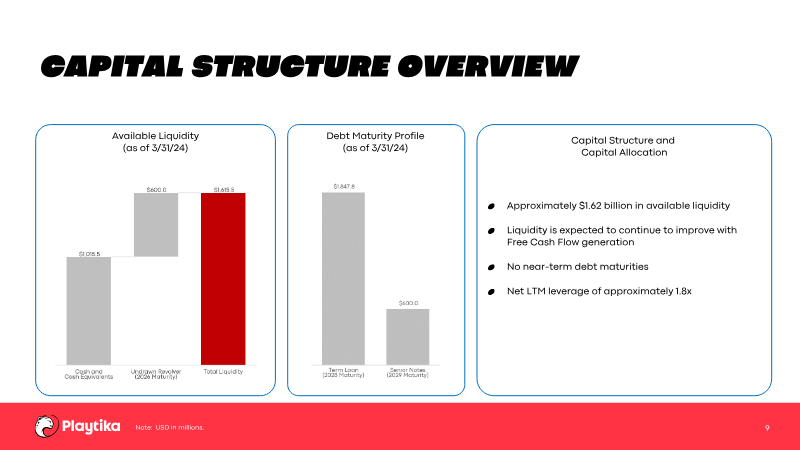
The company maintains a stable liquidity position with $1.1 billion in cash and short-term investments as of June 30, 2024, and no near-term debt maturities. Management continues to navigate significant risks, including reliance on a limited number of games and users, exposure to geopolitical instability in Israel and Ukraine, and the competitive nature of the mobile gaming industry. Future growth strategies remain tied to the successful integration of acquisitions, the expansion of direct-to-consumer reach, and the ongoing optimization of monetization models within its casual and social casino game portfolios.
Playtika · 2026
Playtika · 2026
Playtika · 2026
Playtika · 2025
Playtika · 2025
Playtika · 2025
Playtika · 2025
Playtika · 2024
Playtika · 2024
Playtika · 2024
Playtika · 2024
Playtika · 2024
Deconstructor of Fun · 2026
Two & a Half Gamers · 2026
Two & a Half Gamers · 2026
Deconstructor of Fun · 2026
Deconstructor of Fun · 2026
Sensor Tower · 2026
Two & a Half Gamers · 2026


Sensor Tower · 2026
PocketGamer.biz · 2026
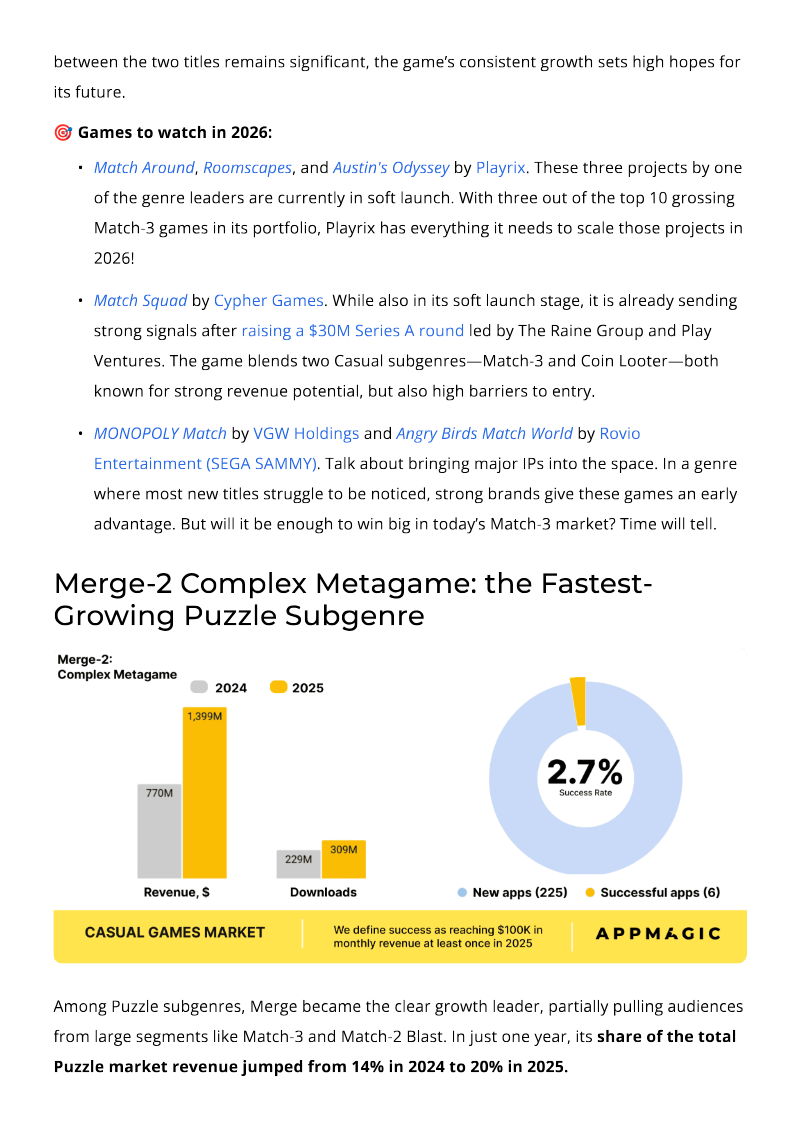
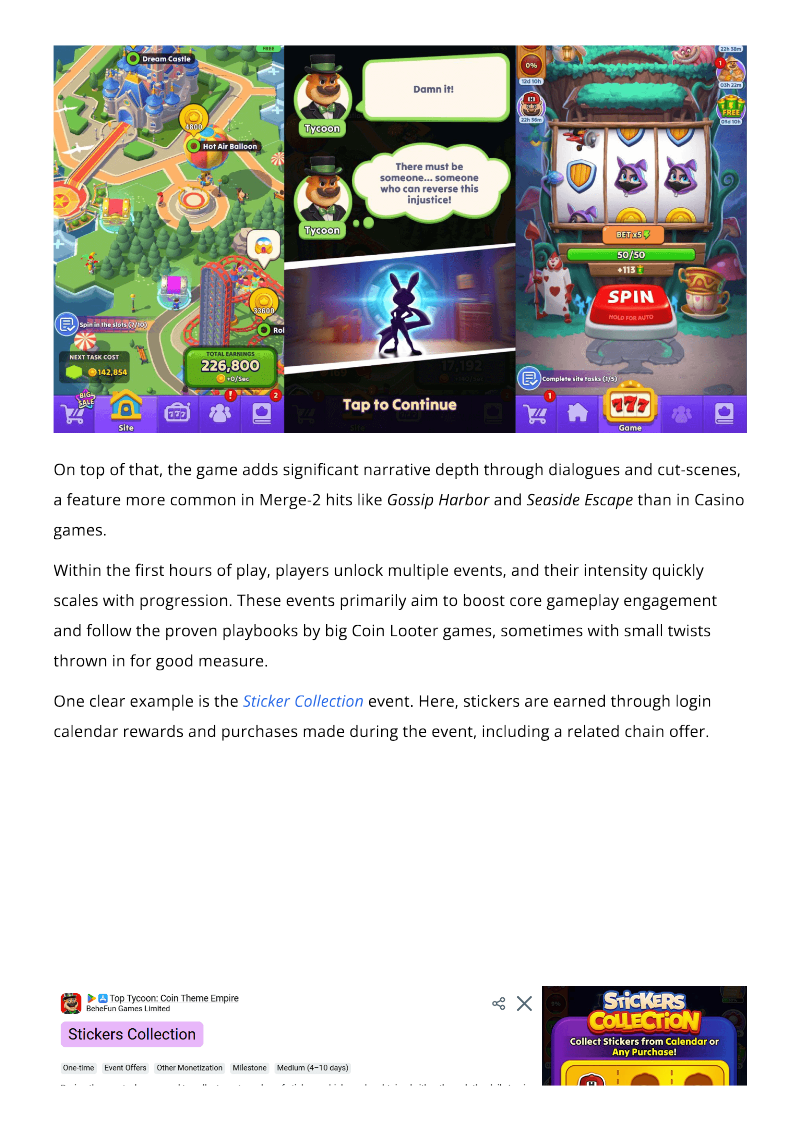
AppMagic · 2026
PocketGamer.biz · 2026
Two & a Half Gamers · 2026
Comments