1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticle Dungeon Investing
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountArticleDungeon Investing
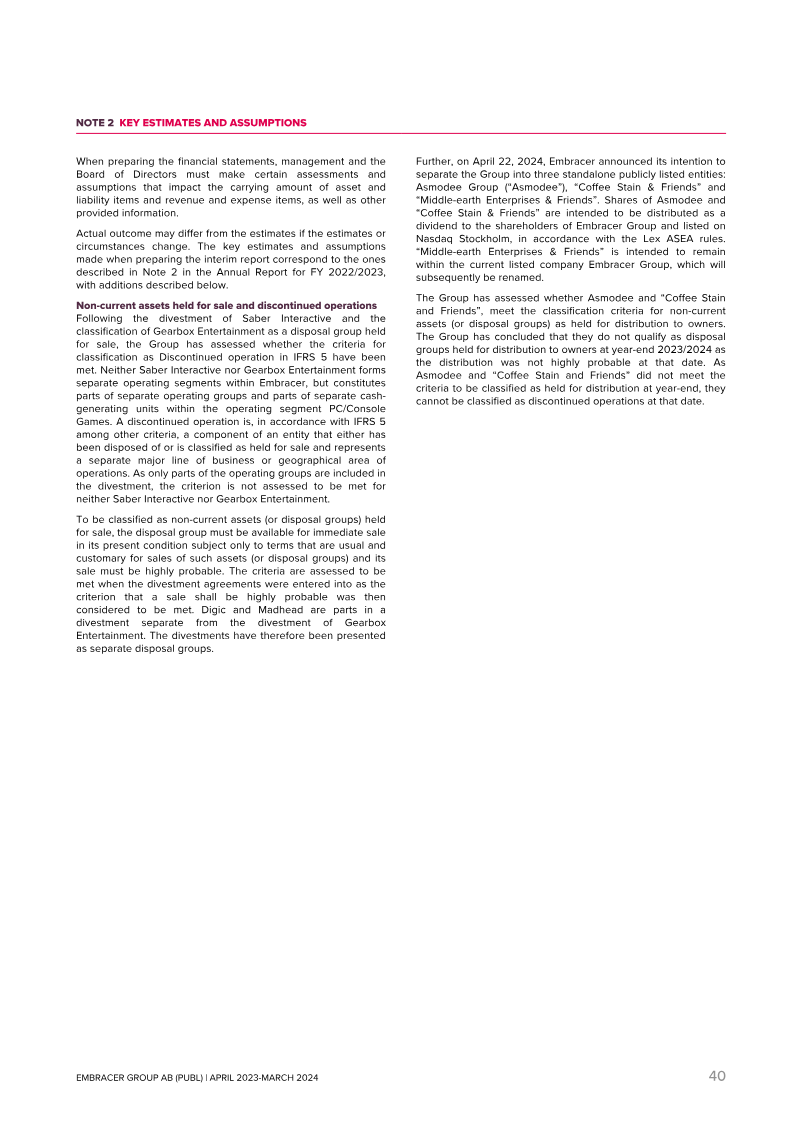
Asmodee aims to establish itself as a standalone leader within the global tabletop gaming sector. The company is currently positioning itself for this transition.
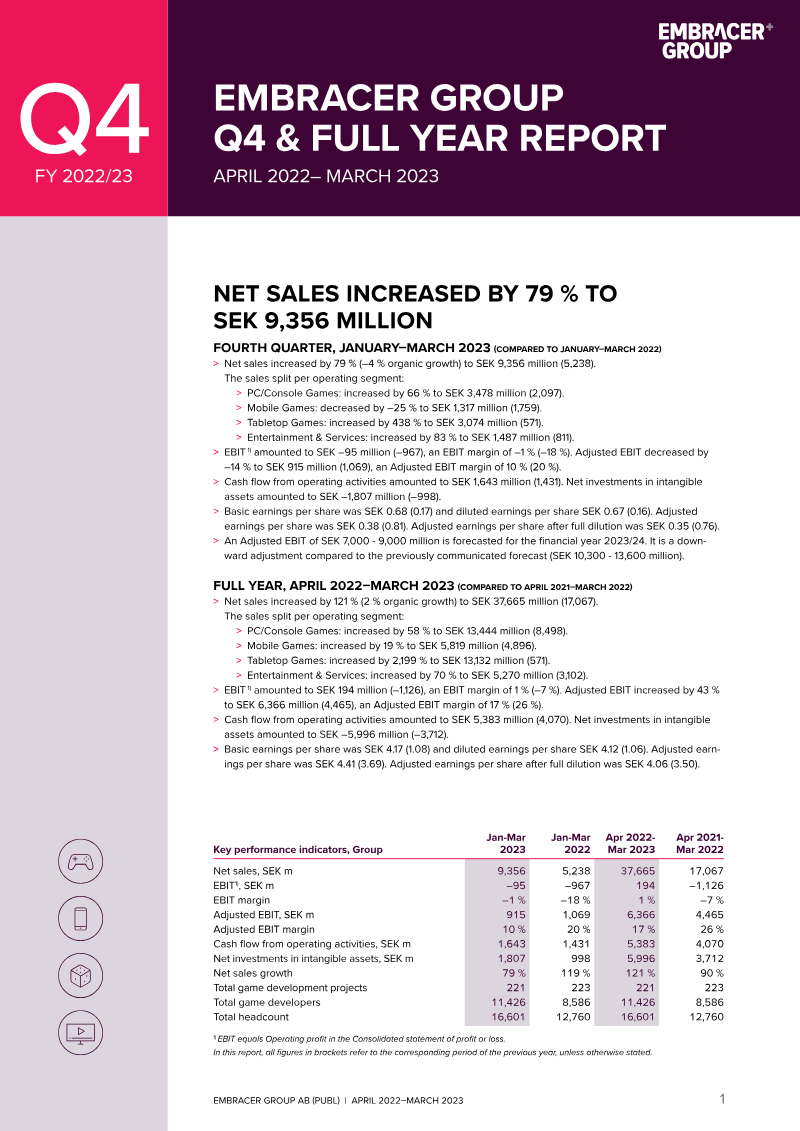
Asmodee's capital markets day ahead of its spin-off from Embracer prompts a skeptical assessment of the company as a distribution-heavy "mini-Embracer." About 46% of revenue comes from trading card games, mostly third-party Pokémon and Magic carrying thin margins, and roughly 64% of total revenue is third-party. The growth story looks weak: tabletop sales peaked in 2020, strategy-game and Kickstarter data suggest a slowdown, miniature games rely on licensed IP with heavy royalties, and evidence for the "IP factory" and transmedia ambitions is thin. The main bright spot is TCG distribution and licensed or fad-driven TCGs such as Star Wars Unlimited.
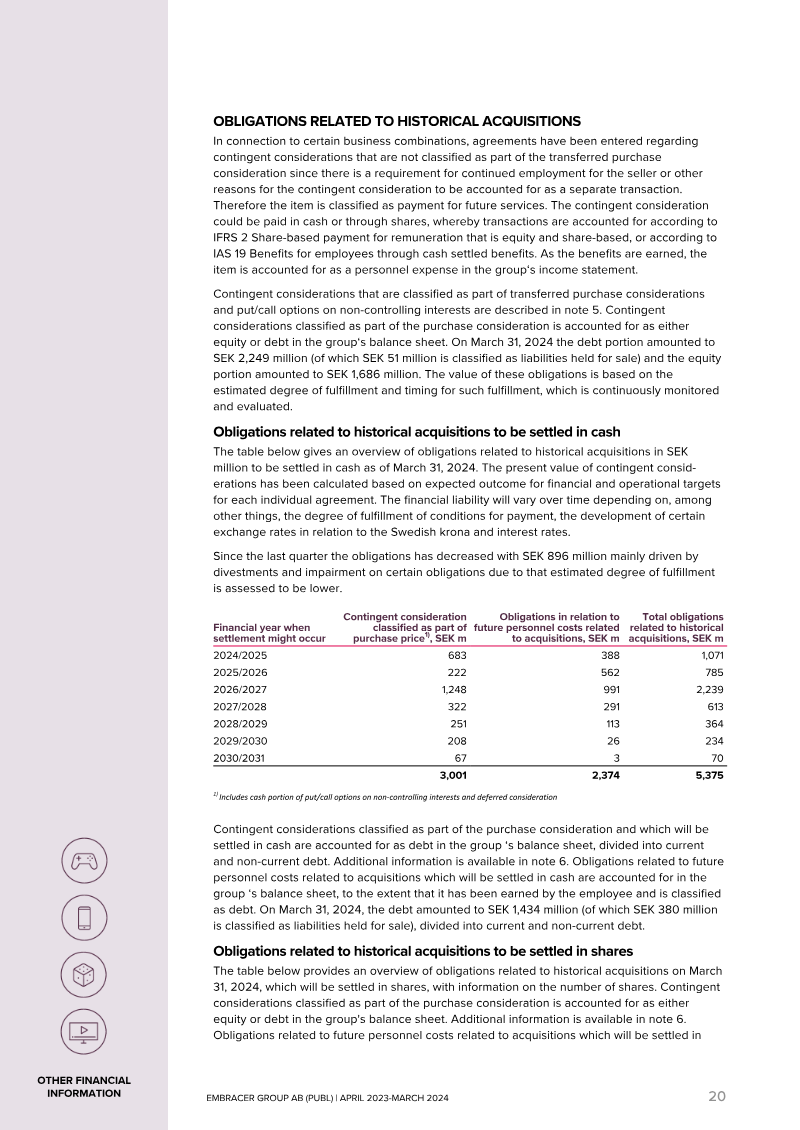
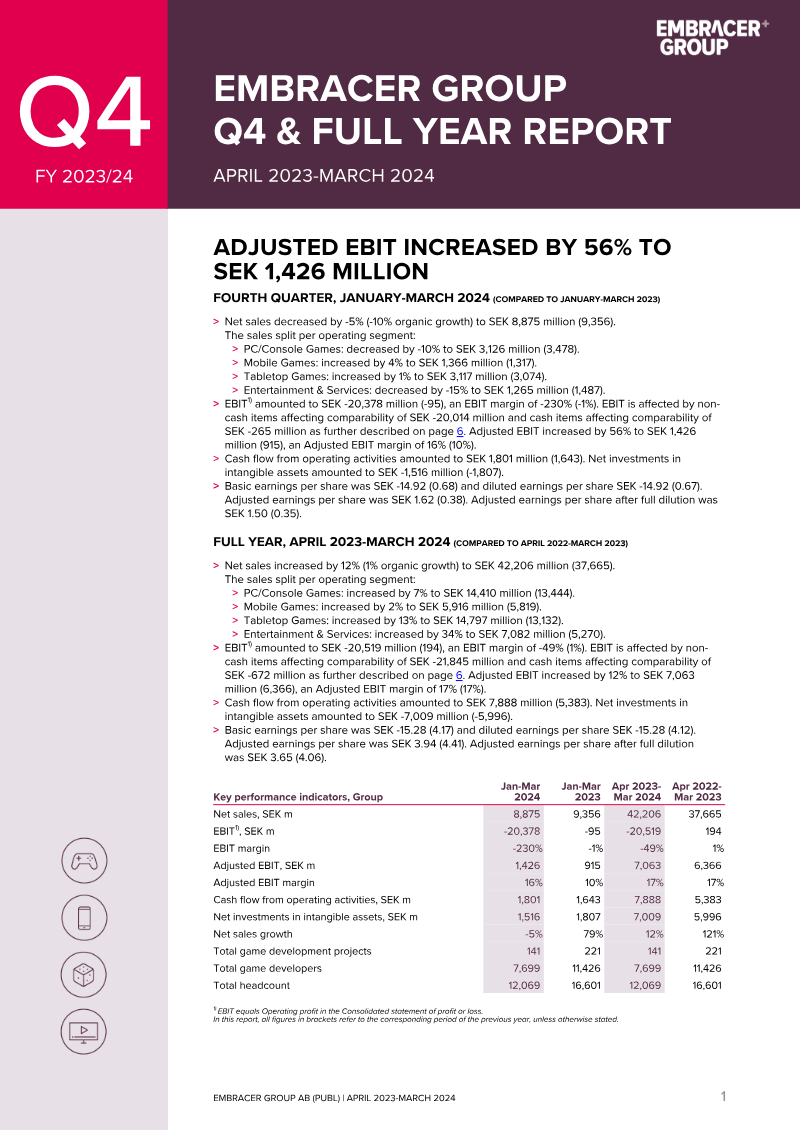
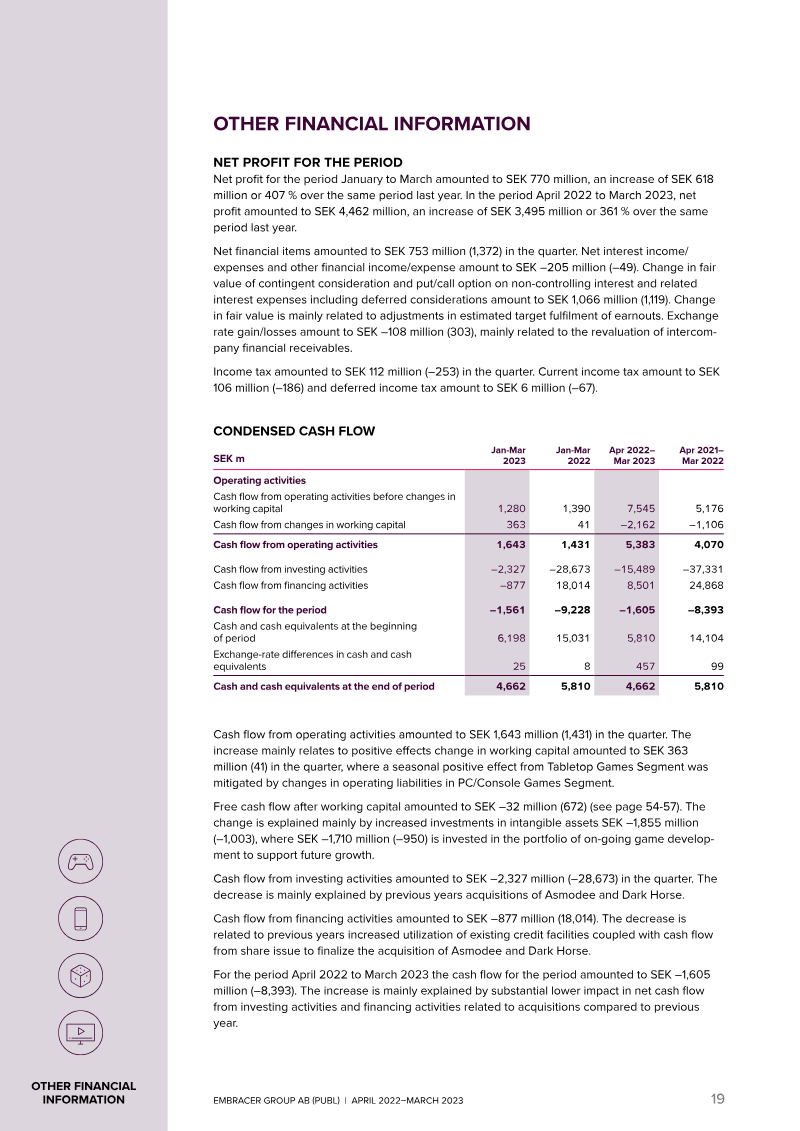
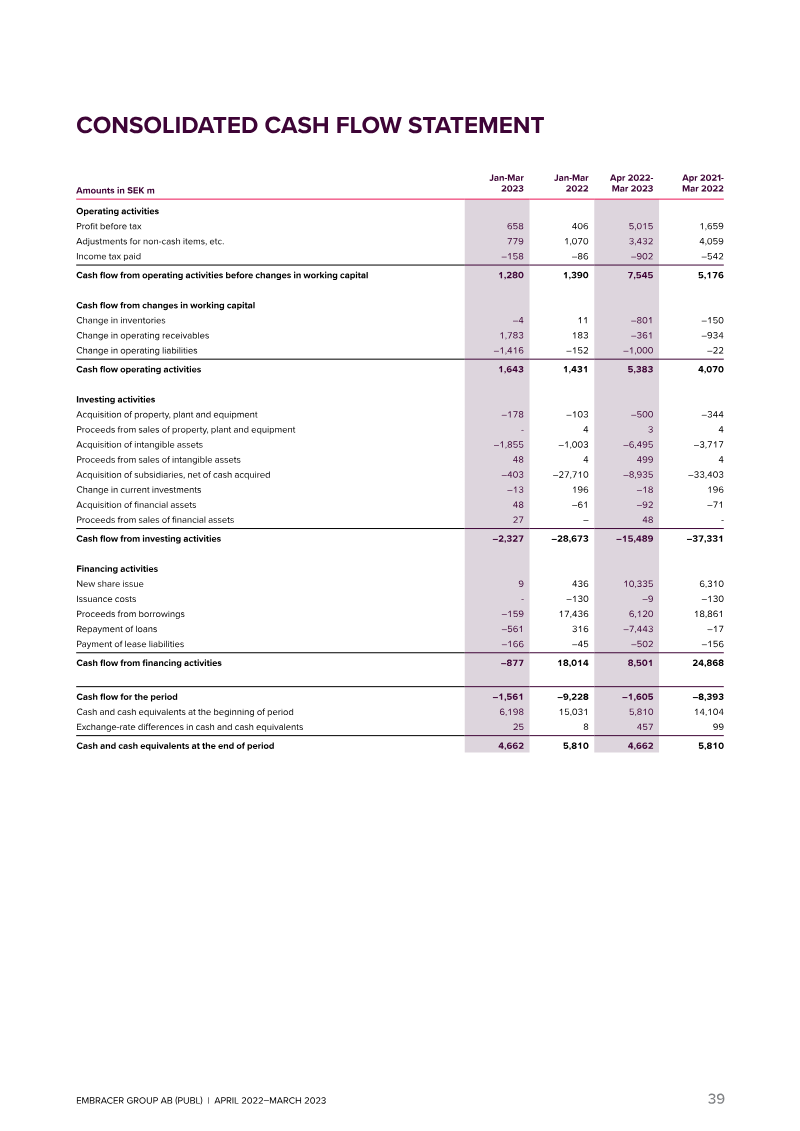
Financially, Asmodee is one of Embracer's few reliably profitable units, yet EBIT has barely covered interest. First-half EBIT rose almost 50% to a 7% margin, aided by Star Wars TCG, but long-term margins are expected to stay limited. The company will retain about 6B SEK of debt at an assumed 5% interest. Back-of-the-envelope scenarios built on growth and lower interest suggest that leverage near 5x EBIT is ample for a slow-growing business with a high fixed-cost distribution base. The analysis questions a planned return to acquisitions before margins improve and distrusts management, who appear to have abandoned competing with Games Workshop in wargames.
Beyond Asmodee, the coverage spans several adjacent developments, mainly in late 2024. Sony is in talks to acquire Kadokawa, valued near $4B, with its manga and anime IP seen as the draw. Furyu's purikura business is declining faster than expected, though results grew 6% and guidance held. Mandarake shows weak trends but guidance implying growth and better margins. Games Workshop posted a 24.9% rise in first-half operating profit, helped by Space Marine 2 and 10% core sales growth. Smaller items include the Dan Da Dan hit, a potential 7-10M PLN boost to PlayWay's Q4 operating profit from Crime Scene Cleaner, and a new player peak for Hearts of Iron IV after its DLC.
 Sony GroupCompany · Game company · 927 documents
 Embracer GroupCompany · Game company · 194 documents
 AsmodeeCompany · 50 documents
 Kadokawa CorporationCompany · Game company · 42 documents
 Hearts of Iron IVGame · Paradox Development Studio · 2016 · 30 documents
 Hearts of IronGame · Paradox Development Studio · 2002 · 28 documents
 Games WorkshopCompany · Game company · 20 documents
 PlayWayCompany · Game company · 19 documents
Each row is a game or company this document names, each column a document, oldest first. A mark means that document names it. Select a row to see those documents.
Dungeon Investing · 2025
Deconstructor of Fun · 2026