Monetization & Live Ops
Revenue models, in-game economies, retention and live operations.
258 documents
data.ai · 2023
ReportGaming Spotlight 2023: The Year in Review
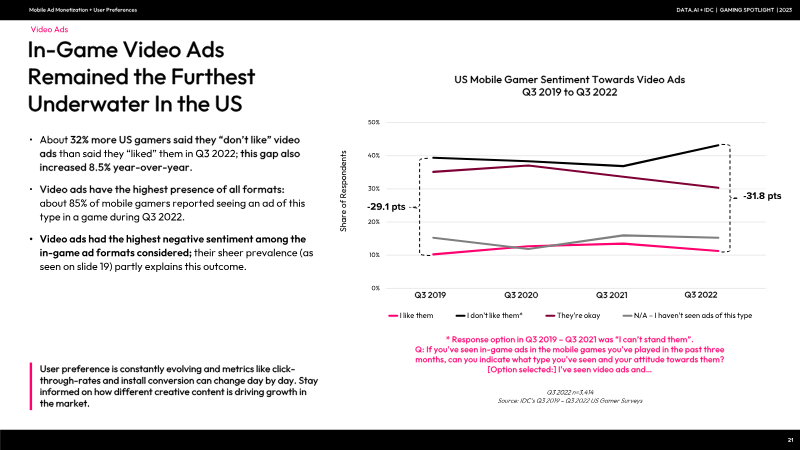
The 2023 Gaming Spotlight provides a comprehensive analysis of the global gaming landscape, focusing on market shifts across mobile, PC, and console platforms during the first half of 2023. Utilizing data from data.ai and IDC, the analysis highlights that while mobile remains the largest market opportunity, it faces a projected 2% year-over-year decline in consumer spend to $108 billion. This softening is attributed to macroeconomic instability, privacy regulations like Apple’s App Tracking Transparency (ATT), and stricter regulations on adolescent gaming in China. In contrast, home console and PC/Mac spending are expected to rise by 3% and 4% respectively, driven by increased hardware availability and subscription-based revenue. Geographically, the Asia-Pacific region remains a primary revenue driver, with South Korea showing significant market share gains. The report identifies a shift in handheld gaming; while the Nintendo Switch Lite faces declining interest, newer devices like the Steam Deck are gaining traction, albeit with distinct demographic profiles. Mobile gaming success in H1 2023 was defined by titles like Monopoly GO and Honkai: Star Rail, which leveraged strong intellectual property and sophisticated monetization strategies, such as high-value in-app purchases and social engagement features. A significant portion of the analysis examines user acquisition and monetization challenges. Findings indicate that US gamer sentiment toward in-game advertising is deteriorating, with negative sentiment toward banner and video ads rising significantly. Rewarded video remains the most tolerated format due to its clear value exchange, though even its popularity has dipped. The report concludes that as acquisition costs rise and tracking becomes more difficult, publishers must optimize creative strategies—particularly through playable ads for action genres—and diversify monetization models beyond traditional ads to include subscriptions and battle passes to maintain growth in an increasingly competitive and privacy-conscious environment.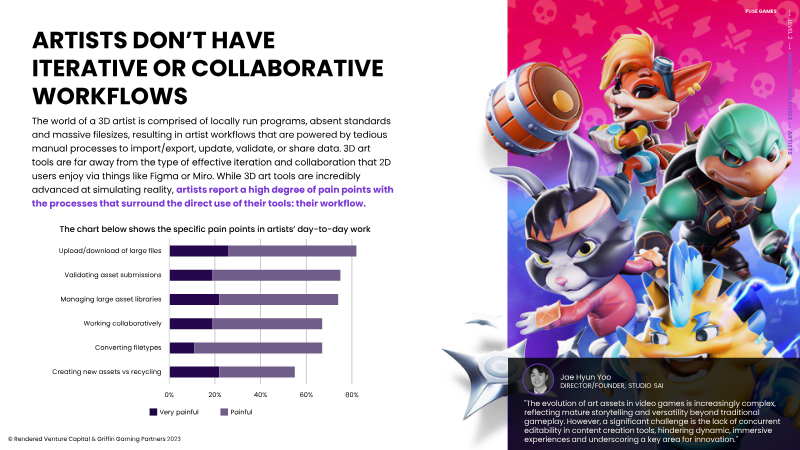
Rendered VC · 2023
ReportGame Development Report 2023
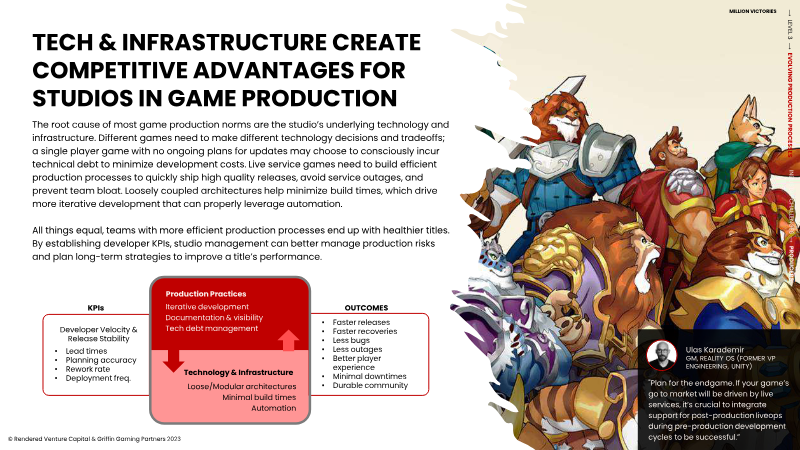
The global game development landscape is currently undergoing a fundamental transition driven by escalating project complexity and the widespread adoption of live service models. With 95% of studios now pursuing or planning live service strategies, the industry faces a critical mismatch between traditional production pipelines and the need for rapid, iterative release cycles. Rising development costs affect 77% of studios, fueled by consumer demands for AAA quality and the technical debt inherent in maintaining custom middleware. Consequently, 88% of developers are actively seeking new technological solutions to address systemic inefficiencies, particularly regarding long build times and fragmented collaborative 3D art pipelines. To mitigate these challenges, there is a significant shift toward a "buy vs. build" philosophy, with 65% of studios prioritizing off-the-shelf tools over proprietary systems to accelerate time-to-market. Modern development is increasingly adopting SaaS-inspired DevOps practices, modular architectures, and automated testing to improve developer velocity and ensure the stability required for live operations. These infrastructure investments are viewed as vital business drivers, as technical outages or defects in a live service environment result in immediate player churn and revenue loss. The industry's future growth depends on the integration of emerging technologies such as cloud infrastructure and artificial intelligence to streamline content creation and enhance player experiences. As market saturation and production risks intensify, the move toward agile, software-centric engineering practices represents a necessary departure from legacy norms. Studios that successfully leverage these innovations to reduce technical debt and improve production sophistication are positioned to become the next generation of category leaders in an increasingly competitive global market.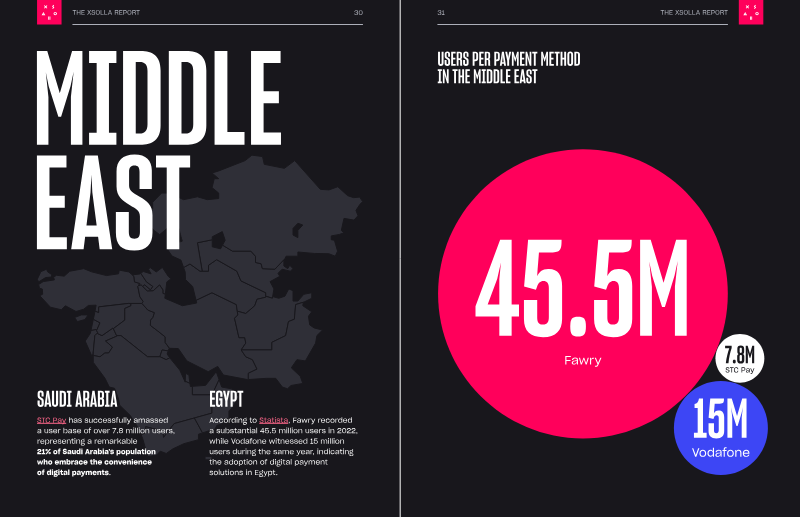
Xsolla · 2023
ReportThe Xsolla Report: The State of Play
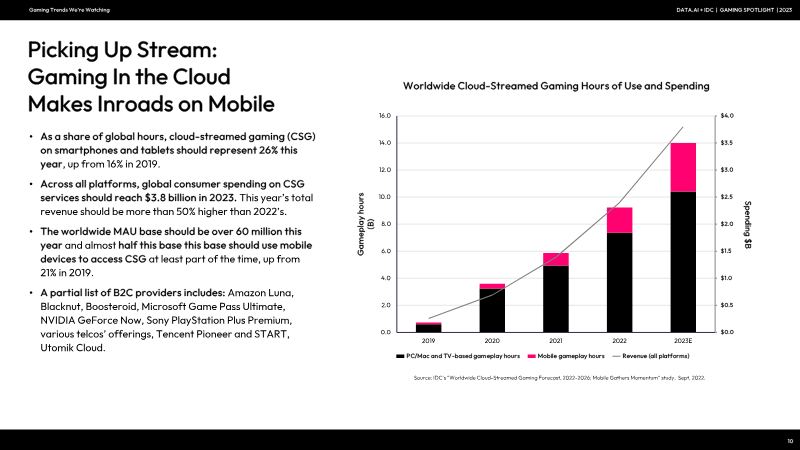
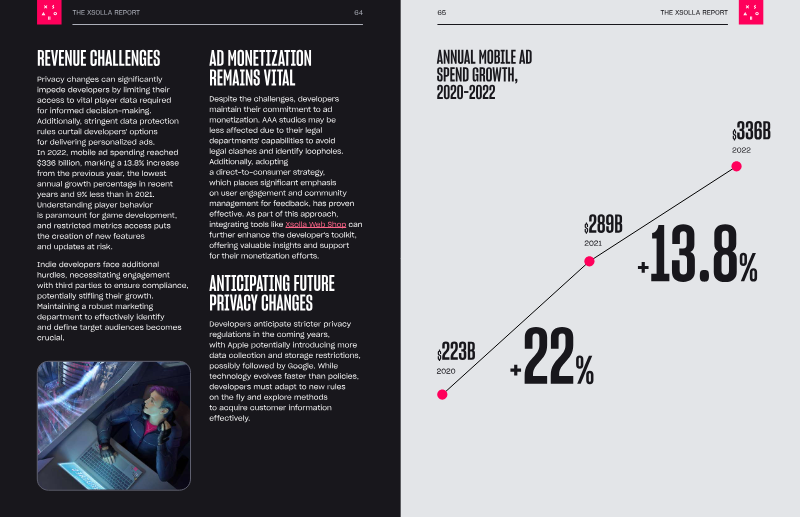
The global gaming market is undergoing a structural transformation driven by multiplatform integration and the rapid evolution of financial technologies, with total revenues projected to reach $211.2 billion by 2025. A significant catalyst for this growth is the rise of real-time payments, which are expected to account for 28% of global electronic transactions by 2027. This shift is particularly pronounced in emerging markets across the MEA and LATAM regions, where systems like India’s UPI and Brazil’s PIX are facilitating new revenue streams. To bypass traditional platform commissions and rising acquisition costs, developers are increasingly adopting mobile web shops and hybrid monetization models, including Buy Now, Pay Later services, which are forecasted to reach a $309 billion market value by 2030. Technological advancements in cloud gaming and artificial intelligence are further reshaping the industry landscape. Cloud gaming is anticipated to reach 2.5 billion users by 2024, though it continues to face technical challenges regarding latency and infrastructure. Simultaneously, generative AI is becoming a fundamental development pillar, with over 50% of top studios expected to utilize the technology by 2024 to improve efficiency by up to 30%. Within the next decade, AI is projected to support more than half of the entire game creation process, significantly reducing production timelines and costs. The industry is also pivoting toward a more interconnected ecosystem where cross-platform capabilities are a primary consumer demand, supported by 87% of multiplayer gamers. This integration, combined with advancements in virtual reality and blockchain, is fueling the expansion of the metaverse, which is forecasted to reach a $710 billion valuation by 2027. As privacy regulations and shifting ad efficiencies challenge traditional growth strategies, the sector is prioritizing flexible payment solutions and immersive, cross-play environments to maintain global momentum.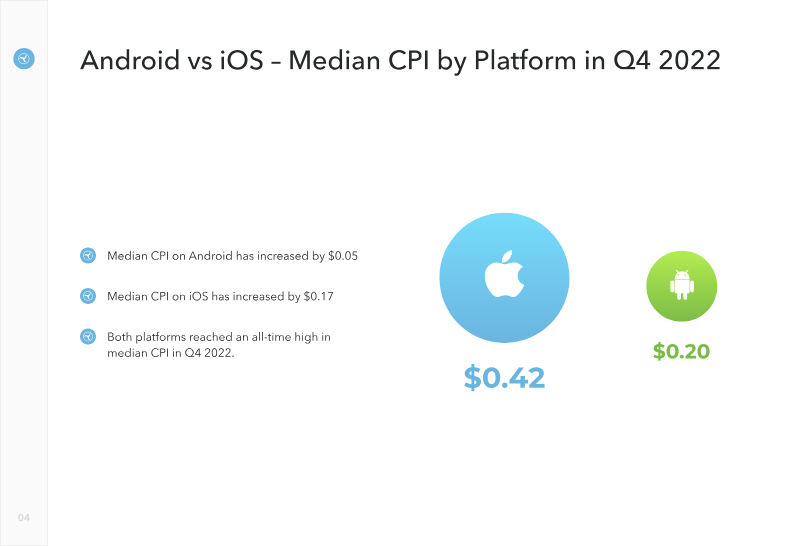
Tenjin · 2022
ReportHyper-Casual Games Benchmark Report: Q4 2022
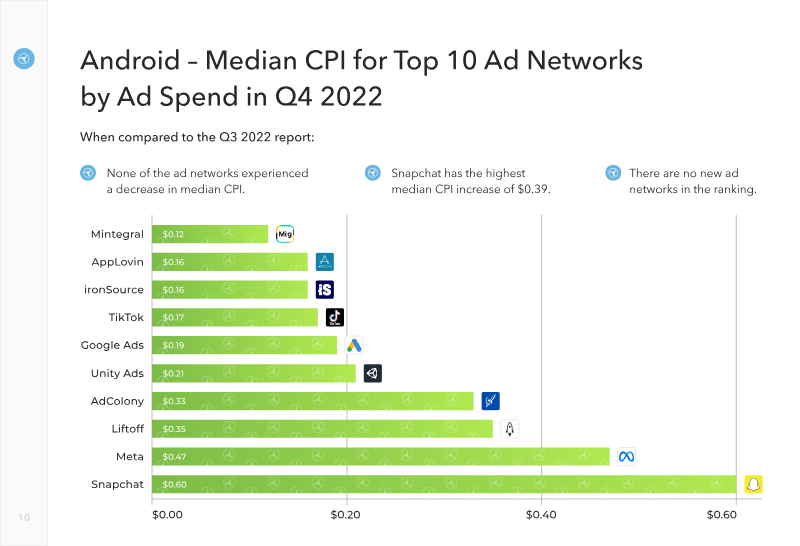
The benchmark focuses on hyper-casual mobile games during the fourth quarter of 2022, comparing performance metrics across iOS and Android and highlighting shifts from the previous quarter. Data are drawn from GameAnalytics, which tracks more than 100 000 titles and reaches roughly one-third of the global mobile player base, providing a broad, cross-regional view of the segment. Cost-per-install (CPI) reached an all-time high of $0.20 median on both platforms, with the overall median CPI rising to $0.42. Android’s median CPI grew by $0.05 while iOS saw a larger increase of $0.17. Among the top ten ad-spending countries, the United States posted the highest iOS median CPI at $0.80, overtaking France and Germany, while Brazil dropped out of the ranking. South Korea and Canada recorded the steepest CPI hikes on Android, each climbing $0.06 from Q3 2022. The report covers major markets in North America, Europe, Asia-Pacific and Latin America, reflecting a worldwide scope. Retention benchmarks reveal a consistent advantage for iOS. In the top-2% of games, Day 1 retention was 45% on iOS versus 38% on Android, and Day 7 retention stood at 19% versus 14%. For the top-25% tier, Day 1 rates were 33% (iOS) and 28% (Android), with Day 7 at 10% and 6% respectively. Across all titles, median Day 1 retention was 24% on iOS and 23% on Android, while median Day 7 retention was 7% versus 4%. The gap between elite, good and average games is pronounced, underscoring the importance of early-stage player engagement. Overall, Q4 2022 saw rising acquisition costs and modest but platform-dependent retention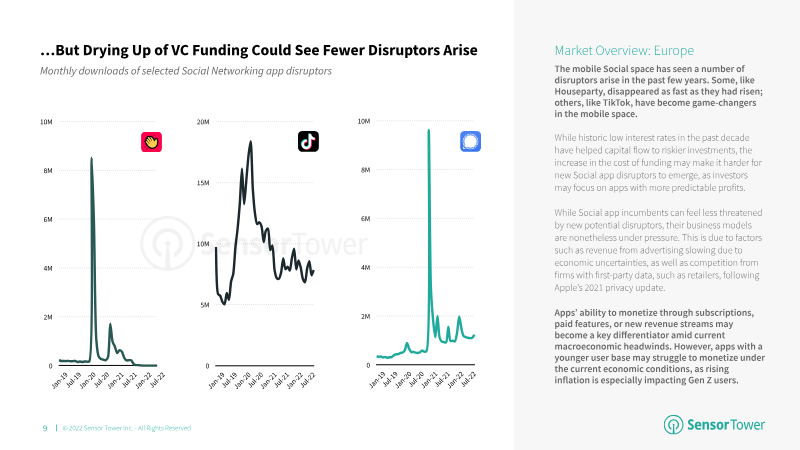
Sensor Tower · 2022
ReportThe State of Social Apps in Europe 2022
The European social application market in 2022 was characterized by a significant shift from rapid user acquisition toward aggressive monetization and the rise of niche, authenticity-driven platforms. While overall download volumes stabilized following the 2020 pandemic peak, consumer spending reached a record $830 million in the first ten months of 2022, representing an 86% year-over-year increase. This financial surge was primarily driven by TikTok, which maintained its position as the region's most downloaded app while diversifying its revenue streams through gaming, music, and high-value in-app purchases. Despite this dominance, TikTok’s revenue growth began to decelerate by the third quarter of 2022, signaling a maturing market. Competitive dynamics within the messaging and social networking subsectors revealed a diversifying landscape. Telegram emerged as a formidable challenger to WhatsApp, nearly closing the download gap and capturing significant market share in Russia. Simultaneously, BeReal disrupted the market by targeting Gen Z with dual-camera, privacy-focused content, forcing established giants like Instagram and TikTok to develop similar features to retain younger demographics. These shifts occurred against a backdrop of lower barriers to entry for new apps, as the download threshold required to reach the top of the App Store rankings declined by 30% compared to 2019. Despite the emergence of new competitors and shifting consumer preferences, legacy platforms maintained a strong foothold across the continent. Meta-owned applications, particularly Facebook, continued to lead in monthly active users across most European markets, with sustained dominance in Central and Eastern Europe. The industry's evolution reflects a broader transition where established leaders leverage massive existing user bases to pivot toward new monetization strategies, while newcomers focus on hyper-specific engagement models to challenge the status quo in an increasingly fragmented digital ecosystem.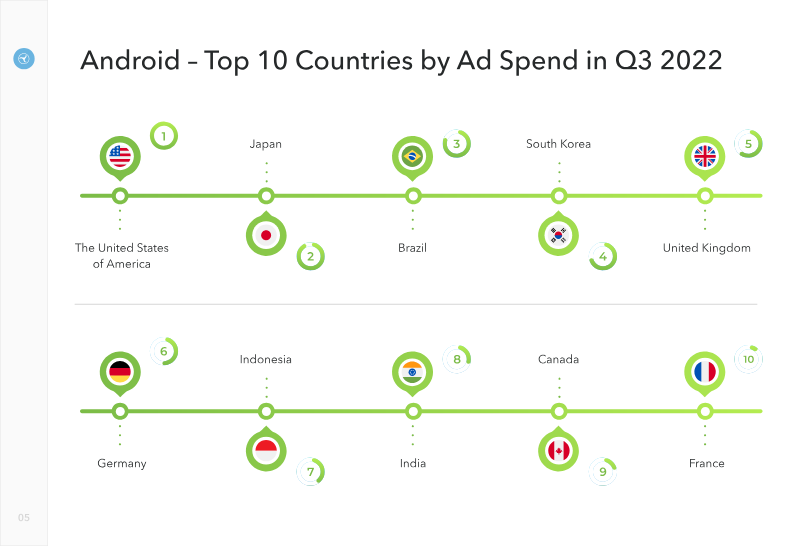
Tenjin · 2022
ReportHyper-Casual Benchmark Report Q3 2022
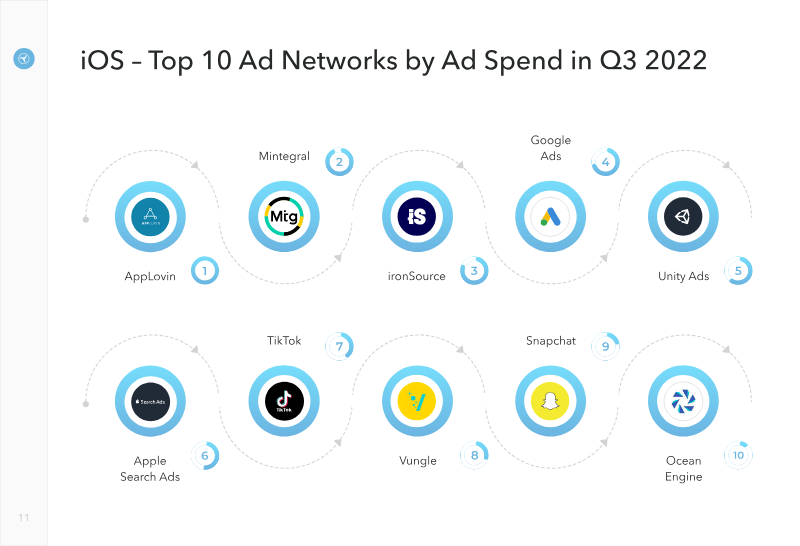
The hyper-casual gaming landscape continues to evolve as developers navigate shifting attribution models and monetization strategies. Analysis of the sector reveals that advertising remains the primary revenue driver, with a heavy reliance on high-volume user acquisition and optimized ad mediation. Data from 2021 and 2022 indicates that the top-performing ad networks for hyper-casual titles are those capable of delivering massive scale at low costs per install, while simultaneously providing robust monetization tools to capture value from short-lived player lifecycles. Geographic trends show a significant concentration of activity in established markets, though emerging regions are increasingly contributing to the global install base. The industry segments covered include both Android and iOS platforms, with a specific focus on how privacy changes have impacted attribution and marketing efficiency. Statistics suggest that while the cost of acquiring users has fluctuated, the most successful publishers are those utilizing sophisticated data analytics to balance spend across a diverse range of ad networks. Methodological insights derived from industry benchmarks highlight the importance of real-time data processing and cross-platform tracking. By examining the performance of the top ten ad networks, it becomes clear that market leadership is defined by the ability to integrate seamlessly with attribution partners. The findings conclude that the hyper-casual market remains resilient, provided that developers adapt to the technical requirements of modern mobile advertising and maintain a rigorous focus on retention metrics and effective ad placement strategies.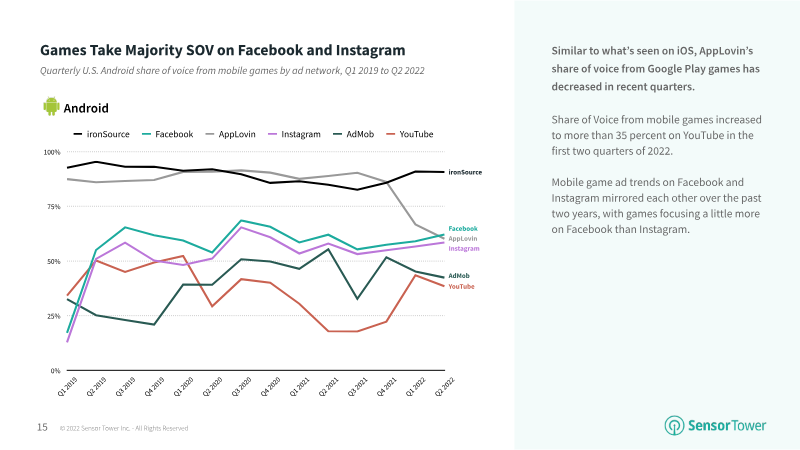
Sensor Tower · 2022
ReportMarket Outlook 2022: An Overview & Analysis of Industry Trends
The global mobile gaming market is currently undergoing a period of stabilization following unprecedented pandemic-era growth, characterized by a slight 6% year-over-year revenue decline to $21.2 billion in early 2022. Despite this correction, the industry maintains a high baseline of approximately 14 billion quarterly downloads and is projected to reach $117 billion in annual revenue by 2026. While casual titles account for 78% of total downloads, the financial core of the industry remains the mid-core segment, specifically RPG and strategy genres, which generate 60% of all player spending. Growth is increasingly concentrated in Asia-Pacific markets, though Western regions are showing significant engagement spikes driven by major intellectual property launches. The RPG and MMORPG sectors remain the primary engines of monetization, particularly in Asian markets which contribute 80% of total genre revenue. However, the successful launch of titles like Diablo Immortal, which earned $28 million in its first six weeks in the United States, signals an expanding Western appetite for these complex mobile experiences. Simultaneously, the card battler sub-genre has emerged as a top-five growth category, benefiting from cross-media synergies and established franchises. This expansion is supported by a strategic shift in advertising, as developers increasingly leverage social platforms like YouTube and Instagram to capture a higher share of voice among target demographics. Market leadership in the strategy and RTS segments is shifting, with China surpassing the United States in player spending for real-time strategy titles. While established leaders like Clash Royale maintain global dominance, the success of newer entries demonstrates that local market expertise and the integration of popular IPs are essential for sustained growth. As the industry moves toward a projected 73 billion annual downloads by 2026, the reliance on sophisticated advertising networks and the ability to monetize mid-core audiences will define the competitive landscape of the mobile gaming ecosystem.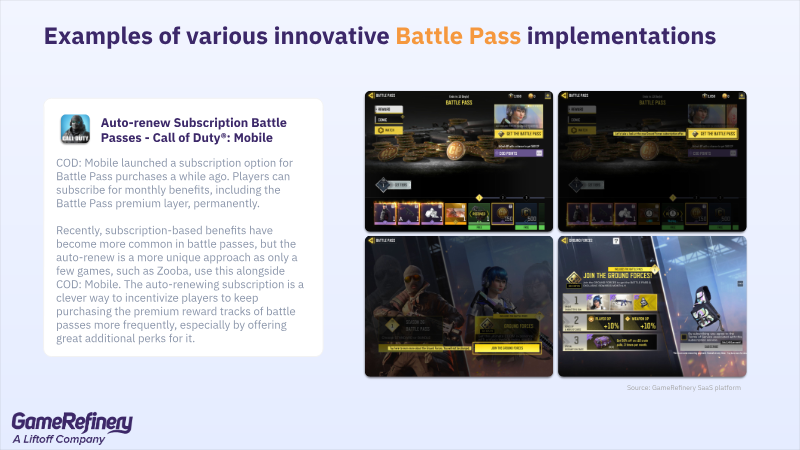
GameRefinery · 2022
ReportInnovative Monetization Features Snapshot Report June 2022
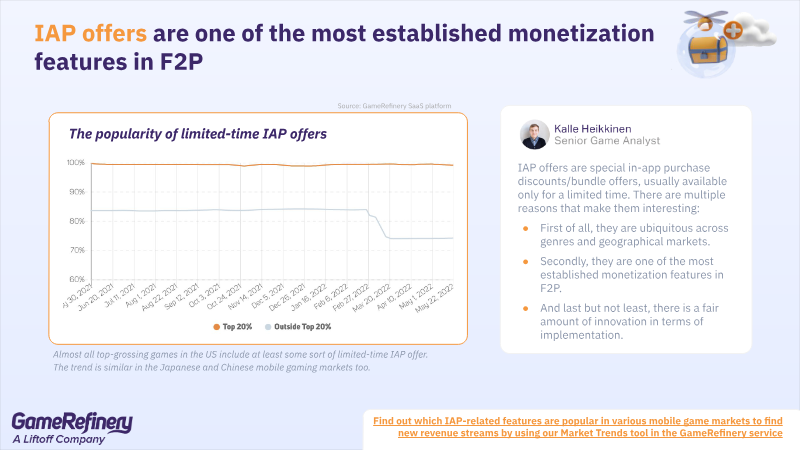
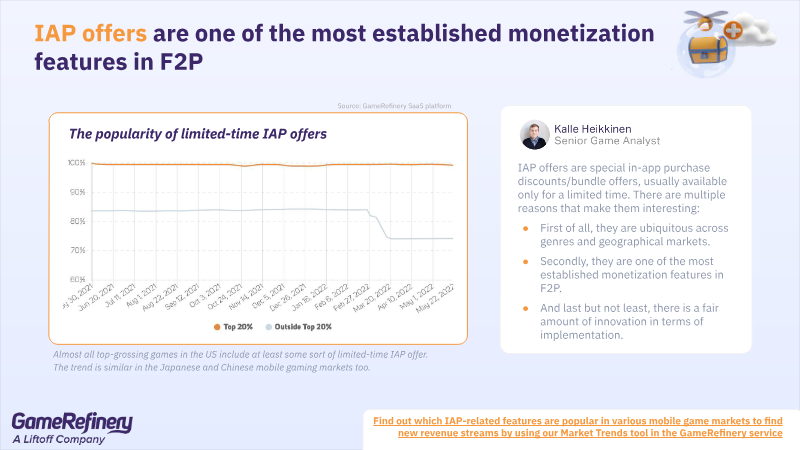
The mobile gaming landscape in mid-2022 is defined by the maturation and diversification of Battle Passes and gacha mechanics, which serve as the primary drivers for revenue in top-grossing titles. Battle Passes have evolved into sophisticated retention tools, appearing in 60% of high-performing games and incorporating social elements like guild-wide rewards and cooperative progression. Gacha mechanics remain even more pervasive, integrated into 93% of top titles in Japan and 75% of the top 20% grossing games in the United States. To maintain player trust and engagement, these systems increasingly feature transparency-focused innovations such as "pity" mechanics, player-selected prize pools, and social "joint-pull" events. Monetization strategies are shifting away from direct gameplay boosters toward meta-layer engagement, focusing on narrative depth and cosmetic customization. Successful developers utilize psychological triggers like urgency and exclusivity through "Mystery Shops" and randomized discount events. For instance, mechanics that allow players to manipulate bundle contents or discount rates increase perceived agency, while quantity-based limitations create social pressure to purchase. These tactics are particularly effective when combined with hybrid monetization models, such as ad-supported tracks that convert non-paying users into the ecosystem. Data indicates a clear correlation between sophisticated in-app purchase structures and market success. Progressive reward systems, which grant bonuses based on cumulative spending thresholds, are utilized by 23% of the top 20% grossing US iOS games, a significantly higher adoption rate than the 9% seen in lower-performing titles. By prioritizing player agency and social integration over simple transactional offers, developers are able to drive higher conversion rates and long-term player loyalty across diverse global markets and genres.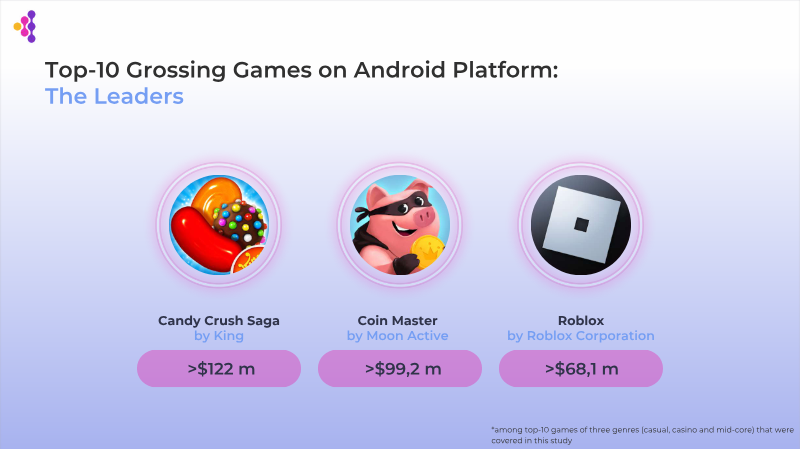
Apptica · 2022
ReportThe Highest-Grossing Mobile Games on iOS & Android: Q2 2022
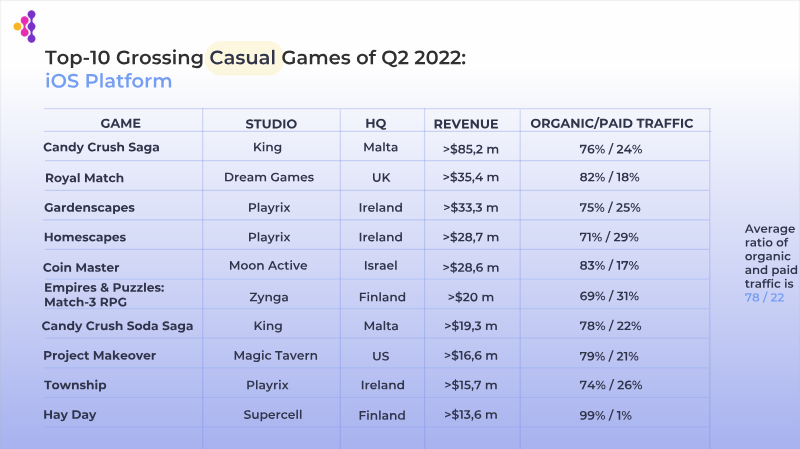
The analysis set out to pinpoint the highest-grossing mobile games of the second quarter of 2022, evaluating performance across Android and iOS markets. Data were drawn exclusively from Apptica’s Top Apps section, covering 37 countries between 1 April and 30 June 2022, and were segmented into casual, casino and mid-core categories without supplementation from other analytics services. Across both platforms, mid-core titles generated the greatest revenue, with “Rise of Kingdoms” leading the chart at $179.5 million. Other top earners included “Candy Crush Saga” ($122 million), “Coin Master” ($99.2 million) and “Roblox” ($68.1 million). Casual games such as “Homescapes,” “Gardenscapes” and “Royal Match” each surpassed $20 million, while casino titles like “Slotomania” and “Jackpot Party” contributed between $10 million and $30 million. Organic traffic dominated most titles, typically accounting for 70-95% of user acquisition, with paid channels playing a smaller role. Publisher analysis showed King as the highest-grossing publisher with over $264 million from four leading titles, followed closely by Lilith Games ($254.6 million) and Playrix ($182.8 million). Playrix and Playtica each appeared in 16.2% of top-10 slots, while Supercell and King accounted for 10.8% each, and Lilith Games 8.1%. Studios headquartered in the United States held the most positions (17), with Finland, Singapore, Hong Kong and Israel also featuring prominently. The study concludes that mid-core games dominate revenue in Q2 2022, “Rise of Kingdoms” stands as the single biggest earner, and a relatively small group of publishers and studios capture the bulk of market share, underscoring the concentration of financial success within a few leading developers and regions.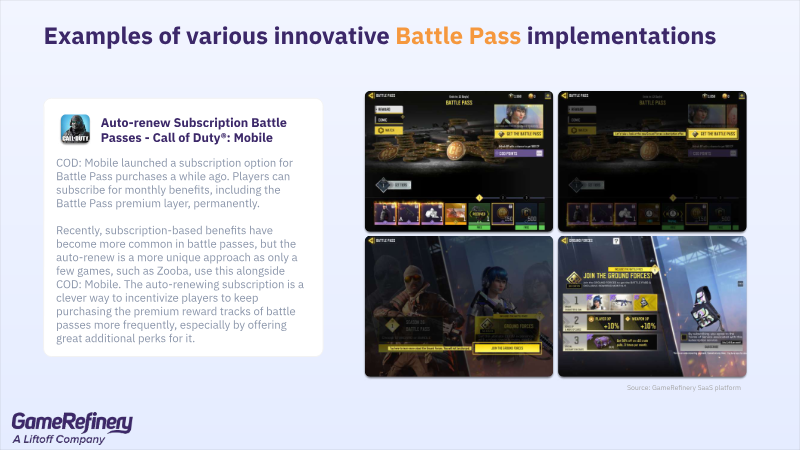
GameRefinery · 2022
ReportInnovative Monetization Features Snapshot Report
Modern mobile game monetization is increasingly defined by the integration of sophisticated Battle Pass systems and gacha mechanics, which serve as the primary drivers for the industry's highest-grossing titles. Gacha mechanics are nearly universal among top-tier games, appearing in 93% of the top 20% grossing titles, while Battle Passes are utilized by 60% of this same demographic. These tools have evolved from simple transactional models into complex systems that leverage social cooperation, urgency, and psychological progression. Innovations such as auto-renewing subscriptions, social gifting within guilds, and "pity" systems for gacha pools have become standard practices to ensure transparency and maintain long-term player engagement without compromising core gameplay balance. The geographic focus remains centered on the United States mobile market, where 75% of top-grossing games now employ gacha mechanics. A significant shift is occurring in the nature of in-app purchases, moving away from direct gameplay boosters toward meta-layer content such as narrative elements and collectibles. Furthermore, progressive reward systems—which provide escalating gifts based on cumulative spending—have seen a steady two-year increase in adoption. These systems are highly correlated with financial success, as they are nearly three times more likely to be found in top-performing iOS games than in lower-grossing titles. Ultimately, the most successful monetization strategies rely on emotional triggers and social integration rather than isolated transactions. Features like randomized "Mystery Shops" and quantity-limited community offers create a sense of scarcity and collective participation. Developers who find success in this landscape are those who look across diverse genres to adapt innovative features like piggy bank integrations and co-op progression tracks. By focusing on these sophisticated meta-layer incentives, studios can drive both retention and revenue while fostering a more committed player base.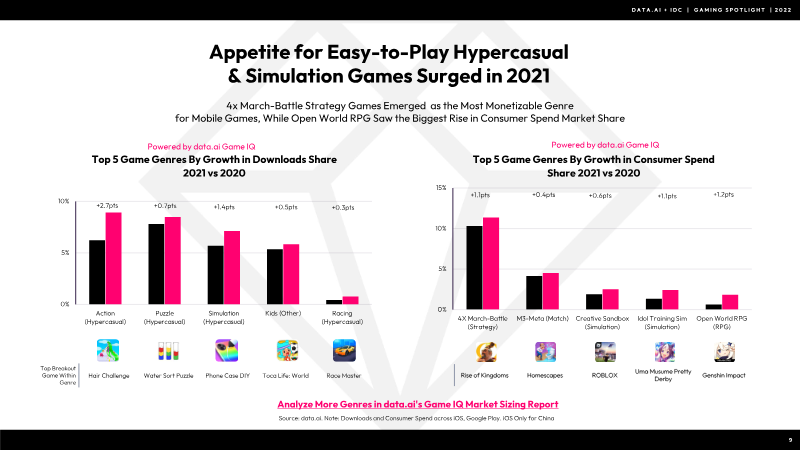
data.ai & IDC · 2022
ReportGaming Spotlight: 2022 Review
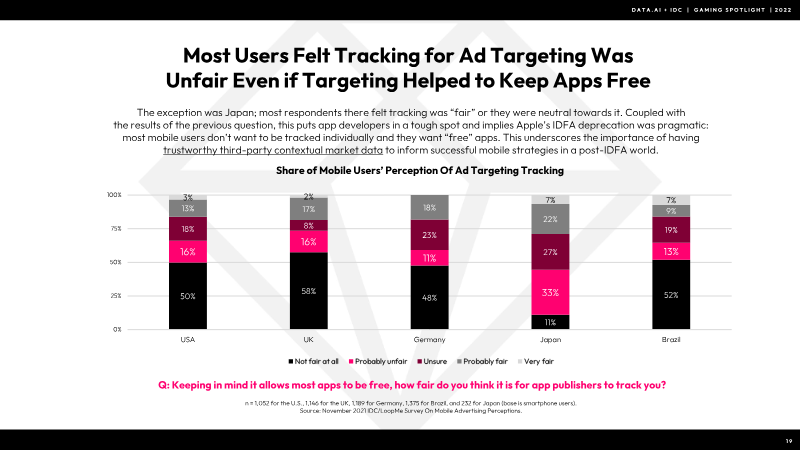
Mobile gaming has emerged as the primary engine of the global games market, projected to reach $136 billion in 2022 and accounting for over 60% of the industry's total $222 billion valuation. This segment is expanding 3.3 times faster than the home console market, driven largely by the Asia-Pacific region and the sustained popularity of core titles such as Genshin Impact and Roblox. While macroeconomic instability and geopolitical conflict have caused localized spending declines in Eastern Europe, the broader global trend points toward a more inclusive player base. Female gamers and Gen Z cohorts are increasingly influential, serving as primary drivers of monetization and shifting the demographic focus of the industry. The monetization landscape is undergoing a significant transformation toward hybrid models, with 42% of top-grossing U.S. games now combining in-app purchases with advertising. Although global audiences generally accept advertisements in exchange for free content, privacy concerns regarding individual tracking have intensified. In a post-IDFA environment, success depends on leveraging contextual third-party data rather than granular user tracking. Player sentiment varies significantly by format; rewarded video and playable ads enjoy the highest levels of acceptance, while standard video ads remain divisive, particularly among the high-growth female and Gen Z demographics. Strategic intelligence for this evolving market relies on extensive global research infrastructure, utilizing data from over 1,100 analysts across 50 countries. By surveying more than 350,000 end users annually, market analysts provide the necessary framework for developers, publishers, and hardware manufacturers to navigate shifting consumer behaviors and technological transitions. This comprehensive oversight ensures that stakeholders can adapt to the rapid pace of innovation and the diversifying needs of the global gaming community.
Newzoo · 2022
Report