Monetization & Live Ops
Revenue models, in-game economies, retention and live operations.
258 documents
Liftoff · 2023
Report2023 Liftoff Company Midcore Gaming Apps Report
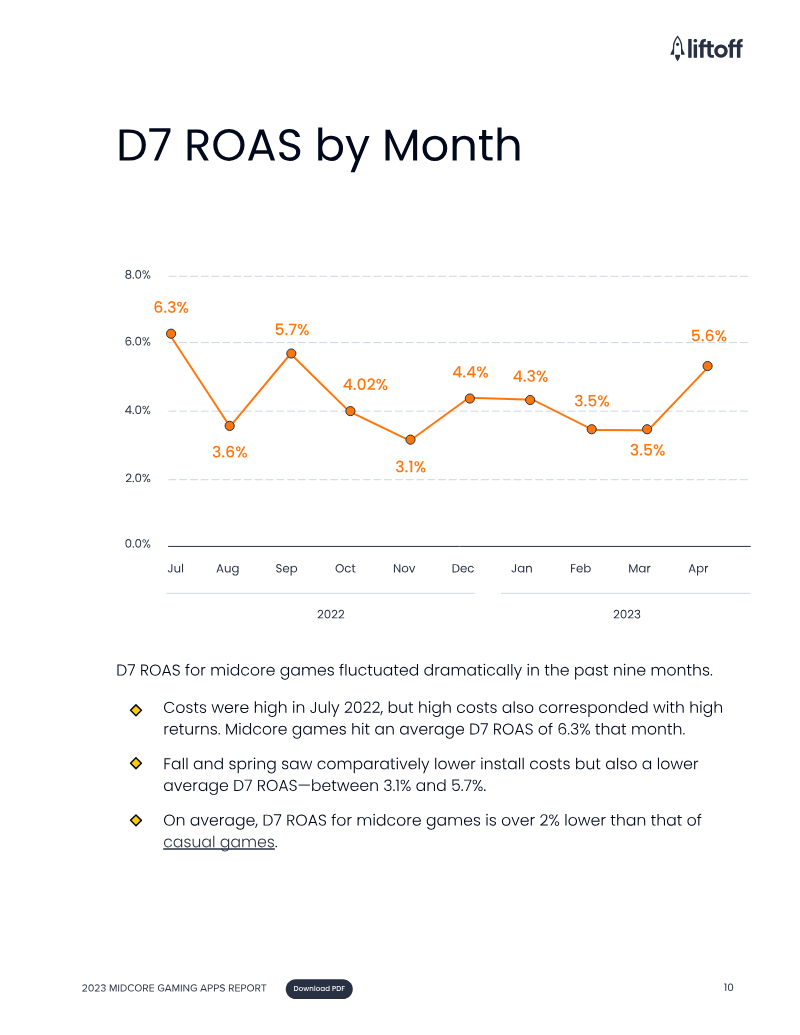
The midcore mobile gaming market in 2023 is defined by a strategic pivot toward deeper gameplay mechanics and diversified monetization streams, now commanding 35% of total iOS gaming revenue in the United States. While North America remains the most lucrative region with a 4.5% Day-7 return on ad spend, significant performance disparities exist between platforms. Android offers a more cost-effective environment for user acquisition compared to iOS, though the shooter genre remains the most expensive and rewarding category, commanding a $7.47 cost per install alongside a leading 6% Day-7 return on ad spend. Market longevity favors midcore titles over casual alternatives, as evidenced by midcore games being twice as likely to maintain a top-200 grossing position over a twelve-month period. The strategy genre, particularly 4X and "Build & Battle" subgenres, continues to dominate revenue charts. To sustain this momentum, developers are increasingly adopting sophisticated engagement models such as extraction shooter mechanics, multi-layered Battle Passes with dedicated storefronts, and seasonal progression resets designed to prevent late-game stagnation. Operational strategies have shifted toward aggressive LiveOps and the circumvention of traditional platform fees. Top-performing titles typically manage fifteen simultaneous unique events and fifteen limited-time gachas to drive consistent monetization. Furthermore, publishers are leveraging legal shifts to direct players toward external web stores, offering better value while avoiding app store commissions. Competitive social structures remain the backbone of retention, with 88% of leading midcore games utilizing permanent PvP seasons and over half incorporating guild-based competitions to foster long-term player commitment.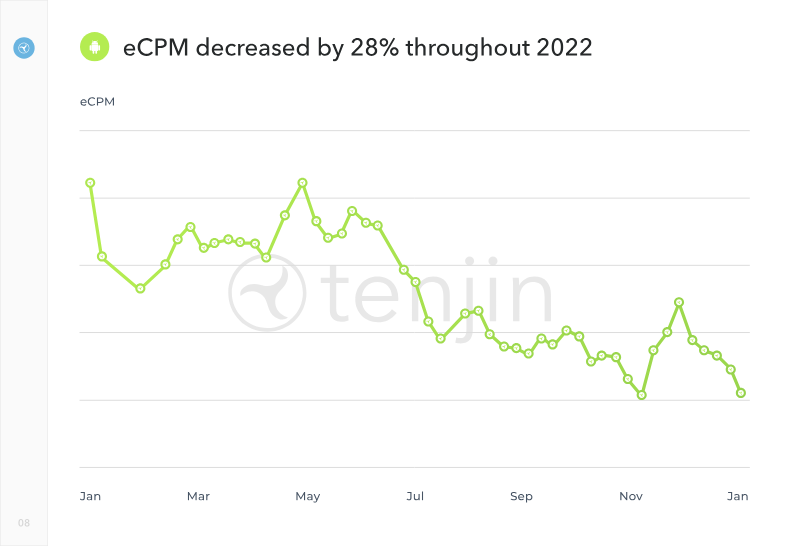
Tenjin · 2023
ReportHyper to Hybrid: Mobile Gaming Market Trends 2023
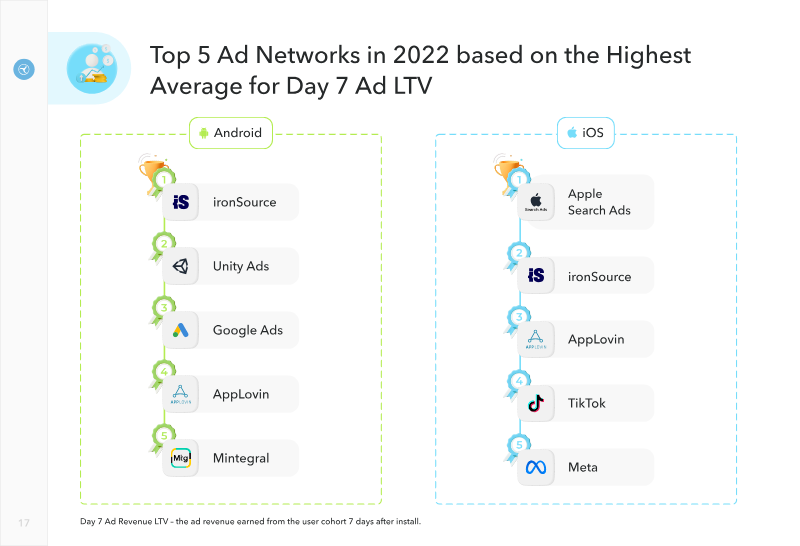
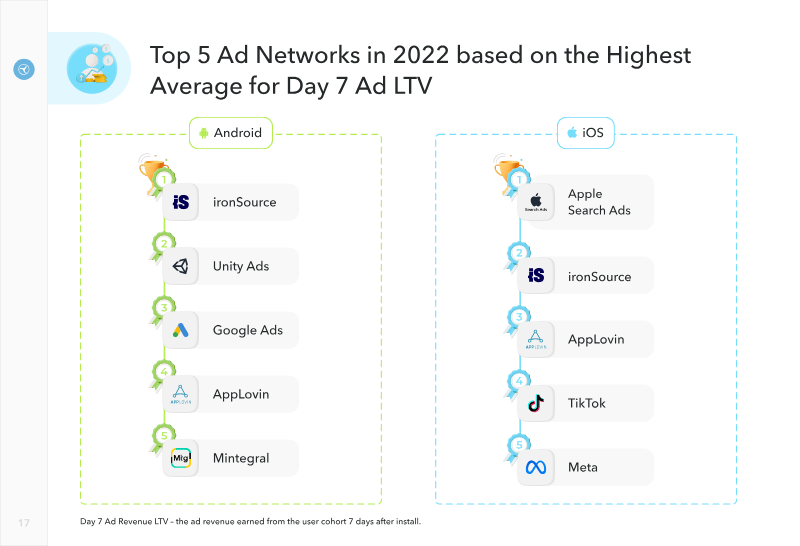
The mobile gaming landscape is undergoing a fundamental shift as developers transition from hyper-casual to hybrid-casual business models. This evolution is driven by a significant downward trend in ad revenue profitability, influenced by Apple’s App Tracking Transparency framework, shifting post-pandemic user behaviors, and increased selectivity from major publishers. To maintain sustainability, developers are increasingly adopting self-publishing strategies and integrating sophisticated meta-gameplay components alongside in-app purchases to diversify revenue streams beyond traditional advertising. Data from the 2022 calendar year reveals a cooling market for ad-centric models, characterized by declining ad impressions and effective cost per mille (eCPM) across both Android and iOS platforms. Conversely, the volume of in-app purchases grew on both operating systems, signaling a successful pivot toward hybrid monetization. Geographically, India emerged as the leader for Android installs, while the United States maintained its position as the primary market for both ad revenue and in-app purchase value across all devices. The competitive landscape for ad networks and monetization channels shows distinct platform preferences. Apple Search Ads dominates iOS rankings for installs, retention, and lifetime value, while AppLovin and ironSource lead the Android market. AppLovin currently stands as the top monetization channel by total ad revenue on both platforms. These findings are based on anonymized data from the full 2022 period, utilizing a weighted average methodology for performance metrics and focusing on networks and regions that exceeded a threshold of 25 million installs. The analysis underscores a broader industry movement toward deeper player engagement and more complex economic structures in mobile gaming.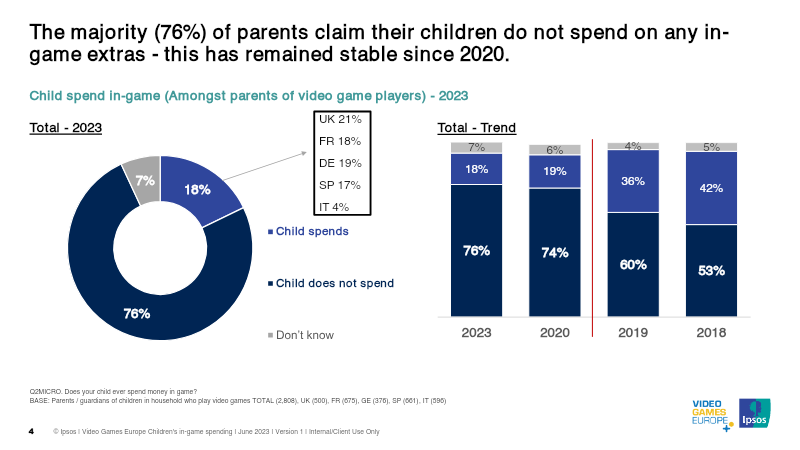
Video Games Europe · 2023
ReportIn-Game Spending: Parents' Supervision of In-Game Spending 2023
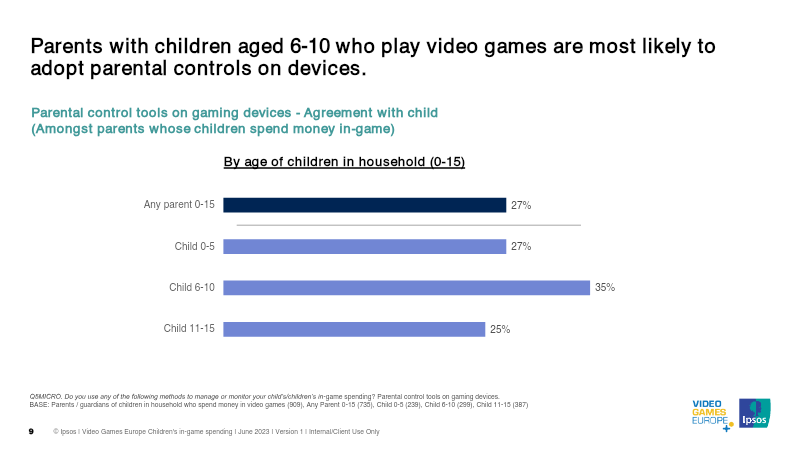
The research investigates how parents supervise and manage their children’s in-game purchases, tracking trends across five European markets—United Kingdom, France, Germany, Spain and Italy—over four survey waves (2018, 2019, 2020 and 2023). Each wave surveyed adult parents or guardians of children who play video games, with sample sizes ranging from 962 in 2018 to 2,808 in 2023, providing a broad cross-section of the region’s gaming households. Findings show that three-quarters of parents consistently report that their children do not spend on in-game extras, a proportion that has remained stable since 2020. Among the minority who do spend, the average monthly outlay rose from €33 in 2020 to €39 in 2023, reflecting a €6 increase that aligns with inflation. Most spending (64%) falls within the €1-20 range, with the most popular items being gameplay-impacting content (34%) and decorative or cosmetic items (just under one third). Loot boxes and other unknown-reward items remain relatively unpopular. Parental oversight is high: nine-in-ten parents of spending children have some form of agreement, half of which are explicit—either seeking permission (38%) or setting limits (23%). Preferred monitoring tools include credit-card bill checks, parental-control settings, and two-factor authentication, though 44% of parents who avoid controls deem them unnecessary and 32% find them difficult to activate. Awareness of in-game currency and loot boxes among all players (ages 11-64) is also limited, with only 9% having purchased in-game currency and 4% having bought loot boxes. The study’s methodology relies on standardized questionnaires administered to representative adult panels in each country, ensuring comparability within each survey year while noting that cross-year comparisons are constrained by methodological changes.
Nexters · 2023
ReportMisleading (Non-Core) Gameplay Ads Research 2023
The prevalence and perception of non-core gameplay advertisements, often categorized as misleading, represent a significant shift in mobile gaming marketing strategies. Based on a 2023 survey of 5,212 respondents across the United States, Japan, Europe, and Brazil, findings indicate that a vast majority of gamers have encountered these ads. Recognition is highest in the United States at 91%, while other regions range between 71% and 77%. Despite the controversial nature of these promotions, approximately 75% of players in Western markets and 70% in Japan and Brazil admit that the mechanics showcased in these ads are often more fascinating than the actual core gameplay of the advertised titles. The research challenges the assumption that misleading ads lead to immediate user churn. Between 35% and 46% of gamers reported they would continue playing a game despite the discrepancy, choosing to evaluate the product on its own merits rather than the accuracy of the advertisement. Players generally understand that developers use these tactics to inflate download numbers and revenue or to revitalize interest in older titles. The most appealing elements of these ads are the specific gameplay mechanics and puzzles, while user interface and new features hold the least draw. Notable titles associated with this phenomenon include Hero Wars, various "Scapes" games, and Evony. Demographic data reveals that the modern gaming audience is maturing, with nearly 10% of U.S. gamers over the age of 60 and less than 2.5% of the global sample under 18. Regional preferences vary significantly; casual titles dominate the U.S. market, while RPGs and complex math-based mechanics are preferred in Japan. In Europe and Brazil, competitive RPG and MMORPG genres lead in popularity. While engagement is high in the West, with many playing over 18 hours weekly, nearly half of Japanese respondents play for less than four hours per week. Ultimately, the industry is seeing a blurring of lines as developers integrate these advertised mini-games into their products to transition from "misleading" to "non-core" content.
data.ai · 2023
Report5 Mobile App Forecasts: 2023
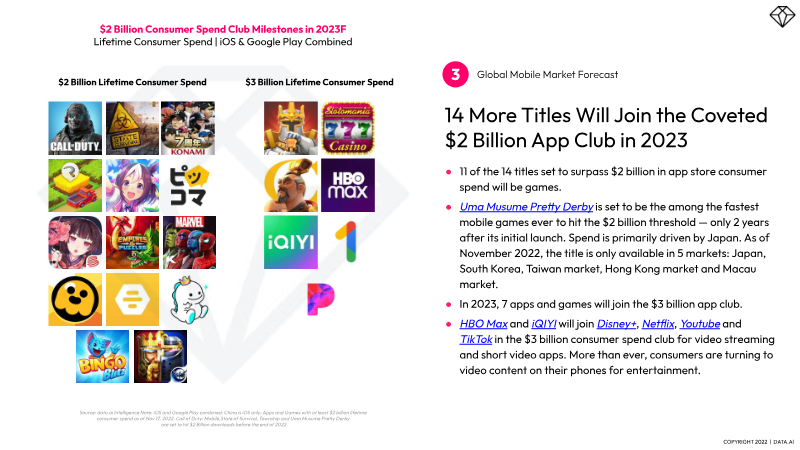
Global mobile market projections for 2023 indicate a complex landscape defined by shifting consumer priorities and economic pressures. While total mobile advertising spend is expected to reach $362 billion, growth is projected to slow due to macroeconomic headwinds. Short-form video apps are anticipated to be the primary drivers of this ad spend, helping to offset a decline in performance marketing budgets. Conversely, mobile gaming is facing a downturn, with consumer spending forecasted to drop to $107 billion in 2023. This decline is attributed to a combination of the global economic squeeze and tightening privacy regulations, such as IDFA and Google’s upcoming changes, which complicate the targeting of high-spending users. Despite the contraction in gaming spend, specific high-performing titles continue to reach massive financial milestones. Fourteen new apps and games are projected to surpass $2 billion in lifetime consumer spend during 2023, with eleven of those being games. Notably, the video streaming sector remains robust, with platforms like HBO Max and iQIYI expected to join the $3 billion lifetime spend club, reflecting a sustained consumer shift toward mobile-first entertainment. The broader mobile economy is also seeing a migration of retail dollars toward experiential sectors. As discretionary income tightens, consumers are prioritizing travel, live events, sports, and wellness over physical goods. This shift is supported by a long-term trend of increasing mobile engagement; total time spent in apps is forecasted to surpass 6 trillion hours by 2028. This growth is fueled by 5G rollout and the deepening personalization of apps, with emerging markets in Latin America, Southeast Asia, and the Middle East driving significant engagement. These findings are based on proprietary market estimates and historical data analysis of global app store performance and consumer behavior.
Unity · 2023
ReportMobile Growth & Monetization Report 2023
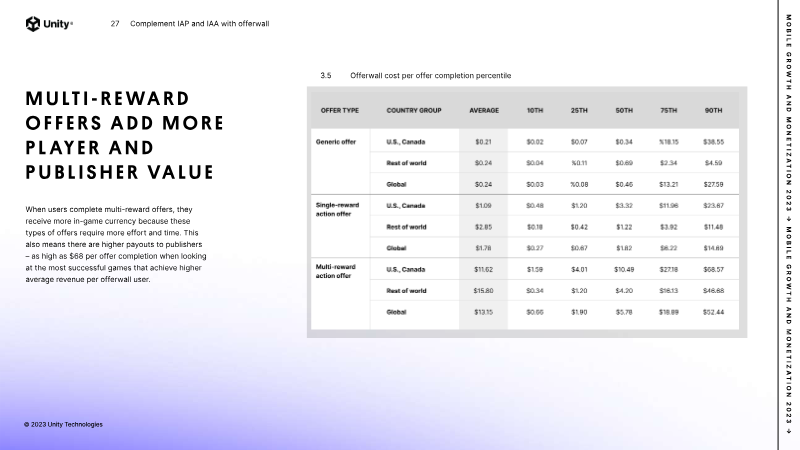
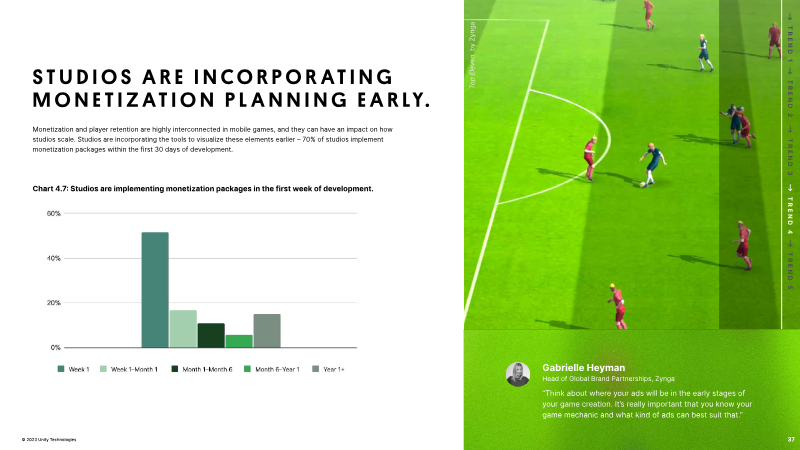
The mobile gaming landscape in 2023 reflects a strategic pivot toward operational efficiency as developers navigate softening in-app purchase (IAP) and advertising revenues. Success currently hinges on capturing player interest within the first 14 days, a critical window where 77% of all conversions occur. To capitalize on this timeframe, monetization strategies emphasize low-friction price points between $1.01 and $5.00, with high-performing assets such as virtual currencies, limited-time bundles, and sales generating over 56% of total IAP revenue. Beyond direct purchases, the integration of rewarded video ads and offerwalls has become essential for sustaining non-paying user bases. Strategic ad placement between levels or within game lobbies yields the highest engagement, particularly when incentivized by currency or gacha mechanics. Offerwalls, in particular, represent a significant growth lever, contributing 33% of total ad revenue for games utilizing multi-faceted monetization. These tools also serve as powerful retention drivers; players engaging with offerwalls demonstrate a 14% retention rate at Day 90, vastly outperforming the 3% rate seen among non-converters. From a global marketing perspective, hypercasual advertising remains the most effective conversion engine across the majority of gaming genres. Advertisers are increasingly looking toward high-value Tier-2 markets, noting exceptional click-through rates for sports titles in Japan and trivia games in South Korea. Furthermore, the adoption of Custom Store Pages is emerging as a vital tactic for improving return on investment, particularly within the puzzle, casino, and lifestyle segments. These findings underscore a broader industry trend toward data-driven personalization and diversified revenue streams to maintain long-term player lifetime value.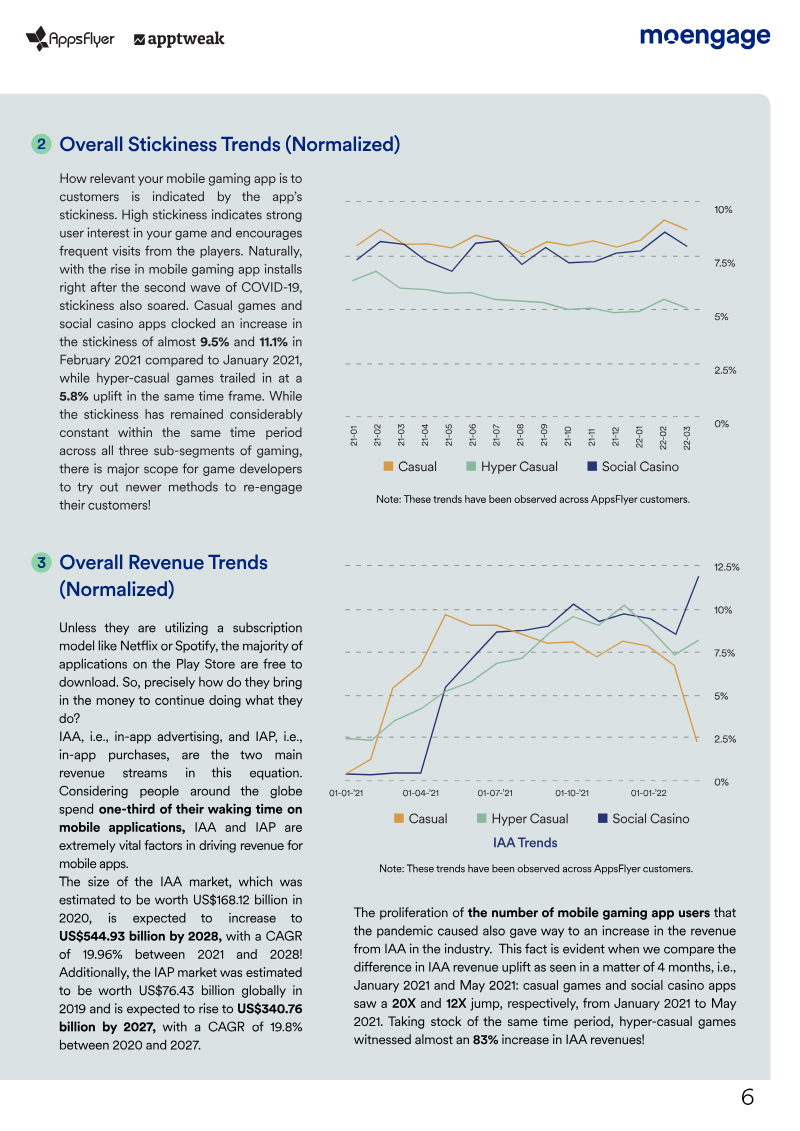
MoEngage · 2023
ReportThe State of Mobile Gaming in India: A Look at India's Casual, Hyper-Casual, and Real Money Gaming App Industry Trends
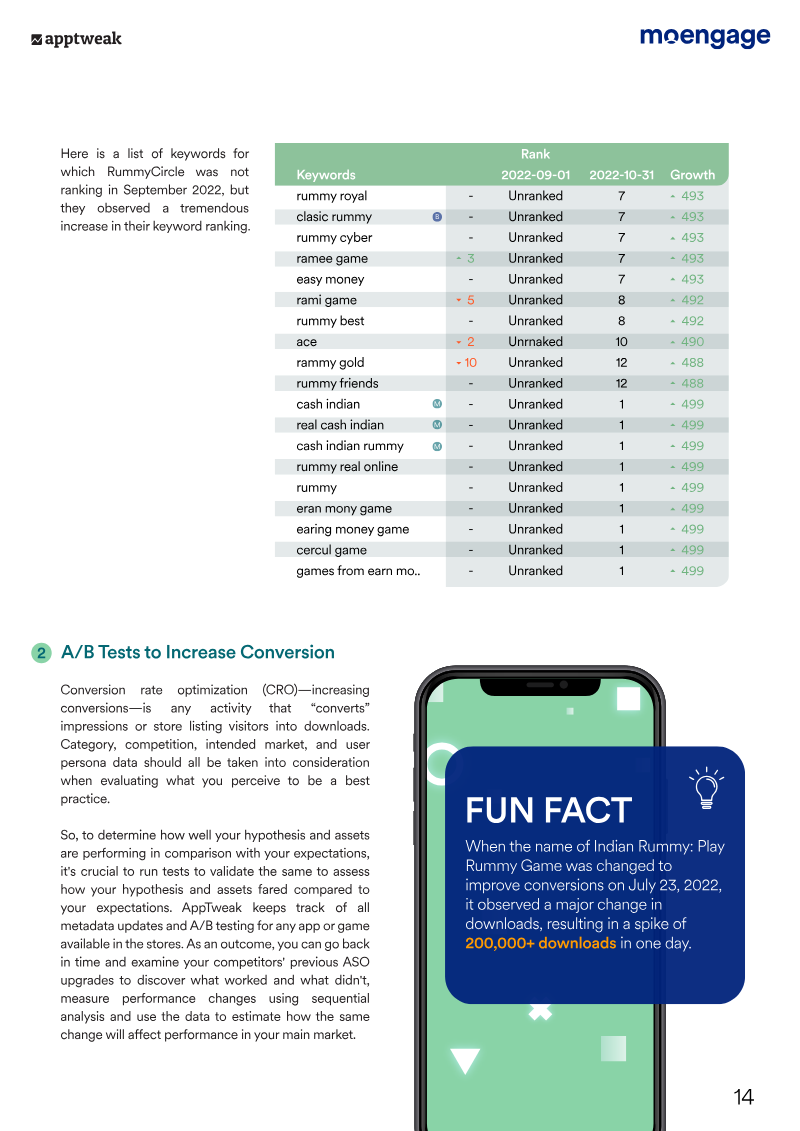
This analysis examines the rapid expansion and evolving user behavior within the Indian mobile gaming market, focusing on the casual, hyper-casual, and real-money gaming (RMG) segments. The primary thesis asserts that while the COVID-19 pandemic and increased smartphone penetration triggered a massive "gold rush" in installs and engagement, the industry now faces a critical inflection point. As organic growth stabilized in 2022, the focus for developers has shifted from simple acquisition to sophisticated, insights-led retention and monetization strategies to sustain long-term profitability. Key findings value the Indian gaming industry at $2.6 billion, with projections to reach $8.6 billion by 2027. Data indicates that India has surpassed the United States in terms of user base, exceeding 300 million gamers. During the 2021 pandemic waves, casual games saw a 90% uplift in installs, while RMG apps experienced significant revenue fluctuations, including a 35% increase in April 2021. However, the data reveals a downward trend in "stickiness" and installs moving into 2022, highlighting a retention crisis where 68% of users engage with an app fewer than ten times. The scope of the research covers the Indian market from 2021 through the first quarter of 2022, utilizing data from over 100 gaming brands. The methodology relies on a combination of market analysis from MoEngage, AppTweak, and AppsFlyer, incorporating normalized trends in installs, In-App Advertising (IAA), and In-App Purchases (IAP). The conclusions emphasize that technical optimization and personalized engagement are mandatory for survival. Effective strategies identified include App Store Optimization (ASO) to improve discoverability, RFM (Recency, Frequency, Monetary) segmentation to target "champion" players, and the use of predictive AI to prevent churn. The findings suggest that brands utilizing multi-channel engagement platforms can achieve push notification conversion rates as high as 91%, which is essential for navigating India's highly competitive and maturing digital landscape.
Adjust · 2023
ReportMobile App Trends: 2023 Edition
The mobile application market entered a period of significant transition in 2023, navigating a complex landscape defined by economic volatility and evolving privacy regulations. Despite these headwinds, the industry achieved a record half-trillion dollars in combined advertising and consumer spending. While global advertising growth slowed to 14% and consumer spending experienced a marginal 2% decline, the sector demonstrated remarkable resilience through strategic adaptations. Key shifts include a rising App Tracking Transparency (ATT) opt-in rate of 29% and an increased reliance on media mix modeling and Connected TV (CTV) to optimize return on investment in a privacy-centric environment. Sector-specific performance reveals a stark contrast between industries. Fintech and e-commerce emerged as primary growth drivers, with fintech in-app revenue surging over 90% between late 2022 and early 2023. E-commerce sessions grew by 12%, supported by record-breaking revenue peaks in late 2022. Conversely, the mobile gaming industry faced its most challenging year on record in 2022, marked by a 12% decline in installs and a 9% drop in consumer spending. However, early 2023 data indicates a nascent recovery for gaming, with installs and sessions rebounding by 10% and 11% respectively over previous averages. The current market environment necessitates a shift from broad acquisition strategies toward long-term user retention and sophisticated measurement. As retention and "stickiness" remain persistent challenges across all verticals, developers are increasingly prioritizing reattribution campaigns, personalized onboarding, and loyalty programs. Success in the coming years depends on the adoption of advanced analytics and cross-platform insights to navigate data-privacy requirements. By leveraging these tools, stakeholders can effectively drive user acquisition and maximize lifetime value in an increasingly competitive global marketplace.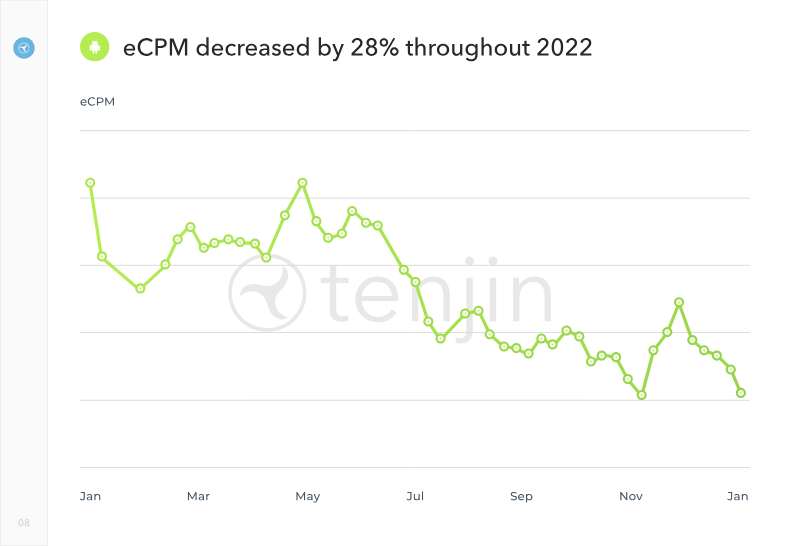
Tenjin · 2023
ReportFrom Hyper to Hybrid: Hypercasual Gaming Trends 2023
The mobile gaming landscape is undergoing a significant structural shift as developers transition from hyper-casual models toward hybrid-casual strategies. This evolution is driven by a marked decline in ad revenue profitability, influenced by the implementation of App Tracking Transparency on iOS, shifting post-pandemic user behaviors, and increased selectivity from major publishers. To maintain sustainability, developers are increasingly integrating in-app purchases and meta-gameplay components into their titles while opting for self-publishing models to retain greater control over their assets. Data from 2022 reveals a downward trend in ad impressions and eCPMs across both Android and iOS platforms. Conversely, the volume of in-app purchases grew on both operating systems, signaling a successful pivot toward diversified monetization. Geographically, the United States remains the dominant market, ranking first for both ad revenue and in-app purchases across platforms. India emerged as the leading territory for total installs on Android, highlighting the importance of emerging markets for scale, even as monetization remains concentrated in Tier 1 regions. The competitive landscape for ad networks and monetization channels shows distinct leaders. Apple Search Ads dominates the iOS ecosystem, securing the top position in multiple categories including retention and lifetime value. On Android, AppLovin and ironSource lead the market. AppLovin specifically stands out as the top monetization channel by total ad revenue on both operating systems. For eCPM performance, Meta Audience Network and ironSource lead on Android and iOS respectively. These findings are based on anonymized data collected throughout the 2022 calendar year, utilizing a weighted average methodology. The analysis focuses on high-scale performance, only including countries and ad networks that exceeded a threshold of 25 million installs. This comprehensive view underscores a broader industry movement where the traditional reliance on pure advertising is being replaced by a more balanced, hybrid approach to game design and revenue generation.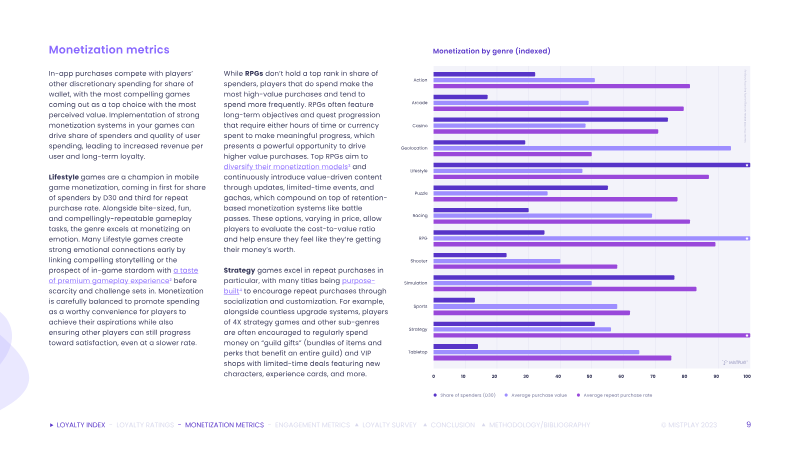
Mistplay · 2023
ReportMobile Gaming Loyalty Report 2023
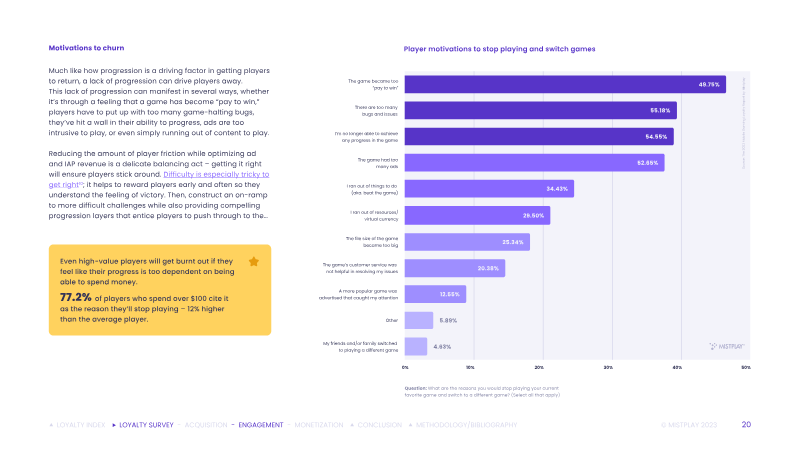
The Mobile Gaming Loyalty Report examines the drivers of player engagement, retention, and spending across the mobile landscape. By combining a longitudinal benchmark of 500 games with a survey of 3,000 mobile gamers in the US and Canada during 2023, the analysis establishes a Loyalty Index based on six key monetization and engagement KPIs. The findings emphasize that while user acquisition remains expensive, maximizing the lifetime value of existing players through loyalty-centric design is essential for sustainable growth. Role-Playing Games (RPGs) emerge as the most loyal genre, scoring 75 out of 100 on the index due to deep gameplay loops and compounding monetization systems that encourage high-value, frequent spending. Strategy games follow closely, excelling in repeat purchases and session frequency. Conversely, Lifestyle games lead in average sessions per user, utilizing bite-sized tasks and emotional storytelling to drive incremental spending. Data indicates a significant gap between average and top-quartile performers in genres like Casino and Sports, suggesting substantial room for optimization in retention and spender conversion. Consumer behavior insights reveal a disconnect between play and spend habits; while over 77% of spenders rotate between two to seven games weekly, 53% concentrate their spending on a single title. Progression is the primary motivator for both continued play and in-app purchases, whereas "pay-to-win" mechanics and poorly received updates are leading causes of churn. Notably, 39% of players will abandon a game if a bad update is not corrected within a week. High-value spenders, defined as those spending over $100, exhibit more demanding standards for app store ratings and customer service. Marketing effectiveness is heavily influenced by authenticity and social proof. Over 71% of gamers demand real gameplay footage in advertisements, and 60% consider app store ratings and reviews crucial for downloads. While digital ads remain the primary discovery tool, word-of-mouth ranks as a top-three acquisition source. Additionally, there is a strong interest in play-and-earn mechanics, with 84% of respondents open to trying games that offer tangible rewards.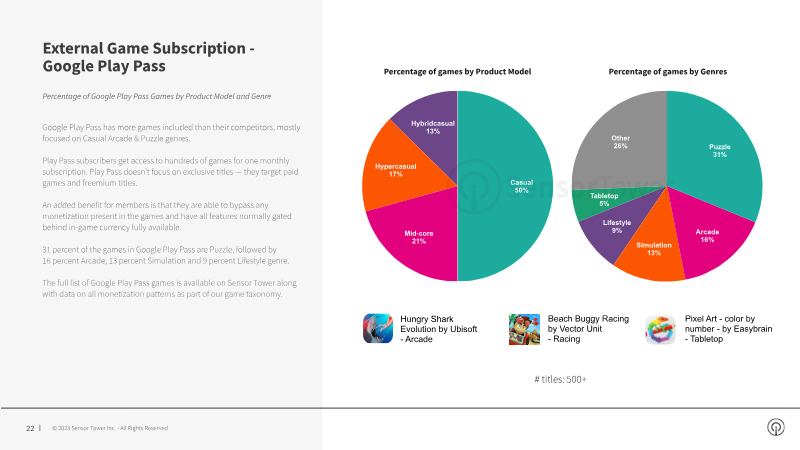
Sensor Tower · 2023
ReportThe State of Mobile Gaming 2023: Mobile Gaming Market Trends and Top Titles in the U.S., Europe, and Asia
The global mobile gaming landscape underwent a significant structural transition in 2022, characterized by a 14% decline in total player spending from its 2021 peak alongside a stabilization of download volumes at approximately 13.8 billion per quarter. While major markets such as the United States, Japan, and South Korea experienced revenue contractions, China emerged as the second-largest market globally, and India solidified its position as the leader in download volume, accounting for 17% of total installs. This period marked a definitive shift away from the hypercasual genre, which saw an 18% decline in downloads due to rising user acquisition costs and broader economic pressures. In response to these market pressures, the industry is pivoting toward a hybridcasual model that blends accessible core mechanics with sophisticated mid-core monetization and meta-progression features. This emerging segment grew by 13% and generated $1.4 billion in revenue, driven by significantly higher player engagement than traditional casual titles. Success in the current environment is increasingly dictated by the effective use of Live Ops, which now accounts for 97% of revenue among top-grossing games. Features such as character collection and social clan systems have become essential for maintaining high engagement levels and driving long-term player retention. While established genres like RPGs and shooters faced revenue declines, the action genre grew by 9%, and subscription-based models gained momentum, exemplified by the expansion of ad-free gaming catalogs. Conversely, the crypto and NFT gaming sector experienced a sharp downturn, with downloads falling from 46 million to 29 million and revenue dropping by 35%. Despite the overall contraction in spending, the market remains larger than pre-pandemic levels, with legacy titles like Honor of Kings and Subway Surfers maintaining dominance in revenue and download rankings, respectively, across a diversifying global audience.
Unity · 2023
Report