Mobile Games
The mobile market by genre, from hypercasual and puzzle to midcore and idle.
456 documents
AppMagic · 2025
ReportTop 10 Hybridcasual Games in Q1 2025: The Great Puzzle Takeover
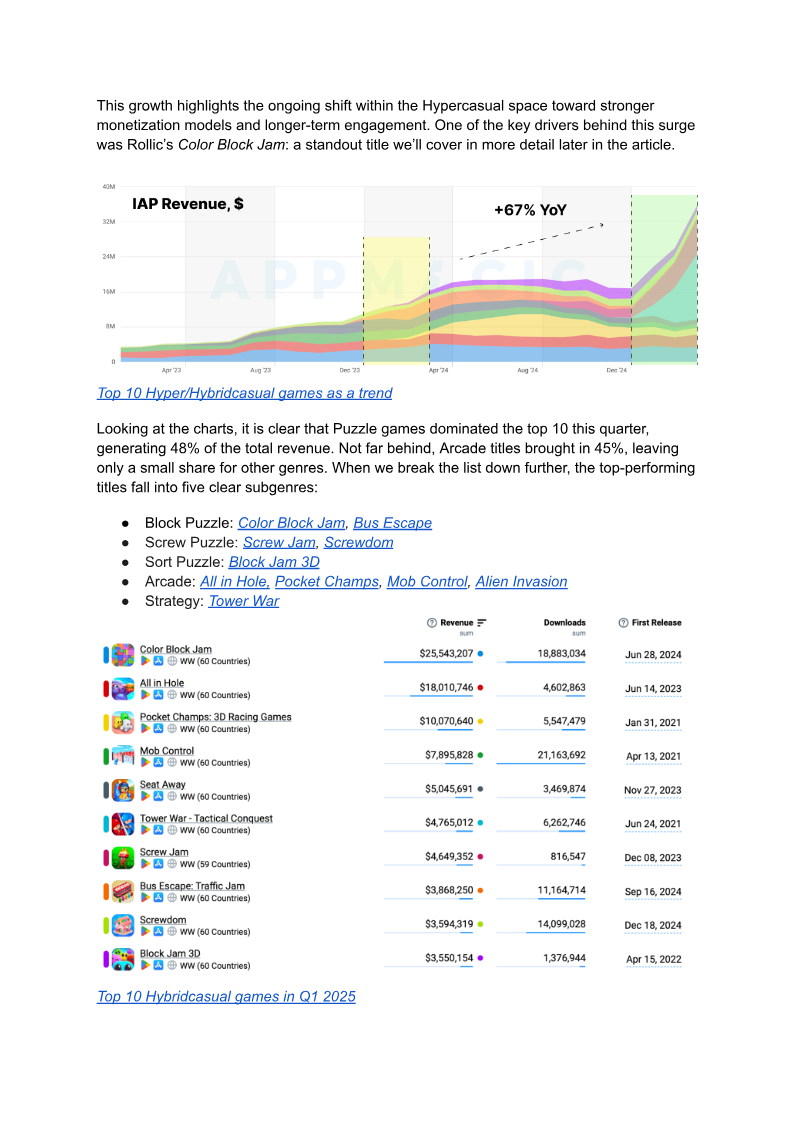
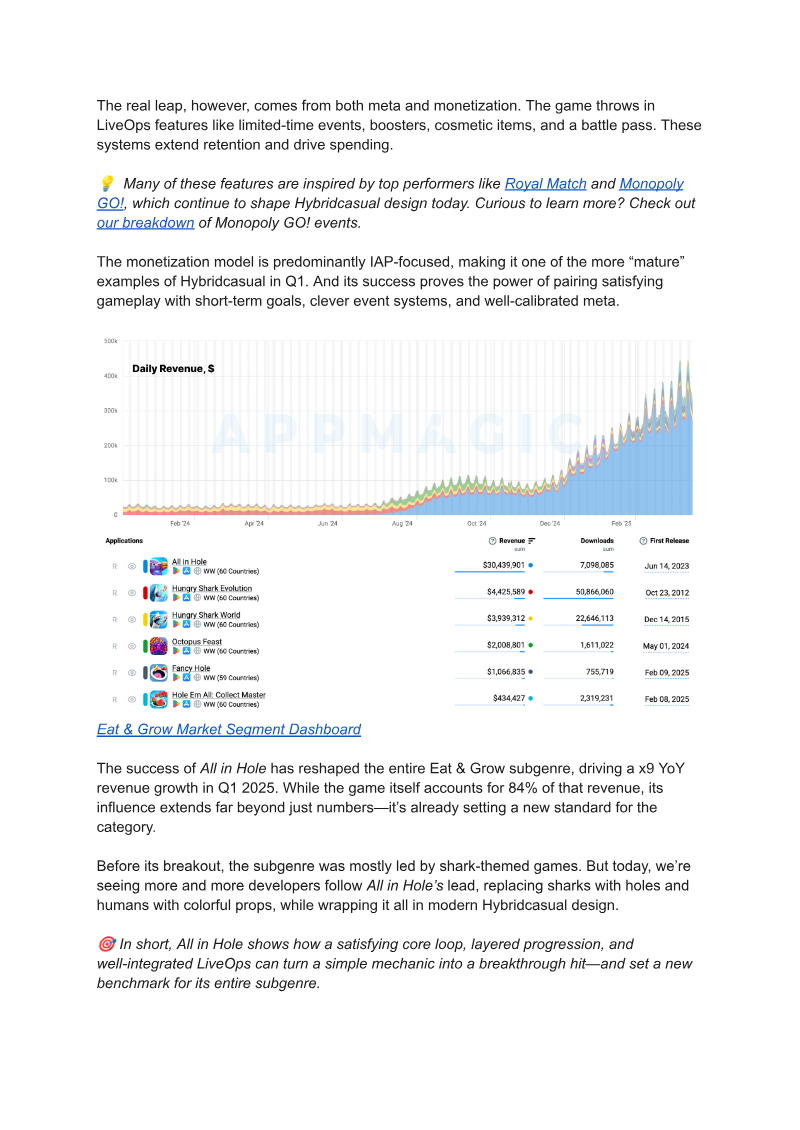
The analysis highlights a rapid maturation of the hybrid‑casual segment in the mobile gaming market, showing that the top ten titles generated $87 million in net in‑app‑purchase (IAP) revenue in the first quarter of 2025—a 67 percent year‑over‑year increase from the same period in 2024. Puzzle games dominate the revenue mix, contributing 48 percent, while arcade titles account for 45 percent; together they represent more than 90 percent of total earnings. Within puzzles, block‑puzzle titles lead with 71 percent of puzzle revenue, followed by screw‑puzzle (20 percent) and sort‑puzzle (9 percent), the latter posting a 5.6‑times YoY growth. The report covers a global scope of 60 countries, focusing on the period from Q1 2023 through Q1 2025 and concentrating on the hybrid‑casual niche that blends hyper‑casual mechanics with deeper casual‑style monetisation and live‑ops. Methodologically, the study isolates hybrid‑casual games by filtering the hyper‑casual tag for top‑grossing apps, then examines revenue, download, and release data for each title. Key case studies include Color Block Jam, which achieved $25 million in Q1 2025 after a modest Q4 2024 start, All in Hole, whose eat‑and‑grow model drove a nine‑fold YoY revenue surge and now accounts for 84 percent of its sub‑genre’s earnings, Mob Control, which posted 27 percent revenue growth and introduced “skip tickets” to balance ad and IAP streams, and Screwdom, whose shift to 3D puzzle design generated $3.6 million and set a new benchmark for screw‑puzzle games. The findings suggest that successful hybrid‑casual titles combine a highly clickable core loop with layered progression, strategic live‑ops, and nuanced monetisation—often leveraging high‑budget user‑acquisition campaigns and viral social media exposure. This convergence of design and marketing is reshaping sub‑genres, lowering acquisition costs, and establishing hybrid‑casual as a dominant, profit‑rich trend in the mobile gaming ecosystem.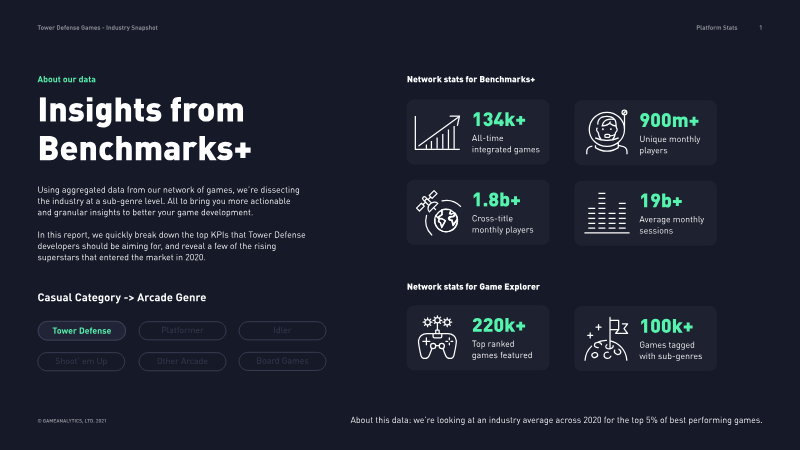
GameAnalytics · 2025
ReportTower Defense Games - Industry Snapshot
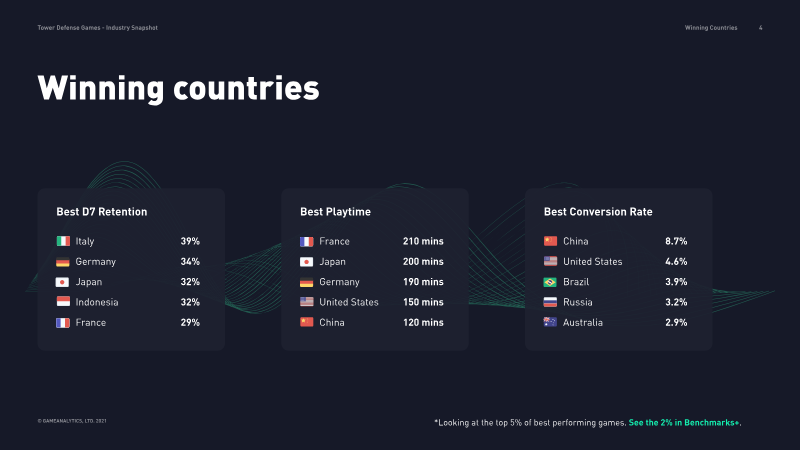
Tower Defense games represent a high-performing sub-genre within the casual arcade category, characterized by exceptional monetization and engagement depth. Analysis of 2020 industry data reveals that the top 5% of Tower Defense titles significantly outperform related sub-genres like Idlers, Platformers, and Board Games in financial efficiency. Specifically, these top-tier games achieve a conversion rate of 3.83%, more than double that of their closest competitors, and maintain an Average Revenue Per Daily Active User (ARPDAU) of $1.66. This financial strength is further evidenced by an Average Revenue Per Paying User (ARPPU) of $83, suggesting a highly committed and spending-prone player base. Engagement metrics for the genre are equally robust, with top-performing titles commanding an average daily playtime of 130 minutes. While Day 1 retention sits at 40%, slightly lower than some competing sub-genres, Day 7 retention remains competitive at 15%. Geographic performance varies by metric; Italy leads in Day 7 retention at 39%, while France sees the highest daily playtime at 210 minutes. China stands out as the most lucrative market for conversion, reaching a rate of 8.7%. The success of the genre is attributed to its accessible core mechanics, high replayability, and the ease with which developers can integrate meta-features such as PvP modes, daily challenges, and RPG elements. These features allow for significant meta-game shifts with minimal content overhead. Notable titles entering the market in 2020, such as Rush Royale and Towerlands, exemplify the trend of blending traditional defense mechanics with strategy and role-playing elements to drive long-term player investment. This data is derived from a network of over 134,000 integrated games and 1.8 billion monthly cross-title players.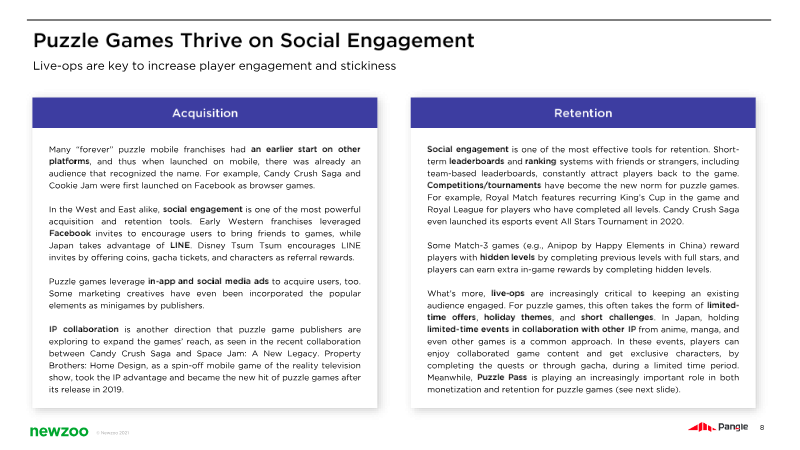
Newzoo · 2025
ReportNewzoo Puzzle Games Report: Mobile Game Genre Insights
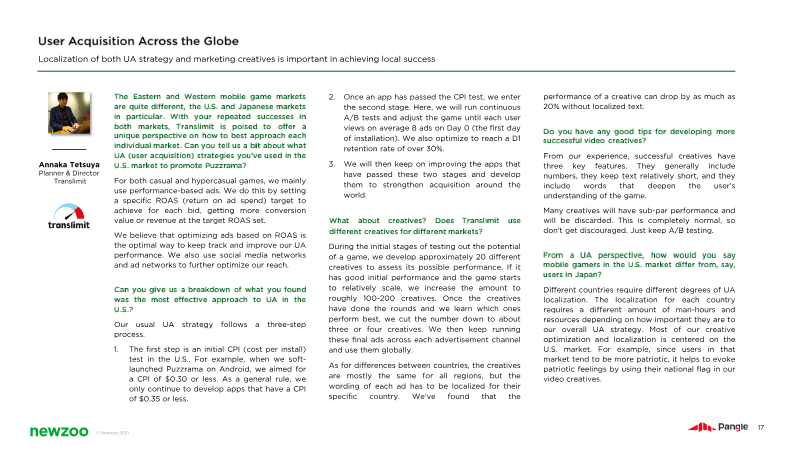
Produced through a partnership between Newzoo and Pangle, this analysis examines the global mobile puzzle game market with a specific focus on the divergent trends between Western and Eastern territories. The study covers major markets including the United States, China, Japan, and South Korea, utilizing 2020 revenue data and 2021 consumer insights. By comparing market dynamics, monetization strategies, and player demographics, the research aims to provide actionable intelligence for developers seeking global expansion. Findings indicate that the United States is the world’s largest mobile puzzle market, followed by Japan and China. While classic match-3 mechanics remain dominant globally, the genre is evolving through "meta" elements like narrative and decoration. A significant regional distinction exists in monetization: Western titles rely heavily on in-app advertising (IAA) and simple economies, whereas Eastern titles—particularly in Japan—integrate deep character collection, progression, and gacha mechanics, leading to higher in-app purchase (IAP) revenue. Data shows that while Western players demonstrate a higher tolerance for frequent ad breaks, Japanese players prefer longer sessions with fewer interruptions but show a greater willingness to pay for additional functions and aesthetic enhancements. Demographically, puzzle gamers across all regions skew female and are typically full-time employees with mid-to-high income. However, Eastern players tend to be younger and more highly educated than their Western counterparts. The methodology relies on Newzoo’s proprietary Global Games Market Report and Consumer Insights, supplemented by a case study from Japanese developer Translimit. The analysis concludes that success in the puzzle genre requires localized user acquisition strategies, such as performance-based A/B testing and region-specific ad creative optimization, to navigate the distinct cultural expectations of the global mobile audience.
Newzoo · 2025
ReportNewzoo Hypercasual Mobile Game Genre Report: Eastern vs Western Markets
Hypercasual mobile games represent a significant and evolving segment of the global gaming industry, accounting for 36 of the top 100 downloaded mobile games in 2021. While the genre is characterized by simple mechanics and high accessibility, it has faced increasing competition, leading to a shift toward hybrid-casual models. These newer titles incorporate meta-features and live operations to improve player retention, which typically falls below 10% by the seventh day for standard hypercasual titles. The market demonstrates distinct regional variations, with hypercasual games enjoying significantly higher popularity in Western markets like the United States and United Kingdom compared to Japan and South Korea. In 2021, runner and racing subgenres overtook simulation and puzzle titles as the most downloaded categories. Demographically, hypercasual players across key markets skew male, are often full-time employees with mid-to-high incomes, and are younger than the average mobile gamer. Monetization remains primarily driven by in-game advertising, with interstitial video identified as the most adopted format, followed by rewarded videos and banner ads. However, hybrid monetization is rising, with developers increasingly offering in-app purchases for ad removal or exclusive content. Data from 2021 indicates that the hypercasual sector is highly dynamic; only eight of the top 36 hypercasual titles from 2020 remained in the top rankings the following year. To maintain growth, publishers are leveraging broad targeting strategies that are less affected by privacy changes like IDFA and are utilizing sophisticated retention optimization tools to acquire loyal users.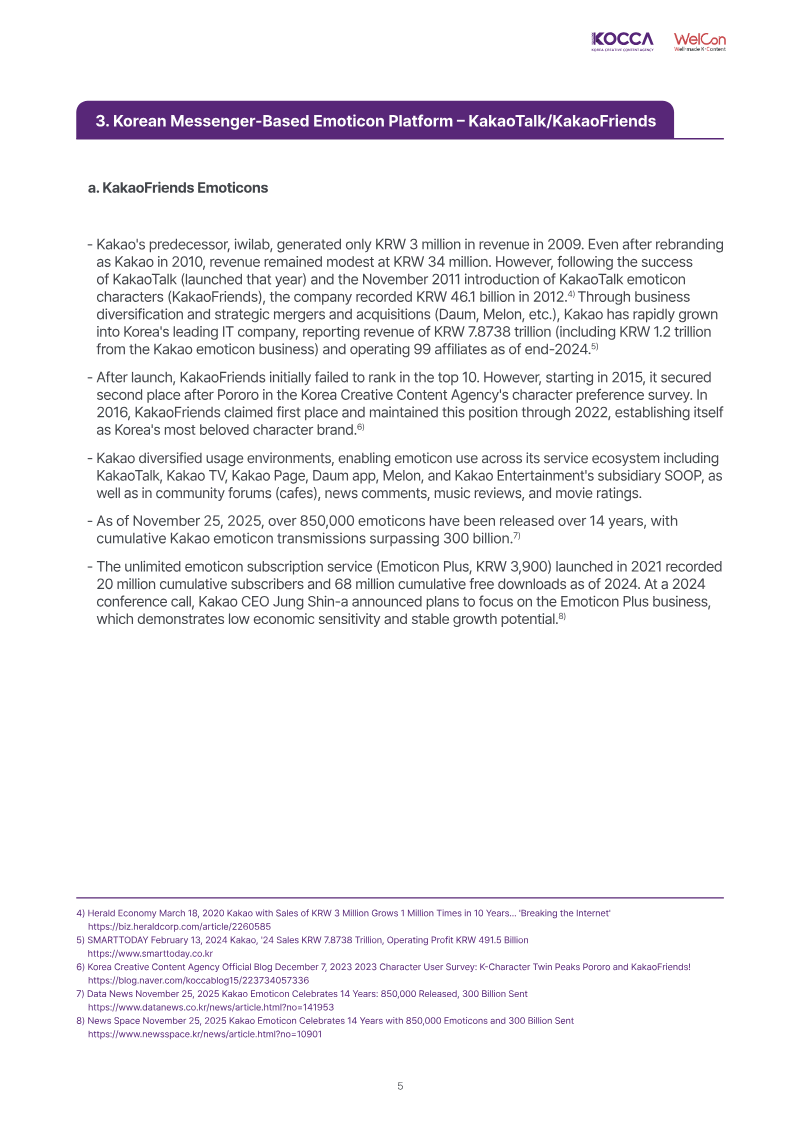
KOCCA – Korea Creative Content Agency · 2025
ReportGrowth of the Korean Emoticon Market: A New Distribution and Expansion Method for the K-Character Industry
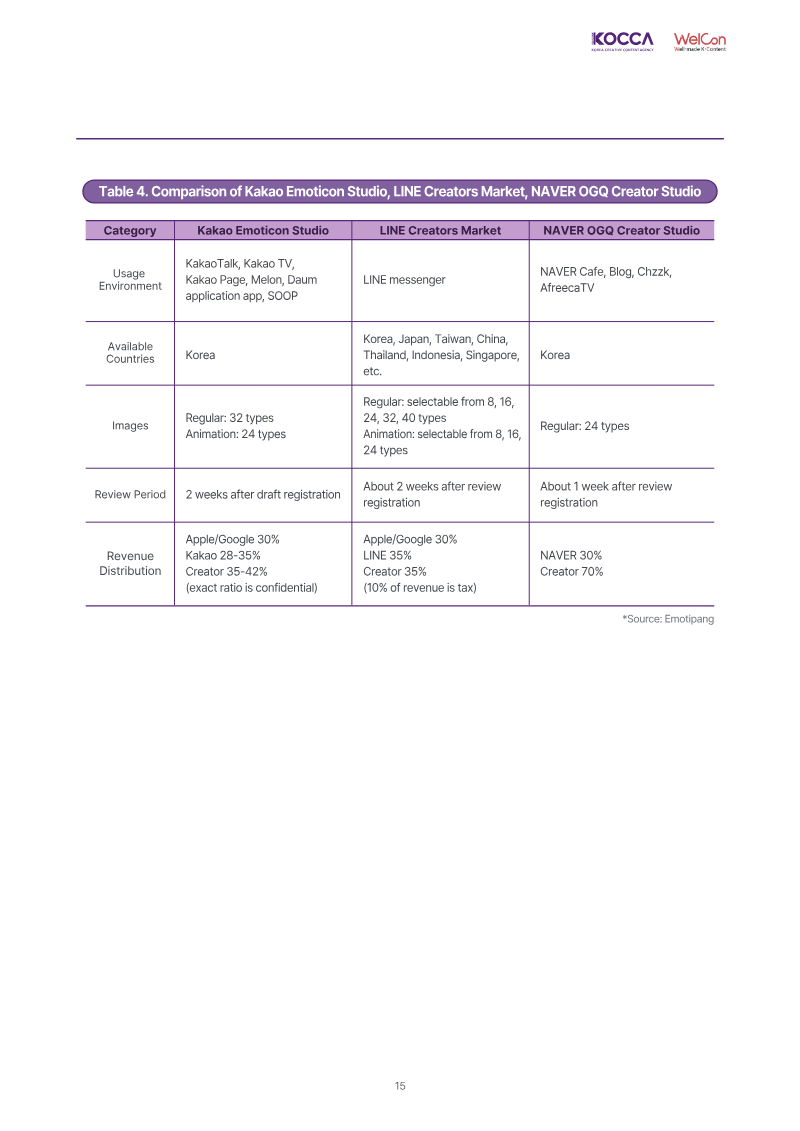
The Korean emoticon market has evolved from a peripheral messaging feature into a multi‑billion‑won character‑IP industry, now valued at roughly KRW 1.5 trillion (≈US$1.2 trillion). This transformation is anchored by KakaoTalk, whose emoticon platform expanded from an initial KRW 100 billion base in the early 2010s to a dominant revenue stream that underpins a broader ecosystem of licensed characters and digital content. Over the past fourteen years, more than 850 000 distinct emoticons have been released, generating in excess of 300 billion individual sends, illustrating both high user engagement and the low‑sensitivity nature of the market’s cash flow. The core of this growth lies in the development of unique intellectual‑property (IP) assets such as KakaoFriends and LINE Friends. These brands have transcended simple sticker usage to become central brand assets that are licensed across a spectrum of media, including merchandise, mobile games, animation, and information‑communication‑technology services. By converting emoticons into high‑value IP, companies have created diversified revenue channels that extend well beyond the messaging platform itself. Export potential is accelerating, driven by corporate collaborations and strategic international expansion. Partnerships with established IP owners enable Korean firms to tap into global distribution networks, while the modular nature of emoticon‑based branding facilitates rapid adaptation to foreign markets. The overall trajectory suggests that the emoticon sector will continue to serve as a catalyst for the broader K‑character industry, reinforcing Korea’s position as a leading exporter of digital cultural content.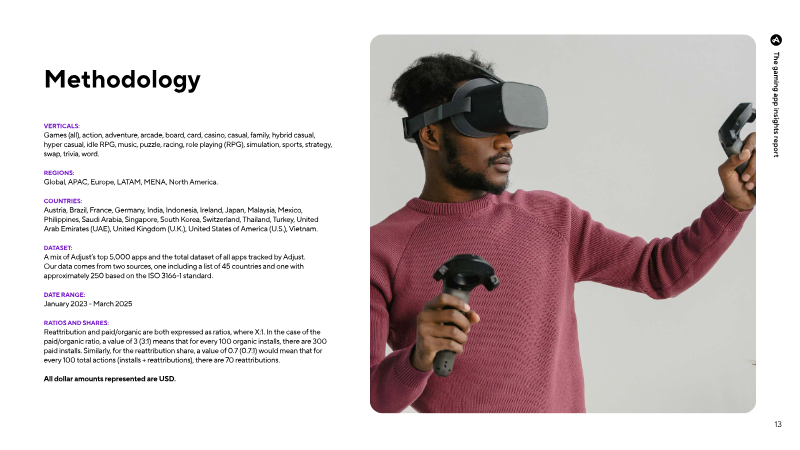
Adjust · 2025
ReportGaming App Insights Report: 2025 Edition
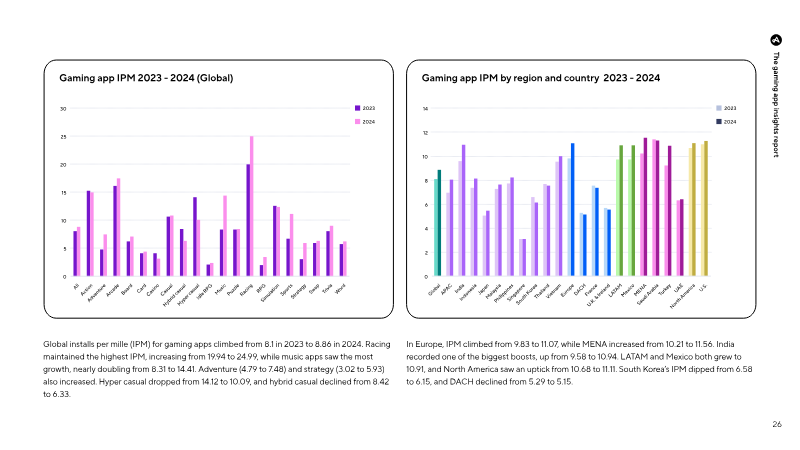
The analysis tracks the state of the global mobile‑gaming market through 2024 and projects its trajectory toward 2025, emphasizing how emerging AI‑driven personalization will shape growth. It establishes that the sector is recovering from the volatility of 2023, with worldwide app installs climbing 4 % year‑over‑year in 2024, even as average session length contracted. Core user engagement metrics, however, show modest decline: day‑1 retention fell from 28 % to 27 % and median revenue per active user dropped from $0.31 to $0.28, indicating pressure on traditional monetization models. In contrast, advertising efficiency improved, reflected in higher installs per mille (IPM) and stronger ad‑performance indicators across major markets. The report’s geographic scope is global, encompassing all major mobile‑gaming regions, and its temporal frame spans the 2023‑2025 period. It integrates data from app stores, ad networks, and cross‑platform measurement tools to deliver a comprehensive view of user acquisition, retention, and revenue trends. The central thesis posits that the next wave of growth will be powered by AI‑enabled, culturally tailored experiences that adapt difficulty, blend monetization formats, and deploy live events to boost lifetime value. Developers and marketers who adopt a metrics‑focused, AI‑augmented approach—identifying pivotal in‑game moments and steering users toward optimal pathways—are projected to achieve the most scalable expansion. Cross‑platform analytics suites are highlighted as essential for delivering the visibility required to implement these strategies effectively.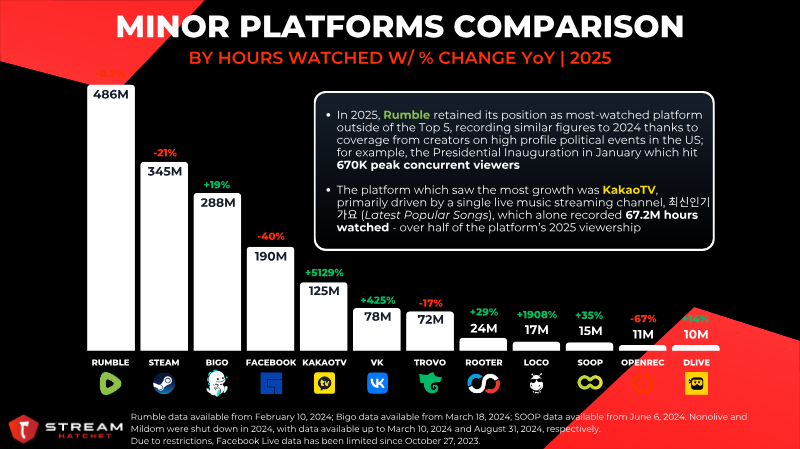
Stream Hatchet · 2025
ReportYearly Live Streaming Trends Report 2024
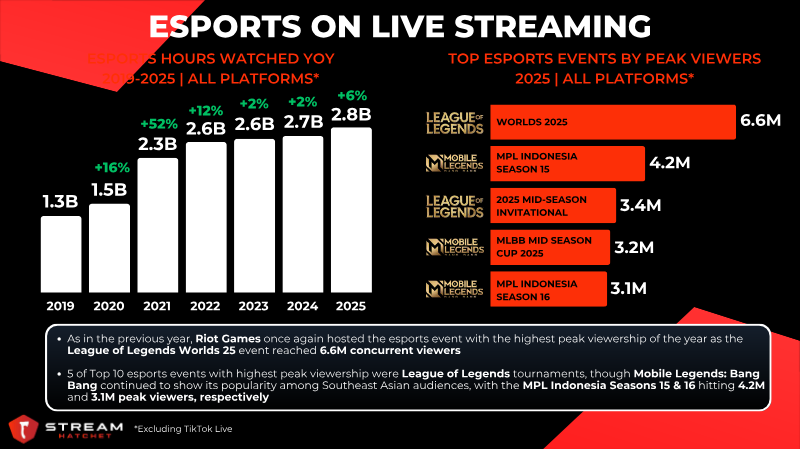
The live streaming industry experienced a period of stabilization and strategic maturation throughout 2024, characterized by a modest 3% year-over-year increase in total hours watched across major platforms. This growth brought the global annual viewership to approximately 35 billion hours, signaling a shift from the volatile surges of previous years toward a more sustainable, long-term trajectory. While Twitch maintained its position as the market leader in terms of total hours watched, its market share faced increasing pressure from YouTube Gaming and Kick, the latter of which saw a 45% increase in viewership as it successfully attracted high-profile creators through non-exclusive contracts and aggressive revenue-sharing models. Geographically, the Asia-Pacific region remains the primary engine for mobile streaming growth, while North American and European markets show a deepening preference for high-production "eventized" content. Non-gaming content, specifically the Just Chatting category, continues to dominate the landscape, accounting for nearly 15% of all platform activity. However, the competitive gaming sector saw a resurgence driven by the massive success of tactical shooters and the expansion of co-streaming rights for major esports tournaments. These community-driven broadcasts often outperformed official channels, representing a fundamental shift in how audiences consume professional competitive play. The integration of artificial intelligence and enhanced monetization tools defined the technological landscape of the year. Creators increasingly utilized AI-driven moderation and clip-generation tools to maximize reach across short-form video platforms like TikTok and Instagram Reels, which now serve as the primary discovery funnel for live broadcasts. Brands have responded by shifting budgets toward long-term creator partnerships rather than one-off sponsorships, seeking to capitalize on the high engagement rates of mid-tier streamers who boast more dedicated, niche communities. As the industry moves into 2025, the convergence of live commerce and interactive broadcasting is expected to become the next major frontier for platform revenue.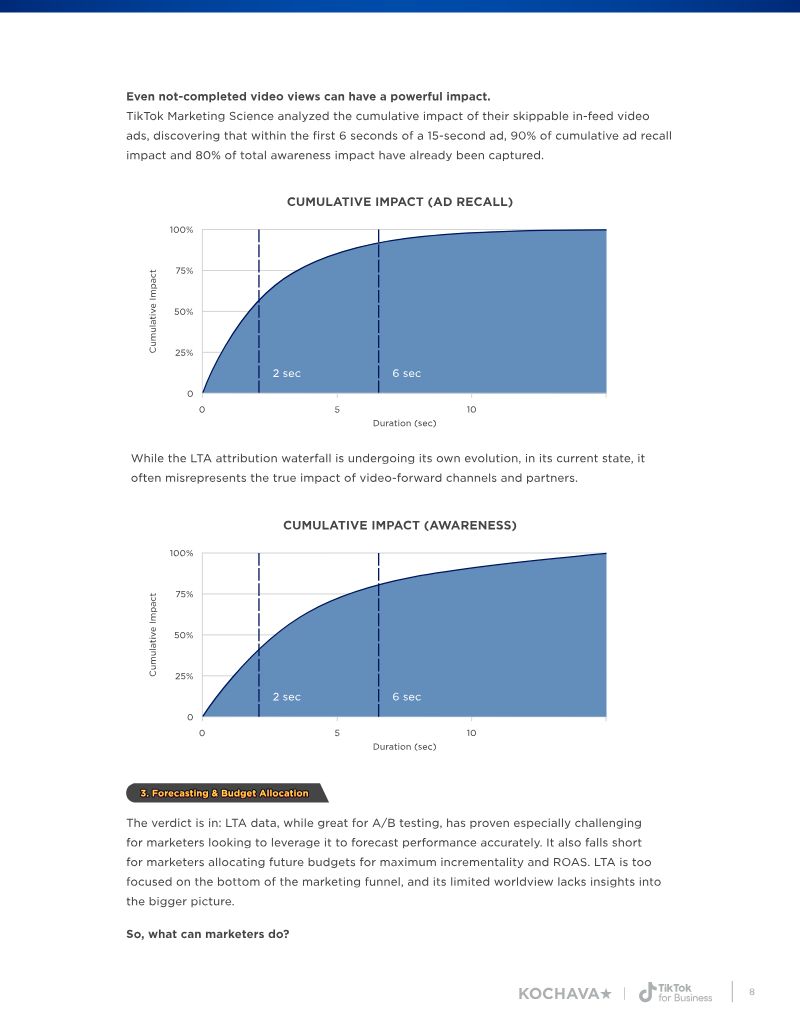
Kochava & TikTok for Business · 2025
ReportThe Power of Marketing Mix Modeling
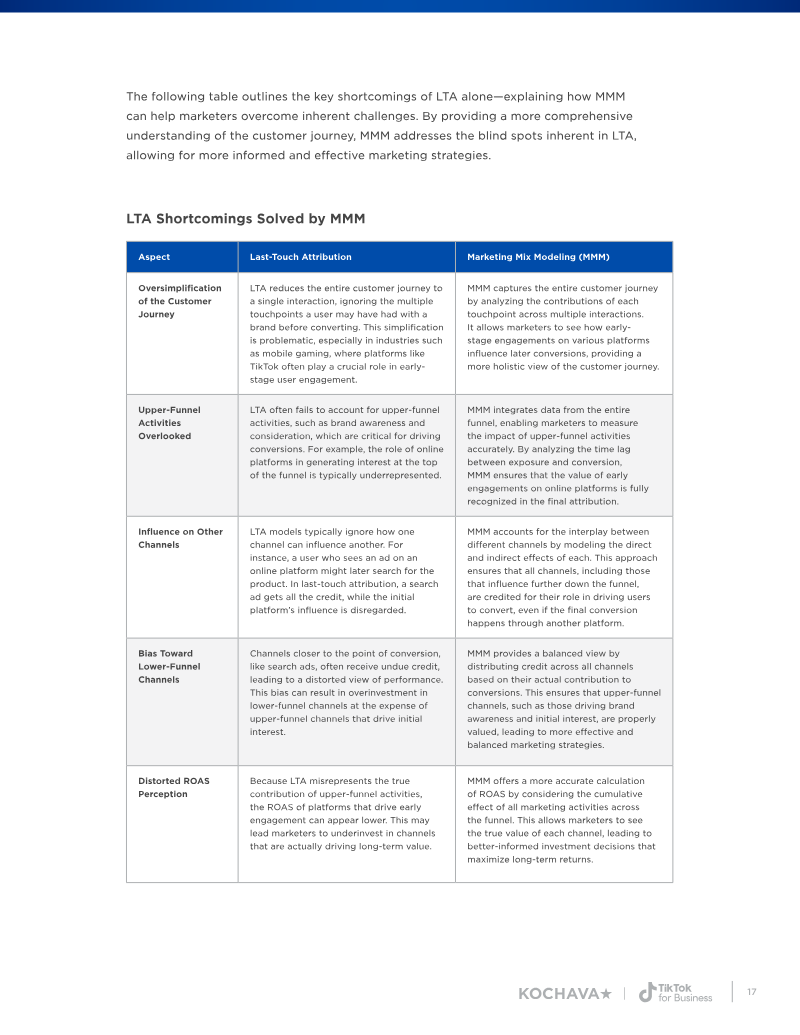
This analysis explores the transition from traditional last-touch attribution (LTA) to next-generation marketing mix modeling (MMM) within the mobile gaming industry. It posits that while LTA has long been the standard for measuring return on ad spend (ROAS), it is increasingly inadequate due to systemic signal loss from privacy regulations (such as Apple’s AppTrackingTransparency), the rise of multi-platform gaming, and a heavy bias toward bottom-of-funnel channels that ignores the incremental value of top-of-funnel platforms like TikTok. The findings highlight a significant shift in the global gaming landscape, noting that the industry is projected to reach three billion players by 2029. Despite this growth, marketers face rising user acquisition costs, which are forecast to exceed $130 billion by 2025. Data from Kochava and TikTok indicates that LTA frequently under-attributes early-stage revenue events. For example, a case study shows that at a $5,000 daily spend, an MMM model attributed 43% more Day 7 revenue events to TikTok than a traditional LTA model, revealing that LTA often fails to capture the full impact of video-forward media. The scope of this research is global, with specific emphasis on the North American and Asia-Pacific markets, which accounted for $50 billion and $84 billion in 2023 revenue, respectively. The methodology involves comparing aggregated market-level data against granular user-level data to demonstrate how MMM identifies channel saturation and incrementality without relying on depreciating user identifiers. The conclusion advocates for a dual-wielding strategy where studios utilize both LTA for tactical, real-time creative optimization and next-gen MMM for strategic budget allocation and forecasting. Organizations spending over $160,000 monthly per region with a diverse mix of at least five media partners are identified as the primary beneficiaries of this advanced attribution framework.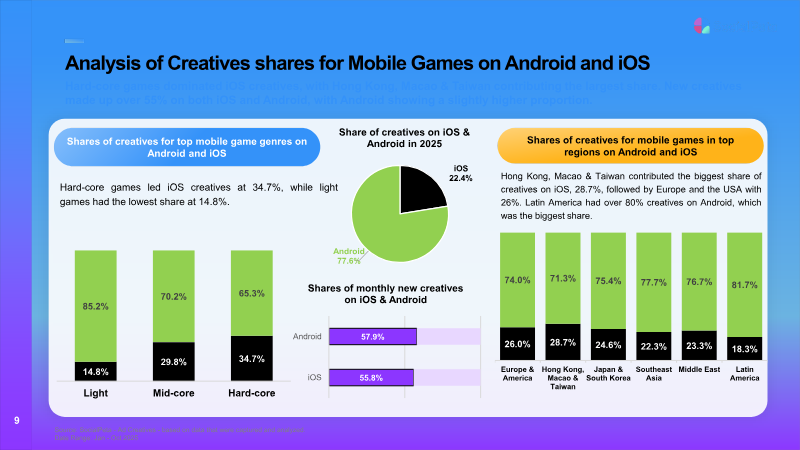
SocialPeta & Reforged Labs · 2025
Report2025 Global Mobile Game Marketing Insights & Creative Breakdown
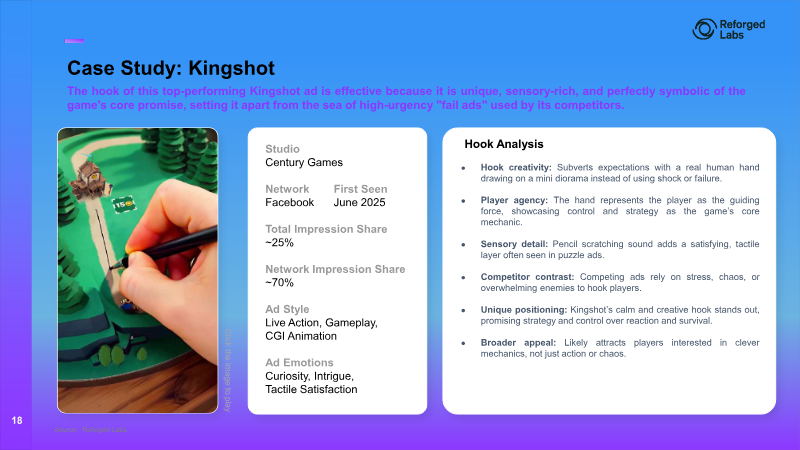
The 2025 Global Mobile Game Marketing Insights & Creative Breakdown provides a comprehensive analysis of the mobile advertising landscape, focusing on the evolution of ad creatives across more than 80 countries and 80 ad channels. Utilizing data from SocialPeta and Reforged Labs, the findings cover over 1.6 billion creatives and 10,000 tracked mobile games between January 2024 and October 2025. The primary thesis suggests that the mobile market is experiencing a significant surge in creative volume and a rapid shift toward AI-driven production to combat creative fatigue and rising competition. Key data points indicate that the average monthly creatives per advertiser rose to 123 in 2025, a nearly 20% year-over-year increase. New creatives now account for 58% of total monthly ads, peaking at over 60% in October. Geographically, North America and the Hong Kong, Macao, and Taiwan regions lead in total creative volume, while Europe maintains the highest refresh rate for new content. From a genre perspective, Strategy Games (SLGs) dominate advertising intensity with 325 monthly creatives per advertiser, while Casino games lead in creative turnover, with new assets making up 65.6% of their monthly output. The analysis highlights a clear platform divide, with Android hosting 77.6% of total creatives compared to 22.4% on iOS. Hard-core games represent the largest share of iOS creatives at 34.7%, whereas light games are more prevalent on Android. Video remains the dominant format, particularly for Puzzle games, where it accounts for 83.5% of ads. Furthermore, the industry has reached a tipping point in automation, with over 90% of advertisers now utilizing AI to generate scenes, characters, or scripts. Case studies of top performers like Royal Match and Monopoly GO! emphasize that successful marketing currently relies on "hook" innovation—such as diegetic sound, tactile satisfaction, and subverting brand expectations—to maintain high return on ad spend in an oversaturated market.
Sensor Tower · 2025
ReportMobile Game Market Insights: India 2025
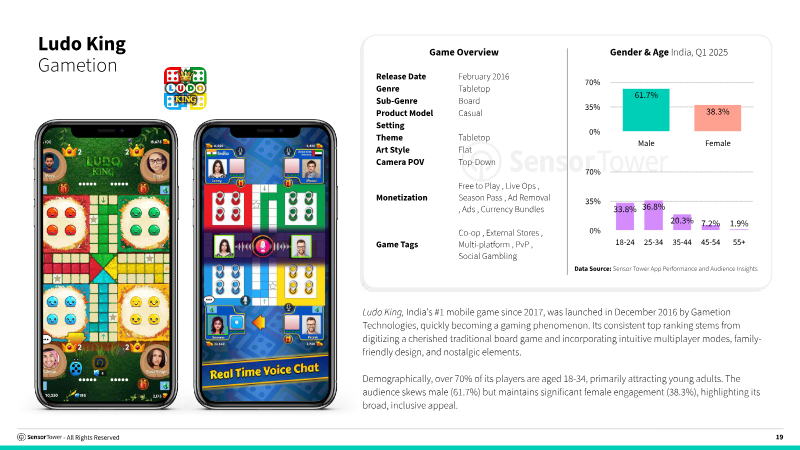
India is the world’s largest mobile gaming market by volume, reaching 8.45 billion downloads in the 2024-25 fiscal year. Despite this massive scale, which is more than double that of Indonesia, the market faces significant monetization hurdles. Total in-app purchase revenue stands at approximately $400 million, reflecting a cost-sensitive consumer base that favors free-to-play models. However, the market shows signs of evolution, with revenue growing 8.5% year-over-year, driven largely by high-value spenders on iOS and the increasing adoption of digital payment systems like UPI. The player base is predominantly young and male, with 77% of gamers aged 18-34 and 86% identifying as male. While casual subgenres such as driving simulators, platformers, and tabletop games dominate download charts due to their cultural resonance, revenue is concentrated in core competitive genres. Shooters, specifically Battle Royale titles like Garena Free Fire and Battlegrounds Mobile India, command 50% of total market revenue. Strategy and Casino games also represent significant portions of the spending landscape, highlighting a divide between mass-market reach and deep-engagement monetization. A central fixture of the domestic industry is Ludo King, which has remained the most downloaded game in India since 2017, surpassing 1.25 billion lifetime downloads. Its success is attributed to the digitization of a traditional board game combined with social features like live voice chat. While domestic publishers like Gametion and Dream11 maintain strong local positions, there is a growing trend of India-based firms expanding into overseas markets, such as the United States and Saudi Arabia, to capture higher per-user revenue. The findings are based on Sensor Tower’s App Performance and Audience Insights data for the period of April 2024 through March 2025. The methodology utilizes estimates from the App Store and Google Play, excluding ad revenue, third-party Android stores, and pre-installs. The scope focuses on the Indian mobile ecosystem while providing comparative context against other major Asian markets.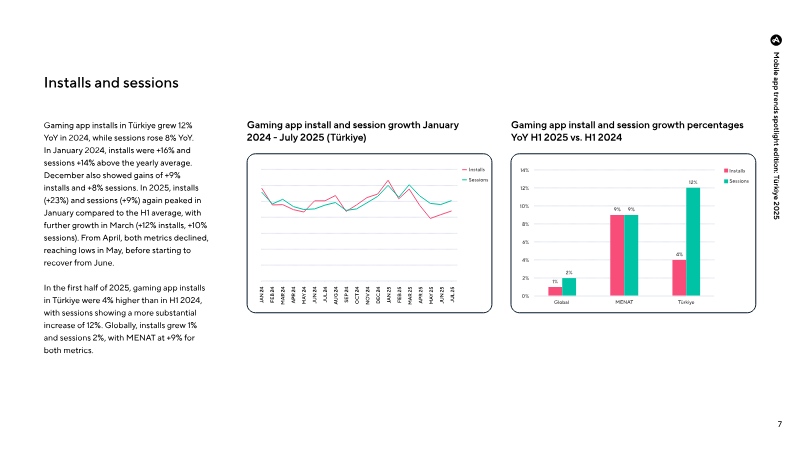
Adjust · 2025
ReportMobile App Trends Spotlight Edition: Türkiye 2025
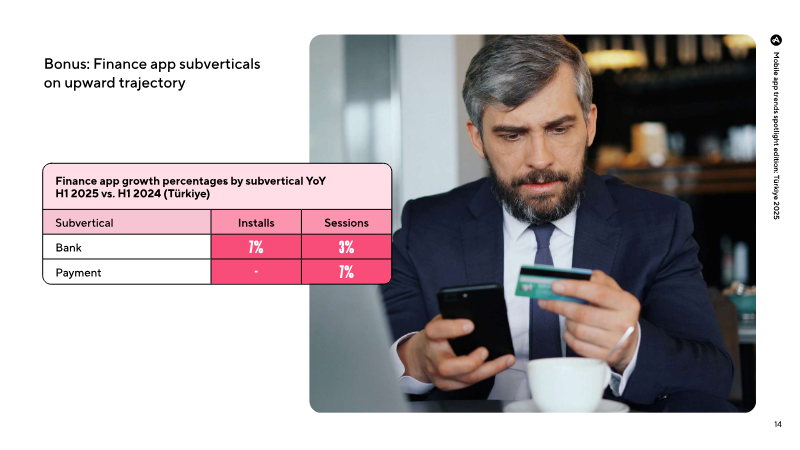
The mobile application economy in Türkiye is entering a high-growth, maturing phase, with total revenue projected to reach $1.65 billion by 2029. Ranking eighth globally for both total downloads and time spent in-app, the market is driven by a young, tech-oriented population and an 87% internet penetration rate. Analysis of data from January 2023 through July 2025 reveals that while the market is scaling globally, it maintains unique local characteristics across the gaming, finance, and e-commerce verticals. The gaming sector remains a primary driver, with installs growing 12% year-over-year in 2024. Hyper-casual games dominate install shares at 28.6%, yet music and action genres command the highest session engagement. Notably, Turkish users spend an average of 32.8 minutes per gaming session, surpassing both regional and global averages. However, retention rates in Türkiye tend to be lower than global benchmarks, with only 19% of users returning the day after installation compared to 26% globally. The finance and e-commerce sectors show similar trends of high engagement and rapid adoption of new technologies. Finance app installs surged 30% in the first half of 2025, supported by a high mobile banking adoption rate of 85%. In e-commerce, local developers maintain a strong foothold, creating 80% of the top shopping apps. While session lengths in these categories are gradually declining—potentially indicating more efficient user paths to purchase—retention rates for finance and shopping apps in Türkiye consistently outperform global medians. A significant emerging trend is the rapid rise of generative AI applications, which saw a 142.5% increase in downloads between 2023 and 2024. This growth is fueled by a strategic pivot of local hyper-casual game studios toward AI-first apps and the development of proprietary Turkish-language models. These findings suggest that Türkiye is transitioning from a regional player to a global powerhouse, characterized by a highly engaged user base and a robust ecosystem of domestic developers.
Appodeal · 2025
Report