Mobile Games
The mobile market by genre, from hypercasual and puzzle to midcore and idle.
403 documents
data.ai · 2023
ReportGaming Spotlight 2023: The Year in Review
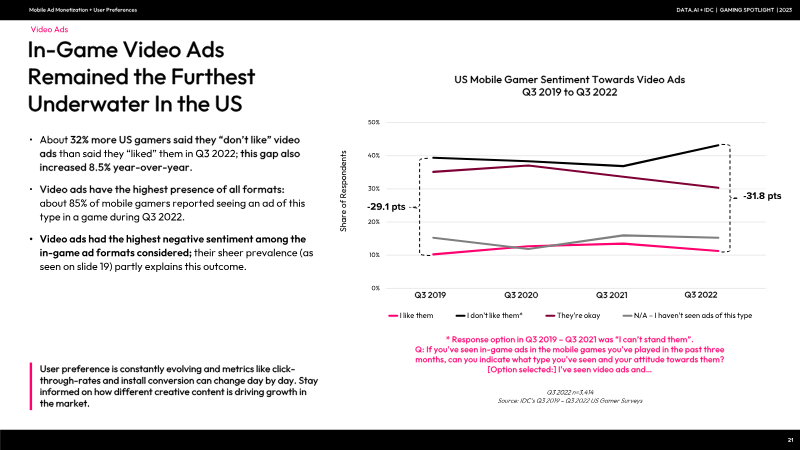
The 2023 Gaming Spotlight provides a comprehensive analysis of the global gaming landscape, focusing on market shifts across mobile, PC, and console platforms during the first half of 2023. Utilizing data from data.ai and IDC, the analysis highlights that while mobile remains the largest market opportunity, it faces a projected 2% year-over-year decline in consumer spend to $108 billion. This softening is attributed to macroeconomic instability, privacy regulations like Apple’s App Tracking Transparency (ATT), and stricter regulations on adolescent gaming in China. In contrast, home console and PC/Mac spending are expected to rise by 3% and 4% respectively, driven by increased hardware availability and subscription-based revenue. Geographically, the Asia-Pacific region remains a primary revenue driver, with South Korea showing significant market share gains. The report identifies a shift in handheld gaming; while the Nintendo Switch Lite faces declining interest, newer devices like the Steam Deck are gaining traction, albeit with distinct demographic profiles. Mobile gaming success in H1 2023 was defined by titles like Monopoly GO and Honkai: Star Rail, which leveraged strong intellectual property and sophisticated monetization strategies, such as high-value in-app purchases and social engagement features. A significant portion of the analysis examines user acquisition and monetization challenges. Findings indicate that US gamer sentiment toward in-game advertising is deteriorating, with negative sentiment toward banner and video ads rising significantly. Rewarded video remains the most tolerated format due to its clear value exchange, though even its popularity has dipped. The report concludes that as acquisition costs rise and tracking becomes more difficult, publishers must optimize creative strategies—particularly through playable ads for action genres—and diversify monetization models beyond traditional ads to include subscriptions and battle passes to maintain growth in an increasingly competitive and privacy-conscious environment.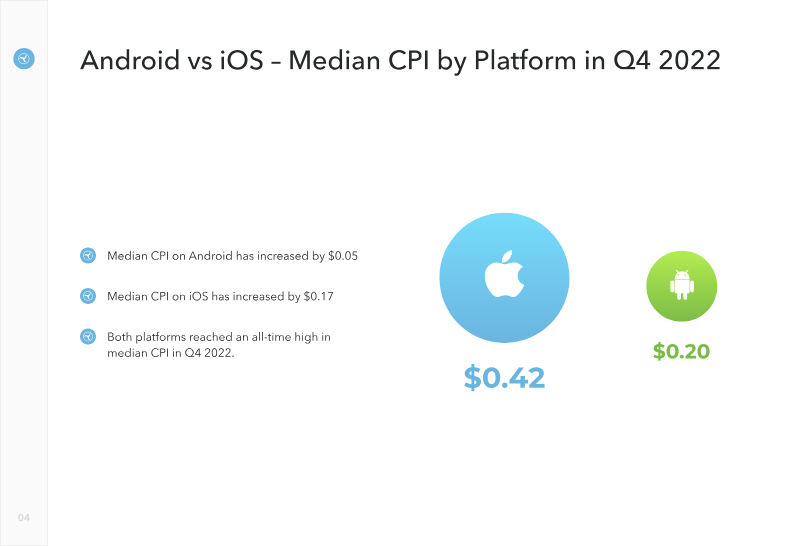
Tenjin · 2022
ReportHyper-Casual Games Benchmark Report: Q4 2022
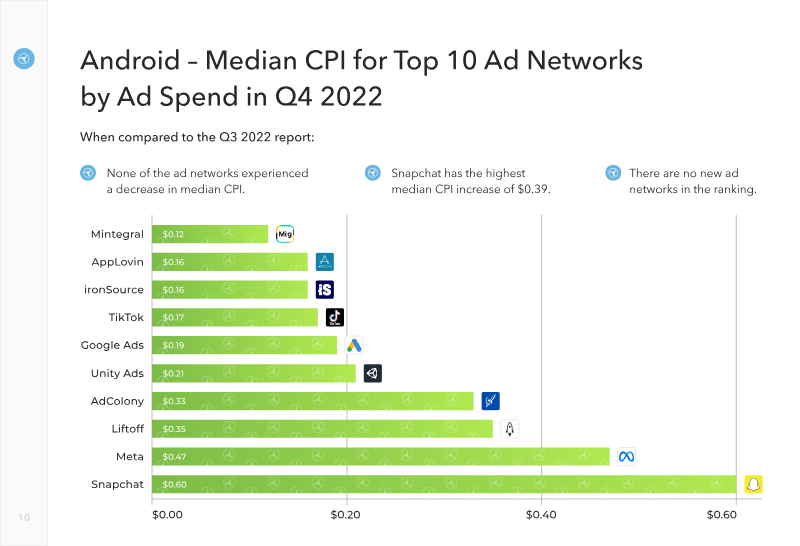
The benchmark focuses on hyper-casual mobile games during the fourth quarter of 2022, comparing performance metrics across iOS and Android and highlighting shifts from the previous quarter. Data are drawn from GameAnalytics, which tracks more than 100 000 titles and reaches roughly one-third of the global mobile player base, providing a broad, cross-regional view of the segment. Cost-per-install (CPI) reached an all-time high of $0.20 median on both platforms, with the overall median CPI rising to $0.42. Android’s median CPI grew by $0.05 while iOS saw a larger increase of $0.17. Among the top ten ad-spending countries, the United States posted the highest iOS median CPI at $0.80, overtaking France and Germany, while Brazil dropped out of the ranking. South Korea and Canada recorded the steepest CPI hikes on Android, each climbing $0.06 from Q3 2022. The report covers major markets in North America, Europe, Asia-Pacific and Latin America, reflecting a worldwide scope. Retention benchmarks reveal a consistent advantage for iOS. In the top-2% of games, Day 1 retention was 45% on iOS versus 38% on Android, and Day 7 retention stood at 19% versus 14%. For the top-25% tier, Day 1 rates were 33% (iOS) and 28% (Android), with Day 7 at 10% and 6% respectively. Across all titles, median Day 1 retention was 24% on iOS and 23% on Android, while median Day 7 retention was 7% versus 4%. The gap between elite, good and average games is pronounced, underscoring the importance of early-stage player engagement. Overall, Q4 2022 saw rising acquisition costs and modest but platform-dependent retention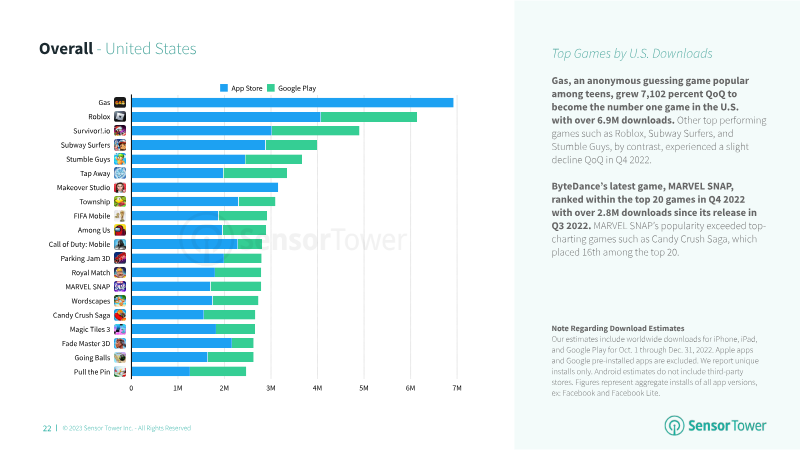
Sensor Tower · 2022
ReportStore Intelligence Data Digest: Q4 2022
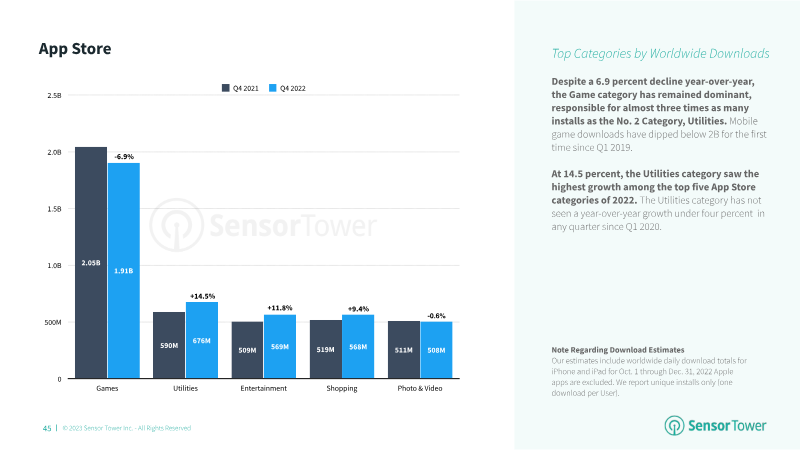
The fourth quarter of 2022 delivered a nuanced portrait of the mobile-app ecosystem, tracking download activity across the world’s two dominant storefronts and highlighting shifts in consumer preference. Global install volume slipped marginally to 35.5 billion, a 0.1% decline, while the Apple App Store posted a 2.4% rise to 8.1 billion downloads and Google Play contracted 0.9% to 27.5 billion. Instagram reclaimed the top-ranked position worldwide, and Meta’s portfolio occupied half of the top-ten list, underscoring the company’s entrenched influence. TikTok, CapCut and the newly launched game Stumble Guys emerged as the fastest-growing titles, signaling continued appetite for short-form video and casual gaming. In the Asian market, video-centric applications remained dominant. TikTok delivered roughly 29 million installs despite a 19% quarter-over-quarter dip, while Instagram led Google Play with more than 116 million downloads, driven largely by India’s sizable user base. The FIFA World Cup spurred a surge in football-related games, with FIFA Mobile and Soccer Super Star posting 136% and 112% QoQ growth respectively. New releases such as Gas (7,102% QoQ in the United States), Makeover Studio (2,035% QoQ) and MARVEL SNAP broke into the top-20, and Ludo King amassed over 36 million Asian downloads. Meta and Google continued to dominate the download landscape, with Meta recapturing the No. 1 slot on Google Play. Regional spikes, notably Stumble Guys’ peak performance in Indonesia, illustrate how localized trends can amplify global patterns. Overall, the quarter reflects a stable yet evolving market where established platforms retain supremacy while emerging titles and event-driven spikes reshape the
DeNA Co. · 2022
ReportDeNA Integrated Report 2022
DeNA is undergoing a strategic evolution to diversify its portfolio into two primary pillars: "Entertain," comprising Games and Live Streaming, and "Serve," focusing on Healthcare and Sports. This transition is supported by core competencies in artificial intelligence, agile in-house development, and a regional "Home Base" strategy centered in Yokohama. By leveraging high-potential technologies such as Web3 and health big data, the organization aims to balance stable cash flow from established entertainment properties with high-growth opportunities in medical data and global streaming markets. Financial performance in fiscal year 2021 reflects this transition, with profit attributable to owners reaching 30.5 billion yen and a return on equity of 13.2%. While the Game Business experienced a revenue decline to 74.7 billion yen due to a lack of new hits, the Live Streaming segment saw a 1.4x revenue increase, and the Healthcare segment achieved its first quarterly profit. Strategic capital moves, including the sale of approximately half of the company's Nintendo shareholdings and the acquisition of subsidiaries like IRIAM and DATA HORIZON, have been implemented to increase asset efficiency and expand the medical database to over 15 million insured individuals. Operational and governance structures have been modernized to support this multi-sector growth. The January 2022 establishment of a cross-departmental Product Development Department and a new Group Executive System aims to accelerate business execution and talent cultivation. Personnel strategies now emphasize specialized technical rankings to attract top-tier engineers, while executive compensation is increasingly linked to mid-to-long-term growth indicators. Looking ahead, the strategy focuses on releasing three to five global game titles annually, expanding the Pococha streaming service into the United States and India, and deepening the long-term strategic partnership with Nintendo to secure a robust global presence.
SocialPeta · 2022
ReportMobile Game Marketing: Insights & Trends of Popular Game Genres Q3 2022
The analysis examines mobile-game marketing dynamics during the third quarter of 2022, concentrating on the performance of leading genres and the geographic distribution of traffic and revenue. By comparing download activity, user engagement, and monetisation across regions, it identifies where growth opportunities are emerging and which markets continue to dominate the ecosystem. Casual games recorded only modest increases in downloads, adding roughly five million installs versus the previous quarter and less than one percent year-on-year growth. Despite the limited acquisition surge, daily-active-user and monthly-active-user ratios remained stable, while revenue climbed seven percent year-on-year, an uplift of about thirty million dollars. The United States accounted for the largest share of earnings, generating more than $250 million—46 percent of total casual-game revenue—and posted an eleven-percent increase over the prior year. Meanwhile, less-developed markets showed accelerating expansion, signalling untapped monetisation potential. Regionally, North America retained its position as the primary source of mobile-game traffic, delivering a five-percent year-on-year rise in downloads and a modest one-percent quarter-on-quarter gain. Southeast Asia emerged as the fastest-growing market, with download growth of eleven percent year-on-year and twelve percent quarter-on-quarter, underscoring its role as a catalyst for user-base expansion. The contrast between the mature, revenue-rich U.S. market and the rapidly scaling Southeast Asian audience highlights divergent strategic imperatives for acquisition versus monetisation. Overall, the findings suggest that while casual-game revenue remains anchored by the United States, future growth will be driven by intensified marketing efforts in emerging regions, particularly Southeast Asia. Companies that balance retention-focused tactics in established markets with aggressive user-acquisition campaigns in high-growth territories are likely to optimise both short-term earnings and long-term audience development.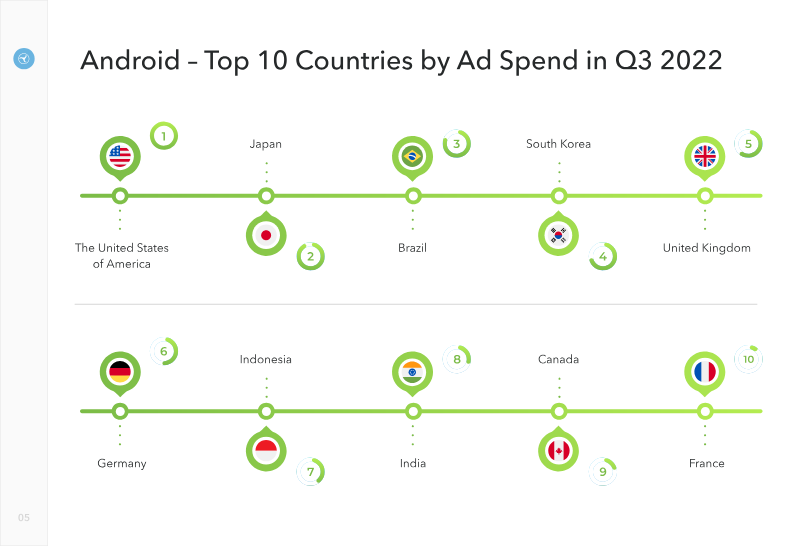
Tenjin · 2022
ReportHyper-Casual Benchmark Report Q3 2022
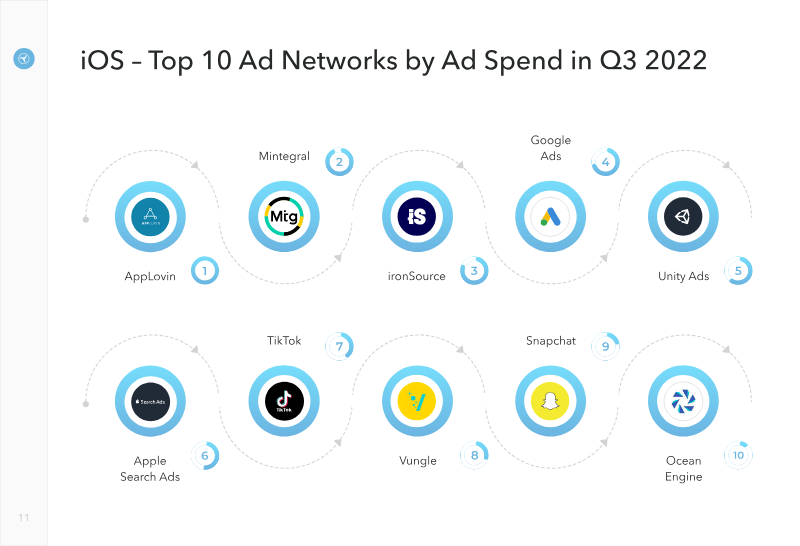
The hyper-casual gaming landscape continues to evolve as developers navigate shifting attribution models and monetization strategies. Analysis of the sector reveals that advertising remains the primary revenue driver, with a heavy reliance on high-volume user acquisition and optimized ad mediation. Data from 2021 and 2022 indicates that the top-performing ad networks for hyper-casual titles are those capable of delivering massive scale at low costs per install, while simultaneously providing robust monetization tools to capture value from short-lived player lifecycles. Geographic trends show a significant concentration of activity in established markets, though emerging regions are increasingly contributing to the global install base. The industry segments covered include both Android and iOS platforms, with a specific focus on how privacy changes have impacted attribution and marketing efficiency. Statistics suggest that while the cost of acquiring users has fluctuated, the most successful publishers are those utilizing sophisticated data analytics to balance spend across a diverse range of ad networks. Methodological insights derived from industry benchmarks highlight the importance of real-time data processing and cross-platform tracking. By examining the performance of the top ten ad networks, it becomes clear that market leadership is defined by the ability to integrate seamlessly with attribution partners. The findings conclude that the hyper-casual market remains resilient, provided that developers adapt to the technical requirements of modern mobile advertising and maintain a rigorous focus on retention metrics and effective ad placement strategies.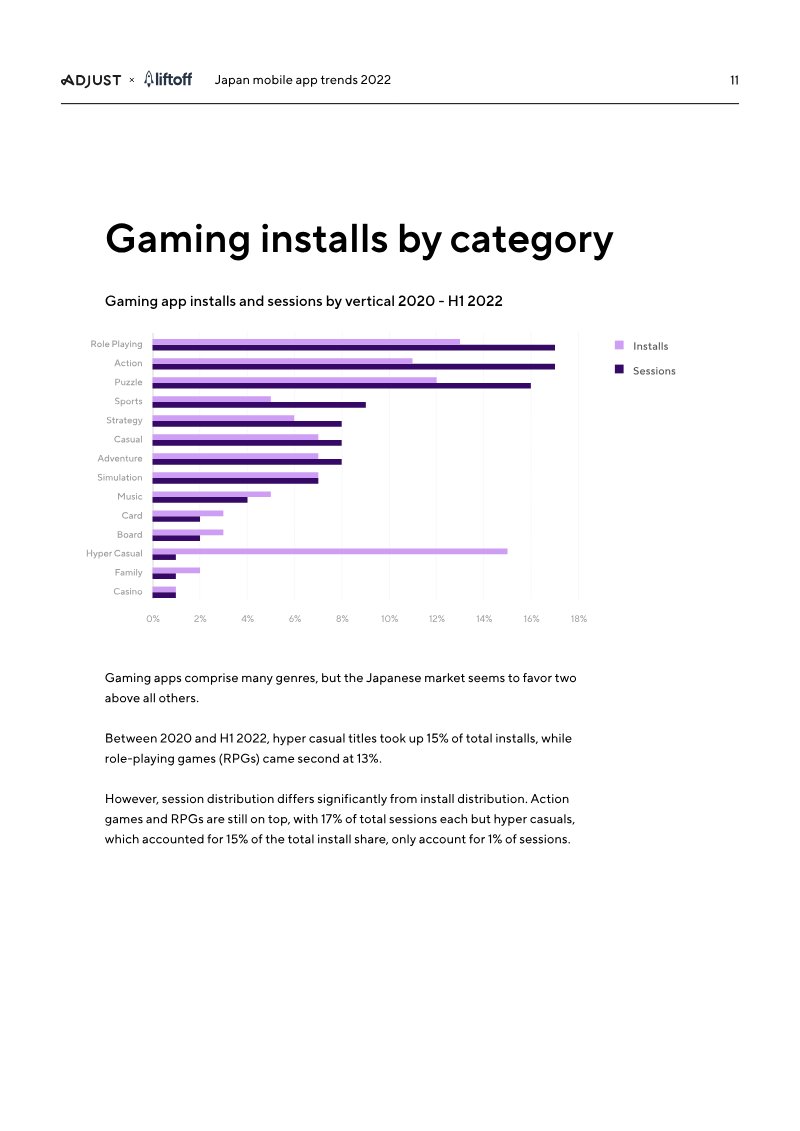
Adjust · 2022
ReportJapan Mobile App Trends 2022: Essential App Performance Benchmarks and Insights
The Japanese mobile app market underwent a period of significant expansion between 2020 and mid-2022, characterized by a 19% increase in total installs and a 12% rise in user sessions. Gaming remains the primary driver of this growth, with installs surging 52% year-over-year. Within this vertical, Hyper Casual and RPG titles command the largest market shares, accounting for 15% and 13% of installs respectively. While gaming leads in volume, the Fintech and E-commerce sectors have reached record engagement levels, with E-commerce sessions growing 29% over 2020 benchmarks and Fintech sessions rising 13% annually. User acquisition dynamics in Japan reveal a complex landscape of costs and returns across different platforms and genres. Dating apps face particularly high acquisition hurdles, with costs per install peaking at $6.60, while puzzle games average a $5.48 cost per install. Data indicates that Android users frequently outperform iOS users in terms of conversion efficiency and return on ad spend, particularly within the gaming and dating verticals. These performance metrics suggest that while the market is maturing, strategic platform selection remains critical for optimizing marketing budgets. Looking toward future growth, the Japanese digital landscape is shifting toward multi-channel engagement, with Connected TV emerging as a vital marketing frontier. Projections suggest that ad spend in the Japanese Connected TV sector will reach ¥58.8 billion by 2024. This evolution, supported by data from the top 2,000 performing apps, underscores a resilient mobile economy where traditional gaming dominance is being supplemented by rapid digital transformation in financial services and retail. The transition from 2020 through the first half of 2022 highlights a market that is both expanding in scale and diversifying in its technological reach.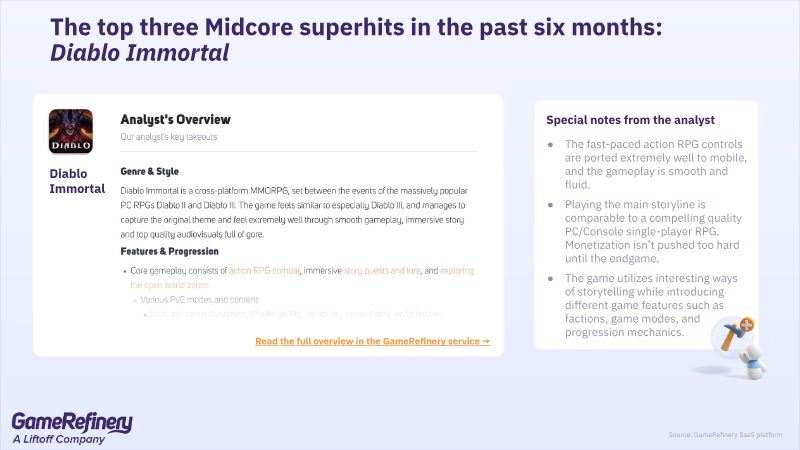
GameRefinery · 2022
ReportThe Rise of Midcore Mobile Games Snapshot Report July 2022
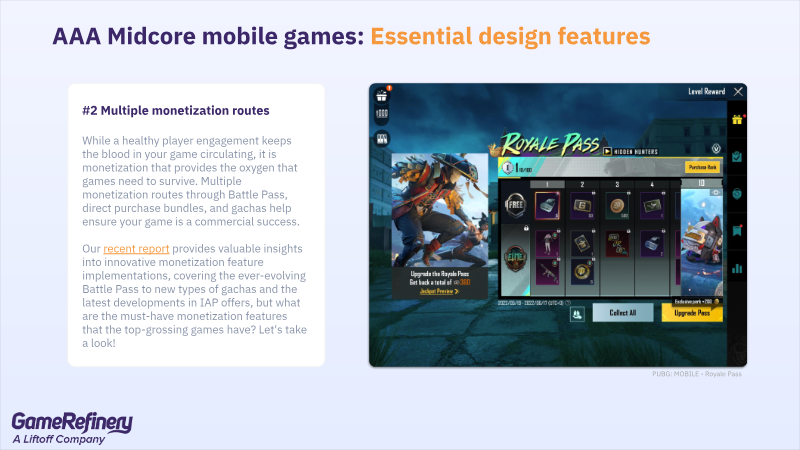
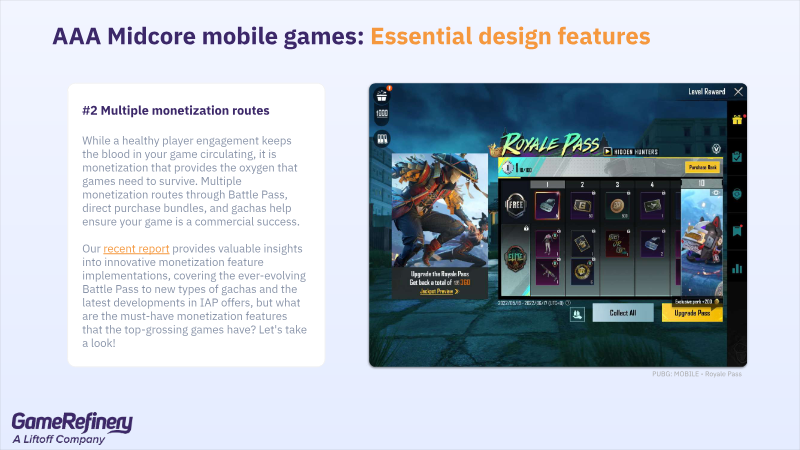
The midcore mobile gaming sector is experiencing a significant shift as AAA developers and high-fidelity titles increasingly challenge the historical dominance of casual and hyper-casual games. Analysis of the US iOS market between Q1 2021 and Q1 2022 reveals that midcore was the only category to achieve revenue growth, currently accounting for 36.73% of total mobile game revenue. This trend is further evidenced by the fact that nine midcore titles released in the past year remain in the top 200 grossing chart, compared to only three casual titles. The success of these games, such as Diablo Immortal, Genshin Impact, and Apex Legends Mobile, is attributed to three essential design pillars: sophisticated control systems, diversified monetization, and high content cadence. Top-performing midcore games differentiate themselves by offering precise, console-like manual controls and minimizing reliance on autoplay. Furthermore, they utilize complex monetization strategies; 75% of top-grossing midcore games employ Battle Pass systems, and over 63% feature five or more distinct gacha mechanics. Live operations and player engagement are equally critical, with 100% of top-tier midcore games utilizing recurring live events. A notable 80% of these titles implement special event-specific currencies to manage game economies and drive temporary sinks. Additionally, a burgeoning trend involves publishers establishing external web stores to bypass standard app store commission fees. Data for this analysis was sourced from the GameRefinery SaaS platform, focusing on feature adoption and revenue performance within the US iOS market to identify the specific mechanics that separate market leaders from the broader competitive field.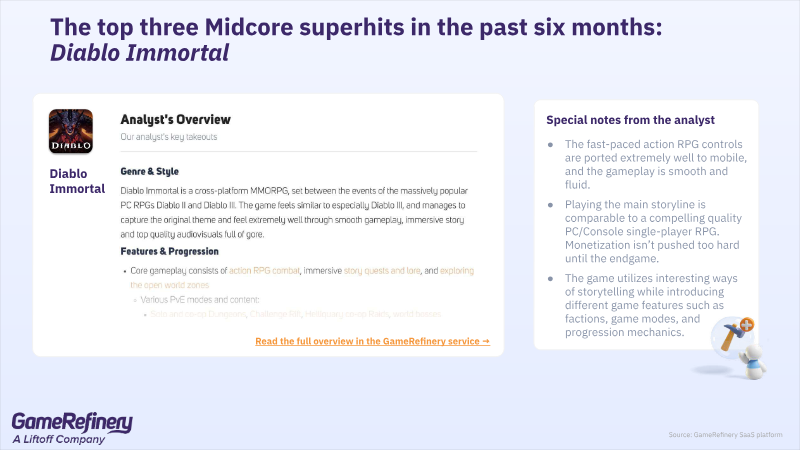
GameRefinery · 2022
ReportThe Rise of Midcore Mobile Games
This analysis explores the significant growth and evolving landscape of midcore mobile games, particularly in the United States market as of mid-2022. While casual and hyper-casual titles historically dominated the mobile space, midcore games—often high-quality AAA experiences ported from PC and console franchises—are increasingly capturing market share. Data indicates that midcore titles accounted for nearly 37% of US iOS mobile game revenue in Q1 2022, representing the only category to see year-over-year growth during that period. The findings highlight a clear performance gap between top-tier midcore games and their competitors. In a 365-day sample, nine midcore titles maintained positions in the top-200 grossing US charts, compared to only three casual titles. Success in this segment is driven by three primary pillars: sophisticated control systems that emulate the precision of console gaming, massive content cadence through live events, and diversified monetization strategies. Notably, 75% of top-grossing midcore games utilize Battle Passes, and over 65% feature five or more distinct gacha mechanics. The scope of the research focuses on the US iOS market, utilizing a proprietary three-layered taxonomy to analyze genre-specific trends. Key case studies include Diablo Immortal, Apex Legends Mobile, and Genshin Impact, which are cited for their ability to balance core gameplay depth with mobile-specific monetization. Additionally, the analysis identifies an emerging trend of publishers implementing external web stores to bypass traditional app store commission fees. The methodology relies on data-driven analysis from the GameRefinery SaaS platform, incorporating feature-level comparisons and revenue tracking to distinguish the design elements that define market leaders.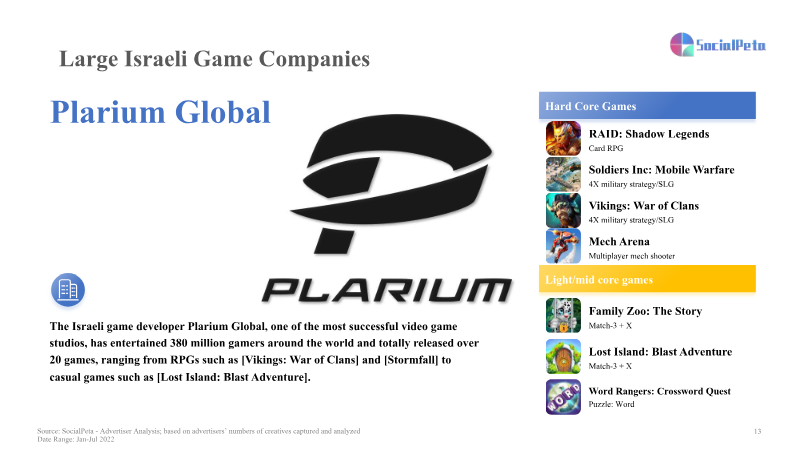
SocialPeta · 2022
Report2022 Israeli Mobile Game Market Report
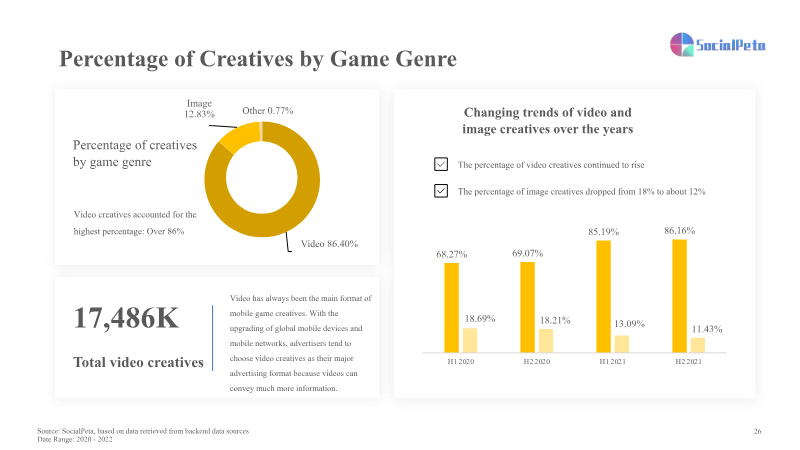
The 2022 Israeli mobile-game market is portrayed as a rapidly expanding sector that now commands a global presence, with the analysis aiming to quantify its economic weight, identify the drivers behind its growth, and assess its competitive standing worldwide. In 2022 the market generated roughly nine billion dollars in revenue, supported by about two hundred development studios employing fourteen thousand people. Social and casual titles dominate both investment flows and install numbers, while action, strategy and hyper-casual games lead in downloads and earnings, exemplified by hits such as Coin Master, PUBG Mobile and Fill the Fridge!. The surge was accelerated by the COVID-19 pandemic, which deepened user engagement and boosted in-app purchases, turning mobile gaming into a habitual pastime for a broad audience. Leading Israeli publishers—Playtika, Plarium, Moon Active and Crazy Labs—have leveraged this momentum to become global players, delivering diversified portfolios that span social, casino, RPG and simulation genres and consistently ranking among the world’s top-performing titles. Beyond domestic performance, the study highlights divergent creative advertising formats across key international markets. U.S. campaigns favor live-action influencer videos, Japanese ads emphasize character artwork, voice acting and gacha-driven narratives, while South Korean promotions adopt their own distinct stylistic approaches. These regional preferences underscore the importance of tailored marketing strategies for Israeli developers seeking to expand beyond their home market.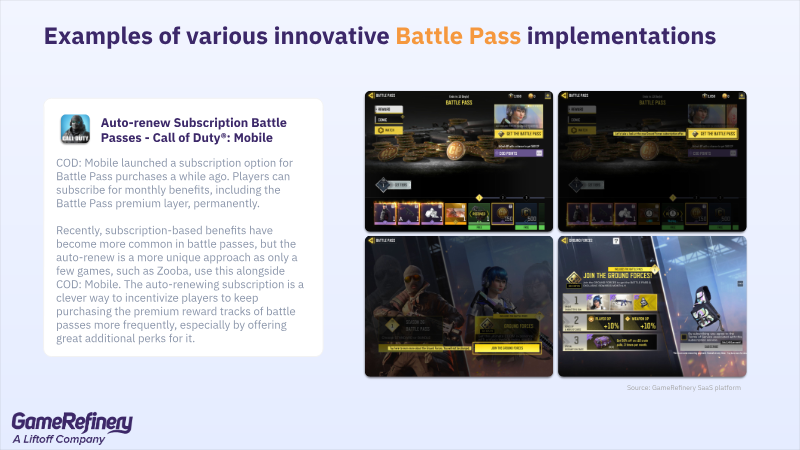
GameRefinery · 2022
ReportInnovative Monetization Features Snapshot Report June 2022
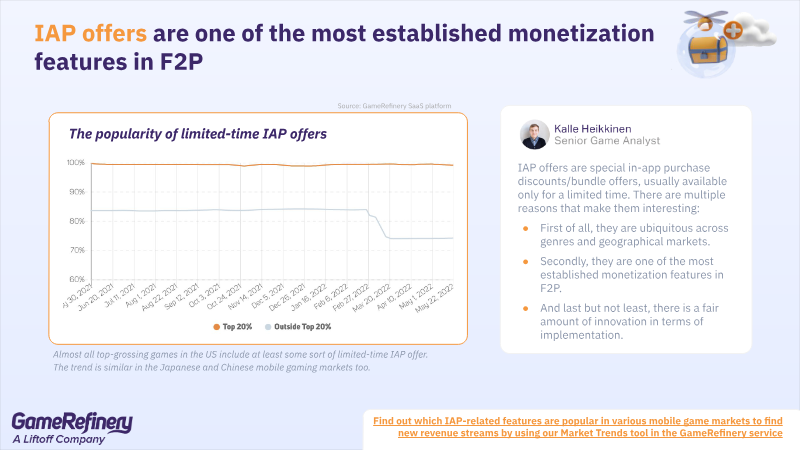
The mobile gaming landscape in mid-2022 is defined by the maturation and diversification of Battle Passes and gacha mechanics, which serve as the primary drivers for revenue in top-grossing titles. Battle Passes have evolved into sophisticated retention tools, appearing in 60% of high-performing games and incorporating social elements like guild-wide rewards and cooperative progression. Gacha mechanics remain even more pervasive, integrated into 93% of top titles in Japan and 75% of the top 20% grossing games in the United States. To maintain player trust and engagement, these systems increasingly feature transparency-focused innovations such as "pity" mechanics, player-selected prize pools, and social "joint-pull" events. Monetization strategies are shifting away from direct gameplay boosters toward meta-layer engagement, focusing on narrative depth and cosmetic customization. Successful developers utilize psychological triggers like urgency and exclusivity through "Mystery Shops" and randomized discount events. For instance, mechanics that allow players to manipulate bundle contents or discount rates increase perceived agency, while quantity-based limitations create social pressure to purchase. These tactics are particularly effective when combined with hybrid monetization models, such as ad-supported tracks that convert non-paying users into the ecosystem. Data indicates a clear correlation between sophisticated in-app purchase structures and market success. Progressive reward systems, which grant bonuses based on cumulative spending thresholds, are utilized by 23% of the top 20% grossing US iOS games, a significantly higher adoption rate than the 9% seen in lower-performing titles. By prioritizing player agency and social integration over simple transactional offers, developers are able to drive higher conversion rates and long-term player loyalty across diverse global markets and genres.
Apptica · 2022
Report