Mobile Games
The mobile market by genre, from hypercasual and puzzle to midcore and idle.
403 documents
SocialPeta · 2023
WhitepaperGlobal Mobile Game & App (Non‑Game) Marketing White Paper 2022
The global mobile landscape in 2022 was defined by a 17.5% year-on-year increase in quarterly advertisers despite a 16% decline in total creative volume. This shift indicates a transition toward more dynamic, high-frequency marketing strategies, with over 90% of advertisers launching new creatives each quarter. While North America maintained the largest advertiser base, markets in Hong Kong, Macao, and Taiwan exhibited the highest creative output per advertiser. Android remained the dominant platform for volume, often doubling the creative output of iOS, though iOS advertisers grew to represent 40% of the market by year-end. The gaming sector experienced a notable decoupling of engagement and monetization. Genres such as strategy, simulation, and casual games saw year-over-year download growth ranging from 8% to 10%, yet simultaneously faced revenue declines between 9% and 16%. To combat rising user acquisition costs and falling revenues, developers increasingly adopted "Casual + X" strategies. This trend involved integrating hyper-casual mini-games—such as "save the dog" puzzles or line-drawing mechanics—into the marketing funnels of complex RPG and strategy titles to lower costs and broaden appeal. Hybrid-casual titles also emerged as a significant force, utilizing Roguelike mechanics and high-volume video ads to bridge the gap between traditional casual play and deeper monetization. In the non-game sector, advertising activity peaked in the fourth quarter, driven largely by utility tools, shopping, and educational applications. Video content remained the primary medium, accounting for over 70% of creatives across most global regions. Major players like TikTok and Duolingo maintained market leadership through exceptionally high creative refresh rates, often exceeding 95% new content. Regionally, Southeast Asia and Turkey showed a heavy reliance on Android and localized "big hit" formulas, while the United States and Japan remained the primary drivers of global revenue. Looking forward, the industry is shifting toward story-centric strategies and user-generated content to navigate a privacy-first environment. With the implementation of SKAdNetwork 4.0 and the impending Android Privacy Sandbox, marketers are moving away from granular user-level targeting in favor of Media Mix Modeling. The prevailing conclusion is that long-term lifetime value and diversified monetization models are now essential to offset rising platform costs and tightening media budgets.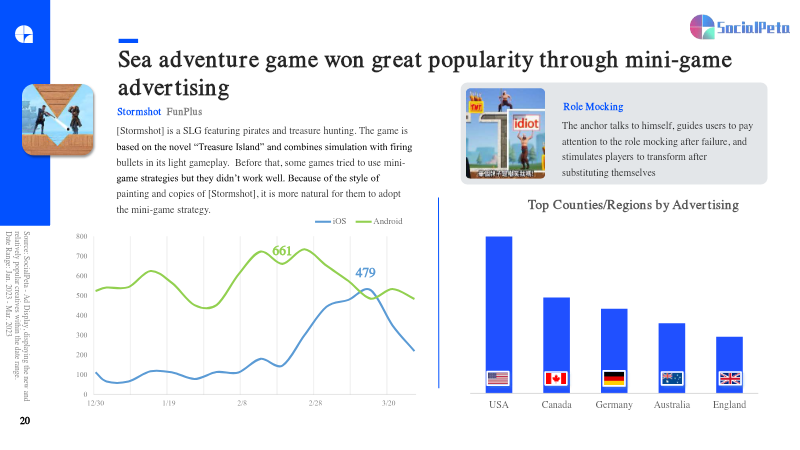
SocialPeta · 2023
ReportQ1 2023 Insights into Global Mobile Game Marketing Trends
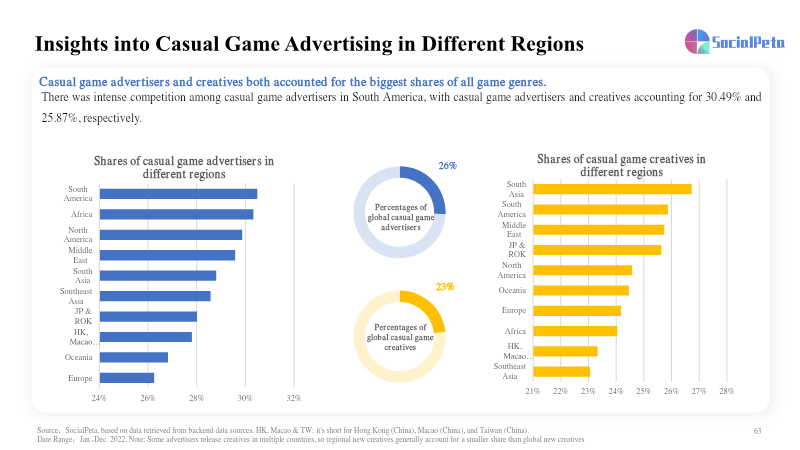
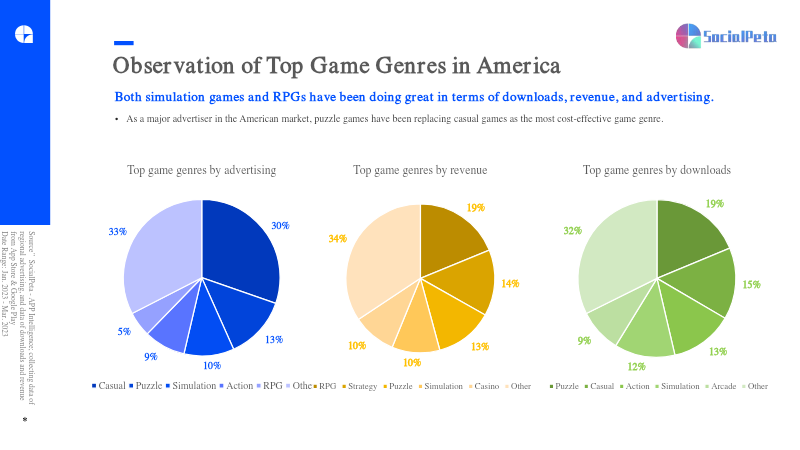
The global mobile game marketing landscape in early 2023 is characterized by a strategic pivot toward high-quality video content and localized engagement strategies. While the number of monthly active advertisers grew by 15% to over 160,000, the volume of new creative assets declined by 16%, signaling an industry-wide shift from quantity to quality. Android remains the primary platform for advertising, accounting for nearly 70% of total ad volume. Casual games continue to lead the market in both advertiser density and creative volume, though strategy and simulation genres are experiencing the most significant growth in advertiser participation. Marketing tactics have become increasingly sophisticated to combat rising acquisition costs and shifting consumer habits. Video content now comprises over 80% of all ad creatives, frequently utilizing "mini-game" mechanics, playable ads, and "deliberate failure" tropes to drive engagement. In the strategy sector, which is projected to see a 6.42% compound annual growth rate through 2027, developers are increasingly integrating casual gameplay elements into their marketing to broaden appeal. Conversely, the RPG market has cooled, experiencing its first revenue decline of 16% in 2022, leading advertisers in this space to rely more heavily on celebrity endorsements and gacha-related incentives. Geographic trends reveal a stark contrast in regional preferences and growth trajectories. North America maintains the highest advertiser density, while Southeast Asia and the Middle East are emerging as high-growth hubs, with Southeast Asian revenue projected to nearly double between 2020 and 2023. Regional success depends heavily on localization, such as TikTok-driven tournament content in Southeast Asia and social-integrated voice features in the Middle East. While puzzle games offer the most cost-effective advertising in the United States, the casino and simulation sectors are finding success in South America and global markets through relaxing creative themes and slots-focused advertising.
SocialPeta · 2023
ReportInsights into Marketing Trends of Global Mobile Apps
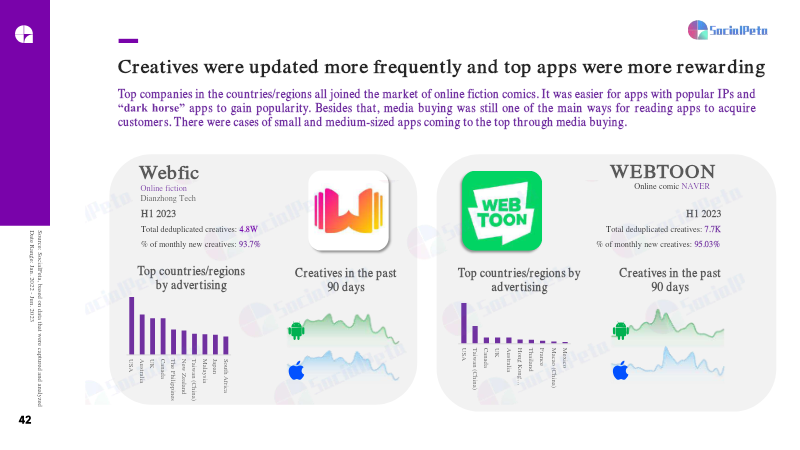
The global mobile app marketing landscape in the first half of 2023 was defined by intense competition and a decisive shift toward dynamic content. Over 93% of the approximately 170,000 active advertisers launched new creatives during this period, with emerging markets in Africa and South Asia exhibiting the highest creative density. Android emerged as the primary platform for this activity, accounting for over 70% of total creatives. Video content has solidified its dominance, representing 45% of total ad impressions globally and reaching as high as 72% in the Middle East, while traditional static image performance continues to decline. Sector-specific trends highlight a massive AI-driven boom in tool apps, which saw year-over-year advertiser growth exceeding 100% across all tracked regions. While entertainment and social apps continue to lead in revenue and downloads across North America and Southeast Asia, the Middle East has surfaced as a high-potential market characterized by a young demographic and high digital engagement. In contrast, the reading app sector has reached a stage of maturity, relying on high creative refresh rates and established intellectual properties to sustain market share in an increasingly crowded environment. Technological innovation, particularly in Artificial Intelligence and Augmented Reality, is fundamentally altering user engagement. AI-integrated tools and "Social+" entertainment platforms are attracting heavy investment in Tier-1 markets, while AR is transitioning from a novelty to a core marketing medium. With over 300 million daily AR users already active on major social platforms, projections suggest that nearly 75% of the global population will be regular AR users by 2025. This shift is driven by the high visual attention and trust associated with immersive formats, which offer significantly higher receptivity compared to traditional digital advertising methods.
data.ai · 2023
Report5 Mobile App Forecasts: 2023
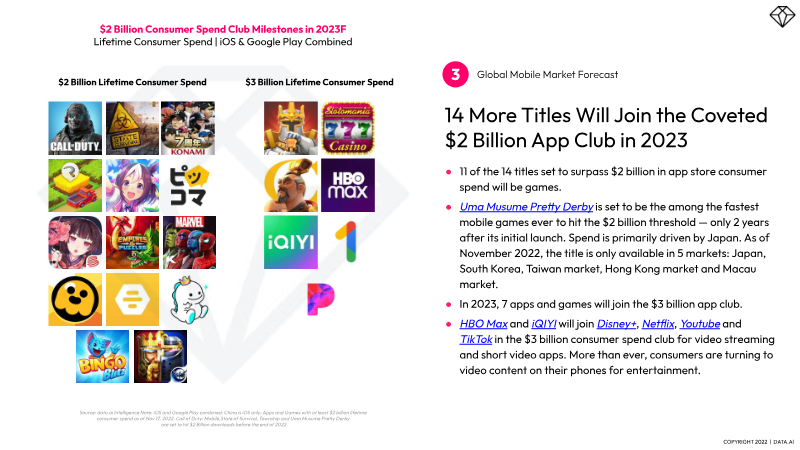
Global mobile market projections for 2023 indicate a complex landscape defined by shifting consumer priorities and economic pressures. While total mobile advertising spend is expected to reach $362 billion, growth is projected to slow due to macroeconomic headwinds. Short-form video apps are anticipated to be the primary drivers of this ad spend, helping to offset a decline in performance marketing budgets. Conversely, mobile gaming is facing a downturn, with consumer spending forecasted to drop to $107 billion in 2023. This decline is attributed to a combination of the global economic squeeze and tightening privacy regulations, such as IDFA and Google’s upcoming changes, which complicate the targeting of high-spending users. Despite the contraction in gaming spend, specific high-performing titles continue to reach massive financial milestones. Fourteen new apps and games are projected to surpass $2 billion in lifetime consumer spend during 2023, with eleven of those being games. Notably, the video streaming sector remains robust, with platforms like HBO Max and iQIYI expected to join the $3 billion lifetime spend club, reflecting a sustained consumer shift toward mobile-first entertainment. The broader mobile economy is also seeing a migration of retail dollars toward experiential sectors. As discretionary income tightens, consumers are prioritizing travel, live events, sports, and wellness over physical goods. This shift is supported by a long-term trend of increasing mobile engagement; total time spent in apps is forecasted to surpass 6 trillion hours by 2028. This growth is fueled by 5G rollout and the deepening personalization of apps, with emerging markets in Latin America, Southeast Asia, and the Middle East driving significant engagement. These findings are based on proprietary market estimates and historical data analysis of global app store performance and consumer behavior.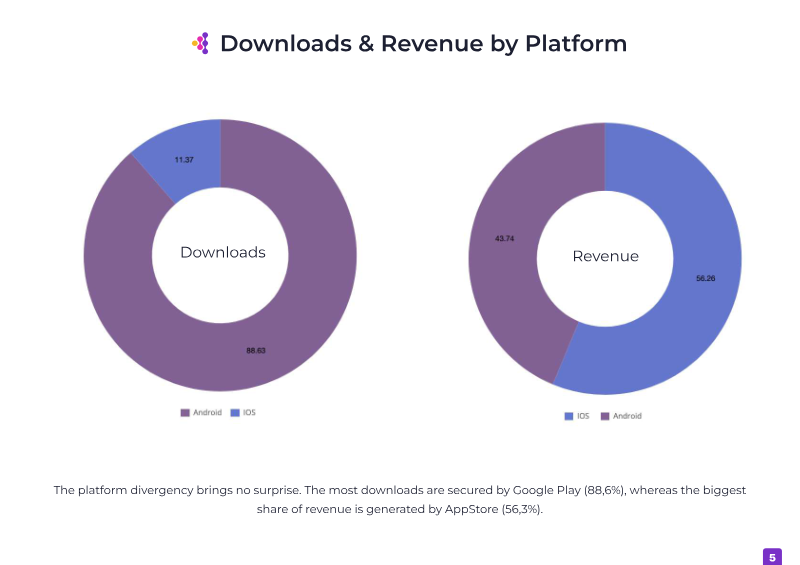
Apptica · 2023
ReportMobile Games: State of the Market
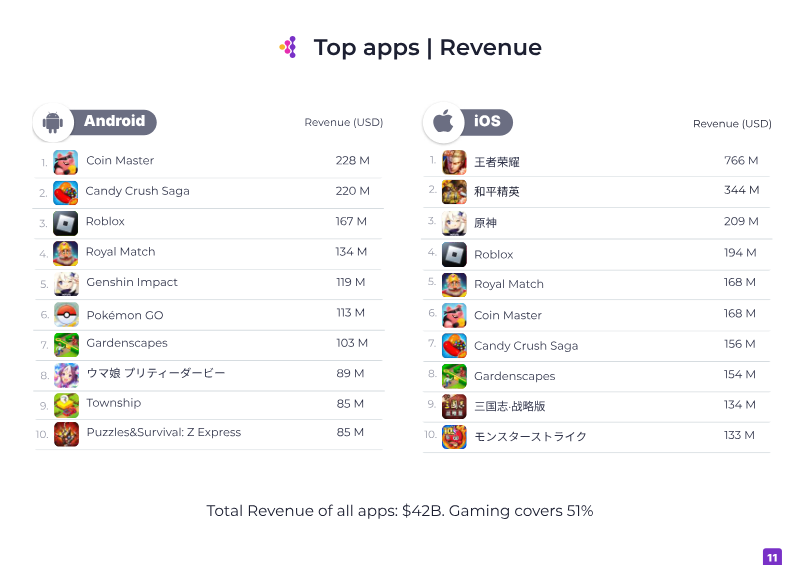
The mobile gaming market in the first half of 2023 is characterized by a general decline in downloads and revenue across most genres, despite continued dominance in the broader application economy. Mobile games currently account for 29.6% of total app downloads and 51% of total revenue. The analysis, based on data from 37 countries across the App Store and Google Play, reveals a significant platform divergence: Google Play secures 88.6% of downloads, while the App Store generates 56.3% of total revenue. Geographically, India remains the largest market for downloads with a 15.29% share, followed by Brazil and the United States. In terms of revenue, the United States leads with $5.71 billion, followed by Japan and China. While the RPG genre remains the largest revenue generator, it has experienced a gradual decline over the past two years, falling from $5.9 billion in the first half of 2022 to $4.4 billion in the same period of 2023. Casual games maintain the largest download share in most Western markets, whereas Action and Strategy genres show higher resonance in regions such as Southeast Asia and the Middle East. The advertising landscape shows a shift toward video content, which now accounts for 72% of all gaming creatives. Although the total number of advertisers on Android saw a slight decrease, the gaming sector specifically experienced a 22% year-over-year growth in the number of advertisers. In total, gaming apps generated 8.9 million creatives during this period, representing 56% of all mobile advertising creatives. Top-performing titles like Subway Surfers and Roblox continue to lead in downloads, while Coin Master and Honor of Kings remain top revenue earners across their respective platforms.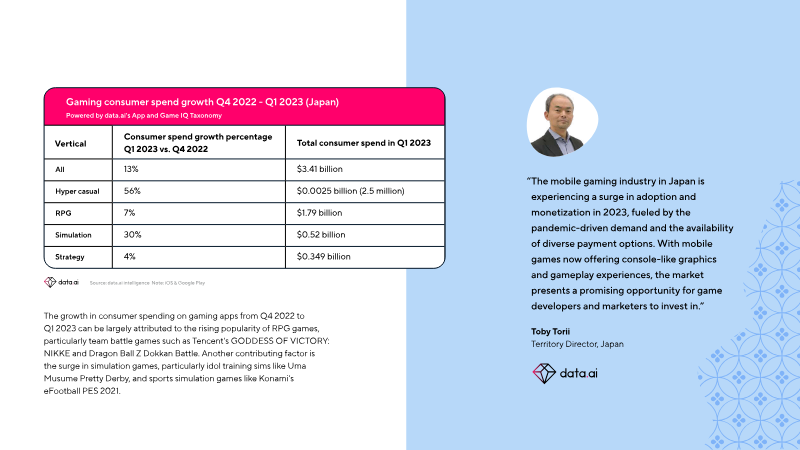
Adjust · 2023
ReportMobile App Trends 2023: Japan Edition
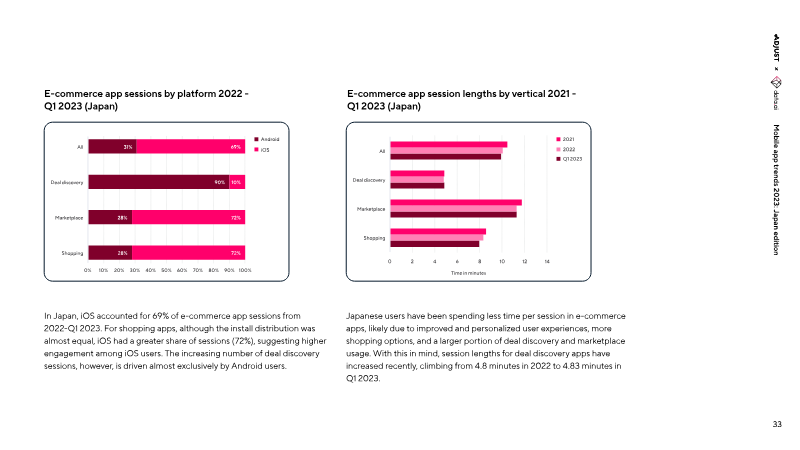
Japan’s mobile app market is undergoing a significant recovery following a downturn in 2022, characterized by a 12% surge in consumer spending to $4.65 billion in the first quarter of 2023. This resurgence is primarily anchored by the gaming sector, which generated $3.14 billion during the same period. Role-playing games and simulation titles remain the dominant forces in the region, leading in both installation volume and user retention. While iOS remains the preferred platform for the majority of Japanese mobile users, accounting for over 60% of gaming and fintech engagement, the market is defined by a unique tension between high engagement and strict data privacy preferences, as evidenced by opt-in rates that consistently trail global averages. Beyond gaming, the e-commerce and fintech sectors are experiencing robust expansion. Marketplace apps currently command nearly half of all e-commerce installs, contributing to a projected annual revenue of $156.3 billion. Simultaneously, fintech adoption is accelerating, with crypto-related applications seeing a 134% quarterly increase in installs. Despite these growth metrics, developers face persistent challenges regarding user loyalty, as evidenced by declining retention rates and shorter session durations in the e-commerce vertical. This necessitates a shift toward more sophisticated user acquisition strategies that balance personalization with privacy-compliant data aggregation. The advertising landscape is also evolving rapidly with the rise of Connected TV (CTV) as a critical growth channel. With household ownership of internet-connected televisions reaching 30 million, the CTV ad market is projected to hit 169.5 billion yen by 2025. This medium offers higher audience receptivity and superior ad quality compared to traditional mobile formats. To maintain momentum through 2023 and beyond, marketers must diversify their channel mix and leverage cross-device measurement tools to optimize return on investment across both mobile and television platforms.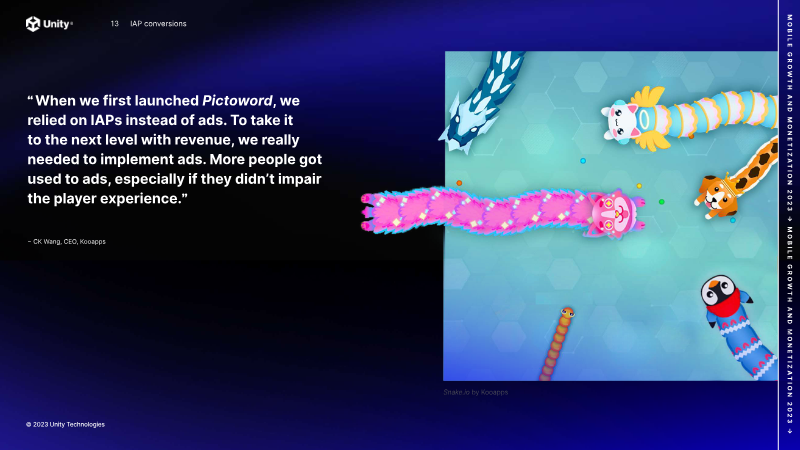
Unity · 2023
ReportMobile Growth & Monetization Report 2023
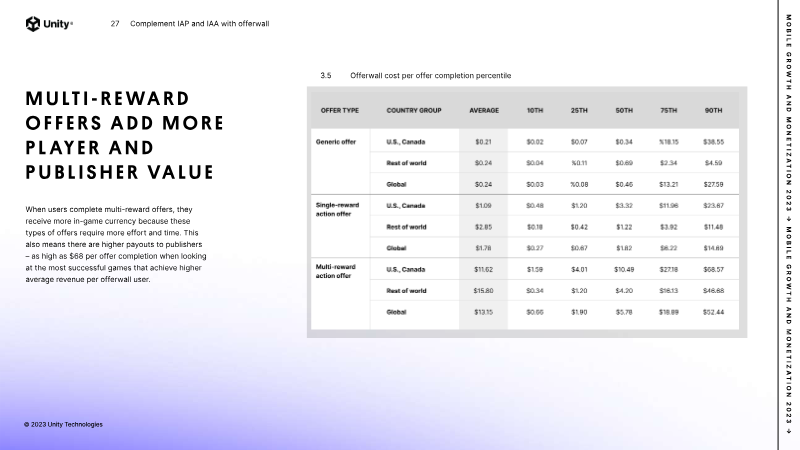
The mobile gaming landscape in 2023 reflects a strategic pivot toward operational efficiency as developers navigate softening in-app purchase (IAP) and advertising revenues. Success currently hinges on capturing player interest within the first 14 days, a critical window where 77% of all conversions occur. To capitalize on this timeframe, monetization strategies emphasize low-friction price points between $1.01 and $5.00, with high-performing assets such as virtual currencies, limited-time bundles, and sales generating over 56% of total IAP revenue. Beyond direct purchases, the integration of rewarded video ads and offerwalls has become essential for sustaining non-paying user bases. Strategic ad placement between levels or within game lobbies yields the highest engagement, particularly when incentivized by currency or gacha mechanics. Offerwalls, in particular, represent a significant growth lever, contributing 33% of total ad revenue for games utilizing multi-faceted monetization. These tools also serve as powerful retention drivers; players engaging with offerwalls demonstrate a 14% retention rate at Day 90, vastly outperforming the 3% rate seen among non-converters. From a global marketing perspective, hypercasual advertising remains the most effective conversion engine across the majority of gaming genres. Advertisers are increasingly looking toward high-value Tier-2 markets, noting exceptional click-through rates for sports titles in Japan and trivia games in South Korea. Furthermore, the adoption of Custom Store Pages is emerging as a vital tactic for improving return on investment, particularly within the puzzle, casino, and lifestyle segments. These findings underscore a broader industry trend toward data-driven personalization and diversified revenue streams to maintain long-term player lifetime value.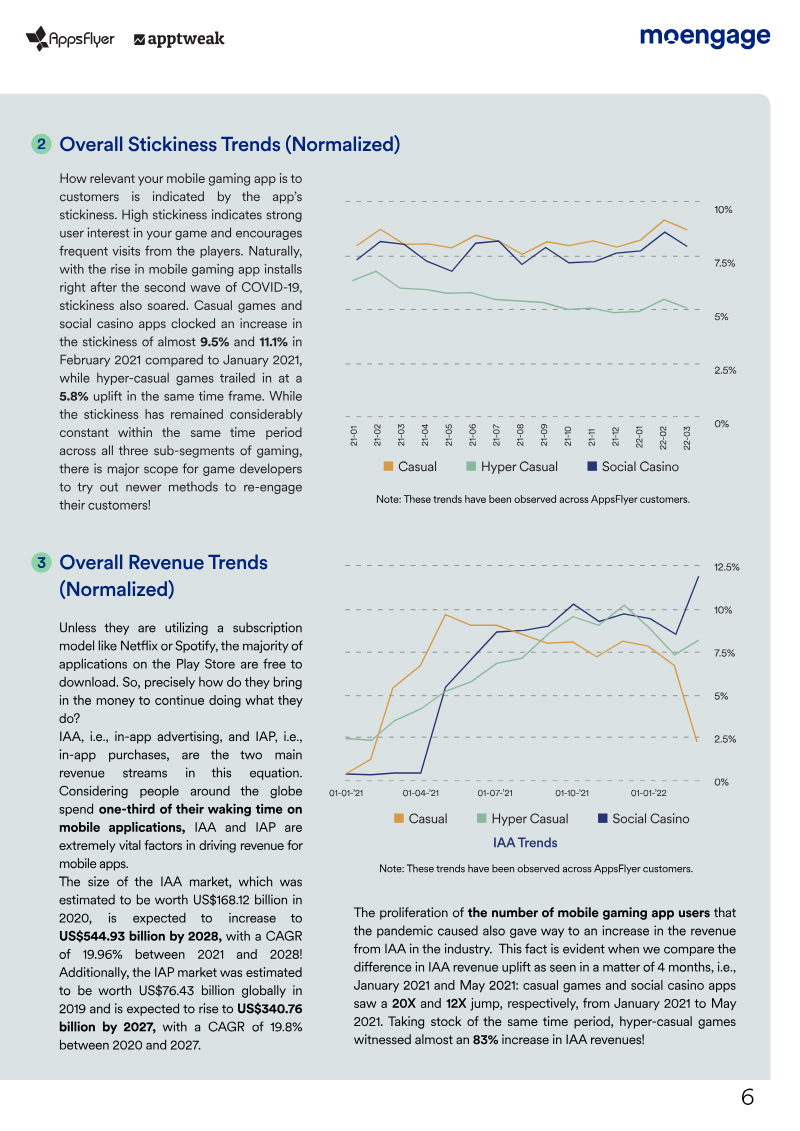
MoEngage · 2023
ReportThe State of Mobile Gaming in India: A Look at India's Casual, Hyper-Casual, and Real Money Gaming App Industry Trends
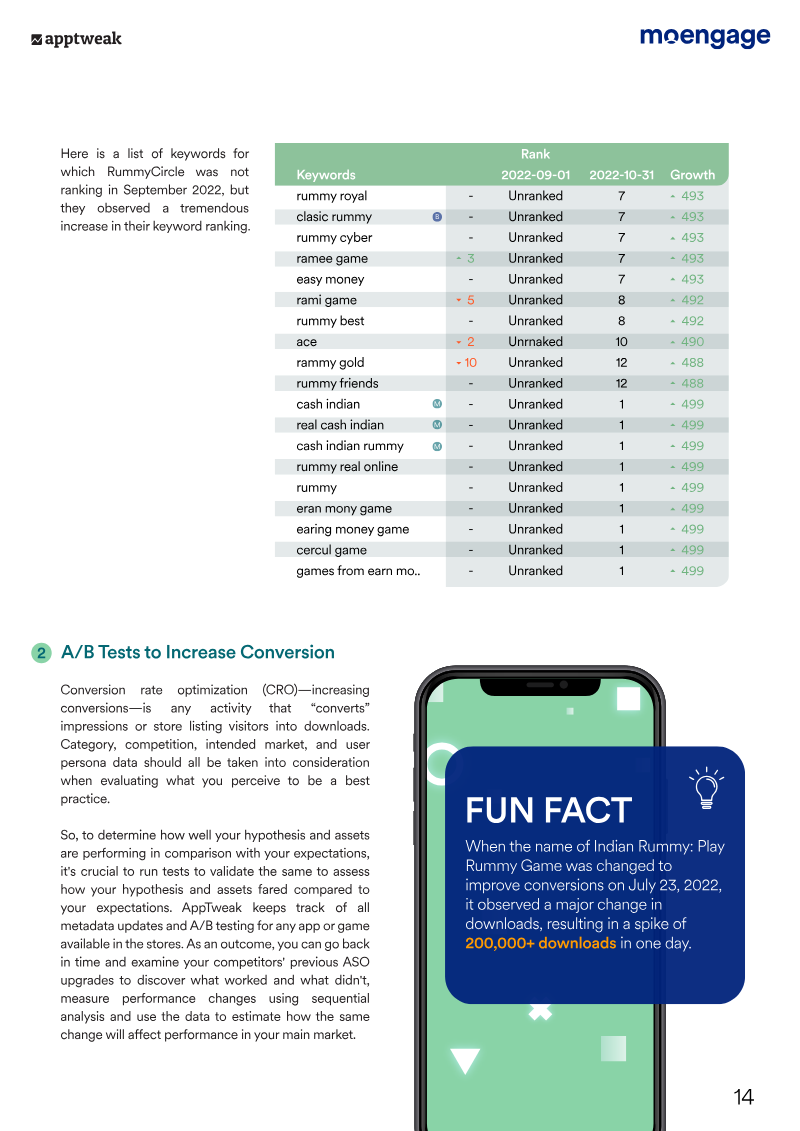
This analysis examines the rapid expansion and evolving user behavior within the Indian mobile gaming market, focusing on the casual, hyper-casual, and real-money gaming (RMG) segments. The primary thesis asserts that while the COVID-19 pandemic and increased smartphone penetration triggered a massive "gold rush" in installs and engagement, the industry now faces a critical inflection point. As organic growth stabilized in 2022, the focus for developers has shifted from simple acquisition to sophisticated, insights-led retention and monetization strategies to sustain long-term profitability. Key findings value the Indian gaming industry at $2.6 billion, with projections to reach $8.6 billion by 2027. Data indicates that India has surpassed the United States in terms of user base, exceeding 300 million gamers. During the 2021 pandemic waves, casual games saw a 90% uplift in installs, while RMG apps experienced significant revenue fluctuations, including a 35% increase in April 2021. However, the data reveals a downward trend in "stickiness" and installs moving into 2022, highlighting a retention crisis where 68% of users engage with an app fewer than ten times. The scope of the research covers the Indian market from 2021 through the first quarter of 2022, utilizing data from over 100 gaming brands. The methodology relies on a combination of market analysis from MoEngage, AppTweak, and AppsFlyer, incorporating normalized trends in installs, In-App Advertising (IAA), and In-App Purchases (IAP). The conclusions emphasize that technical optimization and personalized engagement are mandatory for survival. Effective strategies identified include App Store Optimization (ASO) to improve discoverability, RFM (Recency, Frequency, Monetary) segmentation to target "champion" players, and the use of predictive AI to prevent churn. The findings suggest that brands utilizing multi-channel engagement platforms can achieve push notification conversion rates as high as 91%, which is essential for navigating India's highly competitive and maturing digital landscape.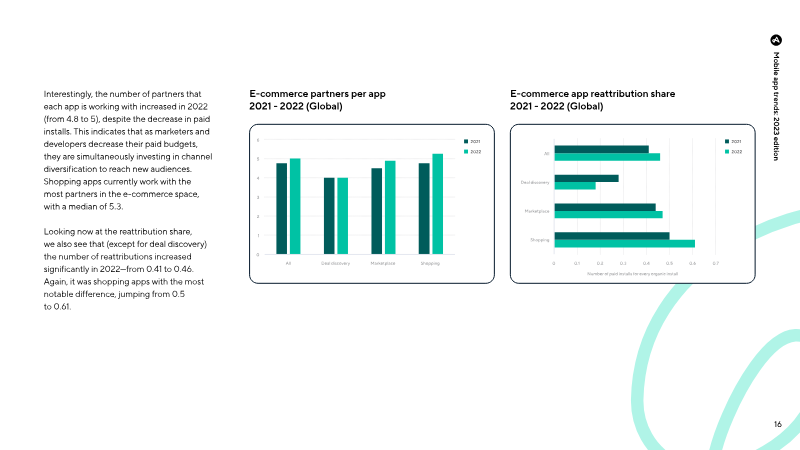
Adjust · 2023
ReportMobile App Trends: 2023 Edition
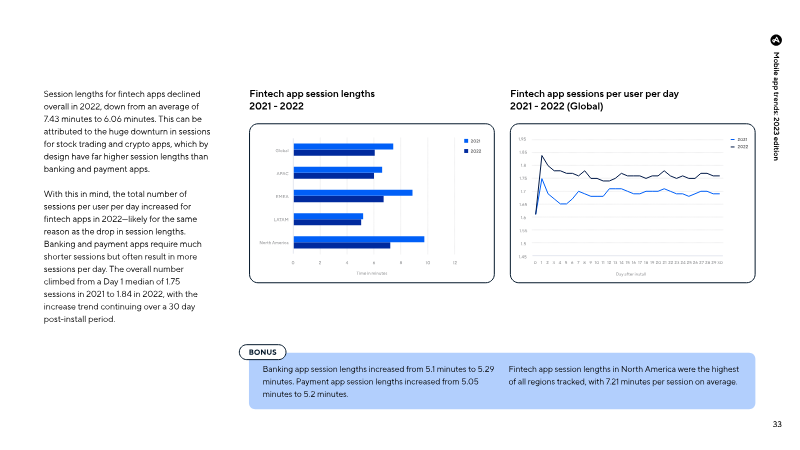
The mobile application market entered a period of significant transition in 2023, navigating a complex landscape defined by economic volatility and evolving privacy regulations. Despite these headwinds, the industry achieved a record half-trillion dollars in combined advertising and consumer spending. While global advertising growth slowed to 14% and consumer spending experienced a marginal 2% decline, the sector demonstrated remarkable resilience through strategic adaptations. Key shifts include a rising App Tracking Transparency (ATT) opt-in rate of 29% and an increased reliance on media mix modeling and Connected TV (CTV) to optimize return on investment in a privacy-centric environment. Sector-specific performance reveals a stark contrast between industries. Fintech and e-commerce emerged as primary growth drivers, with fintech in-app revenue surging over 90% between late 2022 and early 2023. E-commerce sessions grew by 12%, supported by record-breaking revenue peaks in late 2022. Conversely, the mobile gaming industry faced its most challenging year on record in 2022, marked by a 12% decline in installs and a 9% drop in consumer spending. However, early 2023 data indicates a nascent recovery for gaming, with installs and sessions rebounding by 10% and 11% respectively over previous averages. The current market environment necessitates a shift from broad acquisition strategies toward long-term user retention and sophisticated measurement. As retention and "stickiness" remain persistent challenges across all verticals, developers are increasingly prioritizing reattribution campaigns, personalized onboarding, and loyalty programs. Success in the coming years depends on the adoption of advanced analytics and cross-platform insights to navigate data-privacy requirements. By leveraging these tools, stakeholders can effectively drive user acquisition and maximize lifetime value in an increasingly competitive global marketplace.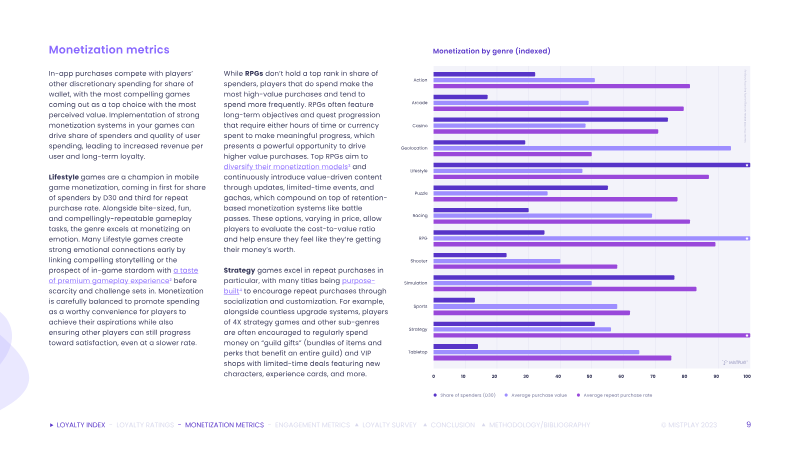
Mistplay · 2023
ReportMobile Gaming Loyalty Report 2023
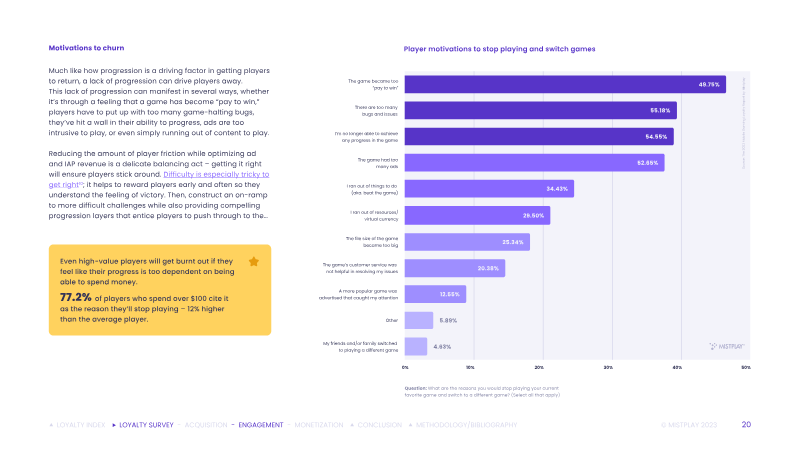
The Mobile Gaming Loyalty Report examines the drivers of player engagement, retention, and spending across the mobile landscape. By combining a longitudinal benchmark of 500 games with a survey of 3,000 mobile gamers in the US and Canada during 2023, the analysis establishes a Loyalty Index based on six key monetization and engagement KPIs. The findings emphasize that while user acquisition remains expensive, maximizing the lifetime value of existing players through loyalty-centric design is essential for sustainable growth. Role-Playing Games (RPGs) emerge as the most loyal genre, scoring 75 out of 100 on the index due to deep gameplay loops and compounding monetization systems that encourage high-value, frequent spending. Strategy games follow closely, excelling in repeat purchases and session frequency. Conversely, Lifestyle games lead in average sessions per user, utilizing bite-sized tasks and emotional storytelling to drive incremental spending. Data indicates a significant gap between average and top-quartile performers in genres like Casino and Sports, suggesting substantial room for optimization in retention and spender conversion. Consumer behavior insights reveal a disconnect between play and spend habits; while over 77% of spenders rotate between two to seven games weekly, 53% concentrate their spending on a single title. Progression is the primary motivator for both continued play and in-app purchases, whereas "pay-to-win" mechanics and poorly received updates are leading causes of churn. Notably, 39% of players will abandon a game if a bad update is not corrected within a week. High-value spenders, defined as those spending over $100, exhibit more demanding standards for app store ratings and customer service. Marketing effectiveness is heavily influenced by authenticity and social proof. Over 71% of gamers demand real gameplay footage in advertisements, and 60% consider app store ratings and reviews crucial for downloads. While digital ads remain the primary discovery tool, word-of-mouth ranks as a top-three acquisition source. Additionally, there is a strong interest in play-and-earn mechanics, with 84% of respondents open to trying games that offer tangible rewards.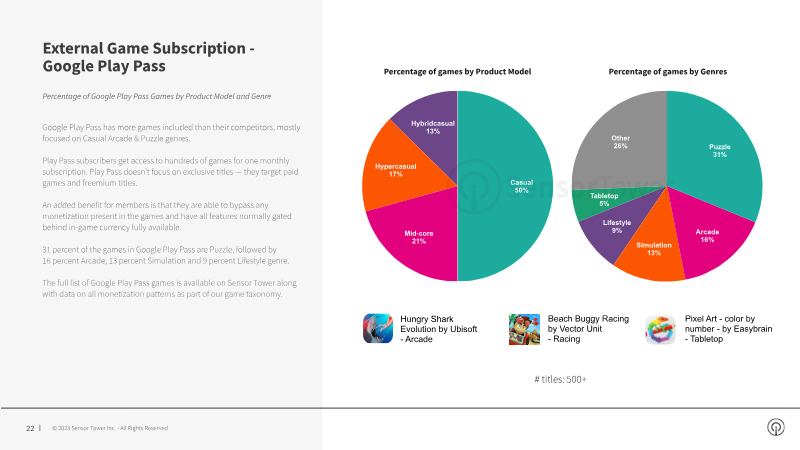
Sensor Tower · 2023
ReportThe State of Mobile Gaming 2023: Mobile Gaming Market Trends and Top Titles in the U.S., Europe, and Asia
The global mobile gaming landscape underwent a significant structural transition in 2022, characterized by a 14% decline in total player spending from its 2021 peak alongside a stabilization of download volumes at approximately 13.8 billion per quarter. While major markets such as the United States, Japan, and South Korea experienced revenue contractions, China emerged as the second-largest market globally, and India solidified its position as the leader in download volume, accounting for 17% of total installs. This period marked a definitive shift away from the hypercasual genre, which saw an 18% decline in downloads due to rising user acquisition costs and broader economic pressures. In response to these market pressures, the industry is pivoting toward a hybridcasual model that blends accessible core mechanics with sophisticated mid-core monetization and meta-progression features. This emerging segment grew by 13% and generated $1.4 billion in revenue, driven by significantly higher player engagement than traditional casual titles. Success in the current environment is increasingly dictated by the effective use of Live Ops, which now accounts for 97% of revenue among top-grossing games. Features such as character collection and social clan systems have become essential for maintaining high engagement levels and driving long-term player retention. While established genres like RPGs and shooters faced revenue declines, the action genre grew by 9%, and subscription-based models gained momentum, exemplified by the expansion of ad-free gaming catalogs. Conversely, the crypto and NFT gaming sector experienced a sharp downturn, with downloads falling from 46 million to 29 million and revenue dropping by 35%. Despite the overall contraction in spending, the market remains larger than pre-pandemic levels, with legacy titles like Honor of Kings and Subway Surfers maintaining dominance in revenue and download rankings, respectively, across a diversifying global audience.
Unity · 2023
Report