1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial report Tencent
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial reportTencent
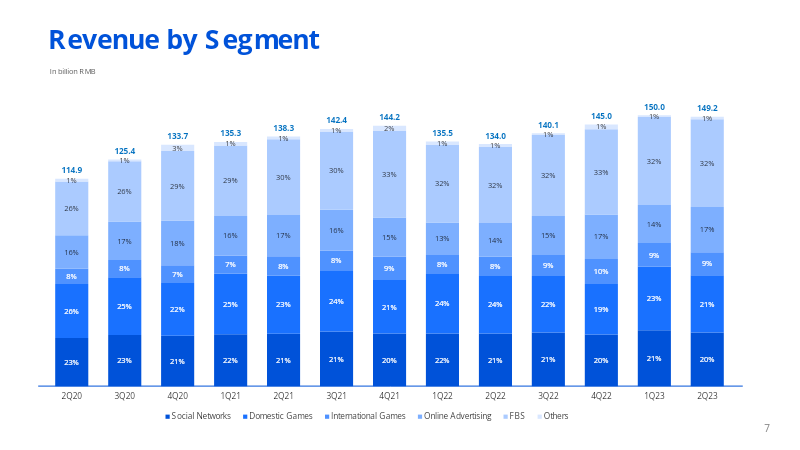
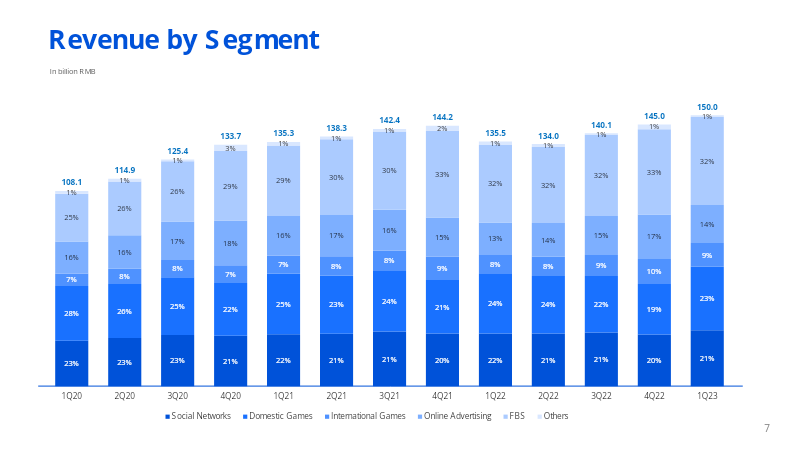
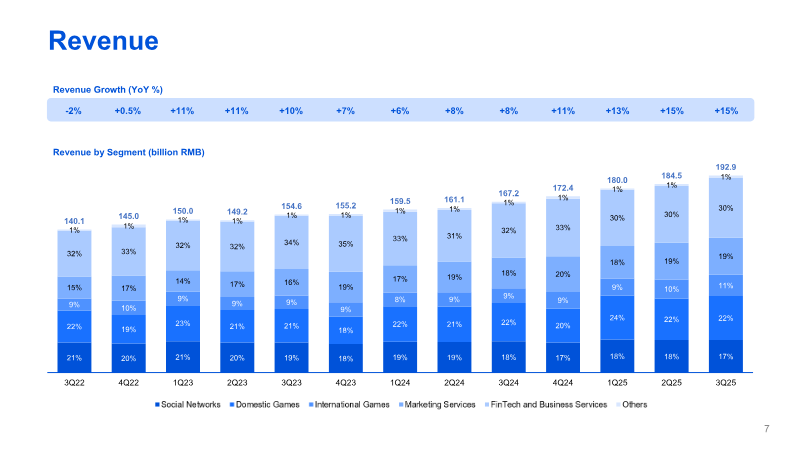
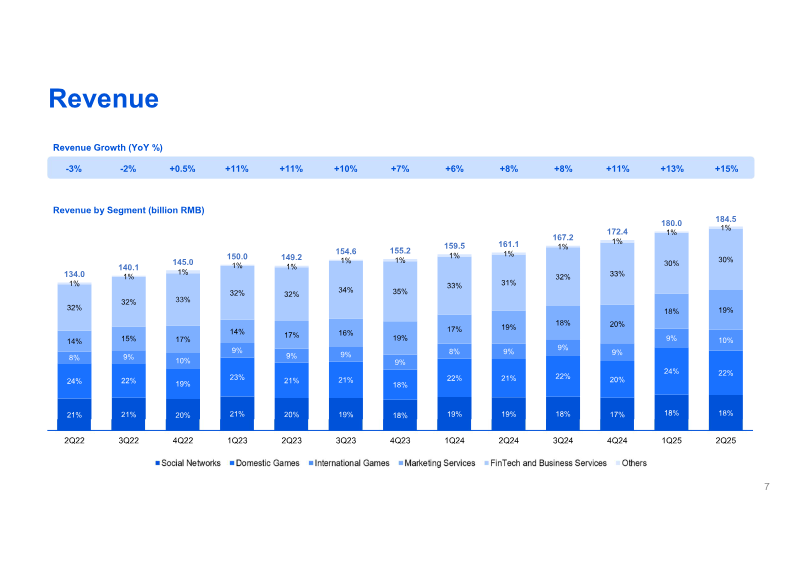
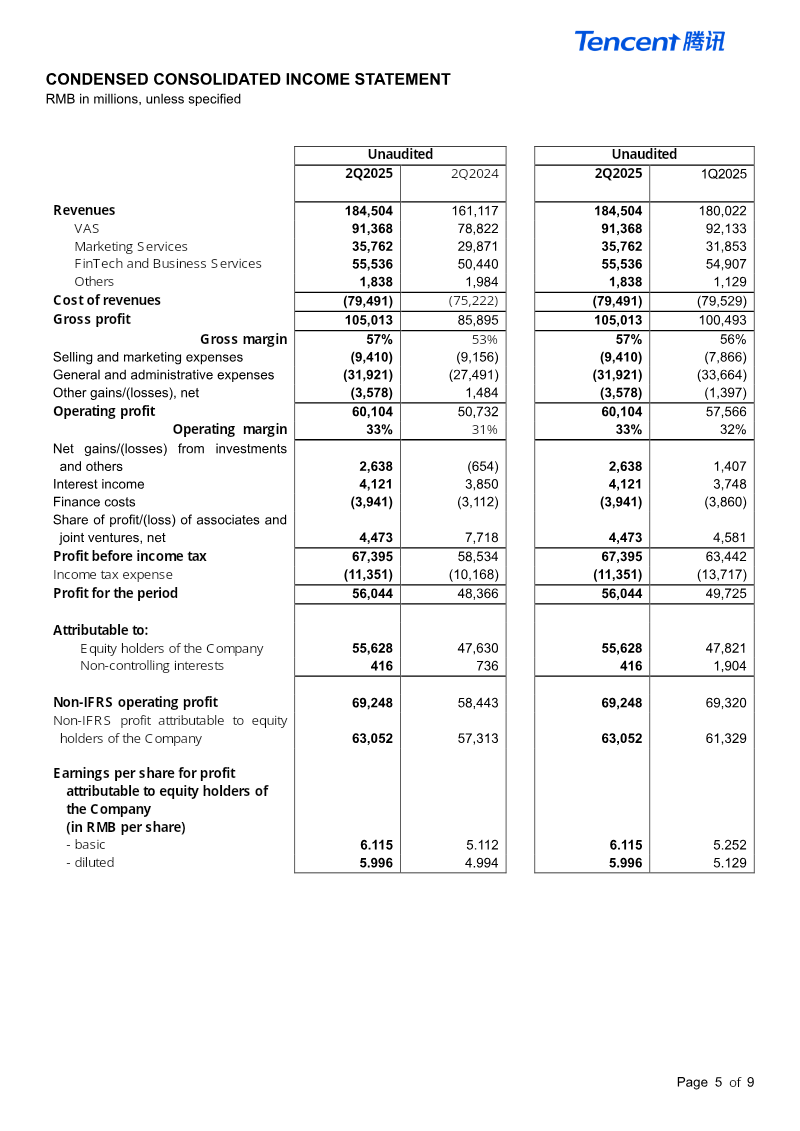
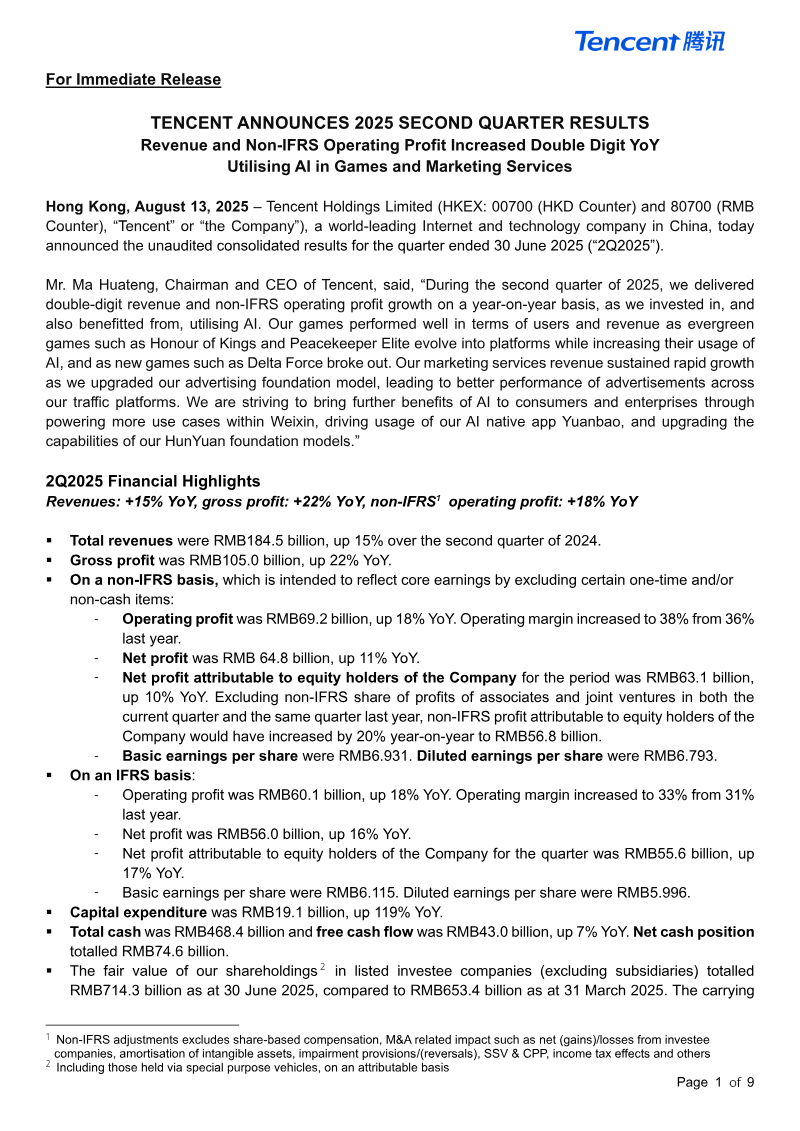
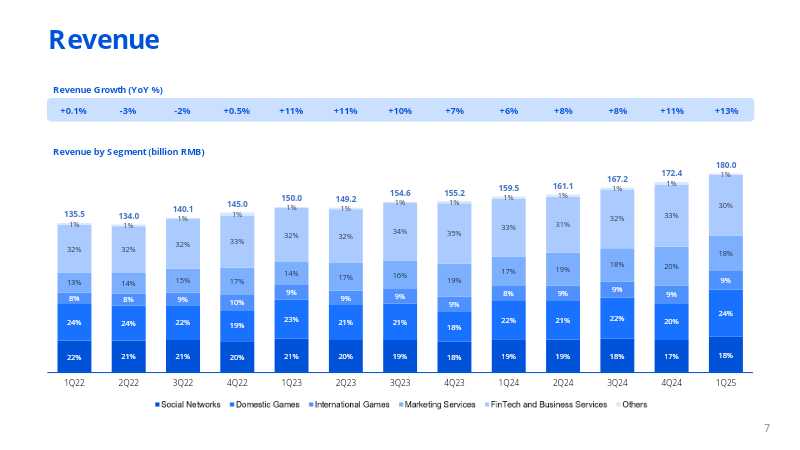
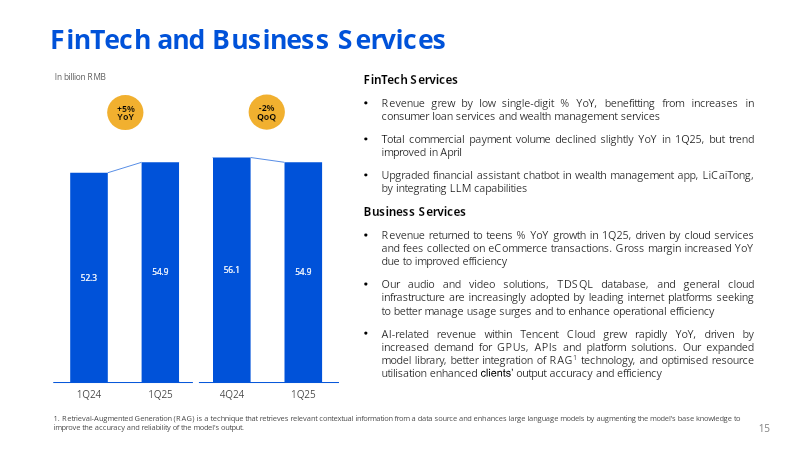
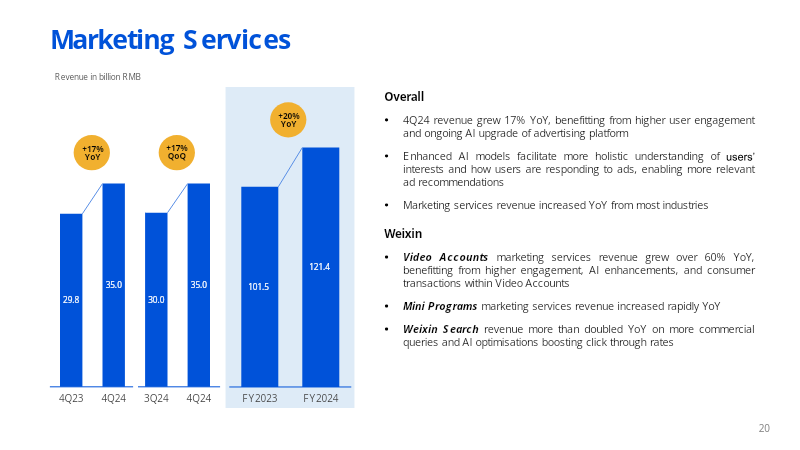
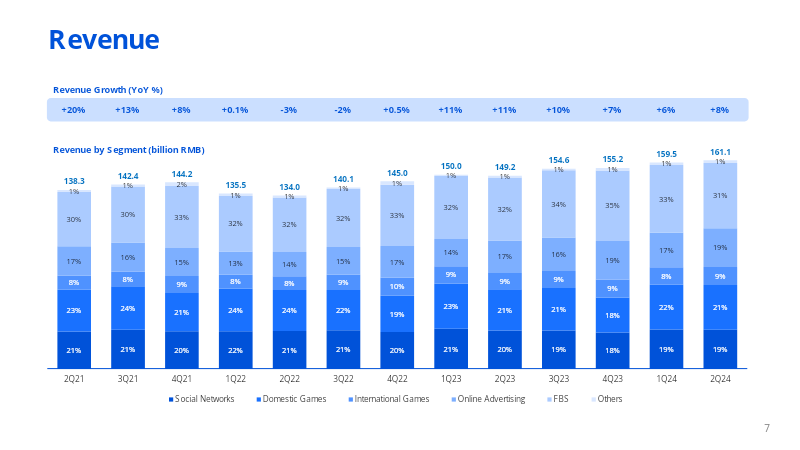
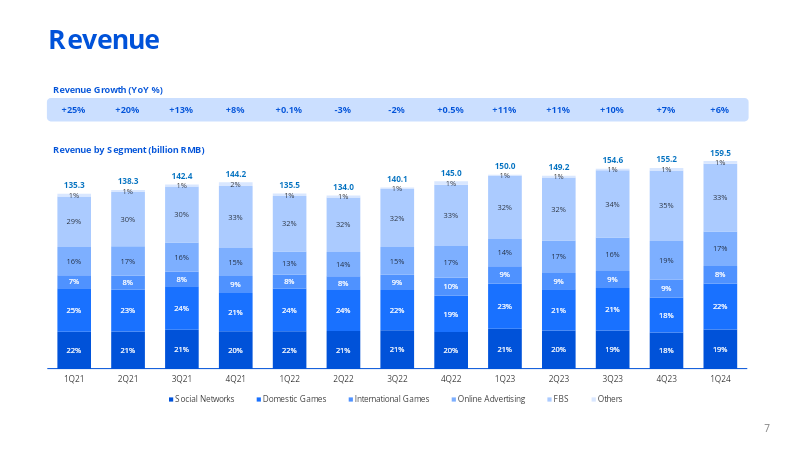
Tencent’s third-quarter 2023 financial results demonstrate a strategic shift toward high-quality, high-margin revenue streams and disciplined cost management. The company reported total revenue of RMB 154.6 billion, representing a 10% year-over-year increase. This growth was underpinned by strong performance in online advertising, which rose 20%, and FinTech and Business Services, which grew 16%. The company’s non-IFRS operating profit reached RMB 55.5 billion, a 36% increase compared to the same period in the previous year, reflecting improved operating leverage and efficiency.
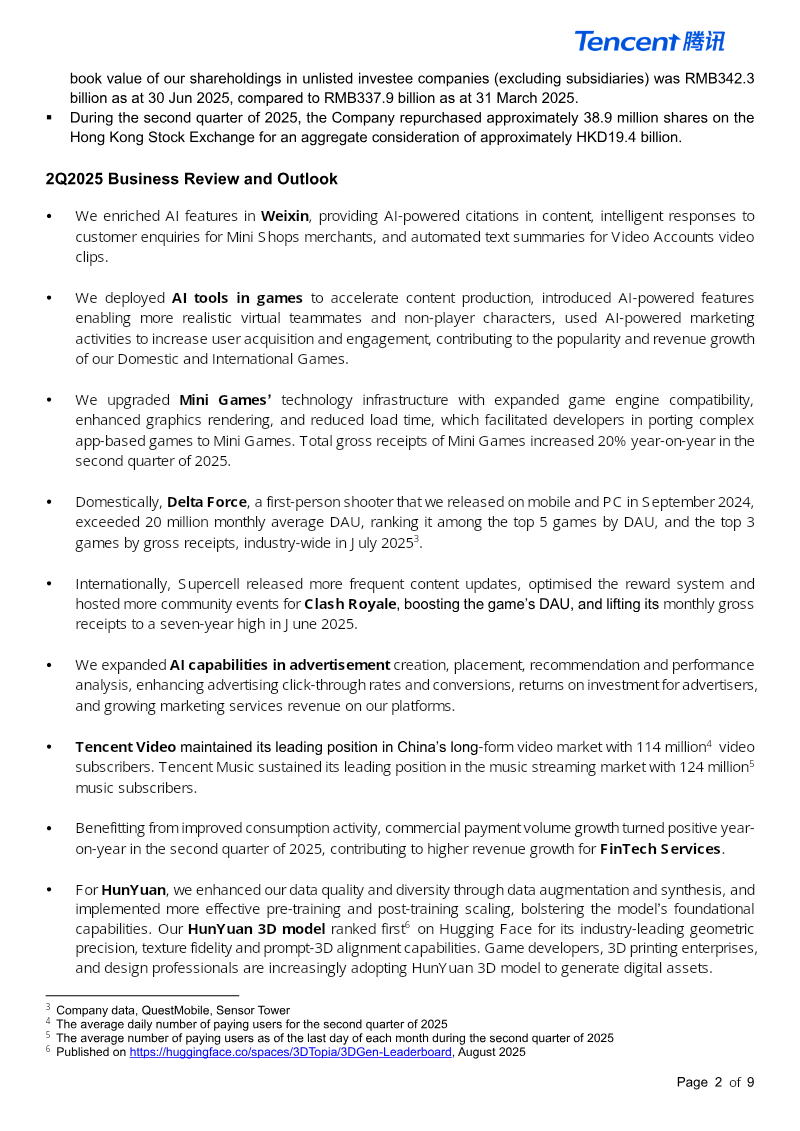
The gaming segment, a core pillar of the business, showed mixed but resilient results. Domestic game revenue grew 5% to RMB 32.7 billion, supported by established franchises and new releases such as VALORANT and Lost Ark. International game revenue saw a 14% increase to RMB 13.3 billion, driven by the recovery of PUBG MOBILE and sustained contributions from titles like NIKKE. The company continues to invest in content-driven and competitive multiplayer games, while leveraging its Mini Games platform to maintain its position as a leader in the casual gaming market.
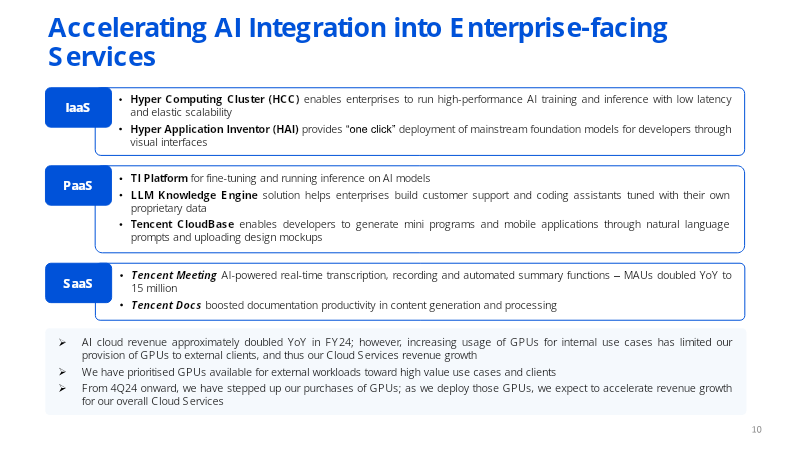
Operational highlights center on the Weixin and WeChat ecosystem, which remains the company's primary mobile community with 1.336 billion monthly active users. Video Accounts have emerged as a significant driver of engagement and incremental revenue, benefiting from high-margin in-feed advertising and eCommerce technology service fees. Furthermore, the company is integrating its proprietary foundation model, Tencent Hunyuan, across its cloud and productivity services to enhance generative AI capabilities for enterprise customers.
The company maintains a strong financial position, reporting a free cash flow of RMB 51.1 billion, an 85% increase year-over-year. This liquidity supported the repurchase of approximately 48 million shares during the quarter. By exiting non-core businesses and optimizing operating expenses, the company has successfully transitioned to a quality-driven growth model, positioning itself for sustained efficiency in its core communications, social networking, and digital infrastructure segments.
Tencent · 2026
Tencent · 2026
Tencent · 2026
Tencent · 2025
Tencent · 2025
Tencent · 2025
Tencent · 2025
Tencent · 2025
Tencent · 2025
Tencent · 2025
Tencent · 2024
Tencent · 2024
NetEase · 2025