Playtika demonstrated robust financial growth during the first quarter of 2022, reporting revenue of $676.9 million compared to $638.9 million in the same period of the previous year. Net income saw a substantial increase to $83.2 million, up from $35.7 million in 2021, supported by a lower effective tax rate of 10.4%. This performance was driven by strategic acquisitions, including JustPlay.LOL Ltd., and enhanced monetization efforts. Despite these gains, Adjusted EBITDA declined to $220.5 million, reflecting elevated operating expenses associated with increased headcount and higher investments in research, development, and marketing.
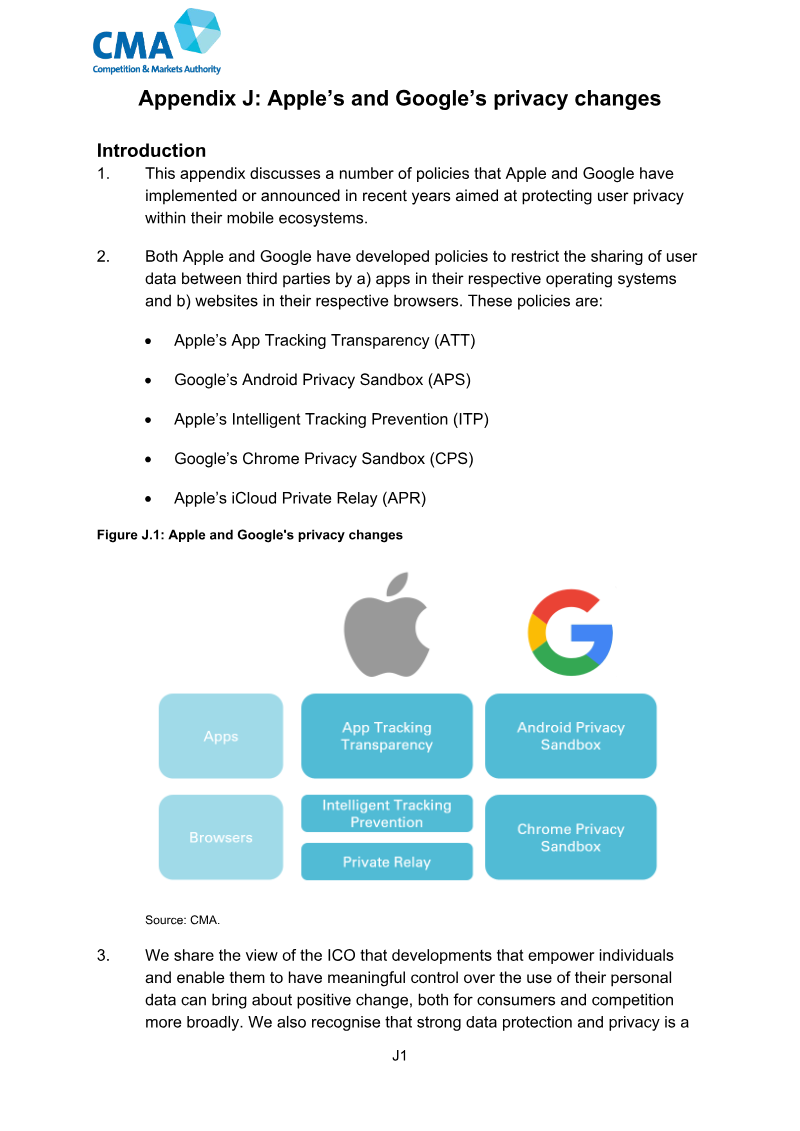
The company maintains a strong liquidity position, holding $1.1 billion in cash and short-term deposits alongside $600 million in available borrowing capacity. Financial stability is further managed through active interest rate swaps and foreign currency hedging strategies to mitigate market volatility. However, the capital structure remains heavily leveraged, with $2.43 billion in total debt. Furthermore, the business model faces significant platform dependency, as 79% of revenue is generated through Apple and Google. To address these concentration risks and reduce payment processing fees, the firm is actively shifting toward direct-to-consumer platforms.
Operational risks remain a primary concern, particularly regarding geopolitical instability in Eastern Europe. The company’s reliance on research and development centers in Ukraine and Belarus exposes it to potential disruptions from military conflict, sanctions, and cyber-attacks. These regional complexities, combined with ongoing legal contingencies and the inherent challenges of a concentrated user base, necessitate a cautious outlook. Nevertheless, management remains confident that current resources and operating cash flows are sufficient to meet all financial obligations and support continued business operations for the foreseeable future.