1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReport Apptica
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReportApptica
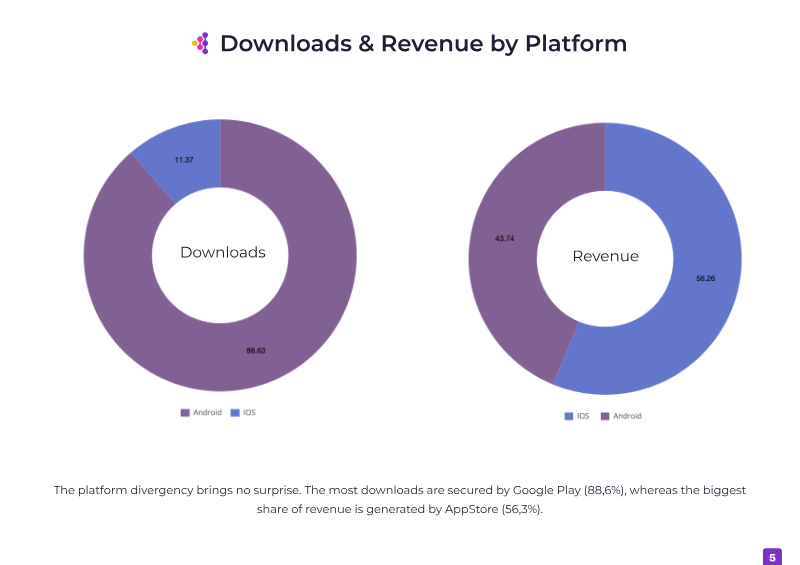
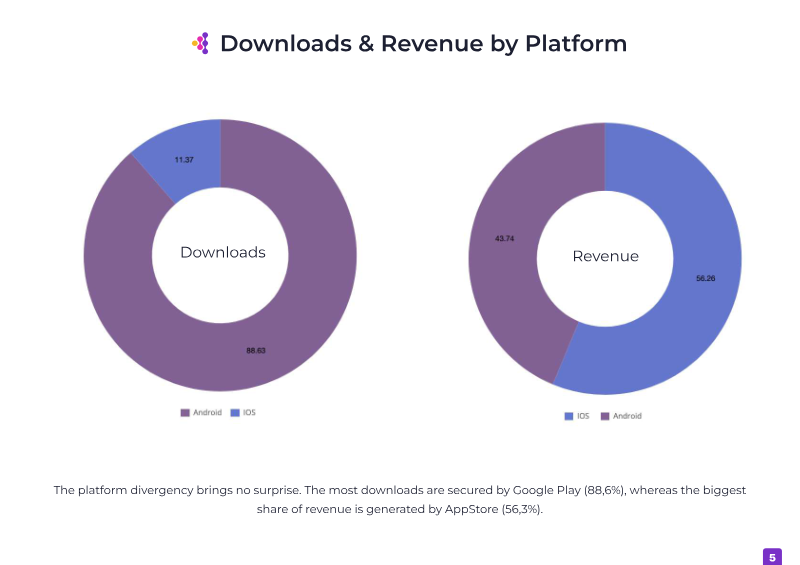
iOS accounts for 56.01% of the total global share, while Android accounts for 43.99%.
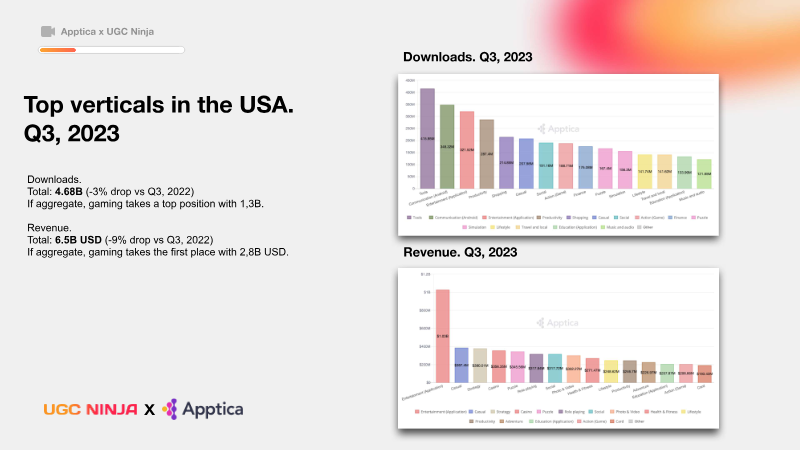
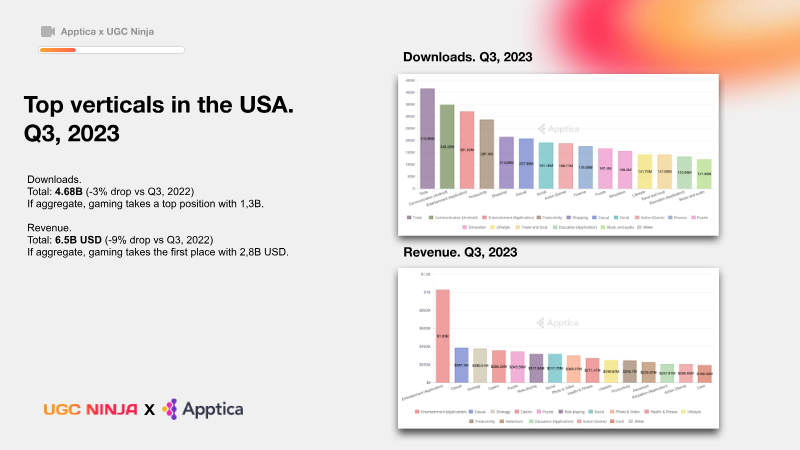
The global mobile gaming market faced a contraction in total installs during the third quarter of 2023, reflecting a broader cooling trend in user acquisition. Despite this decline, the industry maintained a robust financial performance, with iOS securing 56 percent of global revenue, totaling $5.91 billion compared to $4.64 billion on Android. The United States remains the primary driver of both download volume and total earnings, though regional disparities persist. Japan and South Korea continue to anchor the market for Role-Playing Games, while Western European markets like France, Germany, and the UK have seen the rapid ascent of titles such as Monopoly Go! as a dominant force in both engagement and monetization.
Genre performance remains bifurcated between popularity and profitability. While Casual, Action, and Simulation titles command the highest volume of downloads, Role-Playing Games consistently outperform other categories in global revenue generation. Engagement metrics reveal that card games currently serve as the most time-intensive genre for users. Furthermore, established titles including Candy Crush Saga, Royal Match, and Roblox continue to command significant portions of daily playtime across major territories.
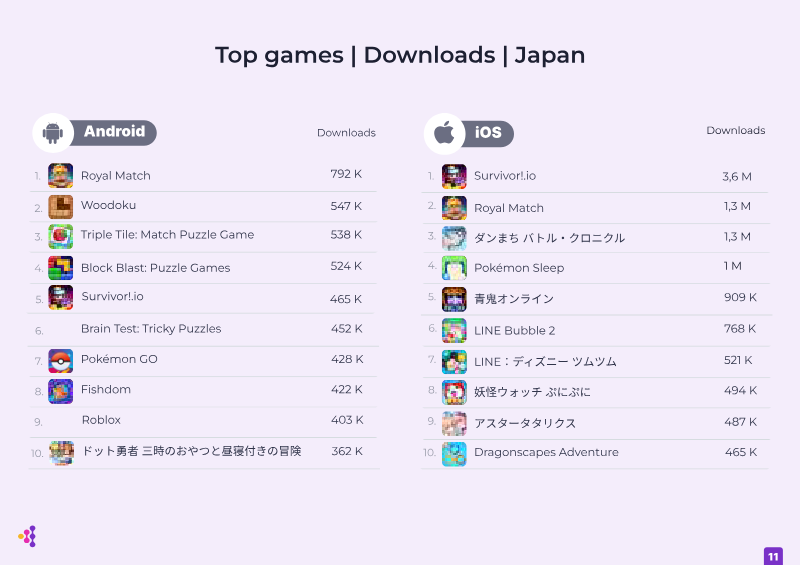
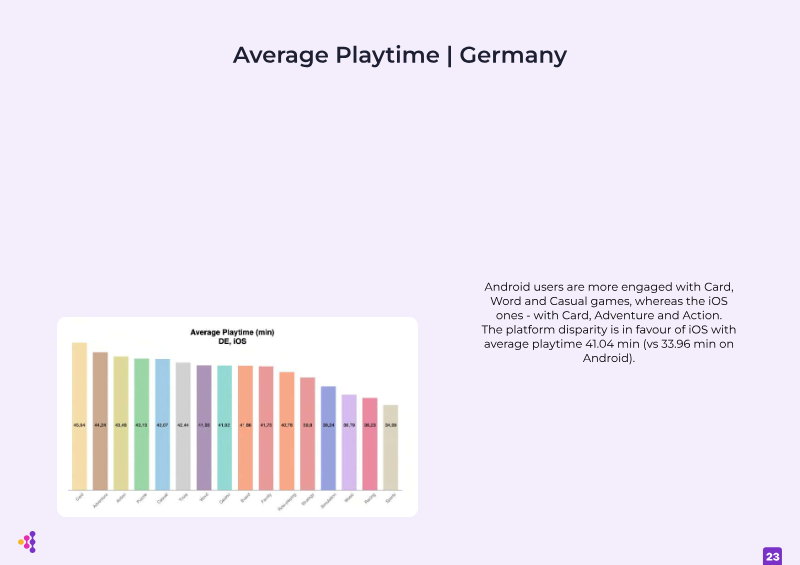
User behavior patterns highlight a clear distinction between operating systems and geographic regions. iOS users consistently demonstrate longer average playtimes than their Android counterparts, with Japan leading the world in total engagement sessions. These findings underscore a market environment where, despite a contraction in new installs, high-performing titles successfully leverage deep engagement loops to maintain revenue stability. The data suggests that while the mobile gaming sector is maturing, success is increasingly defined by the ability to retain players within high-engagement genres rather than relying solely on broad-market acquisition.
Apptica · 2026
Apptica · 2025
Apptica · 2024
Apptica · 2024
Apptica · 2024
Apptica · 2024
Apptica · 2023
Apptica · 2023
Apptica · 2023
Apptica · 2023
Apptica · 2023
Apptica · 2022
Electronic Arts · 2025