Key insights
7 slides
Profit pressure
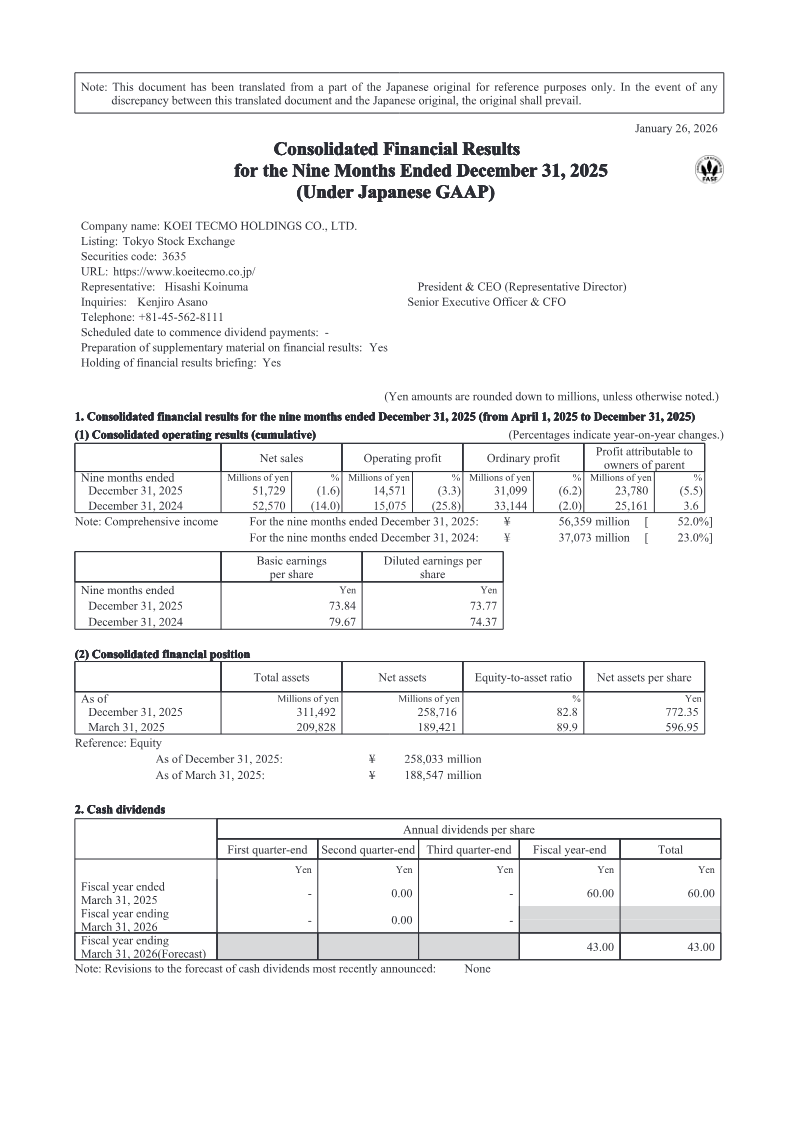
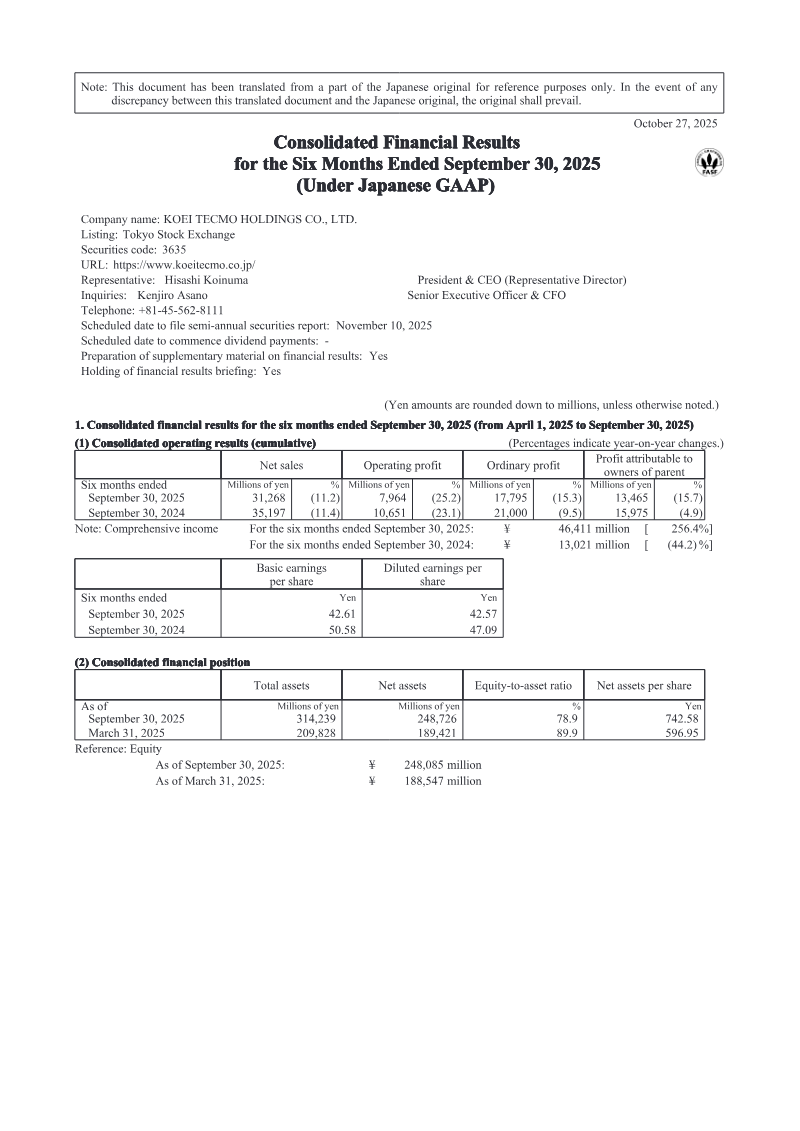
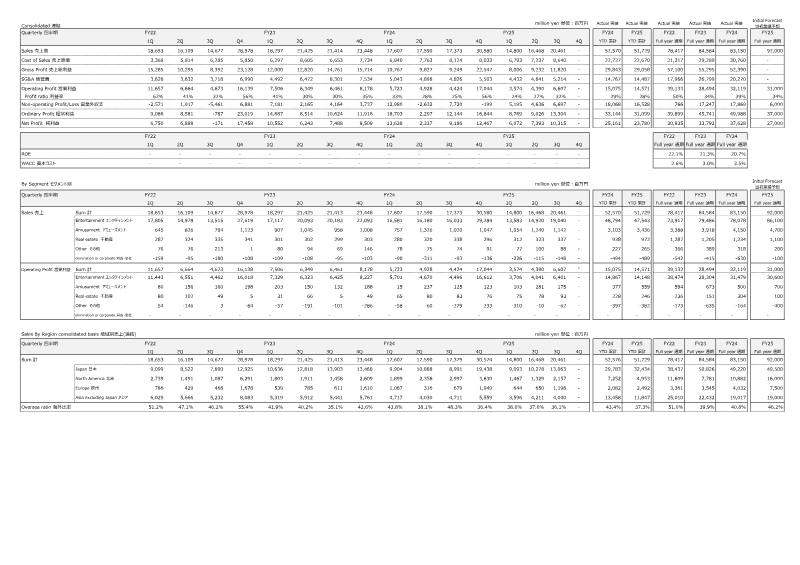
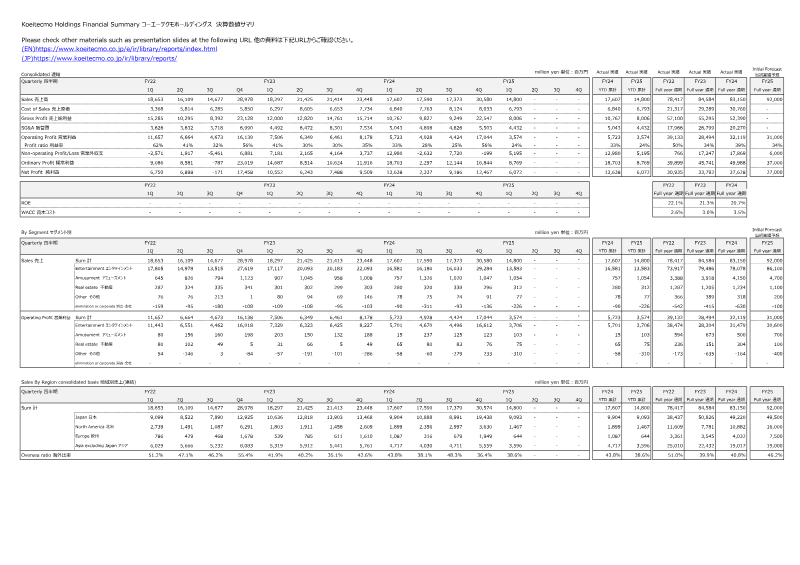
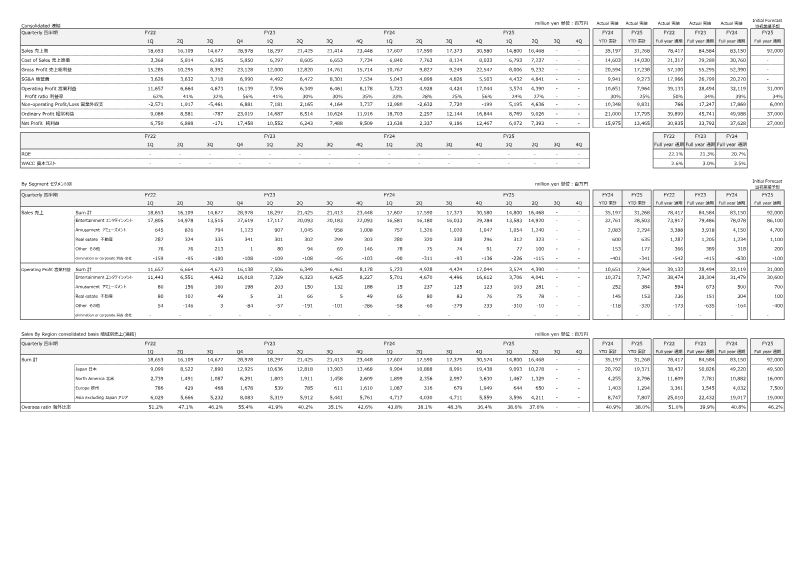
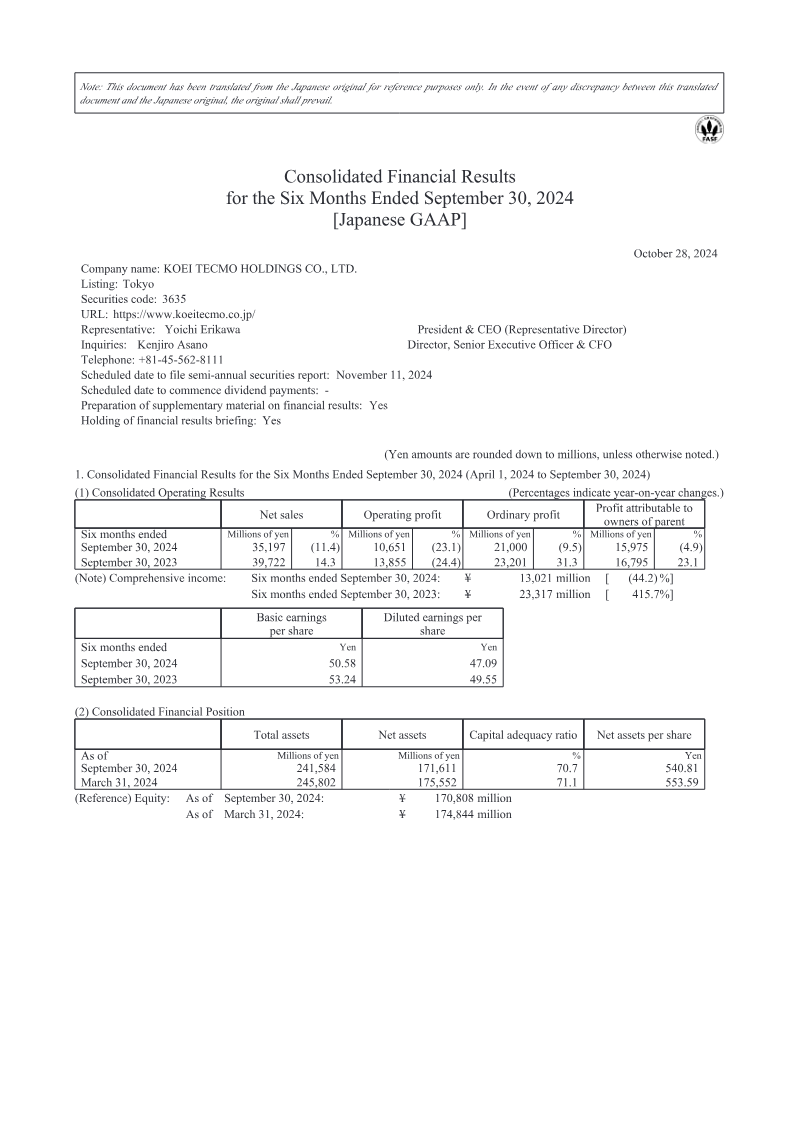
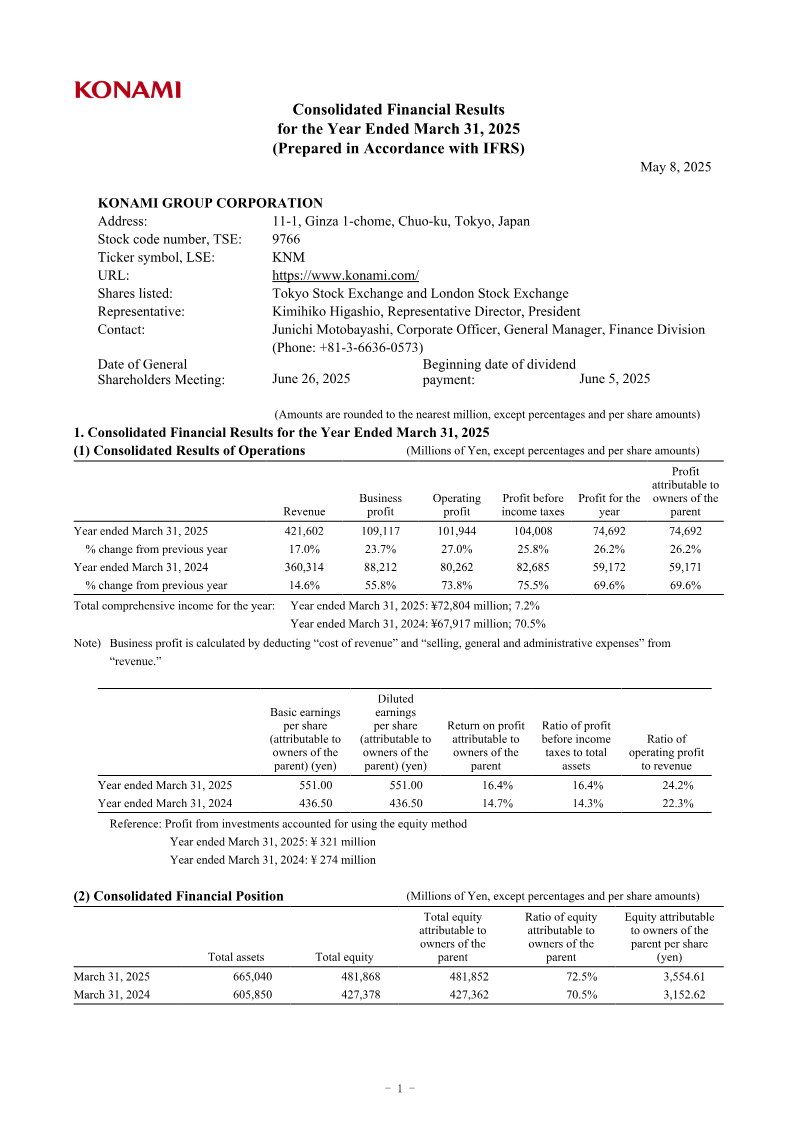
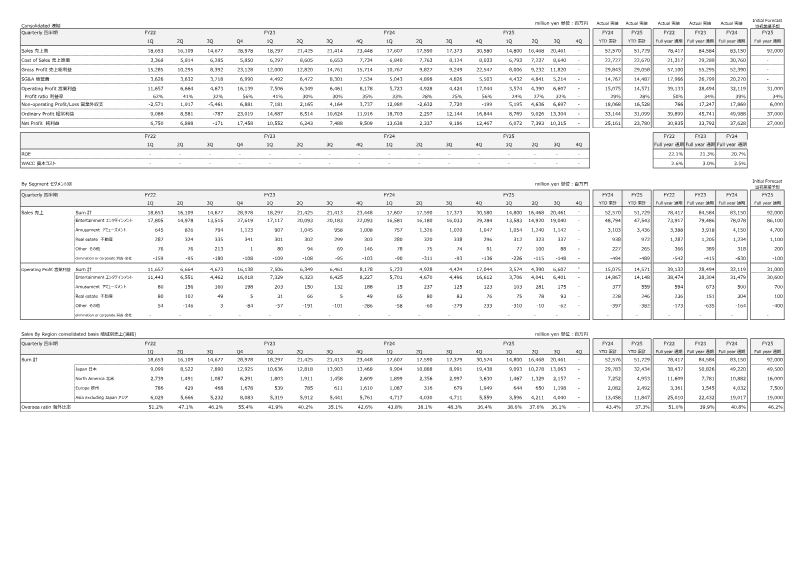
Operating profit fell 15.5% to ¥17,044 million.
The decline was driven by higher SG&A and cost of sales in the entertainment segment. Gross profit improved to ¥22,547 million, up 0.6% YoY.
Bottom-line result
Net profit rose 6.4% to ¥12,467 million.
The increase was supported by a positive non-operating profit of ¥3,737 million. Operating margin stood at 56% and ROE rose to 22.1%.
Segment concentration
Entertainment segment accounted for 95% of total sales.
The segment generated ¥29,284 million in sales.
Geographic shift
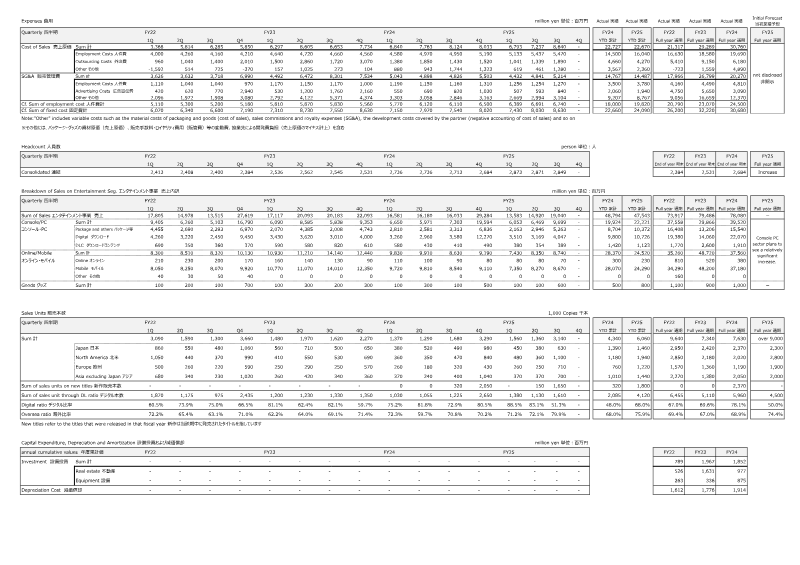
Overseas sales reached 51.0% of total revenue in FY25.
This was up from 46.2% in FY24. Japan remained the largest market with ¥19,438 million in Q3 FY25, followed by North America at ¥3,630 million and Europe at ¥1,949 million.
Workforce growth
Headcount increased 6.7% to 2,531 employees by year-end FY25.
The rise aligned with new product launches and expanded online services. Capital expenditures for FY25 totaled ¥1,967 million, primarily in real estate and equipment.
Page 2 of the report2,531
Employees by year-end FY25
- Prior headcount
- 2,384
Capital spending
Capital expenditures totaled ¥1,967 million for FY25.
Spending was primarily in real estate and equipment. Depreciation expenses reached ¥1,776 million.
Growth focus
The data suggest a focus on digital monetization and overseas penetration.
The company is managing cost pressures in traditional entertainment operations. Profitability ratios reflect efficient capital use with an operating margin of 56% and ROE of 22.1%.
Efficiency. Operating margin stood at 56% and ROE rose to 22.1%.
1 / 7
Ask AI about this report