Reports in the Market (Overall) category.
The global game publishing market is entering a period of significant expansion, with revenues projected to rise from $117.4 billion in 2025 to $150.5 billion by 2030. This growth is underpinned by a fundamental shift toward digital distribution, which already accounted for 95% of industry revenue in 2023. While traditional publishers maintain a competitive edge through high-budget user acquisition and advanced analytics, the democratization of the industry via platforms like Steam and the Epic Games Store has enabled self-published titles to achieve massive commercial success. Consequently, the industry is moving toward a hybrid landscape where multiplatform launches have increased by 40% to maximize player engagement and revenue potential.
Strategic success in the current market relies heavily on closed-loop marketing and data-driven publishing. Developers are increasingly utilizing real-time telemetry and AI analytics to optimize player retention and monetization strategies. This is particularly evident in the rise of Live Service Games, with 95% of studios now developing titles designed for recurring revenue. However, community management and influencer marketing have emerged as equally vital pillars; approximately 40% of gamers now make purchases based on creator recommendations, and social touchpoints drive over 54% of player motivation to continue gameplay. Furthermore, transmedia collaborations, such as television adaptations of gaming franchises, have doubled their share of box office revenues, illustrating the power of cross-media synergy.
The monetization landscape is further diversifying through the growth of subscription services and the esports sector. Subscriptions are expected to reach 318 million active users and a $21.6 billion valuation by 2030, while the esports market is projected to hit $87.7 billion in the same timeframe. To navigate this complexity, many developers are adopting publishing-as-a-service models and leveraging AI to manage diverse revenue streams across platforms. Ultimately, the integration of cross-platform development, which can boost revenue by up to 40%, combined with sophisticated digital marketing and community-focused strategies, defines the modern trajectory of the global gaming industry.
Unlocking Games Revenue: Player Behavior and Payment Trends in the West examines the evolving monetization landscape across North America and Europe. Produced through a partnership between Newzoo and Tebex, the analysis combines market intelligence with transaction data from over $1 billion in processed payments. The primary thesis suggests that as payer growth in mature Western markets plateaus—with a projected Compound Annual Growth Rate (CAGR) through 2027 of only 1.1% in North America and 3.1% in Europe—industry success depends on maximizing value from existing players through diversified payment methods and localized monetization strategies.
The scope of the research focuses on PC, console, and mobile platforms in 2024 and 2025. Findings indicate that while North America and Europe house only 20% of the global player base, they account for 46% of total gaming spend. North America leads the world in average annual spend per payer at $324.90, compared to $125.40 in Europe. Regional motivations for spending differ significantly; North American players prioritize personalization and character customization, whereas European players are more value-conscious, citing sales, special offers, and the removal of advertisements as primary drivers for transactions.
A critical finding involves the impact of alternative payment methods on Average Transaction Value (ATV). While traditional cards and digital wallets dominate total volume, emerging methods like Buy Now, Pay Later (BNPL) and cryptocurrency yield significantly higher ATVs. In North America, BNPL transactions average $85.00 compared to $52.20 for cards. Furthermore, the data shows that players using both traditional and alternative methods do not decrease their transaction frequency, suggesting that offering diverse payment options directly unlocks higher spending tiers. The analysis concludes that studios must reduce friction in payment flows and embrace unbundled, web-based storefronts to maintain loyalty and revenue in a maturing market.
The global games content and services market reached a record $199.4 billion in 2024, a 3.5% year-on-year increase that surpassed pandemic-era peaks. Despite this financial milestone, the industry faces significant structural challenges, including widespread layoffs, studio closures, and a shift toward de-risking strategies. Growth is expected to slow to 0.9% in 2025, largely due to the delay of Grand Theft Auto VI into 2026, which is projected to remove $2.7 billion from the 2025 console market. However, the industry is forecast to surpass the $200 billion threshold for the first time in 2025, with growth accelerating to 2.2% in 2026.
Key growth opportunities center on new hardware and emerging markets. The anticipated launch of the Nintendo Switch 2 in 2025 represents a $7-8 billion content opportunity, with significant potential for increased in-game monetization. Geographically, the Middle East, Africa, and Southeast Asia are expected to outperform Western markets, with the Middle East and Africa projected to grow by 6.3% in 2025. Additionally, significant headroom exists in mature markets like the U.S. by targeting underserved cohorts, specifically females aged 16-24 and adults over 55.
The industry is navigating a transition in monetization and platform dynamics. In-game spending accounts for 77% of total revenue, while physical media is expected to dwindle to just 2% of the market by 2026. To combat escalating AAA development costs, publishers are increasingly utilizing remakes, remasters, and transmedia franchise strategies. While mobile gaming remains the largest segment at 58% market share, PC gaming showed the strongest growth in 2024 at 5.7%. The analysis utilizes proprietary market modeling, financial KPIs, and quantitative consumer research across global regions to provide a comprehensive outlook through 2026.
The gaming industry is currently facing a significant integrity crisis, with 80% of players reporting encounters with cheaters in online environments. This prevalence has transformed cheating from a fringe issue into a routine experience for the majority of the community, with over half of gamers encountering unfair play at least several times a month. The widespread availability of cheating tutorials on social media platforms like YouTube and TikTok has further exacerbated the problem, creating a cycle where 62% of players admit to feeling tempted to cheat themselves.
The impact of this crisis extends beyond player frustration to significant financial and operational risks for developers. Approximately 42% of gamers have considered quitting specific titles due to cheaters, and 55% have either reduced or stopped their in-game spending entirely. This trend is particularly pronounced among high-value players, threatening the core revenue models of modern live-service games. Despite these challenges, there remains a high level of trust in developers to solve the issue, with 94% of players believing studios can effectively address the problem.
Data suggests a strong appetite for robust, industry-wide solutions. Approximately 73% of gamers are willing to undergo identity verification to ensure cheat-free matchmaking, and 79% support cross-game penalties where bans follow a player across multiple titles. Furthermore, 83% of respondents indicated they would be more likely to play a game credibly marketed as "cheat-free." These findings suggest that implementing verified identity systems could restore accountability, protect revenue streams, and improve player retention.
The research was conducted by Atomik Research on behalf of PlaySafe ID, surveying 2,013 adult PC gamers across the United Kingdom and the United States in July 2023. The sample consisted of active players, 82% of whom play multiple times per week, primarily focusing on first-person shooters, sports games, and casual titles.
The 2025 gaming landscape is defined by the convergence of mobile accessibility and PC/console depth. The primary thesis suggests that while mobile serves as a global discovery engine and a source of steady growth, PC and console platforms anchor brand prestige and high-value engagement. To maximize franchise value, publishers must strategically bridge these ecosystems through purposeful cross-platform design, turning mobile’s vast reach into lasting loyalty.
Data highlights a significant scale disparity between platforms: mobile is projected to reach 52 billion downloads and $82 billion in in-app purchase revenue in 2025, while the PC and console segment generates over $12 billion from 1 billion units sold. Mobile leaders like Roblox and Garena Free Fire drive mass acquisition, whereas premium titles such as EA SPORTS FC 25 and Marvel Rivals dominate engagement on Steam, PlayStation, and Xbox. The findings indicate that unified ecosystems, such as those used by Delta Force and Genshin Impact, strengthen retention by allowing players to switch devices without losing progress.
The scope of the analysis is global, covering over 100 markets with specific digital advertising data from 14 major regions, including the United States, Japan, and the United Kingdom. It focuses on the first three quarters of 2025, utilizing Sensor Tower’s proprietary App Performance, Video Game, and Pathmatics Advertising Insights. Methodology involves statistical sampling of digital ad placements and estimated revenue from the App Store and Google Play, excluding third-party Android stores and direct web payments.
Four strategic models for expansion are identified: companion apps for engagement, "lite" versions for mass discovery, adapted standalone experiences for genre diversification, and full cross-play models for community unification. The conclusion emphasizes that a resilient portfolio must balance high-volume mobile genres, such as Simulation and Puzzle, with high-depth PC genres like RPGs and Shooters to maximize monetization efficiency and franchise longevity.
The entertainment industry is increasingly leveraging a transmedia strategy where video game intellectual property serves as the foundation for high-budget scripted content. This approach creates a symbiotic relationship between platforms, where the release of films and television series triggers a boomerang effect that revitalizes interest in the original games. Data indicates that these adaptations drive significant growth across multiple metrics, including active users, digital downloads, and in-app purchases, while simultaneously boosting the performance of the streaming services hosting the content.
The scope of this analysis covers major cross-platform releases between 2024 and 2025, focusing on global mobile, PC, and console gaming segments alongside digital advertising and streaming app performance. Key findings highlight the success of the Minecraft movie, which grossed over $900 million and led to a 44% spike in mobile in-app revenue and a 36% increase in console sales. Similarly, the Fallout television series drove a 23% increase in Amazon Prime Video downloads and a massive 410% surge in daily sales for Fallout 4 on PC. The longevity of this impact is notable, with daily active users for legacy Fallout titles remaining 225% higher for up to 20 weeks following the show's premiere.
Methodology relies on proprietary data from Sensor Tower, tracking digital market insights, app usage, and advertising spend. The data reveals that strategic marketing is essential to this success; for instance, Amazon increased its desktop video ad spend twentyfold to promote Fallout, specifically targeting gaming-focused platforms like Twitch and IGN. While results vary based on the faithfulness of the adaptation and the monetization model of the game, the overarching trend suggests that transmedia releases are a powerful tool for re-engaging historical players and attracting new audiences to established gaming franchises.
This analysis explores the intersection of intellectual property (IP) fandom and player engagement within the global gaming industry. The primary thesis is that while transmedia collaborations are essential for driving player acquisition and retention in a live-service landscape, the effectiveness of an IP is heavily dictated by regional awareness and cultural sentiment. Success in global gaming requires a move away from one-size-fits-all licensing toward market-specific strategies that align with local fanbases.
The findings are based on the 2025 Global Gamer Study, which surveyed over 73,000 consumers across 36 markets, tracking awareness and attitudes toward 42 popular entertainment IPs. Data indicates that a majority of gamers in 24 of the 36 countries are more likely to play a game featuring their favorite IP. This influence is strongest in South Asia (74%) and Latin America (64%), while Western Europe and Oceania show more reserved engagement levels (45%).
The research categorizes IPs into four quadrants based on the relationship between awareness and favorability. Global Favorites, such as Harry Potter and Disney, maintain near-universal recognition (90%) and high sentiment. Familiar Faces like Star Wars and Barbie possess high awareness but suffer from polarizing or lower favorability in specific regions. Hidden Gems, including Studio Ghibli and various anime titles, maintain niche global awareness but command intense loyalty in specific markets like Japan or Vietnam. Finally, IPs with Limited Appeal, such as Doctor Who or Percy Jackson, struggle with both low recognition and lukewarm sentiment outside their core territories.
Geographic variations are stark; for instance, anime franchises like Dragon Ball achieve 85–90% awareness in Latin America and Southeast Asia, nearly double their recognition in the West. Conversely, Western staples like DC Comics see high awareness in the U.S. (70%) but significantly lower traction in Japan (21%). The study concludes that cultural resonance, linguistic accessibility, and historical distribution patterns are the primary drivers of IP success in the gaming sector.
Roblox has evolved from a youth-centric gaming site into a massive entertainment ecosystem and creator economy, boasting nearly 112 million daily active users and distributing over $300 million to creators in a single quarter. While the platform shares structural similarities with mobile gaming—such as an 80% mobile user base and monetization driven by cosmetics and gacha—it functions more like a social media platform such as TikTok or YouTube. Success is dictated by cultural fluency, rapid iteration, and social momentum rather than high graphical fidelity or traditional production cycles.
The platform’s audience is maturing, with the 13+ demographic growing at 54% year-over-year, significantly outpacing younger cohorts. This shift brings higher spending power and more sophisticated expectations to the ecosystem. Data indicates that Roblox is not a siloed experience; only 24% of players engage exclusively on mobile, with significant playtime occurring on PlayStation and PC. The genre landscape is dominated by Roleplay, Simulation, and Platformers, characterized by low-friction, social, and trend-driven mechanics that prioritize accessibility over complex skill sets.
For traditional developers, the platform serves as a strategic testing ground for intellectual property and audience cultivation among Gen Z and Gen Alpha. Because the discovery algorithm rewards speed and native platform knowledge, established studios are increasingly partnering with Roblox-native creators to navigate the unique development rhythm. The most effective strategies treat the platform as a long-term engagement tool rather than a standard publishing channel, focusing on branded activations and collaborative IP experiences to build brand affinity with the next generation of gamers.
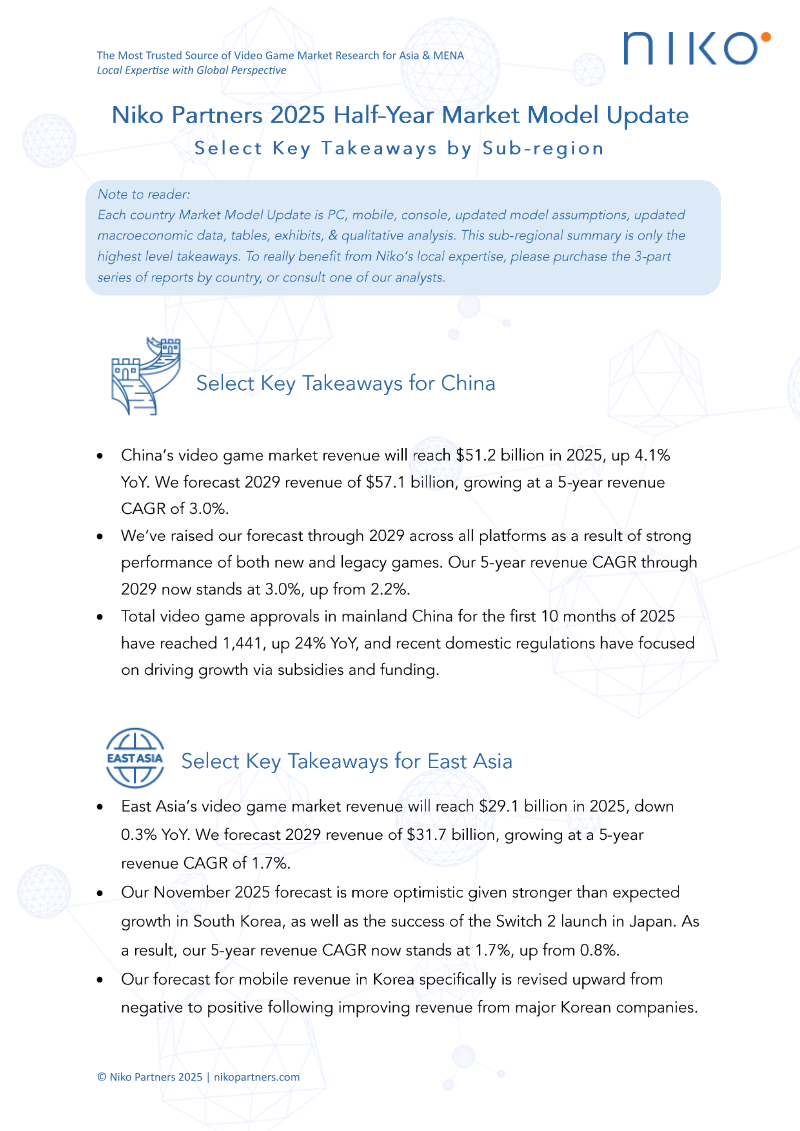
The video game markets across Asia and the Middle East are entering a period of recalibrated growth, with total revenues across key sub-regions projected to reach significant milestones by 2025. China remains the dominant force, with revenues expected to hit $51.2 billion in 2025, supported by a 4.1% year-over-year increase. This growth is fueled by a 24% rise in game approvals and proactive government subsidies. While China maintains a steady long-term outlook with a 3.0% five-year compound annual growth rate, India emerges as the fastest-growing market. India is projected to surpass the $1 billion threshold in 2025 with a 16.2% year-over-year increase, driven by the PROG Act of 2025, which pivoted the industry away from real-money gaming toward traditional video games and esports.
Regional performance varies significantly based on local macroeconomic conditions and hardware cycles. East Asia, comprising Japan and South Korea, shows a more optimistic outlook than previously anticipated, with a revised five-year growth rate of 1.7%. This shift is attributed to the successful launch of the Nintendo Switch 2 and a recovery in the South Korean mobile sector. Conversely, Southeast Asia and the MENA-3 region (Saudi Arabia, UAE, and Egypt) face more tempered expectations. Southeast Asia’s growth forecast was lowered to 3.5% due to headwinds in Thailand and Indonesia, despite strong performance in Vietnam. Similarly, the MENA-3 forecast was adjusted downward to a 6.4% growth rate as economic challenges in Egypt and slower mobile growth in Saudi Arabia offset increased government support for localization and age-rating reforms.
The data, derived from Niko Partners’ 2025 half-year market model updates, covers PC, mobile, and console platforms across 13 distinct markets. The methodology integrates proprietary market models, macroeconomic indicators, and qualitative regulatory analysis to provide a comprehensive five-year outlook through 2029. Overall, the findings suggest that while mature markets like China and East Asia are stabilizing, emerging markets like India and Vietnam are becoming critical drivers of global industry expansion.
Gaming has evolved into a horizontal cultural layer encompassing 3.4 billion global players who utilize interactive platforms to build identity and community. Despite this massive reach, the sector currently receives less than 5% of global media investment, representing a significant disconnect between consumer attention and advertising spend. The industry is increasingly defined by transmedia expansion and social connectivity, particularly among Gen Z audiences who prioritize platforms like Roblox and Discord for brand discovery and social interaction. Success in this landscape requires a strategic shift from isolated sponsorships toward full-funnel integrations that align with specific player motivations, including relaxation, achievement, and immersion.
The shift toward non-intrusive brand integration utilizes high-impact formats such as rewarded video and custom in-game partnerships to secure superior video completion rates and brand recall. Immersive strategies drive substantial consumer consideration, with 55% of players expressing interest in branded virtual items. Furthermore, custom experiences within gaming environments can yield up to 100x higher attention levels than traditional social media. Case studies involving major titles like Genshin Impact demonstrate that blending digital fandom with real-world value can result in triple-digit sales growth and heightened community engagement.
As a full-funnel engine, gaming integrations now produce measurable lifts in awareness and consideration through interactive campaigns. Data indicates that gamified loyalty programs can increase purchase rates by 12% and guest spend by 64%, while in-game commerce on platforms like Roblox generates significant revenue for developers. Looking ahead, the industry trajectory is shaped by the expansion of cloud gaming and highly anticipated hardware and software launches, such as the Nintendo Switch 2 and Grand Theft Auto VI. These developments reinforce gaming's role as a primary driver of modern media consumption and commercial conversion.
The video gaming industry is transitioning into a new era of growth following a post-pandemic stabilization period. While the sector is unlikely to replicate the rapid doubling of the 2010s, a convergence of technological and structural shifts is expected to revitalize the market. This evolution is driven by four primary strategic trends: the integration of Generative AI, the expansion of the user-generated content (UGC) creator economy, the mainstream adoption of cloud gaming, and the regulatory opening of mobile app stores.
Key findings indicate that Generative AI is already being utilized by approximately 50% of studios to improve development efficiency and create adaptive gameplay, with 20% of new Steam games disclosing AI use by mid-2025. Simultaneously, the creator economy is surging; payouts from platforms like Roblox and Fortnite are projected to exceed $1.5 billion in 2025. Cloud gaming is also positioned for a massive scale-up, with revenues forecasted to grow from $1.4 billion in 2025 to $18.3 billion by 2030. This shift toward hardware-agnostic play is mirrored in distribution, where 33% of adult gamers have already purchased titles directly from developer web stores to bypass traditional platform fees.
The scope of this analysis is global, with a particular focus on major markets including the US, China, Germany, Japan, and South Korea. It covers the industry from late 2025 through projections for 2030, spanning mobile, console, and PC segments. Data is derived from the Global Gaming Survey of approximately 3,000 gamers, metadata analysis of the Steam platform, and interviews with industry leaders and developers.
The industry concludes that success in this new landscape requires a departure from traditional "console war" mentalities in favor of ecosystem-based strategies. Developers must master new monetization models, such as tiered pricing and windowing, to protect the value of premium content while navigating a market increasingly defined by infinite digital shelf space and algorithmic discovery.
G5 Entertainment’s 2024 performance reflects a strategic pivot toward operational efficiency and margin expansion within the global mobile gaming sector. Despite a 14% year-over-year revenue decline to SEK 1,135 million, the company achieved a 5% increase in operating profit, reaching SEK 116.8 million. This improvement is attributed to a disciplined focus on its core demographic—women aged 35 and older—and the expansion of its proprietary direct-to-consumer G5 Store, which now accounts for 16.1% of total revenue. By leveraging AI-driven development and a rigorous funnel of five to six soft launches annually, the company aims to sustain its position in the evergreen Hidden Object, Match-3, and Mahjong genres.
The company maintains a robust financial foundation, characterized by SEK 276 million in available cash and an equity/asset ratio of 83%. Financial stability is further supported by a conservative approach to capital, with no external debt and a portfolio where the top ten titles generate 98% of intangible asset value. While the business remains sensitive to market volatility, currency fluctuations, and reliance on major third-party distribution platforms, auditors have provided an unqualified opinion on the financial statements, confirming that the valuation of capitalized development costs remains within reasonable parameters.
Beyond financial metrics, the organization emphasizes a structured approach to corporate governance and human capital. With a gender-balanced workforce and a commitment to ethical business conduct, G5 integrates comprehensive labor policies and 360-degree performance assessments to drive organizational health. While the company has implemented energy-efficient practices, it currently lacks formal climate mitigation plans and EU taxonomy-aligned sustainability metrics. Moving forward, the board remains focused on balancing organic growth with shareholder returns, as evidenced by the proposed dividend of SEK 8.0 per share and a continued emphasis on performance-based executive remuneration.