1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial report Stillfront
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountFinancial reportStillfront
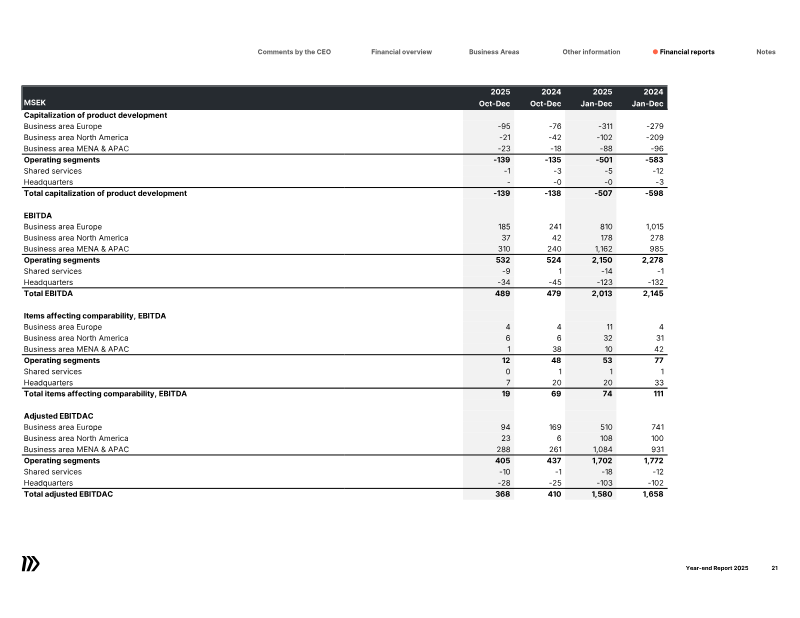
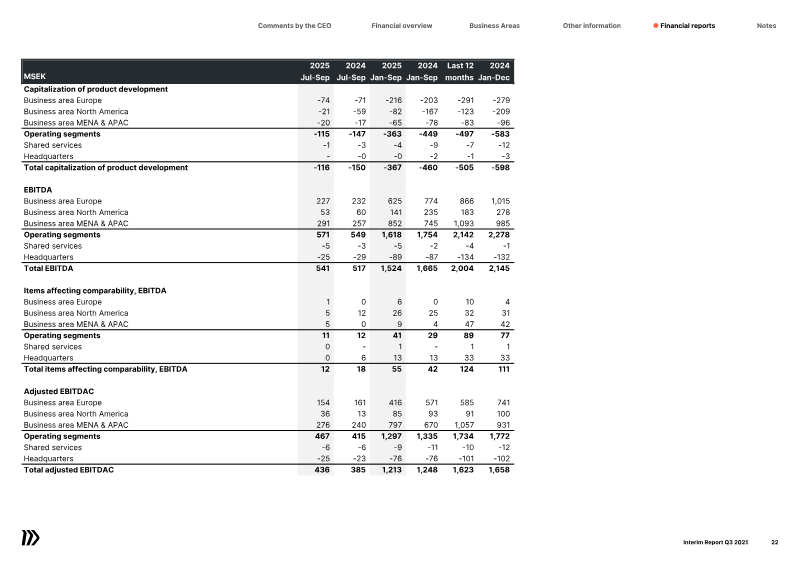
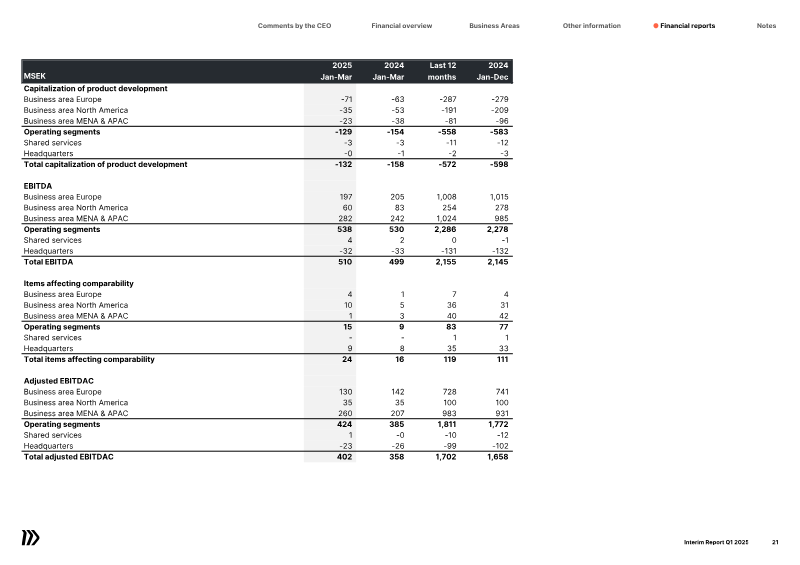
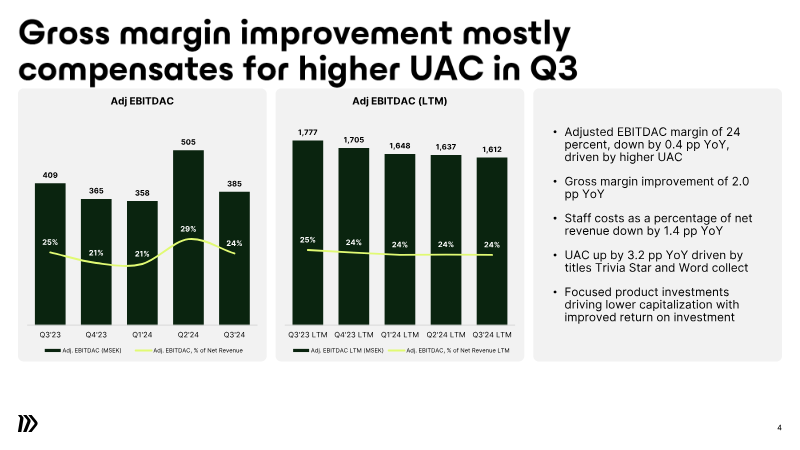
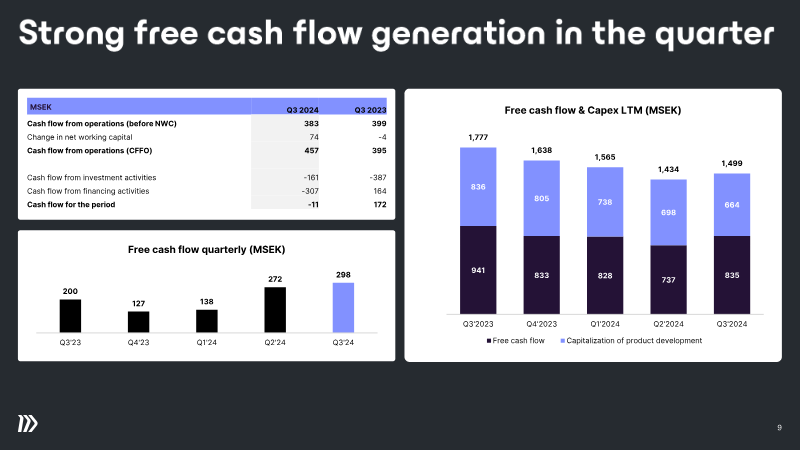
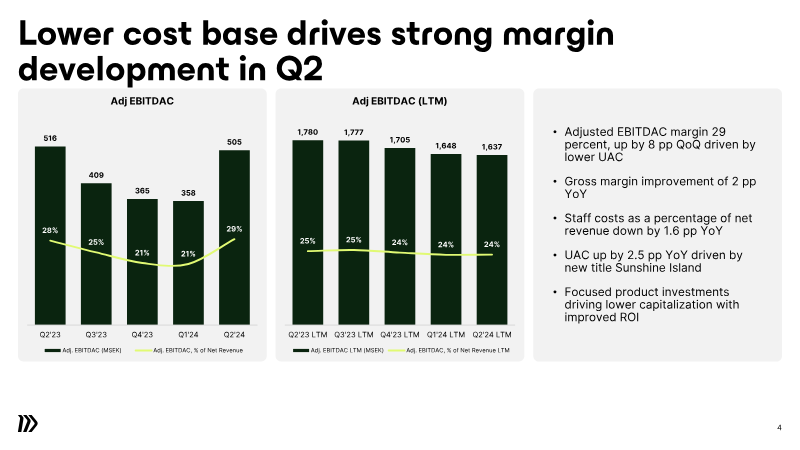
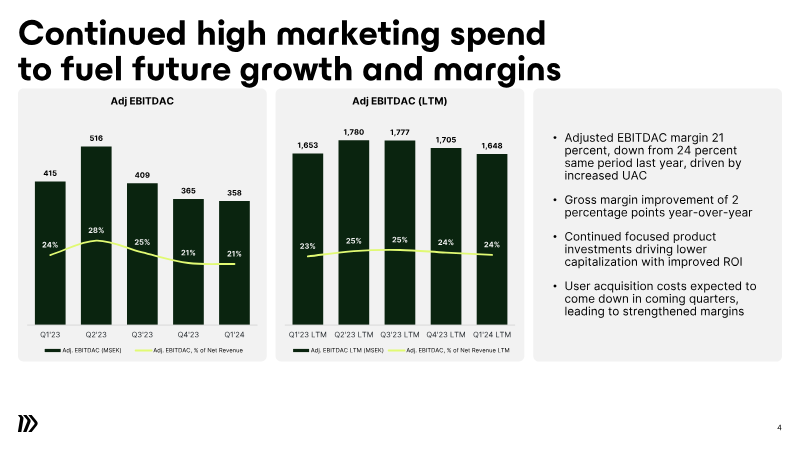
The report presents Stillfront Group’s financial and operational performance for 2024, emphasizing a shift toward streamlined operations and franchise-centric growth. Net revenue reached 1 660 MSEK in Q4, a 5% YoY decline, yet gross profit margin improved to 79%, driven by a higher share of direct-to-consumer (DTC) bookings and favorable mix effects. Adjusted EBITDAC rose to 410 MSEK, reflecting a 25% margin and cost efficiencies from lower fixed and user-acquisition costs. Free cash flow surged 170% YoY to 1 050 MSEK, underscoring stronger liquidity.
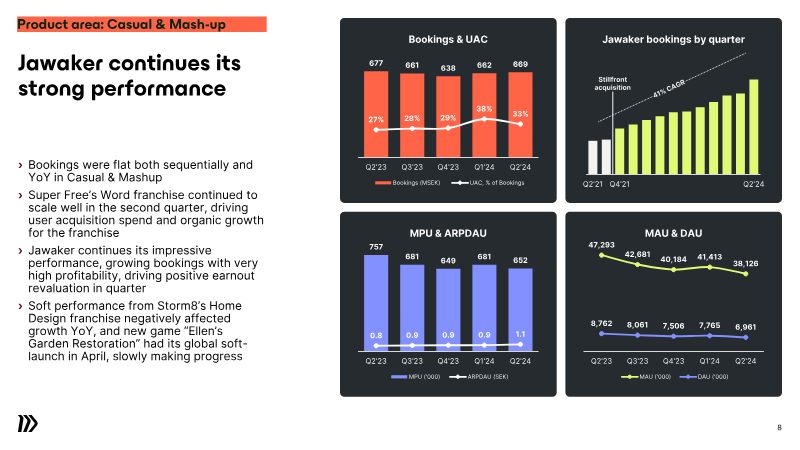
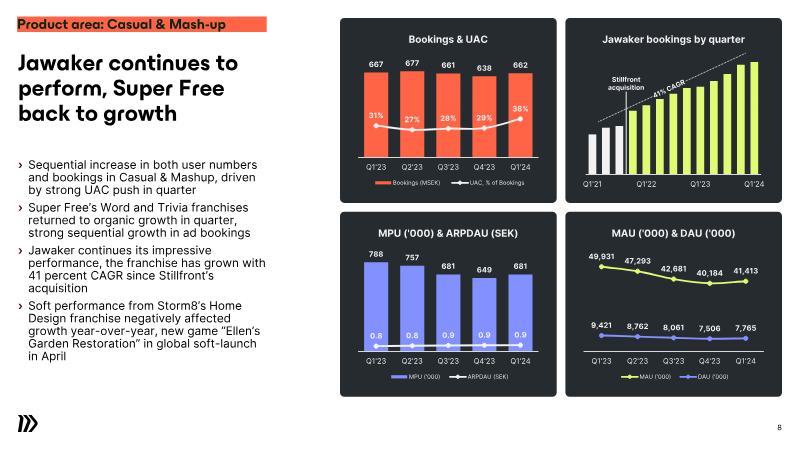
Bookings across the portfolio grew 4% QoQ but fell 4% YoY, largely due to reduced player activity in strategy titles. The DTC channel gained 5 pp of bookings, boosting gross margin and contributing to an 18% YoY rise in ARPDAU. User-acquisition spend fell by 1 pp YoY, while staff costs stabilized around 24% of revenue. The company’s debt profile remained manageable with a leverage ratio near 2.1 and net debt of 957 MSEK.
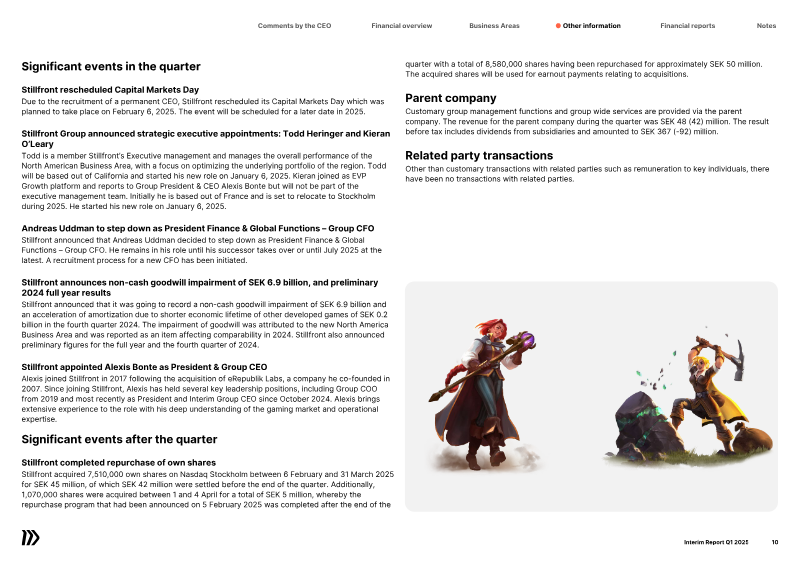
Strategically, Stillfront reorganized into three business areas focused on key franchises, reducing duplication and accelerating decision-making. Studio rationalizations consolidated six studios in 2024, yielding annual run-rate savings of 50 MSEK and projected additional 200–250 MSEK by Q4 2025. The new operating model prioritizes organic growth through high-value franchises, reduced reliance on performance marketing, and enhanced operational efficiency across shared services.
Stillfront · 2026
Stillfront · 2026
Stillfront · 2026
Stillfront · 2026
Stillfront · 2025
Stillfront · 2025
Stillfront · 2025
Stillfront · 2025
Stillfront · 2024
Stillfront · 2024
Stillfront · 2024
Stillfront · 2024
Deconstructor of Fun · 2026