1 free read left. Create a free account for unlimited reading + AI research.
Create free accountWhitepaper SocialPeta
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountWhitepaperSocialPeta
The overall regional trend indicates a consistent rise in both player acquisition and monetization.
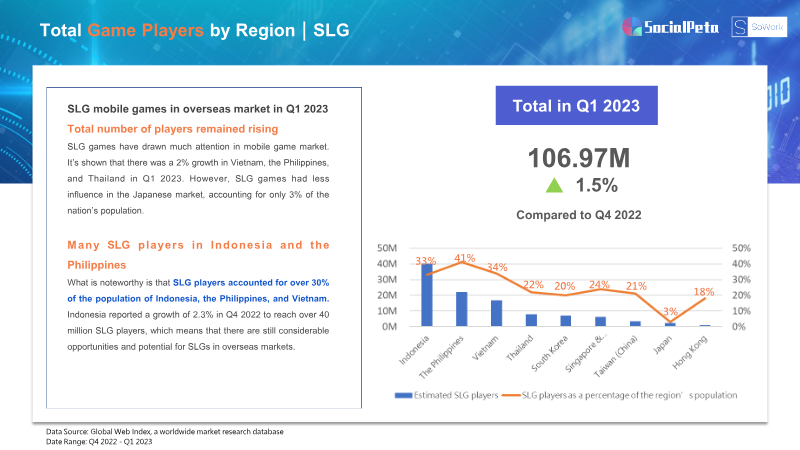
The mobile simulation game market in the Asia-Pacific region demonstrates significant growth and untapped potential, particularly within the strategy and simulation (SLG) genre. As of the first quarter of 2023, the total number of SLG players reached 106.97 million, with Southeast Asian nations such as Indonesia, the Philippines, and Thailand emerging as key growth drivers. While market penetration remains lower in Japan, the overall regional trend indicates a consistent rise in both player acquisition and monetization, with over 40% of the player base actively spending to enhance their gaming experience.
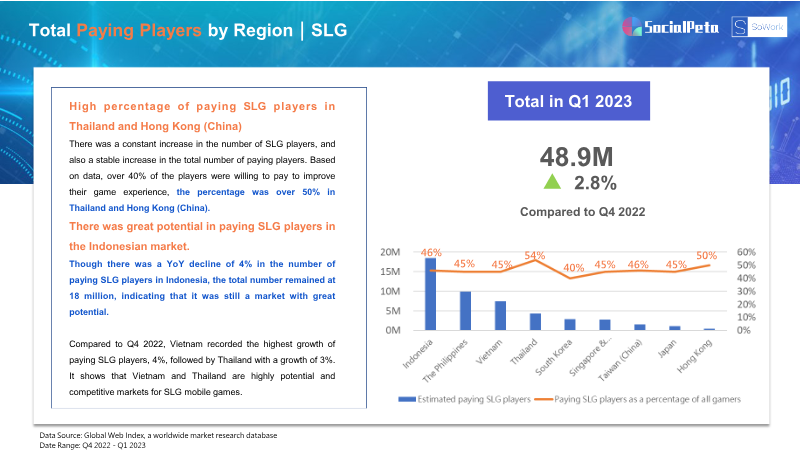
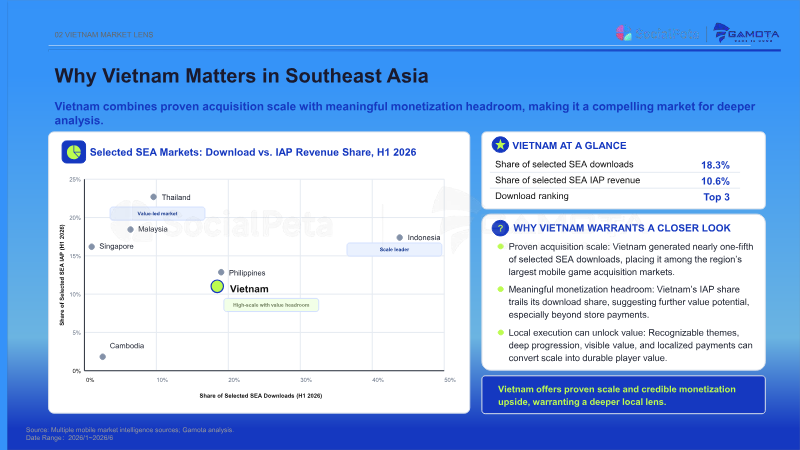
Monetization metrics reveal that Thailand and Hong Kong lead the region, with over 50% of SLG players contributing revenue. Although Indonesia experienced a slight year-over-year decline in paying users, the market remains substantial with 18 million paying players, signaling continued commercial viability. Vietnam and Thailand currently represent the most competitive and high-potential markets, characterized by steady growth in both player volume and spending habits.
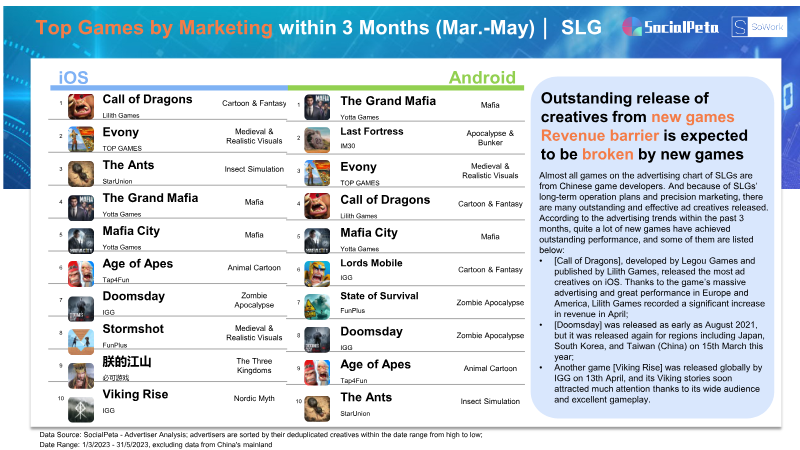
The competitive landscape is dominated by Chinese developers who utilize sophisticated, long-term operational strategies and precision marketing. Successful titles such as Call of Dragons, The Grand Mafia, and The Ants leverage high-frequency advertising campaigns across major global networks. Current marketing trends emphasize the use of live-action elements and integrated mini-games—specifically "hack and slash" mechanics—to boost engagement and conversion. These findings are derived from extensive advertising data tracking, which monitors over 80 global ad networks and millions of daily creative updates to provide actionable insights into competitor performance and consumer acquisition strategies.
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
SocialPeta · 2026
Two & a Half Gamers · 2026